
 Asia-Pacific Protective Packaging Market | 2026-2036
Asia-Pacific Protective Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Protective Packaging Market Outlook
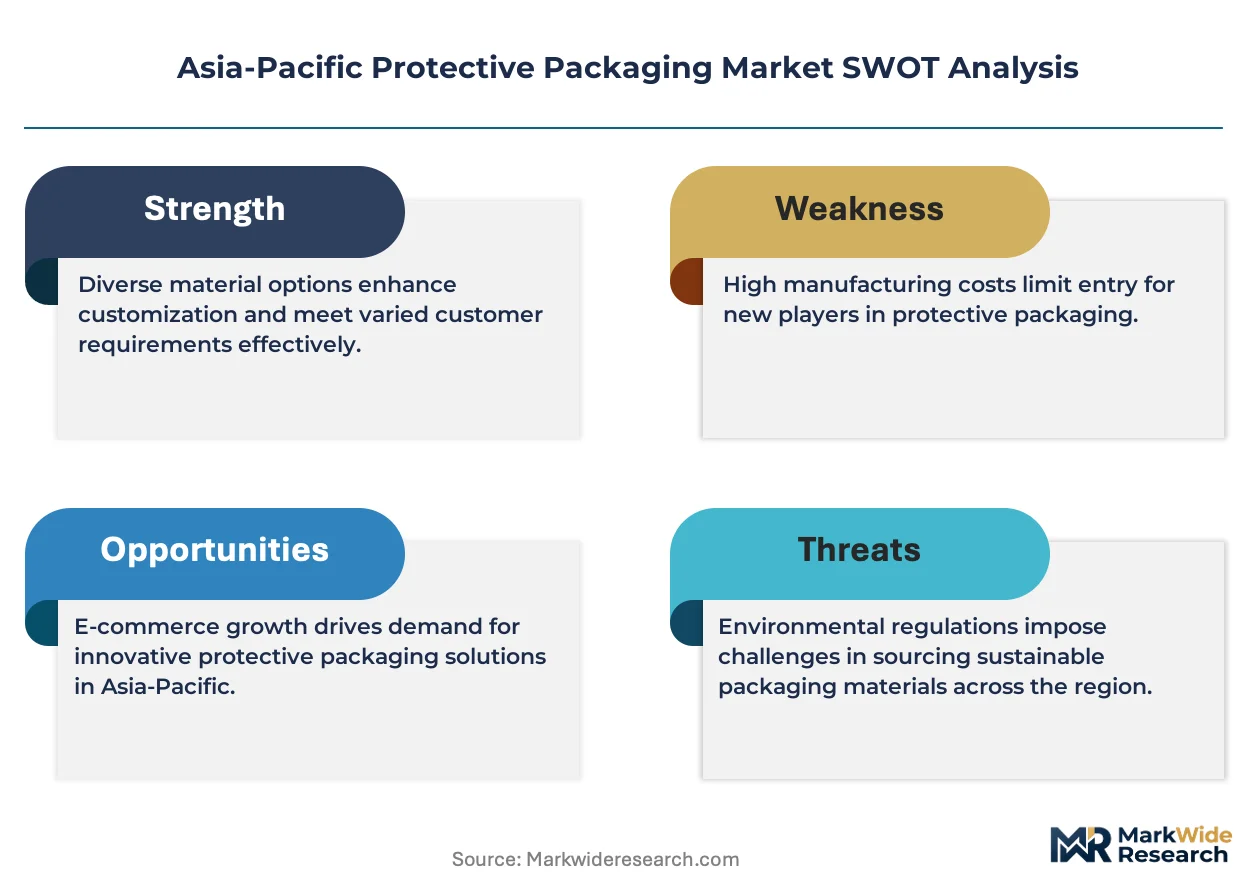
China's dual carbon goals from MEE is expanding compliance pressure across converter networks, forcing substrate transitions from virgin plastic toward paper and biodegradable alternatives. Sealed Air Corporation leverages its global R&D footprint to develop fiber-based cushioning systems for Asian electronics exporters. Huhtamaki Group anchors its regional position through molded fiber capacity expansion serving food and beverage transit applications. Sonoco Products Company differentiates via engineered paperboard solutions that compete directly with expanded polystyrene in industrial packaging.
Asia-Pacific protective packaging encompasses engineered materials and systems designed to absorb mechanical shock, vibration, and environmental stress during product handling, transit, and storage. Specifications typically address drop-test performance per ASTM or JIS standards, with cushioning curves derived from acceleration versus static loading data. Foam segments dominate industrial applications where repeated impact protection governs specification, while protective mailers sustain the fastest expansion as e-commerce parcel volumes multiply across Southeast Asian markets. Biodegradable materials occupy emerging margin pools as Japan's METI guidelines and Australia's packaging covenant reshape procurement criteria for brand owners.
China's MEE enforces carbon intensity benchmarks that elevate paper and plant-fiber substrates over conventional plastics. Japan's METI circular economy frameworks and India's BIS packaging standards collectively tighten material traceability and recyclability mandates across the region. Australia's National Packaging Targets impose recycled content thresholds that filter through multinational supply chains. Stakeholders must monitor regulatory divergence between Northeast Asian precision standards and Southeast Asian phased compliance timelines to align capacity investments with enforceable product requirements.
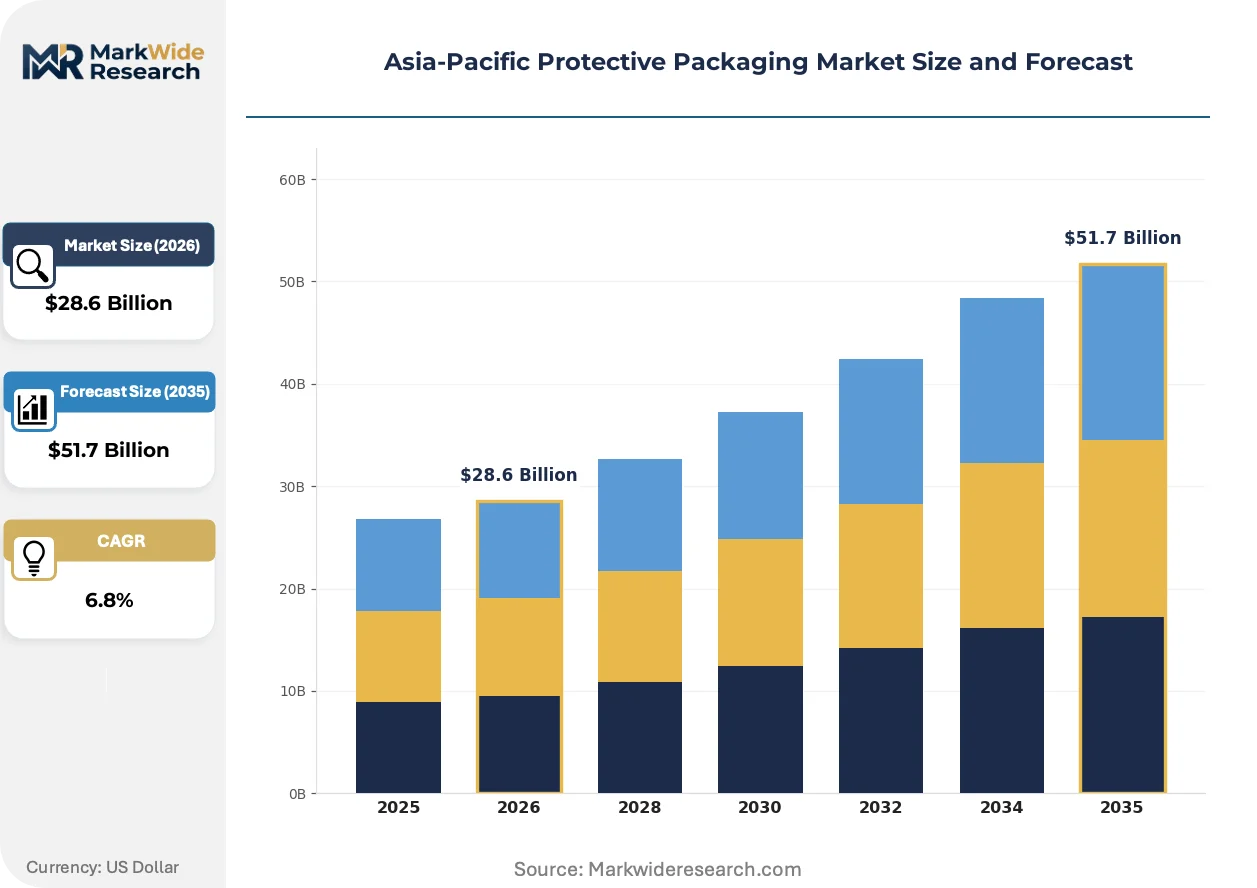
Market Dynamics
China's MEE carbon intensity benchmarks are forcing substrate transitions across converter networks, compressing virgin plastic demand while elevating paper and molded fiber specifications in electronics and food transit applications.
Growth Catalysts
- E-commerce parcel multiplication:Southeast Asian fulfillment centers are scaling protective mailer procurement as cross-border retail volumes concentrate in Indonesia, Vietnam, and Thailand.
- Dual carbon goals from MEE:China's environmental ministry enforces carbon intensity benchmarks that elevate paper and plant-fiber substrates over conventional plastics in Yangtze River Delta manufacturing clusters.
- Semiconductor supply chain densification:Electronics assemblers in South Korea and Japan are expanding engineered foam and anti-static film specifications for chip transit protection.
Market Restraints
- Pulp price volatility:Molded fiber converters face margin compression when bleached kraft pulp futures spike, limiting capacity expansion timing.
- Biodegradable resin supply concentration:PLA and PBAT feedstock production clusters in Thailand and China create single-source vulnerability for certified compostable film specifications.
- Performance gaps in fiber cushioning:Paper-based alternatives fail repeated drop-test thresholds above 1.5 meters for industrial equipment, preserving expanded polystyrene in heavy-goods segments.
Strategic Opportunities
- India's BIS packaging standards evolution:Recyclability mandates in food and pharma transit create specification windows for certified paperboard and barrier-coated fiber solutions.
- Returnable packaging systems:Closed-loop pooling models for automotive component transit between Japan and ASEAN assembly plants reduce single-use consumption.
- Smart packaging convergence:Integration of impact sensors with protective mailers enables real-time damage attribution in high-value electronics fulfillment.
Industry Challenges
- Composting infrastructure mismatch:Biodegradable packaging certified to Australian AS 4736 standards lacks industrial composting facility access across Southeast Asian markets, undermining end-of-life claims.
- Multi-standard certification complexity:Converters must simultaneously satisfy Japan's METI circular economy guidelines, China's GB standards, and Australia's National Packaging Targets for multinational brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Protective Packaging Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bubble Wrap, Foam, Protective Mailers, Inserts Material: Plastic, Paper, Biodegradable, Metal End User: Electronics, Food & Beverage, Pharmaceuticals, E-commerce Application: Transit Packaging, Retail Packaging, Loose Fill, Custom Packaging |
| Companies Covered | Intertape Polymer Group Inc, Storopack Hans Reichenecker GmbH, Sonoco Products Company, International Paper Company, Pro-Pac Packaging Limited, Sealed Air Corporation, Signode Protective Packaging Solutions, Huhtamaki Group, DS Smith PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Protective Packaging Market Strategic Shifts
Active substrate substitution and regulatory harmonization pressures are compressing specification timelines across Asia-Pacific protective packaging, with fiber-based systems gaining share in segments previously dominated by engineered foams.
Molded pulp cushioning derived from agricultural residue is absorbing impact protection demand from expanded polystyrene in consumer electronics transit. South Korean smartphone exporters are qualifying bagasse-fiber corner blocks for ocean freight containers. This substitution is absorbing volume from petroleum-based alternatives as carbon accounting tightens in procurement specifications.
Japan's METI circular economy frameworks now mandate recycled content thresholds for transit packaging used in domestic distribution. Industrial consequences include accelerated converter investment in post-consumer fiber processing lines. Electronics and appliance manufacturers are responding by consolidating supplier panels to vendors with certified closed-loop material flows.
Brand owners are unbundling damage-rate guarantees from logistics contracts and assigning financial responsibility to packaging specifiers. Third-party fulfillment operators in China's Pearl River Delta are absorbing this risk transfer by demanding performance-based cushioning validation. This shift is most visible in cross-border e-commerce channels serving European consumers under EPR compliance obligations.
Asia-Pacific Protective Packaging Market Segmentation
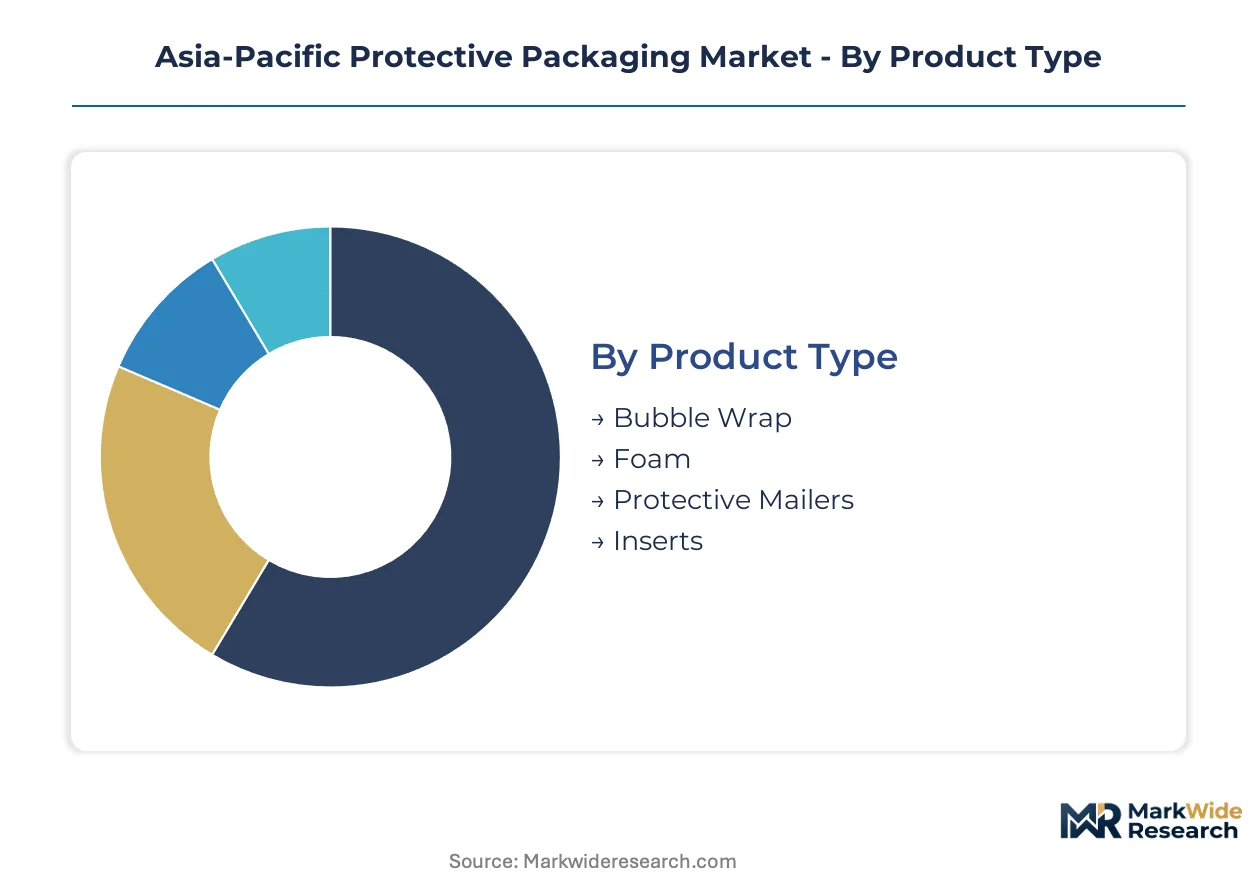
Protective packaging procurement across Asia-Pacific follows distinct specification pathways where substrate selection, drop-test performance, and end-of-life compliance intersect. Electronics assemblers and e-commerce operators drive divergent demand profiles across these four segmentation dimensions.
Product Type:
Engineering specifications and damage-rate guarantees dominate buyer evaluation, with cushioning efficiency measured against ASTM D1596 or JIS Z 0232 drop-test protocols.
- Foam:Polyethylene and polyurethane foam systems deliver calibrated shock absorption for semiconductor transit and industrial equipment. South Korean chip manufacturers specify anti-static formulations for wafer shipment protection. Volume concentrates in industrial applications where repeated impact cycles govern material selection.
- Protective Mailers:Padded envelopes and bubble-lined pouches sustain the steepest expansion trajectory as Southeast Asian fulfillment centers scale cross-border parcel operations. Indonesia and Vietnam e-commerce hubs are qualifying fiber-based alternatives to plastic film laminates under MEE carbon intensity benchmarks.
- Bubble Wrap:Air-retention films in standard and anti-static grades serve secondary cushioning and surface protection roles. China's Yangtze River Delta converters face substrate transition pressure toward paper-based alternatives.
- Inserts:Die-cut foam and molded fiber components secure product positioning within primary containers. Custom geometries dominate electronics and appliance applications.
Volume sits with foam systems; growth tilts toward protective mailers.
Material:
Carbon accounting and recyclability mandates are restructuring converter procurement priorities across substrate categories.
- Plastic:Polyethylene films and expanded polystyrene retain industrial footholds where moisture resistance and repeated drop-test performance exceed fiber capabilities. MEE carbon intensity benchmarks are compressing virgin resin demand in Yangtze River Delta manufacturing clusters.
- Biodegradable:PLA and PBAT films certified to Australian AS 4736 and Japan's METI guidelines occupy emerging specification windows. Thailand's resin production concentration creates supply vulnerability for regional converters.
- Paper:Kraft liners, corrugated board, and molded fiber absorb substrate substitution demand from petroleum-based alternatives. China's dual carbon goals accelerate converter investment in post-consumer fiber processing.
- Metal:Aluminum barrier laminates and steel strapping serve niche pharmaceutical and heavy-machinery transit applications requiring oxygen exclusion or extreme load stability.
Plastic retains volume leadership; biodegradable materials are climbing the fastest.
End User:
Damage-rate liability allocation and regulatory compliance obligations differentiate procurement behavior across customer verticals.
- Electronics:Semiconductor and consumer device manufacturers specify anti-static films, engineered foam, and precision-molded fiber for chip and display transit. China's Pearl River Delta and South Korean production corridors concentrate demand.
- E-commerce:Third-party fulfillment operators absorb financial responsibility for damage rates, driving performance-based cushioning validation. Cross-border channels serving European consumers face EPR compliance obligations.
- Food & Beverage:Temperature-stable molded fiber and barrier-coated paperboard serve chilled and ambient transit applications. India's BIS packaging standards evolution creates specification windows for certified fiber solutions.
- Pharmaceuticals:Serialization requirements and temperature integrity mandates elevate barrier performance specifications. Australia's TGA guidelines and India's CDSCO traceability rules govern material selection.
Electronics commands volume priority; e-commerce channels are expanding most quickly.
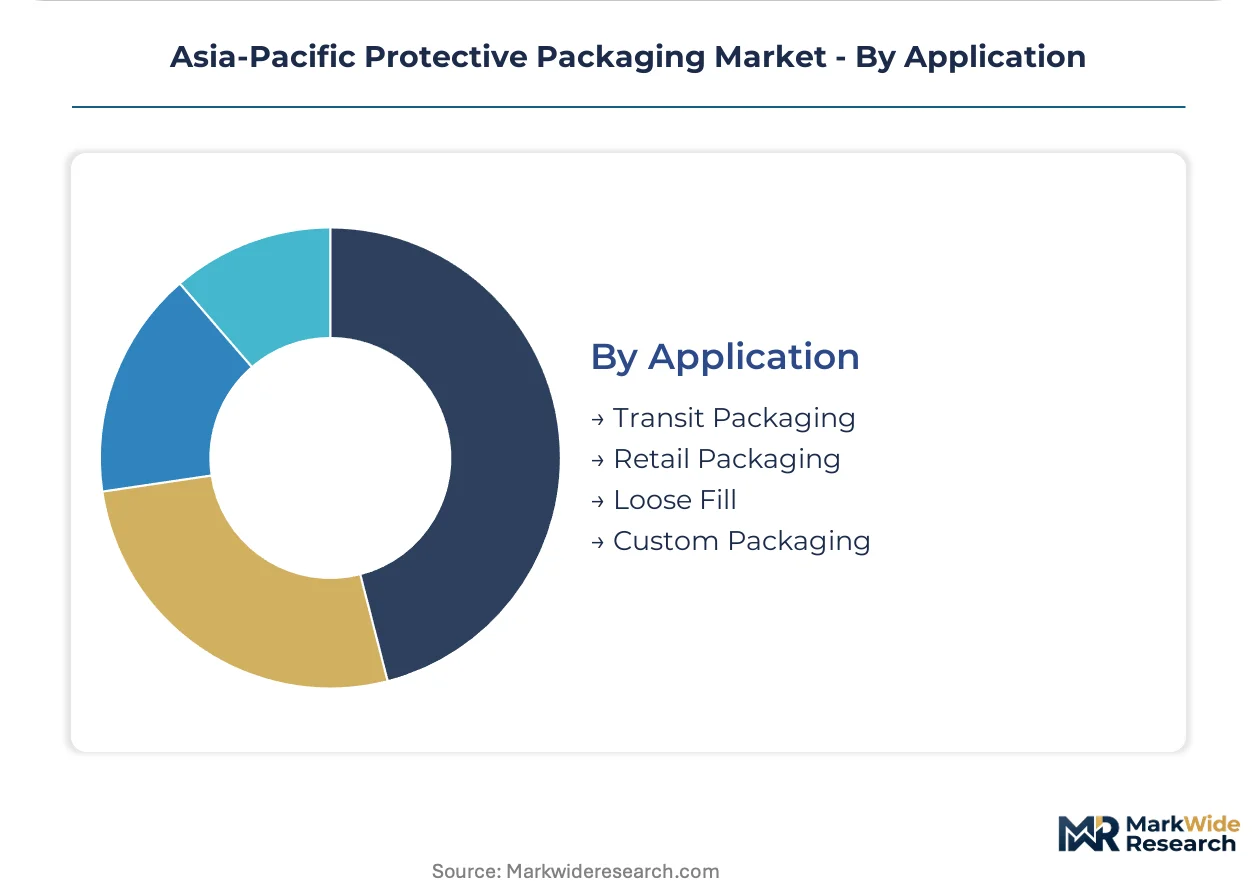
Application:
Logistics contract structures and return-loop economics determine specification complexity across usage modes.
- Transit Packaging:Primary and secondary containment systems for ocean freight and last-mile distribution absorb the majority of regional consumption. Japan-ASEAN automotive component corridors are piloting returnable pooling models.
- Custom Packaging:Engineered solutions for high-value electronics and medical devices integrate impact sensors and real-time monitoring. Australia's National Packaging Targets filter through multinational brand owner requirements.
- Loose Fill:Void-filling peanuts and shredded paper occupy low-specification, cost-sensitive segments. Biodegradable starch-based alternatives face composting infrastructure constraints across Southeast Asian markets.
- Retail Packaging:Shelf-ready protective formats serve omnichannel fulfillment where display and protection functions merge. China's GB standards and Japan's JIS specifications create multi-standard certification complexity for converters.
Transit packaging anchors volume; custom applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in China's coastal manufacturing belts while consumption spreads across Southeast Asian e-commerce fulfillment networks. This geographic split shapes substrate specifications and regulatory compliance requirements across national boundaries.
China
Electronics assemblers in the Yangtze River Delta and Pearl River Delta are scaling molded fiber procurement for smartphone and semiconductor export packaging. MEE carbon intensity benchmarks force substrate transitions from virgin polyethylene toward agricultural residue-based cushioning. Suzhou and Dongguan converter facilities are retrofitting lines to handle post-consumer pulp streams under dual carbon compliance deadlines.
Japan
Precision equipment manufacturers specify anti-static foam systems for robotics and medical device transit protection. METI circular economy frameworks mandate recycled content thresholds for domestic distribution packaging. Osaka and Nagoya industrial corridors concentrate supplier consolidation as brand owners reduce vendor panels to certified closed-loop material flow operators.
South Korea
Semiconductor foundries drive demand for engineered cushioning and barrier films protecting wafer shipments to ASEAN assembly plants. The national industrial regulator enforces packaging traceability standards aligned with chip export documentation requirements. Seoul Capital Area and Busan-Ulsan corridors dominate specification development for regional electronics supply chains.
India
Food and pharmaceutical transit applications absorb expanding molded fiber capacity as BIS packaging standards evolve toward recyclability mandates. Cold-chain infrastructure gaps create specification windows for temperature-stable barrier-coated solutions. Maharashtra and Gujarat manufacturing clusters attract converter investment serving domestic FMCG and generic drug export markets.
Vietnam
E-commerce fulfillment centers in Ho Chi Minh City and Hanoi are qualifying fiber-based protective mailers for cross-border retail volumes. Phased compliance timelines under ASEAN packaging harmonization frameworks allow gradual substrate transitions. Northern industrial provinces concentrate electronics assembly transit packaging demand from China-origin component supply chains.
Asia-Pacific Protective Packaging Market Competitive Environment
The competitive structure tilts toward diversified material specialists with cross-substrate formulation capabilities. Mid-scale converters compete on specification agility rather than volume scale. Three archetypes dominate: integrated paperboard-fiber operators, engineered foam compounders, and film-laminate specialists. Capacity expansion and strategic partnerships represent the primary competitive moves as converters seek substrate breadth and geographic coverage.
Among North American-anchored multinationals, Sealed Air Corporation and Sonoco Products Company exemplify the integrated material specialist archetype with regional R&D footprints. DS Smith PLC represents the European paperboard operator segment with molded fiber capacity serving Asian electronics exporters. Storopack Hans Reichenecker GmbH and Huhtamaki Group occupy positions within the fiber-based cushioning tier, with the latter anchoring food and beverage transit applications through agricultural residue processing capabilities.
| Leading Market Players |
|---|
| Intertape Polymer Group Inc |
| Storopack Hans Reichenecker GmbH |
| Sonoco Products Company |
| International Paper Company |
| Pro-Pac Packaging Limited |
| Sealed Air Corporation |
| Signode Protective Packaging Solutions |
| Huhtamaki Group |
| DS Smith PLC |
| Others |
Value Chain & Pricing Dynamics
Bleached kraft pulp futures transmit volatility through molded fiber pricing tiers, with Yangtze River Delta converters absorbing margin compression when agricultural residue feedstock costs spike against MEE carbon compliance deadlines. This input-cost pathway separates premium certified-fiber specifications from economy-grade polyethylene alternatives in electronics transit procurement.
Pricing Analysis
Damage-rate guarantees anchor value-based pricing for third-party fulfillment operators absorbing financial liability for cross-border e-commerce shipments. Three-tier pricing structure across premium anti-static foam, standard molded fiber, and economy polyethylene separates specifications by drop-test certification grade and carbon-accounting traceability. Pricing pressure stems from pulp price volatility limiting converter capacity expansion timing. E-commerce fulfillment channels exhibit highest price sensitivity; semiconductor foundries prioritize performance validation over unit cost.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale electronics manufacturer demand, while distribution through regional packaging distributors serves mid-tier fulfillment operators. Raw material supply draws from Thailand and China for PLA and PBAT biodegradable resins, bleached kraft pulp from Scandinavian and Southeast Asian mills, and petroleum-based feedstocks from South Korean petrochemical complexes. Single-source vulnerability concentrates in certified compostable film specifications. Logistics chokepoints at Shanghai and Busan container ports amplify lead-time risk for just-in-time electronics assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MEE carbon intensity benchmarks function as a cost-of-compliance moat, elevating capital requirements for substrate transition and filtering non-compliant converters from Yangtze River Delta supplier panels.
For Market Incumbents: Lock in closed-loop fiber processing capabilities through backward integration into post-consumer pulp streams before MEE dual carbon deadlines harden specification requirements. Secure agricultural residue supply contracts to defend margin position against virgin pulp price spikes. Certify multi-standard compliance across METI, BIS, and AS 4736 frameworks to consolidate multinational brand owner supplier panels. For New Entrants and Emerging Players: Enter via India's evolving BIS recyclability mandates where specification windows for barrier-coated fiber solutions remain underpenetrated by established molded fiber operators. Target Vietnam's Ho Chi Minh City e-commerce fulfillment corridor with fiber-based protective mailer alternatives to plastic film laminates. Lead with carbon-accounting transparency as the primary go-to-market angle for European-facing cross-border channels. For Investors and Strategic Acquirers: MEE enforcement actions against non-compliant converters are the leading indicator that substrate transition capacity will command scarcity premiums across the analysis window. Position acquisition screening around mid-scale converters with multi-substrate formulation agility and existing certification infrastructure. Monitor pulp futures spread compression against agricultural residue pricing as the inflection signal for molded fiber margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Processing | Captures feedstock cost control for MEE-compliant molded fiber capacity serving Yangtze River Delta electronics exporters. |
| Multi-Standard Certification Investment | Enables simultaneous compliance with METI circular economy guidelines, BIS packaging standards, and Australia's National Packaging Targets. |
| Returnable Packaging System Deployment | Reduces single-use consumption in Japan-ASEAN automotive component corridors through closed-loop pooling economics. |
| Smart Packaging Convergence Development | Integrates impact sensors with protective mailers for real-time damage attribution in high-value electronics fulfillment. |
| Regional Distribution Partnership Expansion | Secures channel access for mid-tier e-commerce fulfillment operators in Vietnam and Indonesia cross-border retail markets. |
Study Parameters
Document review covered customs and trade flow databases, converter capacity registries, and regulatory filings from MEE, METI, and BIS, complemented by interviews with procurement directors at electronics assemblers, plant managers at molded fiber facilities, sustainability officers at multinational brand owners, and logistics operators at third-party fulfillment centers. Secondary validation drew from pulp futures exchange data, ASEAN packaging harmonization framework documents, and industrial composting infrastructure assessments. Bottom-up volume estimates triangulated against top-down market sizing across substrate categories.
Segment-level projections incorporated product type, material substrate, end-use vertical, and application mode dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves responsive to carbon pricing trajectories and e-commerce parcel volume growth assumptions. Forecast inputs included MEE compliance deadline phasing, pulp price volatility bands, and biodegradable resin production capacity expansion schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt pulp price spikes or accelerated MEE enforcement timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
Adhesive Bubble Wrap Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Protective Packaging Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Tamper Proof Packaging Market