
 Flavored Salt Market | 2026-2036
Flavored Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Flavored Salt Market Insights
Aftermarket recipe content and culinary education revenue is tilting from generic seasoning brands toward artisan salt specialists. McCormick & Company leverages its distribution depth to occupy mainstream retail shelf space. Jacobsen Salt Co. differentiates through Pacific Northwest provenance and hand-harvesting credentials. Maldon Salt Company anchors British heritage positioning in premium export markets.
Flavored salt denotes sodium chloride base crystals infused with botanical extracts, spice oleoresins, smoke condensates, or fermentation-derived compounds, typically processed through tumble-coating, liquid injection, or vacuum impregnation to achieve uniform flavor distribution and moisture stability below 0.5 percent. The product serves as a finishing condiment and formulation ingredient across commercial kitchens, CPG manufacturing, and direct-to-consumer channels. Herbal salt and umami salt command the widest penetration in foodservice, while smoky salt and citrus salt represent the fastest-expanding margin pools as bartenders and pastry chefs adopt savory-sweet crossover applications. Sachet packs and shaker bottles dominate unit volume, though refillable containers capture disproportionate margin among premium consumers and gourmet shops.
FDA oversight of sodium disclosure and EFSA sodium reduction benchmarks shape product reformulation and front-of-pack communication strategies, while FSSAI labeling mandates in India and Japan's JIS standards for food-grade salt purity influence export qualification pathways. Stakeholders must monitor evolving sodium threshold regulations and certification requirements to preserve market access and justify price positioning.
Market Dynamics
Clean-label sodium disclosure mandates under FDA and EFSA frameworks are forcing flavored salt producers to reformulate recipes and redesign front-of-pack communication, compressing lead times for new product launches while elevating R&D expenditure as a structural cost layer.
Growth Catalysts
- EFSA sodium reduction benchmarks:These targets compel CPG manufacturers to reformulate with specialty salts that deliver equivalent taste intensity at lower sodium loads, expanding procurement of umami and mineral-enhanced variants.
- Foodservice premiumization:Michelin-rated kitchens and craft cocktail programs in the United States, France, and Japan are anchoring demand for finishing salts with traceable provenance and botanical infusions.
- Vacuum impregnation technology:This processing method achieves sub-0.5% moisture stability in smoke and citrus salt applications, enabling extended shelf life without synthetic anti-caking agents.
Market Restraints
- Evaporative solar salt supply concentration:Harvesting operations cluster in specific coastal microclimates, exposing processors to weather-induced yield volatility and geographic supply disruption.
- Botanical extract input costs:Oleoresin and smoke condensate prices fluctuate with spice harvest cycles and energy-intensive extraction processes, compressing margin on premium SKUs.
- Substitution by unflavored sea salt:Price-sensitive food manufacturers and home cooks in mass retail channels default to commodity salt with separate seasoning blends, limiting flavored salt penetration in economy tiers.
Strategic Opportunities
- India FSSAI labeling pathway:Export qualification under evolving domestic standards opens access to a foodservice sector undergoing rapid premiumization in metropolitan centers.
- Convergence of fermentation science and salt curing:Collaboration between koji specialists and salt producers creates novel umami delivery systems for plant-based protein applications.
- Direct-to-consumer subscription channels:Refillable container models bypass conventional retail slotting fees while capturing recurring revenue from gourmet home cooks.
Industry Challenges
- Sensory panel calibration:Maintaining consistent flavor intensity across harvest batches requires specialized tasting protocols and trained evaluators that mid-tier producers struggle to retain.
- Dual certification timelines:Simultaneous pursuit of organic and kosher designations extends product development cycles by 8-14 months, delaying market entry.
- Legacy ERP integration:Lot traceability requirements for botanical sourcing clash with decades-old inventory management systems at established salt processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavored Salt Market |
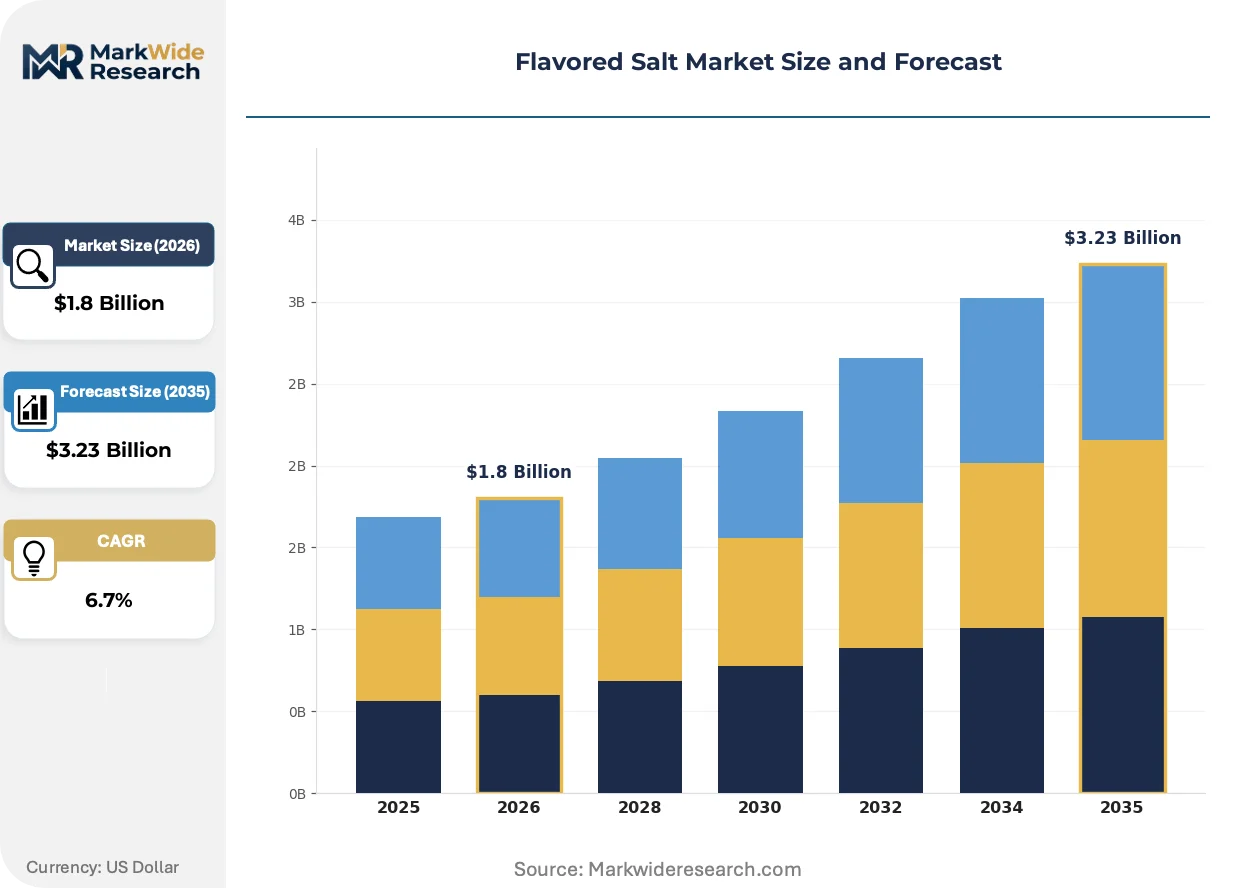
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Salt, Spicy Salt, Sweet Salt, Smoky Salt, Citrus Salt, Umami Salt Application: Home Cooking, Foodservice, Meat Processing, Seafood Preparation, Snack Seasoning, Beverage Enhancer Packaging Type: Shaker Bottle, Sachet Pack, Jar, Bulk Bag, Refillable Container, Tub Customer Type: Premium Consumers, Culinary Professionals, Gourmet Shops, Specialty Retailers, Online Buyers, Food Manufacturers |
| Companies Covered | McCormick & Company, SaltWorks, Morton Salt, San Francisco Salt Company, Jacobsen Salt Co., Maldon Salt Company, The Spice Lab, Bitterman Salt Co., Cornish Sea Salt Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavored Salt Market Trends and Innovations
Digital sensory mapping and rapid formulation prototyping are compressing the innovation cycle from concept to commercial launch, while regulatory disclosure requirements and channel fragmentation reshape how flavored salt reaches end users.
Artificial intelligence-driven flavor compound prediction is virtualizing the traditional artisan blending process. Machine learning models trained on gas chromatography data now suggest botanical pairings that human tasters validate. Mid-sized producers in Oregon and Provence are adopting these platforms to accelerate SKU expansion. This capability is virtualizing the competitive moat once held by generational salt masters with intuitive palates.
Japan's JIS standards for food-grade salt purity are tightening heavy metal thresholds and microbial specifications for imported products. Exporters to the Japanese market must now submit third-party laboratory documentation with every shipment. This regulatory friction is elevating compliance costs for European and North American suppliers. Premium positioning now requires explicit certification badges on packaging to signal adherence.
Chef-driven content creation on streaming platforms is displacing traditional cookbook authority as the primary demand stimulus. Culinary professionals in test kitchens now function as de facto brand ambassadors, with recipe integration replacing conventional advertising spend. This shift concentrates influence among visible personalities rather than institutional food media. The phenomenon is most pronounced in the United States and France, where subscriber-funded platforms reward specialized technique demonstration.
Flavored Salt Market Segmentation
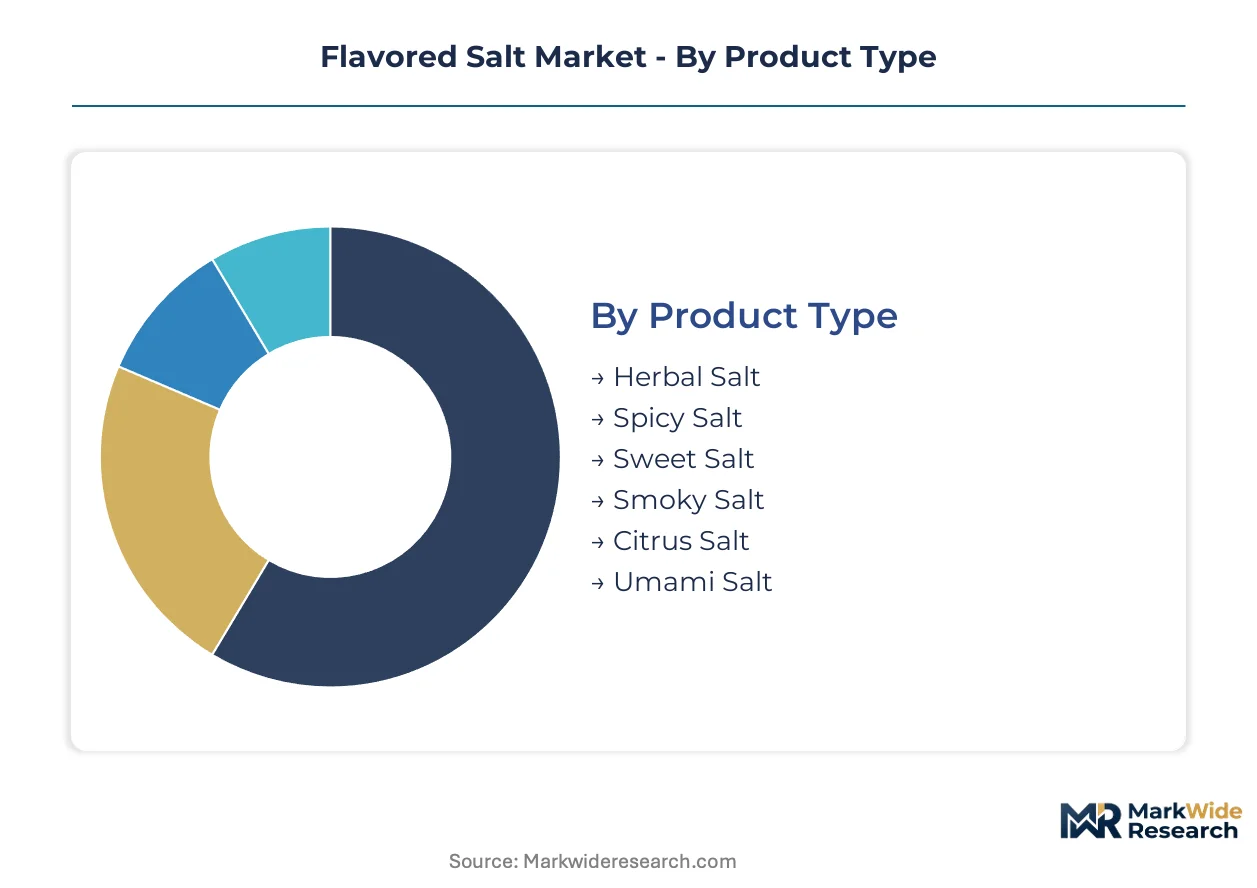
Segmentation in the flavored salt market reveals how procurement patterns diverge across use cases and buyer sophistication. Each dimension—product chemistry, application environment, packaging format, and customer archetype—carries distinct margin structures and regulatory exposure that shape supplier strategy.
Product Type:
Cost tier stratification across flavored salt variants determines R&D allocation and botanical input sourcing intensity.
- Herbal Salt:Sodium chloride base infused with dried herb particulates or essential oil extracts such as rosemary, thyme, and basil. Demand concentrates in French and Italian foodservice channels where chefs deploy finishing salts to signal provenance without additional prep steps. The segment commands stable volume through institutional procurement contracts with Mediterranean-focused restaurant groups.
- Umami Salt:Crystals enhanced with glutamate-rich compounds, yeast extracts, or fermented koji derivatives that amplify savory perception at reduced sodium loads. Japanese and United States CPG manufacturers are expanding procurement to meet EFSA and FDA sodium reduction benchmarks in processed foods. This variant carries the highest technical barrier due to fermentation science requirements and flavor stability testing.
- Spicy Salt:Heat delivery through capsicum oleoresins or dried chili flake suspension.
- Sweet Salt:Caramelized sugar or vanilla-infused crystals targeting pastry and dessert applications.
- Smoky Salt:Cold-smoked or liquid smoke-impregnated crystals for barbecue and mixology segments.
- Citrus Salt:Zest-derived or cold-pressed oil coatings for seafood and cocktail finishing.
Herbal salt holds installed capacity. Umami salt is rotating up the share rankings.
Application:
Volume concentration varies sharply between household units and industrial-scale formulation.
- Foodservice:Michelin-rated kitchens and craft cocktail programs in the United States, France, and Japan drive demand for traceable provenance and small-batch botanical infusions. This segment absorbs premium pricing for hand-harvested credentials and limited seasonal releases.
- Food Manufacturers:CPG processors reformulate savory snacks, ready meals, and meat products with specialty salts to achieve clean-label sodium reduction while maintaining taste intensity. EFSA benchmarks and FDA disclosure mandates are accelerating procurement of mineral-enhanced and umami variants.
- Home Cooking:Direct-to-consumer channels and gourmet retail serve enthusiast home cooks seeking restaurant-quality finishing.
- Meat Processing:Curing and flavoring applications in artisan and industrial charcuterie.
- Seafood Preparation:Delicate citrus and herbal variants for raw and lightly cooked fish.
- Snack Seasoning:High-volume tumble-coating applications for chips and extruded snacks.
- Beverage Enhancer:Salt rims and saline solutions for craft cocktails and non-alcoholic drinks.
Food manufacturers hold installed capacity. Foodservice is rotating up the share rankings.
Packaging Type:
Customer type and channel economics dictate format selection across convenience, sustainability, and bulk efficiency priorities.
- Shaker Bottle:Standard retail format with moisture-resistant closures and flow-control apertures. Mass-market penetration in United States and European supermarkets depends on slotting fee negotiations and shelf placement velocity.
- Refillable Container:Ceramic or glass vessels with subscription refill programs. Premium consumers and gourmet shops in metropolitan United States and Japanese cities drive adoption, bypassing conventional retail margin structures through direct-to-consumer channels.
- Sachet Pack:Single-serve portions for foodservice and airline catering.
- Jar:Wide-mouth glass containers for home pantry storage and gifting.
- Bulk Bag:Industrial-scale packaging for food manufacturers and meat processors.
- Tub:Stackable plastic containers for professional kitchen high-volume access.
Shaker bottles hold installed capacity. Refillable containers are rotating up the share rankings.
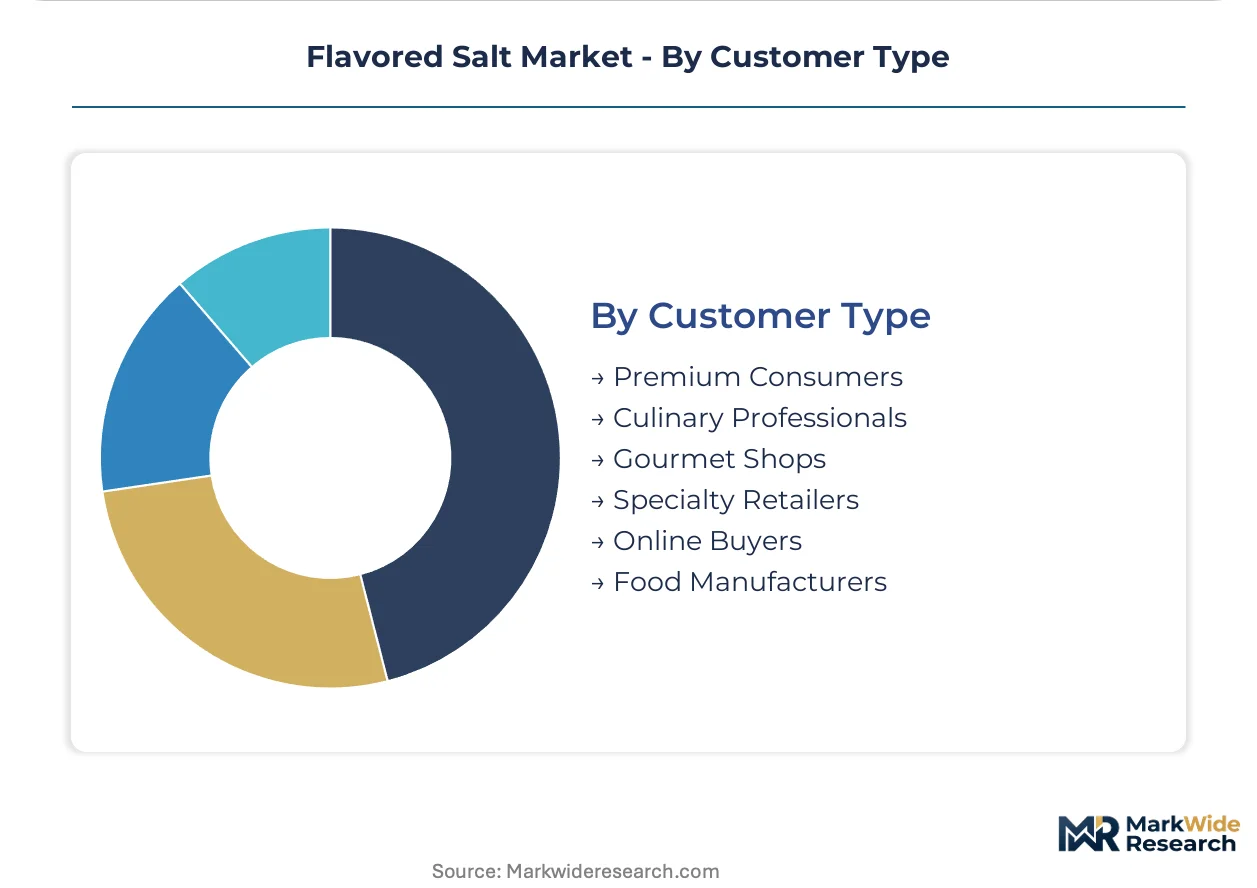
Customer Type:
Margin structure and purchasing behavior diverge across buyer sophistication and scale.
- Culinary Professionals:Executive chefs and pastry specialists in the United States, France, and Japan source through specialty distributors and direct relationships with artisan producers. This segment prioritizes batch traceability, seasonal limited releases, and collaborative product development over unit cost.
- Premium Consumers:Affluent home cooks purchasing through gourmet shops, farmers markets, and subscription services. Japanese and French buyers show particular willingness to pay for regional provenance and hand-harvesting credentials.
- Gourmet Shops:Curated retail environments with educated staff and tasting protocols.
- Specialty Retailers:Regional chains and independents with focused culinary assortments.
- Online Buyers:Direct-to-consumer purchasers responding to chef-driven content and recipe integration.
- Food Manufacturers:Industrial buyers with formulation specifications, lot traceability requirements, and annual volume contracts.
Culinary professionals hold installed capacity. Premium consumers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. French kitchens treat flavored salt as terroir expression, while Japanese manufacturers deploy it as sodium-reduction technology, and American buyers oscillate between craft provenance and mass convenience.
United States
Foodservice premiumization and direct-to-consumer subscription channels drive procurement. FDA sodium disclosure mandates under the Nutrition Labeling and Education Act compel front-of-pack reformulation. Pacific Northwest clusters around Portland and Seattle anchor artisan hand-harvesting operations with chef-direct supply relationships.
France
Michelin-rated kitchens in Paris and Lyon source traceable herbal salts as finishing condiments. EFSA sodium reduction benchmarks shape reformulation partnerships between salt processors and CPG manufacturers. Provence-Alpes-Côte d'Azur concentrates Mediterranean herb infusion specialists serving export markets.
Japan
Umami salt variants dominate procurement by food manufacturers meeting JIS standards for food-grade purity. METI guidelines on processed food sodium content accelerate mineral-enhanced salt adoption. Kanto region processors around Tokyo supply fermentation-derived glutamate formulations to plant-based protein developers.
India
Metropolitan foodservice in Mumbai and Bangalore drives premiumization of specialty salts for upscale dining. FSSAI labeling mandates for sodium disclosure create compliance thresholds for imported products. Gujarat coastal solar harvesting operations supply base material to domestic flavoring facilities.
United Kingdom
Gourmet retail channels in London and Edinburgh absorb heritage-positioned finishing salts for home cooking applications. Trading standards alignment with EFSA frameworks governs import qualification from European suppliers. Cornwall and Essex host coastal harvesting operations with export certification to Commonwealth markets.
Flavored Salt Market Competitive Landscape
Capability concentration sits with artisan specialists commanding chef relationships and provenance narratives; scale advantage sits with diversified seasoning conglomerates with retail distribution depth. The market structures around three tiers: mass-market processors with private-label capacity, mid-sized regional artisans with botanical expertise, and luxury heritage houses with generational harvesting credentials. Dominant competitive moves include backward integration into coastal salt harvesting operations and technology licensing for vacuum impregnation processing.
Among heritage-positioned British specialists, Maldon Salt Company exemplifies export-market premiumization through controlled geographic indication. Jacobsen Salt Co. occupies the American artisan tier with Pacific Northwest provenance credentials. McCormick & Company anchors mass-market penetration through retail slotting leverage and formulation scale. These three represent distinct strategic archetypes rather than direct competitors, each capturing margin through non-overlapping channel access and buyer segmentation.
| Leading Market Players |
|---|
| McCormick & Company |
| SaltWorks |
| Morton Salt |
| San Francisco Salt Company |
| Jacobsen Salt Co. |
| Maldon Salt Company |
| The Spice Lab |
| Bitterman Salt Co. |
| Cornish Sea Salt Company |
| Others |
Pricing and Supply Chain Analysis
Evaporative solar salt harvesting concentration in specific coastal microclimates determines both three-tier pricing structure across premium, standard, and economy levels and supply chain resilience architecture for flavored salt processors. Weather-induced yield volatility in these concentrated sourcing zones compresses margin pools for mid-tier producers while elevating premium pricing power for heritage houses with captive harvesting operations.
Pricing Analysis
Long-term offtake contracts with Michelin-rated kitchens and CPG manufacturers anchor pricing stability for heritage producers, while spot-market transactions dominate commodity salt procurement by mass-market processors. Price differentiation hinges on hand-harvesting credentials and organic certification tier, with FDA sodium disclosure compliance adding a regulatory premium tier. Pricing pressure stems from botanical extract input cost volatility, particularly oleoresin and smoke condensate fluctuations. Food manufacturers exhibit highest price sensitivity due to formulation scale requirements, whereas culinary professionals absorb premium positioning for traceable provenance.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized salt processors in the United States, France, and Japan that hold vacuum impregnation capacity and JIS certification for food-grade purity. Raw material dependencies center on Pacific Northwest and Mediterranean coastal solar salt, capsicum oleoresins from spice harvest regions, and fermentation-derived koji compounds from Kanto-area specialists. Supply chain risk concentrates in single-source vulnerability for smoke condensate extraction facilities. Distribution runs through specialty foodservice distributors for premium tiers and conventional grocery slotting agreements for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flavored salt market functions as a defensive-moat story where regulatory entrenchment through FDA, EFSA, and JIS certification requirements creates substantial switching costs for institutional buyers.
For Market Incumbents: Insulate market position through backward integration into coastal salt harvesting operations in Oregon, Provence, or Cornwall to secure captive supply against weather-induced yield volatility. Deepen chef-direct relationships with collaborative product development programs that embed proprietary formulations into restaurant operations, raising switching costs for culinary professionals. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription channels with refillable container models that bypass conventional retail slotting fees and capture recurring revenue from gourmet home cooks. Target metropolitan foodservice in Indian cities such as Mumbai and Bangalore where FSSAI labeling mandates create compliance thresholds that favor agile specialists over legacy importers. For Investors and Strategic Acquirers: The market sits at a premiumization phase that favors heritage-positioned specialists with generational harvesting credentials and established export certification pathways. Acquisition targets should display concentrated chef relationships and provenance narratives that resist commoditization. The signal to watch is EFSA sodium reduction benchmark acceleration, which will expand procurement of umami and mineral-enhanced variants by CPG manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coastal Harvesting | Captive supply of Pacific Northwest solar salt insulates against weather volatility and elevates provenance credentials. |
| Direct-to-Consumer Subscription Launch | Refillable container models bypass retail slotting fees while capturing recurring revenue from Japanese and American gourmet home cooks. |
| Fermentation Science Collaboration | Partnerships with koji specialists create novel umami delivery systems for plant-based protein applications meeting EFSA benchmarks. |
| Dual Certification Investment | Simultaneous organic and kosher designations extend product development cycles but unlock premium channel access in United States and European markets. |
| Chef-Driven Content Integration | Recipe embedding with streaming platform culinary professionals displaces traditional advertising spend in United States and French markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with executive chefs, CPG formulation scientists, specialty salt procurement managers, and gourmet retail category buyers. Secondary validation drew from FDA sodium disclosure filings, EFSA scientific opinions on sodium reduction, JIS food-grade salt purity standards, and customs trade data for flavored salt imports. Bottom-up volume modeling across product type, application environment, packaging format, and customer archetype segments was triangulated with top-down market sizing from trade association publications and regulatory agency documentation.
Calibration against historical volume trajectories and regulatory implementation timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use environment, packaging format economics, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis and constraint boundary assessment. Industry-specific forecast inputs encompassed botanical extract price indices and chef-driven content platform subscriber growth patterns.
Stress conditions across evaporative solar salt harvest yields, capsicum oleoresin price volatility, and EFSA sodium threshold enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory adherence rates and premium consumer willingness-to-pay trajectories. Quarterly review of FDA disclosure mandate implementation pace and FSSAI labeling pathway evolution is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Winter Melon Peel Extract Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Coloring Foodstuffs Market