
 North America Vanilla and Vanillin Market | 2026-2036
North America Vanilla and Vanillin Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vanilla and Vanillin Market Intelligence
Modular flavor-system bundling is restructuring how food manufacturers source vanilla inputs, with buyers increasingly demanding pre-blended vanilla-vanillin solutions rather than separate procurement of extracts and synthetic alternatives. Givaudan leverages its integrated flavor creation platforms to anchor large-scale supply contracts with North American CPG brands. McCormick competes through retail channel control and consumer-facing brand equity in the pure vanilla extract segment. International Flavors & Fragrances sustains R&D intensity in biotechnology-derived vanillin, positioning its portfolio for regulatory scrutiny on petrochemical-based synthetic routes.
Vanilla and vanillin encompass the aromatic compounds and extracts derived from cured Vanilla planifolia orchid pods or synthesized through chemical and biotechnological processes, with vanillin (4-hydroxy-3-methoxybenzaldehyde) constituting the primary organoleptic compound responsible for characteristic flavor perception. These inputs serve as foundational flavoring agents across food matrices, cosmetic formulations, and pharmaceutical coatings where thermal stability and dosage precision govern functional performance. Natural vanilla extract commands premium positioning among clean-label food manufacturers, while synthetic vanillin occupies high-volume, cost-sensitive applications in processed baked goods and confectionery. Pharmaceutical companies represent a concentrated margin pool, as USP-grade vanillin requirements for tablet coatings and masking agents impose stricter purity thresholds than standard food-grade specifications.
FDA flavor labeling regulations, EPA environmental compliance standards for chemical manufacturing facilities, and USDA organic certification requirements collectively shape product formulation decisions and facility siting across the United States and Canada. The FDA's distinction between "natural flavor" and "artificial flavor" declarations directly determines whether manufacturers specify vanilla extract or vanillin on ingredient panels, influencing consumer perception and procurement economics. Stakeholders must monitor evolving biotech-derived vanillin regulatory classifications, as fermentation-based production methods challenge traditional natural versus synthetic categorization frameworks and threaten to redraw competitive boundaries between extraction-dependent and laboratory-grown supply routes.
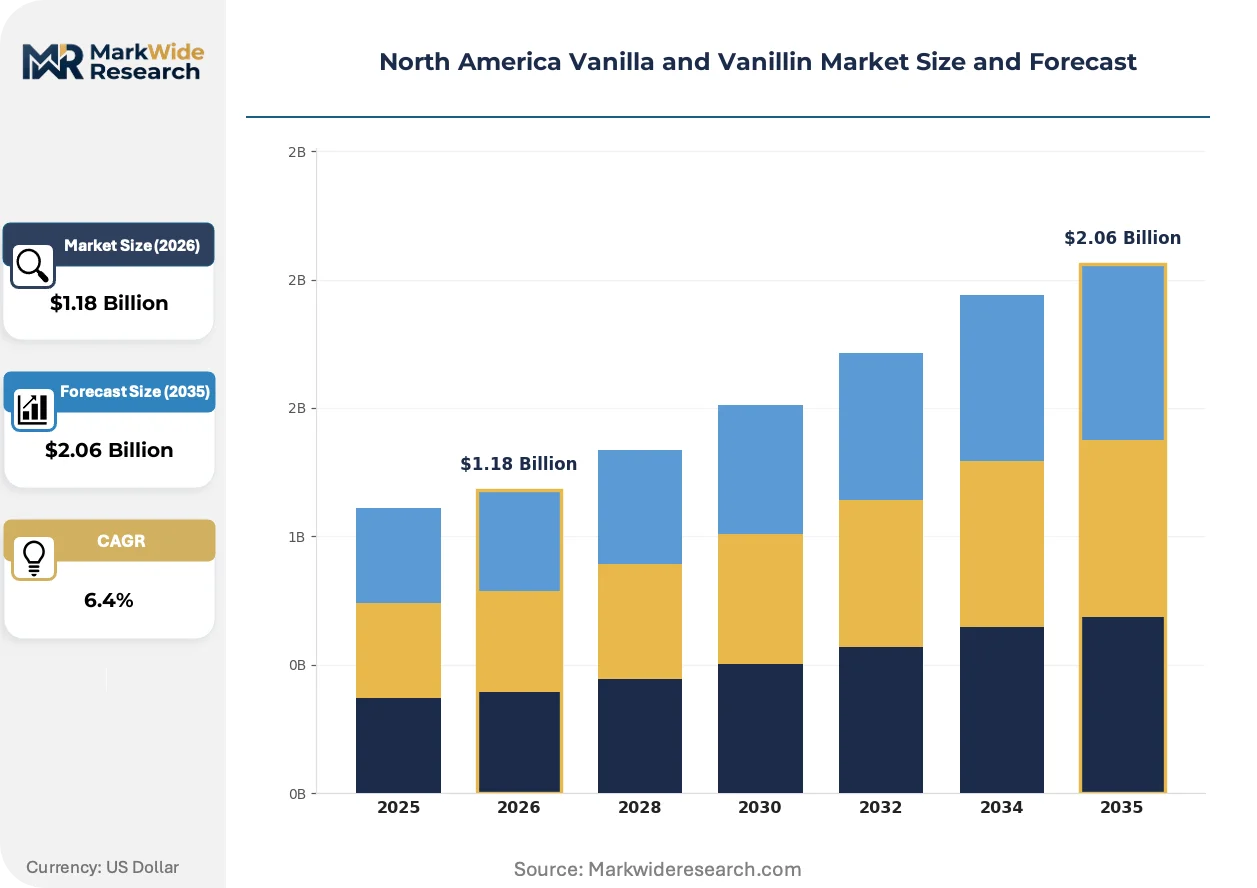
Market Dynamics
The North America vanilla and vanillin market is experiencing a structural pivot as biotechnology-derived production routes challenge century-old extraction economics, forcing incumbents to defend natural positioning while synthetic manufacturers navigate reclassification risks.
Growth Catalysts
- Clean-label bakery demand:Premium ice cream and craft beverage manufacturers across the United States are reformulating with natural vanilla extract to meet consumer transparency expectations.
- FDA labeling clarity:The FDA's tightening distinction between natural and artificial flavor declarations compels CPG brands to specify vanilla extract sourcing on ingredient panels.
- Pharmaceutical tablet coatings:USP-grade vanillin requirements for masking agents in oral solid dosage forms create concentrated margin pools with stricter purity thresholds than food-grade specifications.
Market Restraints
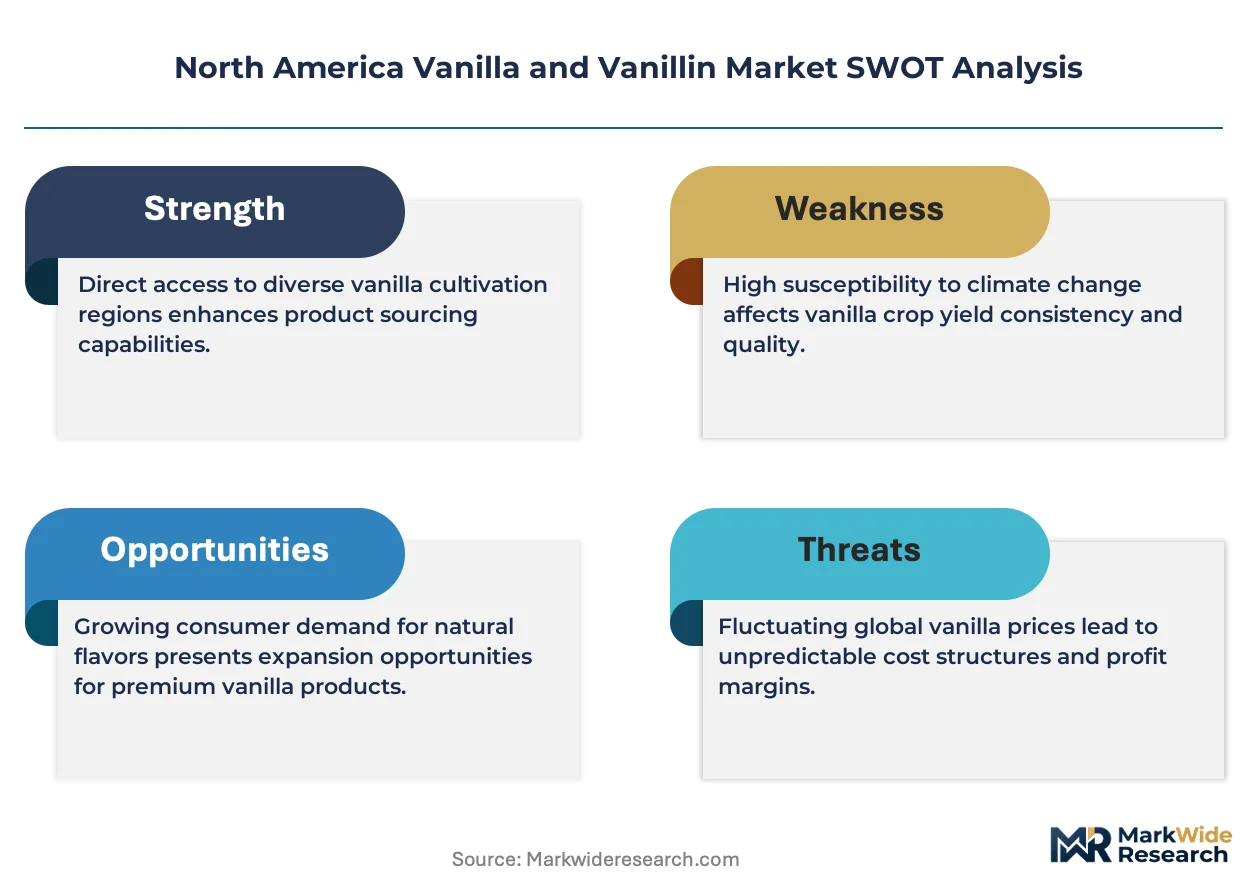
- Madagascar supply concentration:Over 80 percent of global vanilla bean cultivation remains concentrated in a single geography, exposing North American processors to cyclone-induced harvest volatility.
- Petrochemical route scrutiny:EPA environmental compliance standards for guaiacol-based synthetic vanillin manufacturing impose costly wastewater treatment and emissions controls.
- Biotech classification ambiguity:Fermentation-derived vanillin production challenges traditional natural versus synthetic categorization frameworks, creating regulatory uncertainty for manufacturers positioning products.
Strategic Opportunities
- Canadian organic certification:USDA organic certification requirements for vanilla cultivation create premium positioning for Canadian importers developing direct-trade relationships with certified cooperatives.
- Modular flavor-system bundling:Food manufacturers increasingly demand pre-blended vanilla-vanillin solutions rather than separate procurement, enabling integrated flavor houses to capture volume through supply contract consolidation.
- Cosmetic fragrance applications:Thermal stability properties of synthetic vanillin open formulation opportunities in perfumery and personal care products requiring aromatic compound persistence.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in organoleptic compound formulation and sensory evaluation remains concentrated among legacy flavor houses, constraining mid-tier manufacturer R&D capabilities.
- Biotech facility capex intensity:Fermentation-based vanillin production requires substantial capital investment in bioreactor infrastructure and downstream purification systems.
- Legacy extraction integration:Food manufacturers with established natural vanilla extract supply chains face technical complexity in blending biotechnology-derived alternatives without reformulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vanilla and Vanillin Market |
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Vanilla, Synthetic Vanillin, Vanilla Extract, Vanilla Beans Application: Food & Beverages, Cosmetics, Pharmaceuticals, Fragrance End User: Food Manufacturers, Beverage Producers, Personal Care Brands, Pharmaceutical Companies Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Givaudan, International Flavors & Fragrances, Advanced Biotech, Solvay, Borregaard AS, Prinova Group LLC, Symrise AG, McCormick, dsm-firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vanilla and Vanillin Market Strategic Shifts & Innovations
Biotechnology platforms and regulatory reclassification pressures are actively restructuring competitive boundaries between extraction-dependent and laboratory-grown supply routes across North American flavor procurement.
Precision fermentation is electrifying vanillin production economics by enabling microbial biosynthesis of 4-hydroxy-3-methoxybenzaldehyde from renewable feedstocks. Major CPG brands in the United States are piloting these inputs for 2025 product launches. This technological shift is compressing the cost differential between synthetic and natural-positioned alternatives while forcing extraction-dependent suppliers to defend provenance narratives.
The FDA's evolving framework for natural flavor declarations is creating compliance complexity for manufacturers using biotechnology-derived inputs. Food labeling regulations currently under review threaten to reclassify fermentation-based vanillin as artificial regardless of molecular identity. Canadian and United States food manufacturers are responding by diversifying sourcing strategies and engaging early with regulatory comment periods.
Contract consolidation among North American bakery and dairy processors is reshaping procurement relationships with vanilla suppliers. Large-scale manufacturers are consolidating vendor bases and demanding integrated flavor-system solutions rather than commodity extract purchases. This behavioral shift is most visible in the premium ice cream segment, where craft producers have begun bundling vanilla procurement with broader flavor development partnerships.
North America Vanilla and Vanillin Market Segmentation
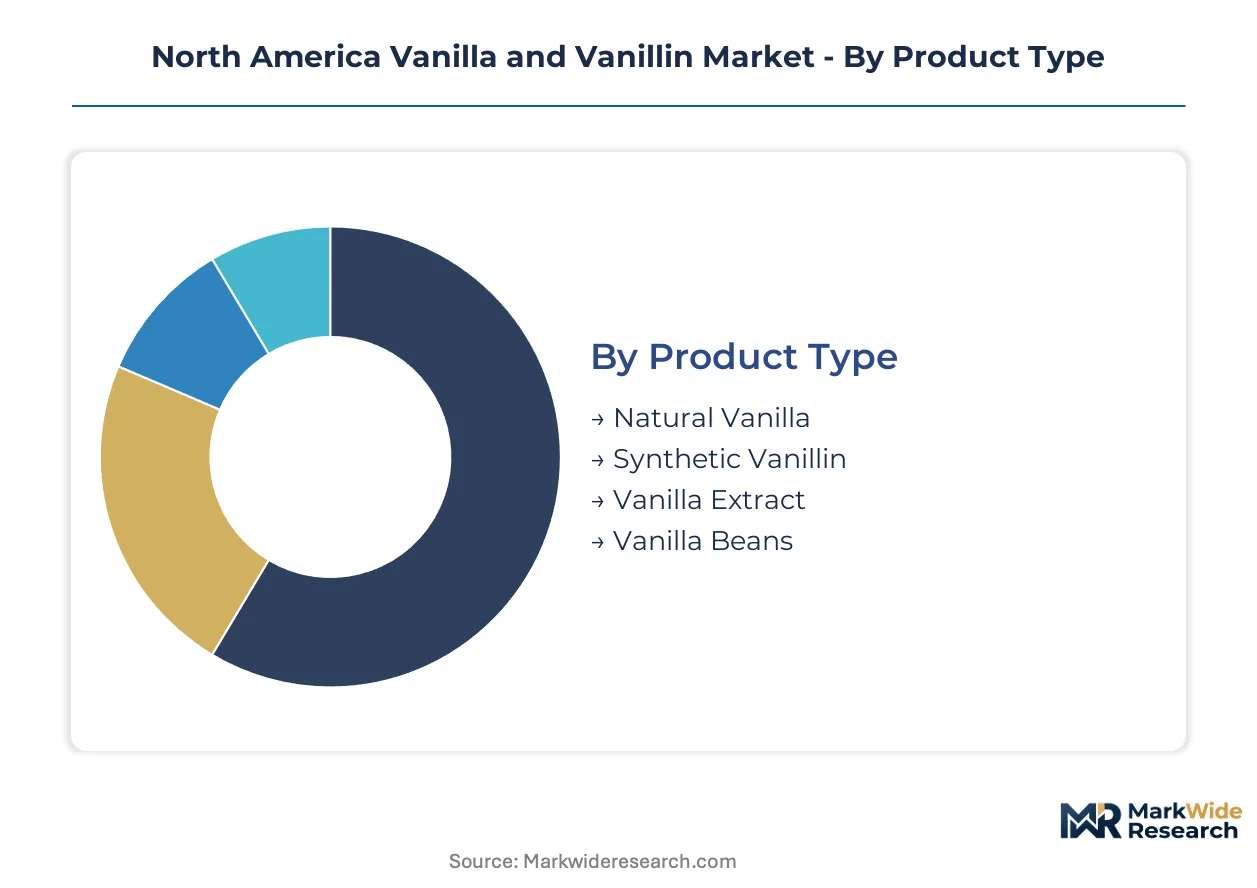
Vanilla and vanillin procurement patterns diverge sharply across product grades and end-use specifications, with FDA labeling requirements and USP purity standards creating distinct commercial corridors that reshape buyer behavior and supplier positioning across North America.
Product Type:
Cost tier determines procurement volume and margin capture, with natural-positioned extracts commanding premium positioning against synthetic alternatives that anchor high-volume food manufacturing.
- Natural Vanilla:Cured Vanilla planifolia orchid pods and their solvent-extracted derivatives containing hundreds of aromatic compounds beyond vanillin. Premium ice cream manufacturers across the United States specify this grade for clean-label declarations, though Madagascar supply concentration exposes buyers to harvest volatility and price spikes.
- Synthetic Vanillin:Petrochemical-derived or lignin-based 4-hydroxy-3-methoxybenzaldehyde produced through guaiacol oxidation or wood pulp processing. Processed baked goods and confectionery applications in the United States absorb the majority of volume, with EPA environmental compliance standards adding cost pressure to manufacturing facilities.
- Vanilla Extract:Alcohol-based extraction meeting FDA standard of identity requirements for vanilla content and solvent residue limits. Craft beverage producers in the United States specify this grade for flavor intensity control in small-batch production.
- Vanilla Beans:Whole cured pods sold primarily to gourmet retail and foodservice channels requiring visual ingredient presentation. Specialty stores and direct-trade relationships with Canadian importers sustain this niche segment.
Volume sits with synthetic vanillin; growth tilts toward natural vanilla as clean-label reformulation accelerates.
Application:
Functional performance requirements separate food-grade thermal stability from pharmaceutical purity thresholds, with each application corridor imposing distinct specification regimes on suppliers.
- Food & Beverages:Thermal stability during baking and pasteurization processes governs vanillin selection, with dairy and bakery matrices representing the dominant consumption categories across the United States and Canada.
- Cosmetics:Synthetic vanillin serves as a fragrance fixative and masking agent in personal care formulations where aromatic persistence matters more than natural positioning.
- Pharmaceuticals:USP-grade vanillin for tablet coatings and oral solid dosage form masking agents imposes stricter purity thresholds than food-grade specifications, creating concentrated margin pools for qualified suppliers.
- Fragrance:Fine perfumery applications in the United States blend vanillin with complementary aromatic compounds, with thermal stability properties enabling formulation persistence.
Food and beverages anchor current volume; pharmaceuticals deliver the steepest margin expansion trajectory.
End User:
Scale and formulation sophistication determine whether buyers procure commodity extracts or demand integrated flavor-system partnerships from suppliers.
- Food Manufacturers:Large-scale bakery and dairy processors across the United States are consolidating vendor bases and demanding pre-blended vanilla-vanillin solutions rather than separate procurement of extracts and synthetic alternatives.
- Beverage Producers:Craft distillers and premium juice blenders in the United States specify natural vanilla extract for clean-label positioning, with flavor intensity requirements varying by alcohol content and thermal processing.
- Personal Care Brands:Cosmetic formulators prioritize synthetic vanillin cost efficiency and supply security over natural provenance narratives.
- Pharmaceutical Companies:Oral solid dosage form manufacturers represent a concentrated buyer segment with stringent USP-grade requirements and long qualification timelines for new suppliers.
Food manufacturers dominate procurement volume; pharmaceutical companies offer the most defensible margin structure.
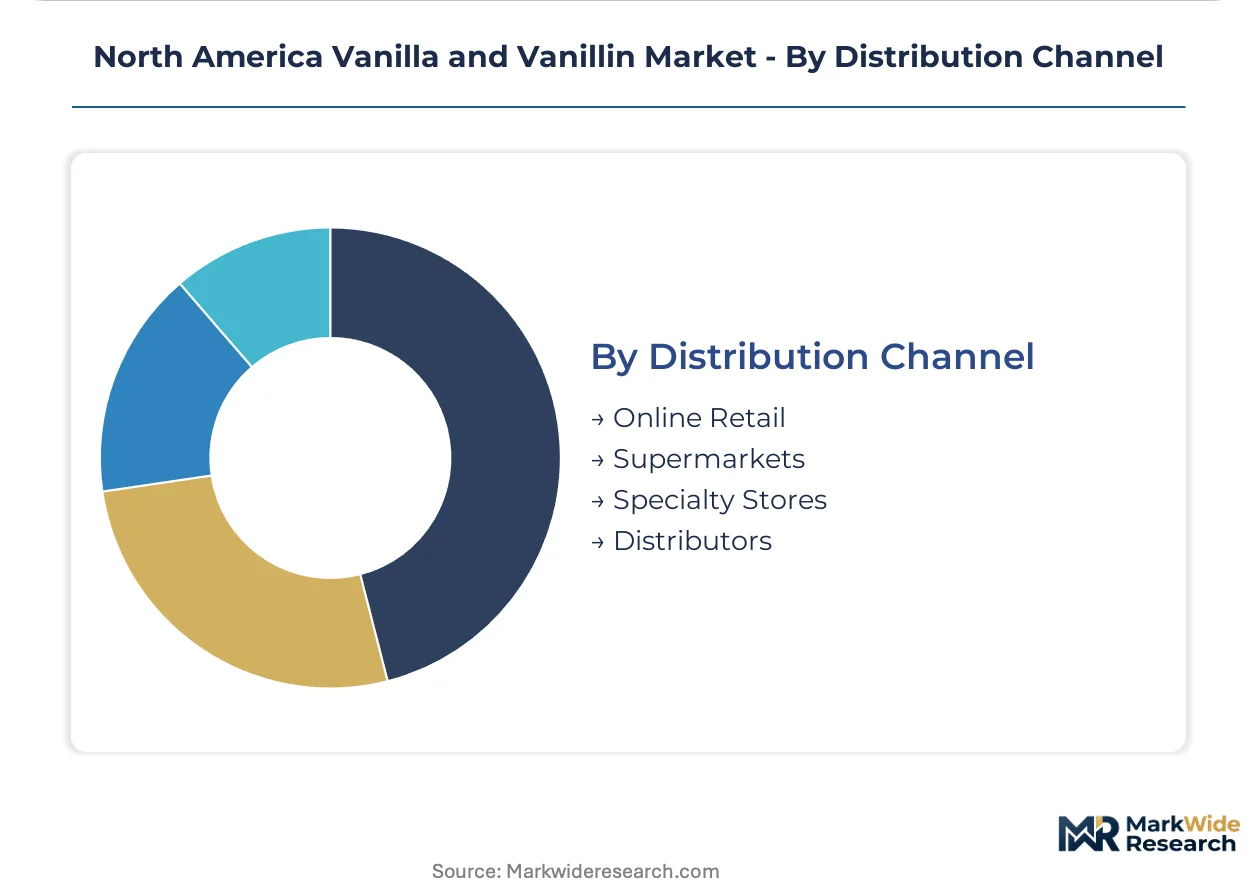
Distribution Channel:
Customer scale and purchase frequency shape channel selection, with integrated flavor houses bypassing traditional distribution for direct supply contracts.
- Online Retail:E-commerce platforms serve small-scale food manufacturers and artisan producers seeking flexible order quantities and rapid delivery across the United States and Canada.
- Supermarkets:Mass-market retail channels move consumer-packaged vanilla extracts and vanilla sugar products, with McCormick and comparable brands controlling shelf placement.
- Specialty Stores:Gourmet food retailers and culinary supply shops cater to foodservice and home baking enthusiasts demanding whole vanilla beans and premium extracts.
- Distributors:Ingredient distributors remain critical for mid-tier food manufacturers lacking direct relationships with integrated flavor houses or vanilla processors.
Distributors and supermarkets handle current volume; online retail is gaining share fastest among emerging craft producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vanilla bean cultivation concentrates in Madagascar, while North American processors and end-users drive value capture through extraction, formulation, and branded distribution. The United States dominates consumption volume, with Canada and Mexico serving distinct procurement roles in the regional supply architecture.
United States
Premium ice cream manufacturers and craft beverage producers in the United States specify natural vanilla extract for clean-label positioning. FDA labeling requirements for natural versus artificial flavor declarations tighten formulation transparency standards. Chicago and New Jersey host major flavor house operations where Givaudan and International Flavors & Fragrances anchor integrated supply contracts with CPG brands.
Canada
Canadian importers develop direct-trade relationships with USDA-certified organic cooperatives to serve clean-label food manufacturers. Health Canada and the Canadian Food Inspection Agency enforce flavor labeling standards aligned with FDA frameworks. Toronto and Montreal concentrate procurement and distribution infrastructure for vanilla beans destined to North American specialty food channels.
Mexico
Mexico's domestic vanilla cultivation in Veracruz supplies regional extractors with Planifolia varieties for foodservice and industrial applications. COFEPRIS regulates flavor additive safety and labeling compliance for products entering the Mexican market. Mexico City anchors processing capacity for vanilla extracts distributed throughout Latin American markets.
North America Vanilla and Vanillin Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the North America vanilla and vanillin market. The vendor base spans integrated flavor houses, commodity chemical producers, and retail-branded extract suppliers. Three strategic archetypes dominate: biotechnology-focused innovators defending fermentation-derived positioning, extraction-dependent suppliers emphasizing provenance narratives, and retail-channel controllers leveraging consumer brand equity. Competitive moves concentrate on supply contract consolidation with large-scale food manufacturers and R&D investment in biotechnological production routes.
Among Switzerland-based integrated flavor houses, Givaudan and dsm-firmenich occupy positions emphasizing modular flavor-system bundling for North American CPG contracts. McCormick represents the retail-channel archetype with consumer-facing brand equity in pure vanilla extract segments. International Flavors & Fragrances anchors the biotechnology vector, exemplifying R&D intensity in fermentation-derived vanillin production.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances |
| Advanced Biotech |
| Solvay |
| Borregaard AS |
| Prinova Group LLC |
| Symrise AG |
| McCormick |
| dsm-firmenich |
| Others |
Cost & Logistics Intelligence
Natural-versus-synthetic grade bifurcation creates divergent pricing corridors that reshape procurement economics and sourcing geography across North American vanilla and vanillin procurement. FDA labeling distinctions between natural flavor and artificial flavor declarations force food manufacturers to choose between premium Madagascar-sourced extracts and cost-efficient petrochemical-derived alternatives, with each tier tethered to distinct supply chain architectures and margin structures.
Pricing Analysis
Cost-down pressure on synthetic vanillin accelerates because EPA environmental compliance standards for guaiacol-based manufacturing impose wastewater treatment and emissions control burdens. Three-tier pricing structure across premium natural extract, standard biotechnology-derived, and economy petrochemical-synthetic levels separates buyers by certification requirements and clean-label positioning. Price differentiation traces to Madagascar harvest volatility for natural grades versus lignin feedstock availability for synthetic alternatives. Mid-tier food manufacturers exhibit highest price sensitivity, while pharmaceutical companies absorbing USP-grade vanillin tolerate premium positioning for purity assurance.
Supply Chain Analysis
Ocean freight costs from Antwerp and Mombasa to North American ports constitute a material component of landed vanilla extract pricing, with container rate volatility amplifying Madagascar supply concentration risks. Raw material flows draw from Malagasy orchid cultivation, Norwegian wood pulp lignin processing, and emerging Brazilian fermentation facilities. Single-source vulnerability concentrates in Madagascar, where cyclone exposure threatens 80 percent of global bean supply. Distribution runs through integrated flavor houses contracting directly with CPG brands, bypassing traditional ingredient distributors for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are displacing century-old extraction economics, forcing stakeholders to recalibrate positioning around biotechnology-derived vanillin as the ascendant production paradigm.
For Market Incumbents: Deploy backward integration into fermentation capacity to defend margin position against biotechnology entrants. Givaudan and International Flavors & Fragrances should accelerate bioreactor infrastructure investment while maintaining extraction relationships for provenance-dependent premium segments. Certification investment in USDA organic and USP-grade qualifications creates switching costs against synthetic-only competitors. For New Entrants and Emerging Players: FDA labeling framework evolution in the United States opens a window for biotechnology-derived vanillin positioned between natural extract and synthetic alternatives. Target contract manufacturing for mid-tier bakery processors seeking cost reduction without artificial flavor declarations. Direct-to-flavor-house partnerships bypass distributor markups and accelerate qualification timelines. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-platform specialists given regulatory tailwinds for biotech-derived ingredients. Long-term viability favors assets with dual capability across natural extraction and microbial biosynthesis. Watch FDA natural flavor reclassification commentary as the decisive inflection signal for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biotechnology-derived vanillin production compresses cost differentials against Madagascar extraction. |
| Direct-Trade Sourcing Partnerships | Canadian importers developing USDA-certified organic relationships capture premium positioning. |
| Modular Flavor-System Integration | Pre-blended vanilla-vanillin solutions consolidate vendor relationships for large-scale CPG contracts. |
| USP-Grade Certification Investment | Pharmaceutical tablet coating specifications create defensible margin pools for qualified suppliers. |
| Regulatory Engagement Capacity | Early participation in FDA natural flavor definition proceedings shapes competitive categorization outcomes. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North America vanilla and vanillin market assessment. Primary interviews with flavor house procurement directors, CPG formulation scientists, pharmaceutical excipient specialists, and vanilla bean importers validated demand assumptions and price trajectory expectations. Secondary sources incorporated FDA flavor additive petitions, EPA facility compliance disclosures, USDA organic certification databases, and United Nations Comtrade vanilla bean import statistics. Bottom-up segment sizing triangulated against top-down market value estimates from trade publications.
Reconciliation of production volume data, import-export flows, and end-use consumption patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, application matrix, end-user scale category, and distribution channel structure. CAGRs derived from curve-fitting historical price and volume trajectories against elasticity assumptions for natural-versus-synthetic substitution. Industry-specific forecast inputs incorporated Madagascar harvest yield volatility and biotechnology facility commissioning timelines.
The model assumes a particular technology adoption path for precision fermentation; alternative pathways for biotech-derived vanillin would alter the outlook if FDA reclassification accelerates or lignin feedstock economics shift. Forecasts reflect documented assumptions about regulatory stability and Madagascar supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Valencene Market
Flavorings and Food Additives
Ylang Ylang Extract Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
China Food Colorants Market
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Global Paprika Oleoresin Market
Flavorings and Food Additives
Egypt Food Colorants Market