
 Lemon Oil Market | 2026-2036
Lemon Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Lemon Oil Market Intelligence
Aftermarket service revenue from technical-grade reformulation and custom blending is narrowing as manufacturers integrate downstream into finished aromatherapy and cosmetic products. Symrise AG leverages captive citrus sourcing across Mediterranean cooperatives to secure raw material consistency. Lionel Hitchen (Essential Oils) Ltd anchors its position through pharmaceutical-grade certification and U.K. pharmaceutical channel relationships. Bontoux S.A.S. competes on cold-pressed extraction scale from its Grasse facility, supplying flavor houses and fragrance compounders.
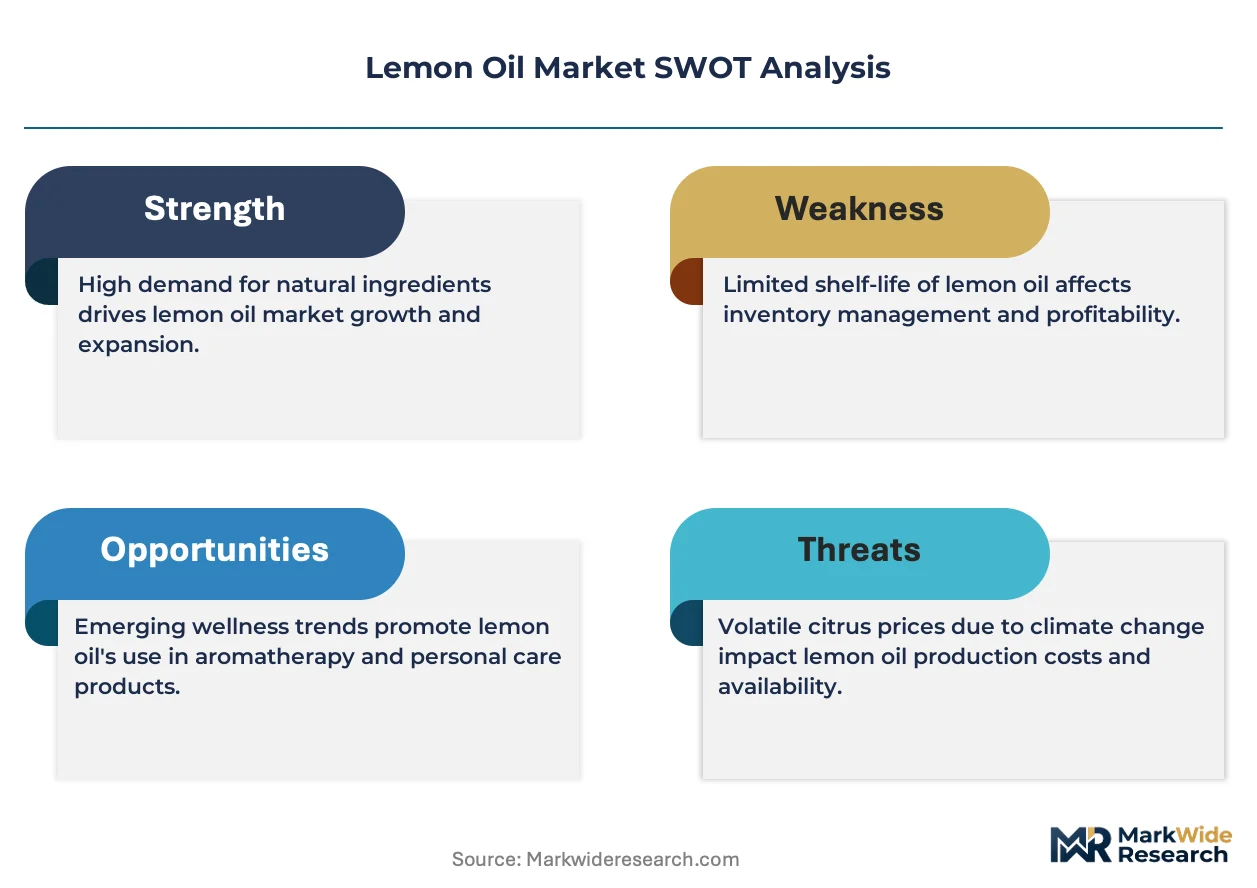
Lemon oil is a volatile essential oil obtained by cold-pressing or steam-distilling the peel of Citrus limon, containing approximately 90% limonene along with citral, gamma-terpinene, and beta-pinene in trace concentrations; its primary commercial purpose is to provide natural flavoring, fragrance, and antimicrobial functionality across food, cosmetic, and cleaning applications. The food grade segment dominates volume throughput as beverage manufacturers replace synthetic citrus flavors with natural extracts to meet clean-label requirements. Cosmetic grade commands premium positioning through cold-pressed Italian and Spanish origins, while pharmaceutical grade supply tightens due to monograph compliance costs and therapeutic claim substantiation demands.
EU REACH registration and the F-Gas Regulation constrain solvent-based extraction methods and synthetic adulteration detection protocols, while U.S. FDA food additive regulations and EPA pesticide residue limits govern import acceptance for cold-pressed oils. ISO 4728 and AFNOR standards for citrus essential oil composition create technical barriers for non-EU suppliers seeking cosmetic and pharmaceutical grade access. Stakeholders must monitor regulatory divergence between EU natural claim definitions and U.S. GRAS self-affirmation pathways, as compliance strategy choices will determine which grade segments remain profitable across Atlantic supply corridors.
Market Dynamics
Cold-pressed extraction capacity concentrates in Mediterranean coastal zones where Femminello and Monachello cultivar availability intersects with EU REACH compliance infrastructure, creating supply-side rigidity against surging beverage and cosmetic demand.
Growth Catalysts
- EU REACH natural claim enforcement:Tightened adulteration detection protocols force synthetic citrus flavor substitution, expanding cold-pressed oil offtake from beverage compounders seeking clean-label compliance.
- Pharmaceutical-grade therapeutic substantiation:Monograph-compliant limonene isolates gain traction in antimicrobial formulations as drug manufacturers validate natural preservative efficacy against synthetic alternatives.
- Calabria-Sicily cluster consolidation:Cooperative processing infrastructure upgrades reduce batch-to-batch terpene profile variance, securing long-term supply agreements with fragrance houses.
Market Restraints
- Limonene price volatility:Citrus greening disease pressure in Florida and Brazil elevates raw peel input costs unpredictably for non-captive processors.
- Extraction method regulatory friction:EU F-Gas Regulation constrains solvent-based recovery techniques, forcing capital-intensive cold-press retrofitting among mid-scale Italian suppliers.
- Synthetic terpene substitution:Biotechnology-derived limonene from sugar fermentation offers cost-competitive parity for industrial cleaning applications with lower purity requirements.
Strategic Opportunities
- Indian ayurvedic pharmaceutical channel:CDSCO registration pathways for essential oil therapeutics remain underpenetrated relative to domestic production scale.
- Carbon dioxide extraction convergence:Supercritical CO2 systems paired with molecular distillation enable pesticide-free pharmaceutical grades without thermal degradation.
- Direct-to-compounder e-procurement platforms:Digital spot markets for certified organic lots bypass traditional Grasse-based broker intermediaries.
Industry Challenges
- Gas chromatography-mass spectrometry analyst scarcity:AFNOR and ISO 4728 compliance verification requires specialized phytochemical identification expertise concentrated in aging Southern European laboratories.
- Multi-jurisdiction certification sequencing:Simultaneous U.S. FDA GRAS self-affirmation, EU REACH registration, and pharmaceutical monograph alignment extends product launch timelines substantially.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lemon Oil Market |
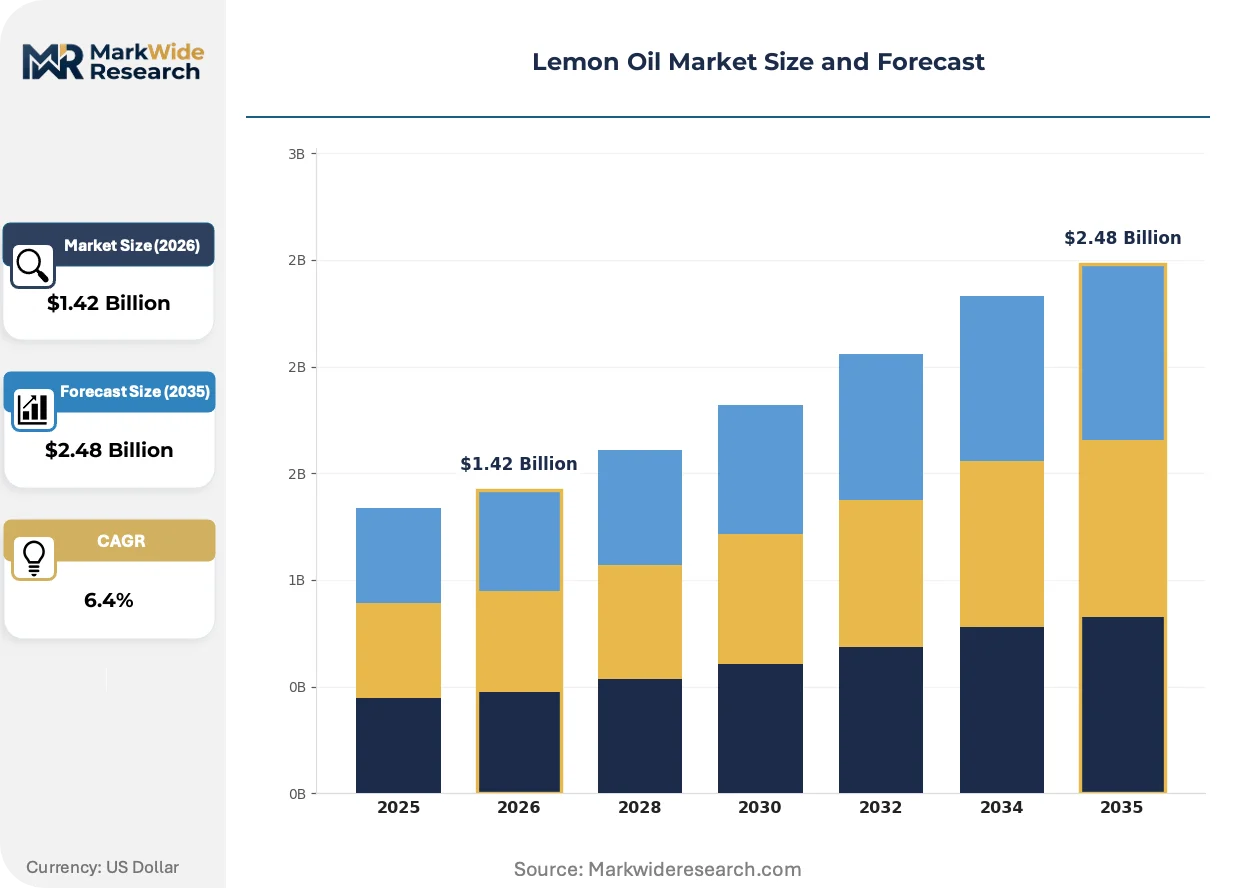
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Cosmetics, Food Flavoring, Aromatherapy, Household Cleaners Form: Liquid, Concentrate, Diluted, Essential Oil Distribution Channel: Online, Offline, Retail Stores, Wholesale Grade: Food Grade, Cosmetic Grade, Pharmaceutical Grade, Technical Grade |
| Companies Covered | Symrise AG, Lionel Hitchen (Essential Oils) Ltd, Bontoux S.A.S., Citrus and Allied Essences Ltd., Young Living Essential Oils, doTERRA International, Mountain Rose Herbs, Edens Garden, Plant Therapy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lemon Oil Market Strategic Shifts & Innovations
Extraction technology and regulatory detection capabilities are advancing in parallel, compressing the viable supply base toward integrated processors while fragmenting demand across certification tiers.
Supercritical carbon dioxide extraction systems are migrating from pilot-scale pharmaceutical applications to mid-volume cosmetic-grade production. Italian processors near Reggio Calabria deploy these units to eliminate heat-induced citral degradation while satisfying EU pesticide residue thresholds. The technology is migrating from niche therapeutic isolates toward mainstream fragrance compound supply, enabling smaller batch runs with documented terpene chain-of-custody.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon solvents are tightening allowable emissions from traditional cold-press auxiliary operations. Distillers in Sicily's Paternò district face equipment replacement deadlines by 2027, redirecting capital toward closed-loop mechanical pressing infrastructure. Cosmetic-grade suppliers with early compliance certification capture preferential sourcing agreements from Paris-based fragrance houses.
Compounders are consolidating supplier relationships around vertically integrated Mediterranean cooperatives offering bundled organic certification and carbon footprint documentation. Spot market purchasing through traditional broker networks contracts as beverage manufacturers mandate lot-specific chromatographic fingerprinting. This concentration is most pronounced among German and Dutch natural flavor houses serving private-label retail chains.
Lemon Oil Market Segmentation
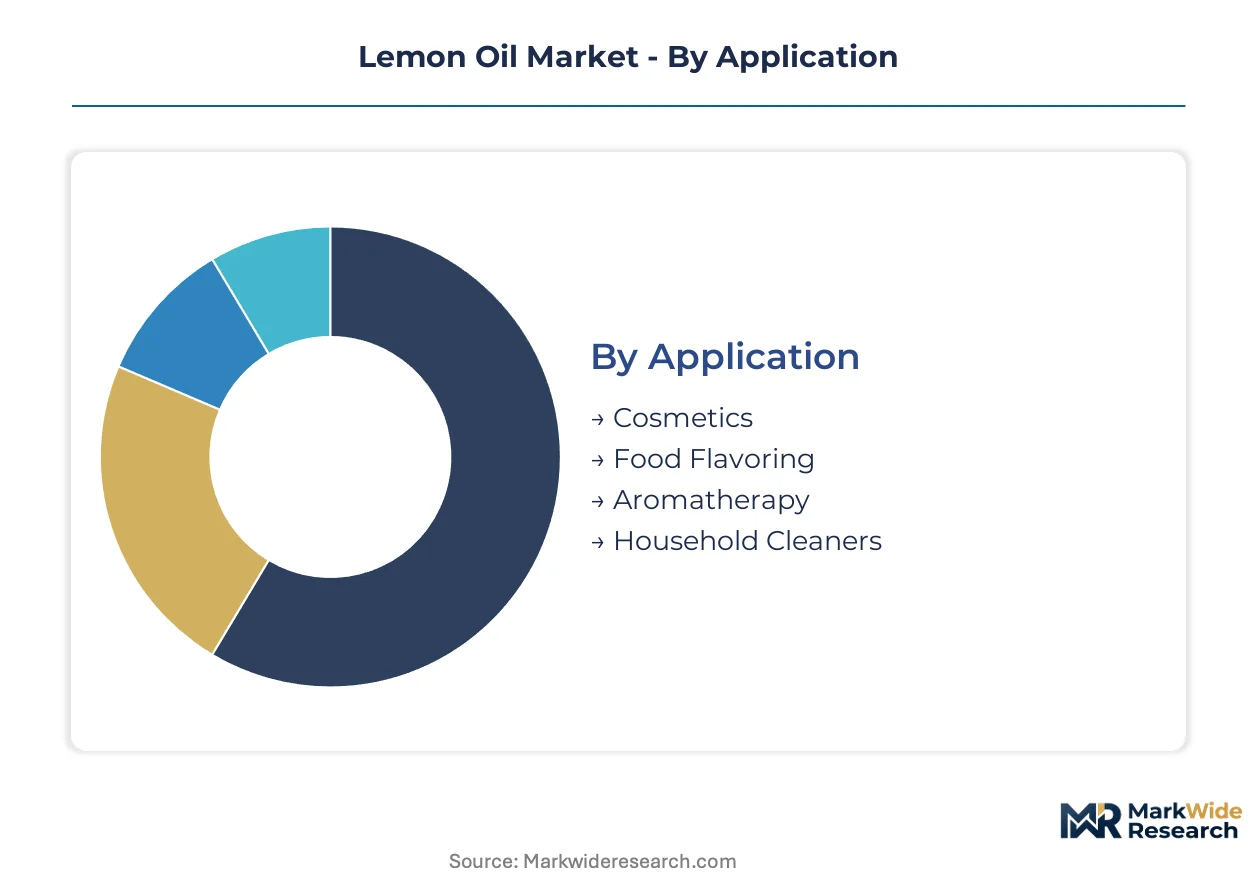
Segmentation in lemon oil markets reflects divergent certification requirements and supply chain configurations across end-use verticals. Pharmaceutical-grade extraction demands AFNOR-compliant terpene profiling, while food-grade volumes flow through beverage compounders with clean-label procurement mandates.
Application:
Cycle times vary sharply across application segments, with household cleaners turning inventory fastest and pharmaceutical formulations locking supply into multi-year monograph validation timelines.
- Food Flavoring:Cold-pressed oils with standardized citral content (4-8%) supply beverage manufacturers replacing synthetic citrus flavors. German and Dutch natural flavor houses now mandate lot-specific chromatographic fingerprinting from Italian cooperatives.
- Cosmetics:Premium cold-pressed grades from Calabria and Sicily command position through terpene consistency and carbon footprint documentation. Paris-based fragrance houses consolidate sourcing around vertically integrated Mediterranean suppliers with bundled organic certification.
- Aromatherapy:Therapeutic-grade oils require ISO 4728 compliance for inhalation safety.
- Household Cleaners:Technical-grade limonene isolates serve industrial formulations with lower purity thresholds.
Food Flavoring dominates installed base. Cosmetics is where expansion concentrates.
Form:
Cost tiers separate form segments, with concentrates and essential oils occupying premium positions against diluted commodity grades.
- Essential Oil:Pure cold-pressed extracts containing 90%+ limonene serve pharmaceutical and high-end cosmetic applications. Supercritical CO2 extraction systems near Reggio Calabria eliminate heat-induced citral degradation while satisfying EU pesticide residue thresholds.
- Concentrate:Standardized terpene blends enable precise formulation control for fragrance compounders. Sicilian processors in Paternò district face 2027 equipment replacement deadlines under EU F-Gas Regulation, redirecting capital toward closed-loop mechanical pressing.
- Liquid:Bulk solvent-extracted oils flow through industrial cleaning supply chains.
- Diluted:Pre-blended solutions reduce handling costs for mid-scale aromatherapy retailers.
Essential Oil captures premium pricing. Concentrate is climbing the fastest as fragrance houses seek formulation precision.
Distribution Channel:
Customer type splits channel performance, with wholesale relationships anchoring volume and digital platforms fragmenting procurement for certified organic lots.
- Wholesale:Long-term supply agreements connect Mediterranean cooperatives directly to beverage and fragrance compounders. Spot market purchasing through traditional Grasse-based broker networks contracts as manufacturers mandate documented terpene chain-of-custody.
- Online:Direct-to-compounder e-procurement platforms bypass intermediary markups for certified organic lots. German private-label retail chains drive adoption of digital spot markets with lot-specific quality verification.
- Offline:Broker-mediated transactions persist for non-certified commodity grades.
- Retail Stores:Small-volume aromatherapy and cosmetic sales serve consumer end-markets.
Wholesale dominates installed base. Online is where expansion concentrates.
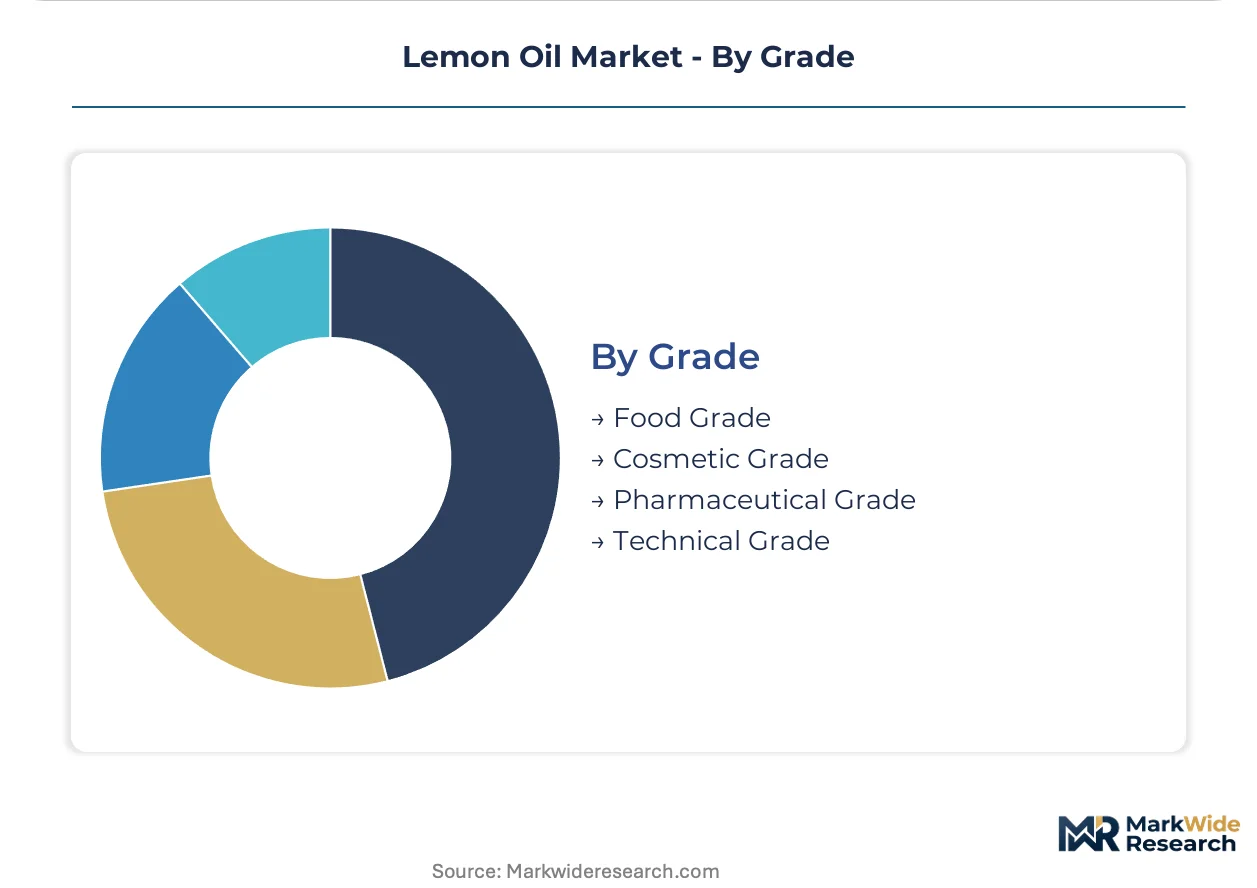
Grade:
Margin structures stratify sharply across grade tiers, with pharmaceutical certification costs creating entry barriers that protect premium positioning.
- Cosmetic Grade:Cold-pressed Italian and Spanish origins with AFNOR-compliant terpene profiles supply fragrance houses and skincare formulators. Early EU F-Gas Regulation compliance among Sicilian distillers captures preferential sourcing agreements.
- Pharmaceutical Grade:Monograph-compliant limonene isolates require therapeutic claim substantiation and specialized phytochemical identification expertise concentrated in aging Southern European laboratories. CDSCO registration pathways in India remain underpenetrated relative to domestic production scale.
- Food Grade:Volume throughput leader serving clean-label beverage substitution trends.
- Technical Grade:Industrial cleaning applications face biotechnology-derived limonene competition from sugar fermentation.
Food Grade dominates installed base. Pharmaceutical Grade is gaining share fastest through antimicrobial formulation validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: beverage compounders in Germany and the Netherlands drive food-grade volume through clean-label procurement mandates, while French and Italian fragrance houses anchor cosmetic-grade premiums through terpene consistency requirements.
Italy
Calabria and Sicily host the densest cold-pressed extraction infrastructure, with Femminello and Monachello cultivar processing concentrated around Reggio Calabria and Paternò. EU REACH registration requirements and F-Gas Regulation compliance deadlines through 2027 are forcing capital redirection toward closed-loop mechanical pressing. Cooperative processing upgrades in these coastal zones reduce batch-to-batch variance, securing multi-year supply agreements with Paris-based fragrance compounders.
Germany
Natural flavor houses in Hamburg and Munich mandate lot-specific chromatographic fingerprinting from Mediterranean suppliers, driving consolidation around vertically integrated cooperatives. The country's national food safety regulator enforces strict additive labeling under EU framework regulations. German private-label retail chains are accelerating adoption of digital spot markets for certified organic lots with documented terpene chain-of-custody.
France
Grasse-based fragrance houses concentrate cosmetic-grade sourcing through early F-Gas Regulation compliance certification, capturing preferential agreements from Sicilian distillers. ANSM pharmaceutical oversight and AFNOR standard enforcement create technical barriers for non-EU suppliers seeking cosmetic and pharmaceutical grade access. The Provence-Alpes-Côte d'Azur cluster maintains broker intermediation for non-certified commodity grades even as wholesale direct procurement expands.
United States
Beverage manufacturers in Florida and California replace synthetic citrus flavors with natural extracts to meet FDA GRAS self-affirmation pathways and EPA pesticide residue limits for cold-pressed oil imports. Citrus greening disease pressure in Florida elevates raw peel input cost unpredictability for non-captive processors. Clean-label procurement from Italian and Spanish origins is displacing domestic sourcing for premium applications.
India
Domestic ayurvedic pharmaceutical production scales rapidly, yet CDSCO registration pathways for essential oil therapeutics remain underpenetrated relative to output capacity. FSSAI food safety standards govern import acceptance for flavoring applications. Maharashtra and Gujarat processing clusters are investing in supercritical CO2 extraction systems to capture pharmaceutical-grade margins from antimicrobial formulation demand.
Lemon Oil Market Key Industry Players
Capability concentration sits with integrated Mediterranean cooperatives commanding bundled organic certification and carbon footprint documentation; scale advantage sits with fragrance compounders and beverage manufacturers consolidating supplier relationships around documented terpene chain-of-custody. The market structures into three tiers: vertically integrated processors with captive citrus sourcing, specialized distillers with pharmaceutical-grade certification, and regional brokers facing displacement from digital procurement platforms. Dominant competitive moves include backward integration into finished aromatherapy and cosmetic products, and technology licensing for supercritical CO2 extraction systems.
Within the integrated processor tier, Symrise AG and Bontoux S.A.S. exemplify archetypes of Mediterranean-sourced supply security and Grasse-based extraction scale respectively. Lionel Hitchen (Essential Oils) Ltd occupies a position representing pharmaceutical-grade certification specialization through U.K. channel relationships. These three entities anchor the competitive spectrum from raw material control through finished product distribution, with each representing distinct strategic postures on compliance investment and customer segment focus.
| Leading Market Players |
|---|
| Symrise AG |
| Lionel Hitchen (Essential Oils) Ltd |
| Bontoux S.A.S. |
| Citrus and Allied Essences Ltd. |
| Young Living Essential Oils |
| doTERRA International |
| Mountain Rose Herbs |
| Edens Garden |
| Plant Therapy |
| Others |
Cost & Logistics Intelligence
Citrus greening disease volatility in Florida and Brazil determines both pharmaceutical-cosmetic grade price spreads and Mediterranean supply chain consolidation patterns. Buyers face escalating input cost unpredictability that compresses margins for non-captive processors while rewarding integrated Italian cooperatives with backward citrus sourcing.
Pricing Analysis
Long-term offtake contracts dominate premium grade procurement as Paris fragrance houses and German beverage compounders lock multi-year supply from Calabria-Sicily clusters. Price differentiation rests on AFNOR certification tier and organic documentation bundling, with pharmaceutical grade commanding substantial premiums over technical grades. Cost compression in industrial cleaning applications is intensifying because biotechnology-derived limonene from sugar fermentation achieves cost parity. Household cleaner manufacturers exhibit highest price sensitivity; cosmetic formulators show least sensitivity due to terpene consistency requirements.
Supply Chain Analysis
Contract manufacturing concentration sits with Sicilian cooperatives in Paternò and Reggio Calabria processors holding cold-pressed capacity. Geographic supply concentrates in Italy, Spain, and Argentina for premium cultivar availability. Raw material dependencies center on Femminello and Monachello peel supply, EU REACH-compliant extraction solvents, and pharmaceutical-grade packaging materials. Single-source vulnerability runs through Mediterranean coastal zones exposed to climate-driven harvest variability. Distribution runs through Grasse-based broker networks contracting as direct wholesale procurement expands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage manufacturer consolidation around clean-label mandates has shifted procurement leverage toward compounders capable of lot-specific chromatographic verification. This buyer-power concentration rewards suppliers with integrated certification and documented terpene chain-of-custody.
For Market Incumbents: Harden supply security through captive citrus sourcing across Mediterranean cooperative networks and accelerate closed-loop mechanical pressing retrofitting ahead of EU F-Gas Regulation deadlines. Biotechnology-derived terpene substitution threatens industrial grade margins; pharmaceutical-grade certification investment protects premium positioning against synthetic alternatives. For New Entrants and Emerging Players: Build out supercritical CO2 extraction capacity in Maharashtra and Gujarat to capture underpenetrated CDSCO registration pathways for ayurvedic pharmaceutical channels. Target Indian antimicrobial formulation demand through pesticide-free molecular distillation capabilities. Digital spot market platforms for certified organic lots offer direct-to-compounder go-to-market positioning bypassing traditional Grasse intermediaries. For Investors and Strategic Acquirers: The market sits at a compliance-investment phase that favors vertically integrated processors with bundled organic certification and carbon footprint documentation. Five-to-ten year viability hinges on regulatory divergence navigation between EU natural claim definitions and U.S. GRAS pathways. Watch for gas chromatography-mass spectrometry analyst scarcity in Southern European laboratories as inflection signal for quality verification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Citrus Sourcing | Secures raw material consistency against citrus greening disease pressure in Florida and Brazil. |
| Supercritical CO2 Extraction Scale-Up | Enables pesticide-free pharmaceutical grades without heat-induced citral degradation near Reggio Calabria. |
| EU F-Gas Regulation Compliance Certification | Captures preferential sourcing agreements from Paris-based fragrance houses ahead of 2027 deadlines. |
| CDSCO Registration Pathway Investment | Opens underpenetrated ayurvedic pharmaceutical channels in Maharashtra and Gujarat processing clusters. |
| Direct-to-Compounder E-Procurement Platform | Bypasses Grasse-based broker intermediaries for certified organic lots with lot-specific verification. |
Research Approach
Initial hypotheses were tested against primary input from extraction plant managers, fragrance house procurement leads, beverage compounder technical directors, and pharmaceutical formulation scientists and refined through secondary validation. Primary interviews combined with customs trade data, ECHA REACH registration databases, AFNOR standard documentation, and SEC filings from listed flavor houses. Bottom-up volume triangulation across grade tiers and top-down value validation against end-use verticals anchored forecast robustness.
Demand-supply balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled encompassed application vertical, grade certification tier, extraction method, and regional regulatory cluster. CAGRs derived from installed base growth rates adjusted for substitution dynamics and compliance cost trajectories. Forecast inputs incorporated citrus greening disease incidence patterns, EU F-Gas Regulation phase-down schedules, and biotechnology-derived terpene cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by fragrance compounders would shift outcomes substantially. Quarterly review of chromatographic analyst labor availability in Southern Europe, CDSCO registration approval velocities, and spot market digital platform adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Marshmallow Root Extract Market