
 Japan Food Colorants Market | 2026-2036
Japan Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Food Colorants Market Foresight
JIS S 0050 certification for food additive purity is reorganizing supplier eligibility across Japan's colorant value chain. San-Ei Gen F.F.I., Inc. leverages captive fermentation capacity for natural anthocyanin production in Osaka prefecture. Nagase & Co., Ltd. sustains distribution dominance through its century-old trading house network covering domestic food manufacturers. Yamaguchi-Gosei Kagaku Co., Ltd. specializes in azo-free synthetic alternatives that meet confectionery sector specifications.
Food colorants comprise chromatic additives—natural extracts, synthetic dyes, caramel compounds, and anthocyanin formulations—delivered in liquid, powder, gel, or emulsion forms to achieve visual standardization in processed foods. Natural colorants command premium positioning as Japanese food manufacturers reformulate away from tartrazine and allura red amid consumer preference shifts. Powder forms anchor industrial-scale bakery and dairy applications where dosing precision and shelf stability determine procurement decisions. Liquid emulsions lead beverage segment adoption for homogeneous dispersion in acidic soft drinks and flavored waters.
METI enforces chemical substance reporting under the Act on the Evaluation of Chemical Substances, while PMDA monitors colorant safety in functional food applications and JIS standards govern manufacturing quality benchmarks. These frameworks elevate compliance costs for imported synthetics while creating preference thresholds for domestically certified natural alternatives. Stakeholders must weigh reformulation timelines against certification backlogs as export-facing producers anticipate alignment with evolving EU REACH-equivalent standards.
Market Dynamics
Clean-label reformulation mandates from METI and PMDA are compressing synthetic colorant shelf life while accelerating natural extract qualification timelines across Japan's processed food sector.
Growth Catalysts
- Anthocyanin fermentation scale-up:Captive bioreactor capacity in Osaka prefecture is reducing natural colorant unit costs for beverage applications. Domestic supply security appeals to risk-averse procurement teams at Kirin and Suntory.
- FSSAI-aligned import screening:Harmonized additive standards between Japan and India are streamlining cross-border raw material flows. Spice and extract suppliers in Kerala now pre-certify shipments against JIS S 0050 benchmarks.
- Tokyo-Saitama processing corridor concentration:Proximity demand from Calbee, Meiji, and Morinaga facilities is creating dedicated logistics lanes for just-in-time colorant delivery. Regional clustering reduces cold-chain spoilage for heat-sensitive natural formulations.
Market Restraints
- Beetroot extract price volatility:Weather-dependent harvests in Hokkaido and Tohoku create input cost instability for betalaine-dependent confectionery producers. Inventory hedging adds working capital pressure.
- Single-source fermentation reliance:Osaka-based anthocyanin capacity concentrates supply risk in one prefecture. Earthquake exposure and utility disruption threats constrain business continuity planning.
- EU REACH-equivalent alignment lag:Pending chemical substance reclassification under METI reporting rules is freezing export qualification timelines. Cross-border shipment delays accumulate at Yokohama customs checkpoints.
Strategic Opportunities
- Kyushu functional food expansion:Underpenetrated nutraceutical manufacturing in Fukuoka and Kumamoto offers white space for colorant-cosmetic crossover applications. PMDA's functional claims framework supports premium positioning.
- Direct-to-bakery distribution platforms:Digital procurement portals are disintermediating traditional trading house networks for small-batch artisan producers. Tokyo's specialty bread segment pilots subscription-based colorant replenishment.
- Dual-carbon packaging mandates:METI's plastic reduction targets favor water-soluble film delivery systems for powder colorants. Biodegradable sachet formats command procurement preference in sustainability-scored RFPs.
Industry Challenges
- JIS S 0050 certification backlog:Third-party laboratory capacity constraints in Kanto are extending qualification timelines to 14-18 months. Reformulation windows compress against fixed product launch schedules.
- Legacy ERP integration friction:Batch traceability requirements for additive genealogy conflict with Showa-era manufacturing execution systems at mid-tier processors. Custom middleware development strains IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Food Colorants Market |
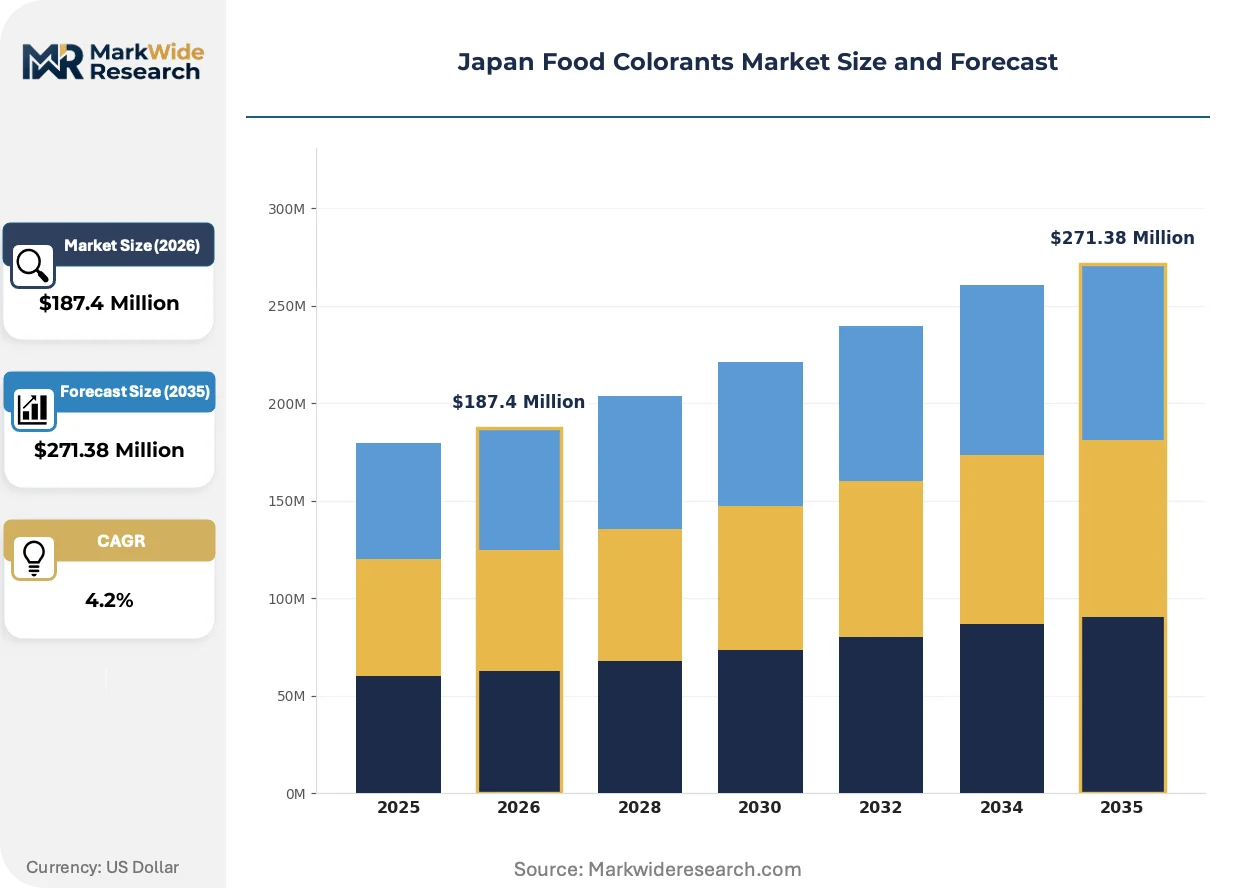
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Color Type: Natural Colorants, Synthetic Colorants, Caramel Color, Anthocyanins Application: Beverages, Bakery Products, Dairy Products, Confectionery Form: Liquid, Powder, Gel, Emulsion End User: Food Manufacturers, Beverage Producers, Snack Companies, Restaurants |
| Companies Covered | San-Ei Gen F.F.I., Inc., Nagase & Co., Ltd., Yamaguchi-Gosei Kagaku Co., Ltd., Lake Foods Co., Ltd., Kishi Kasei Co., Ltd., Hodogaya Chemical Co., Ltd., Japan Food Chemical Co., Ltd., Maruzen Chemicals Co., Ltd., Chr. Hansen Holding AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Food Colorants Market Shifts & Advancements
Microencapsulation technology is compressing dosage volumes while stabilizing natural pigments against pH drift and thermal degradation in Japan's beverage and dairy sectors.
Encapsulated curcumin and paprika oleoresin formulations is miniaturizing effective colorant loads to sub-50-micron particle sizes. Kirin Beverage and Asahi Soft Drinks are piloting these concentrates in acidic RTD tea lines. The technology is compressing freight costs and cold-storage requirements for long-haul distribution to Okinawa and Hokkaido retail networks.
METI's Act on the Evaluation of Chemical Substances is tightening annual reporting thresholds for synthetic dye imports. Industrial consequence includes mandatory substance volume disclosures that expose proprietary formulation details. Confectionery manufacturers in Saitama and Chiba are accelerating azo-free reformulations to bypass disclosure-triggering import volumes.
Buyer concentration among Japan's top-five food manufacturers is compressing supplier negotiation leverage. Trading house intermediaries like Nagase face disintermediation pressure as Meiji and Ajinomoto build direct procurement relationships with Osaka fermentation specialists. The shift is most visible in Kanto's dairy processing cluster, where spot purchasing via digital platforms now supplements annual framework contracts.
Japan Food Colorants Market Segmentation
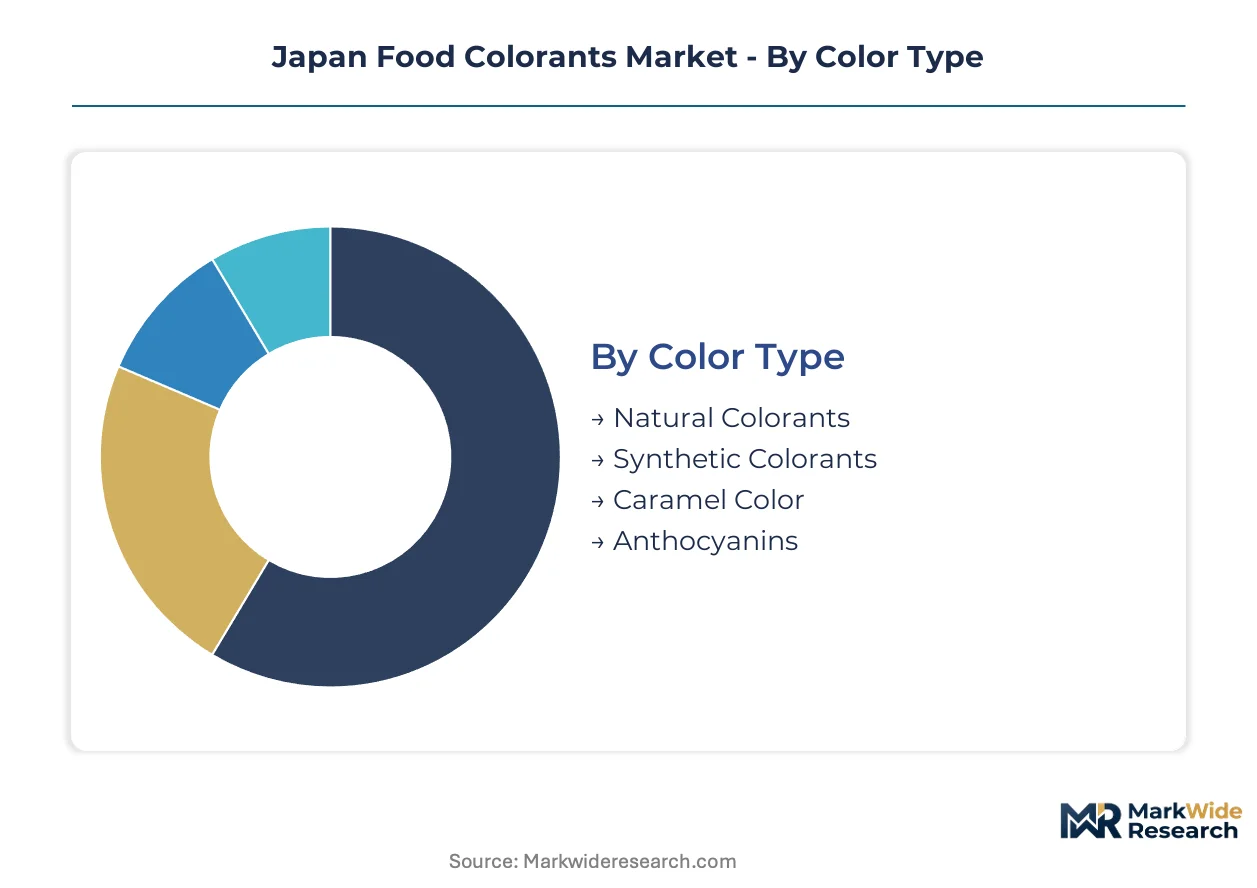
Japanese food colorant procurement patterns diverge sharply across formulation types and delivery formats. METI's chemical substance reporting thresholds and PMDA safety monitoring create distinct compliance burdens that reshape segment economics and supplier qualification priorities.
Color Type:
METI's Act on the Evaluation of Chemical Substances imposes stricter annual reporting thresholds on synthetic imports, elevating natural alternatives in procurement hierarchies.
- Natural Colorants:Plant-derived extracts from beetroot, turmeric, and spirulina face weather-dependent supply volatility from Hokkaido and Tohoku growers. Premium positioning in clean-label reformulations at Kirin and Meiji justifies unit cost premiums despite harvest inconsistency.
- Synthetic Colorants:Azo-based dyes and allura red formulations deliver batch-to-batch consistency for mass-market confectionery applications. Disclosure-triggering import volumes under METI rules are accelerating azo-free transitions among Saitama and Chiba processors seeking formulation confidentiality.
- Caramel Color:Heat-treated carbohydrate derivatives dominate cola and dark beer applications with proven acidic stability.
- Anthocyanins:Osaka-based fermentation capacity supplies pH-sensitive purple-red pigments for beverage pH buffering.
Established volume favors Synthetic Colorants; emerging adoption favors Natural Colorants.
Application:
End-use concentration in Kanto's processing corridor determines logistics economics and just-in-time delivery requirements.
- Beverages:Acidic soft drinks and flavored waters demand homogeneous dispersion formats with pH stability across 2.5-4.0 ranges. Suntory and Asahi Soft Drinks pilot microencapsulated concentrates to compress cold-chain freight to Okinawa and Hokkaido distribution networks.
- Bakery Products:Heat-stable powders enable precise dosing in industrial-scale bread and pastry manufacturing. Calbee's Tokyo-Saitama facilities anchor procurement volume with dedicated logistics lanes reducing spoilage exposure for heat-sensitive natural formulations.
- Dairy Products:Fat-compatible emulsions standardize visual presentation in yogurt and ice cream applications.
- Confectionery:Vivid hue requirements in gummy and hard candy segments sustain synthetic dye demand amid reformulation pressures.
Procurement scale concentrates in Beverages; reformulation velocity runs fastest in Confectionery.
Form:
Physical delivery format selection hinges on dosing precision requirements and cold-chain infrastructure availability.
- Liquid:Ready-to-disperse solutions integrate directly into beverage mixing tanks without hydration steps. Homogeneous dispersion properties dominate acidic RTD tea and flavored water production at Kirin Beverage.
- Powder:Shelf-stable formats with extended ambient storage tolerance anchor industrial bakery and dairy applications. Dosing precision requirements at Meiji's Kanto dairy cluster favor gravimetric powder handling systems over volumetric liquid measurement.
- Gel:Viscous semi-solids enable localized color placement in layered confectionery and decorative applications.
- Emulsion:Oil-in-water dispersions stabilize fat-soluble pigments for dairy and margarine incorporation.
Operational reliability favors Powder; dispersion efficiency favors Liquid.
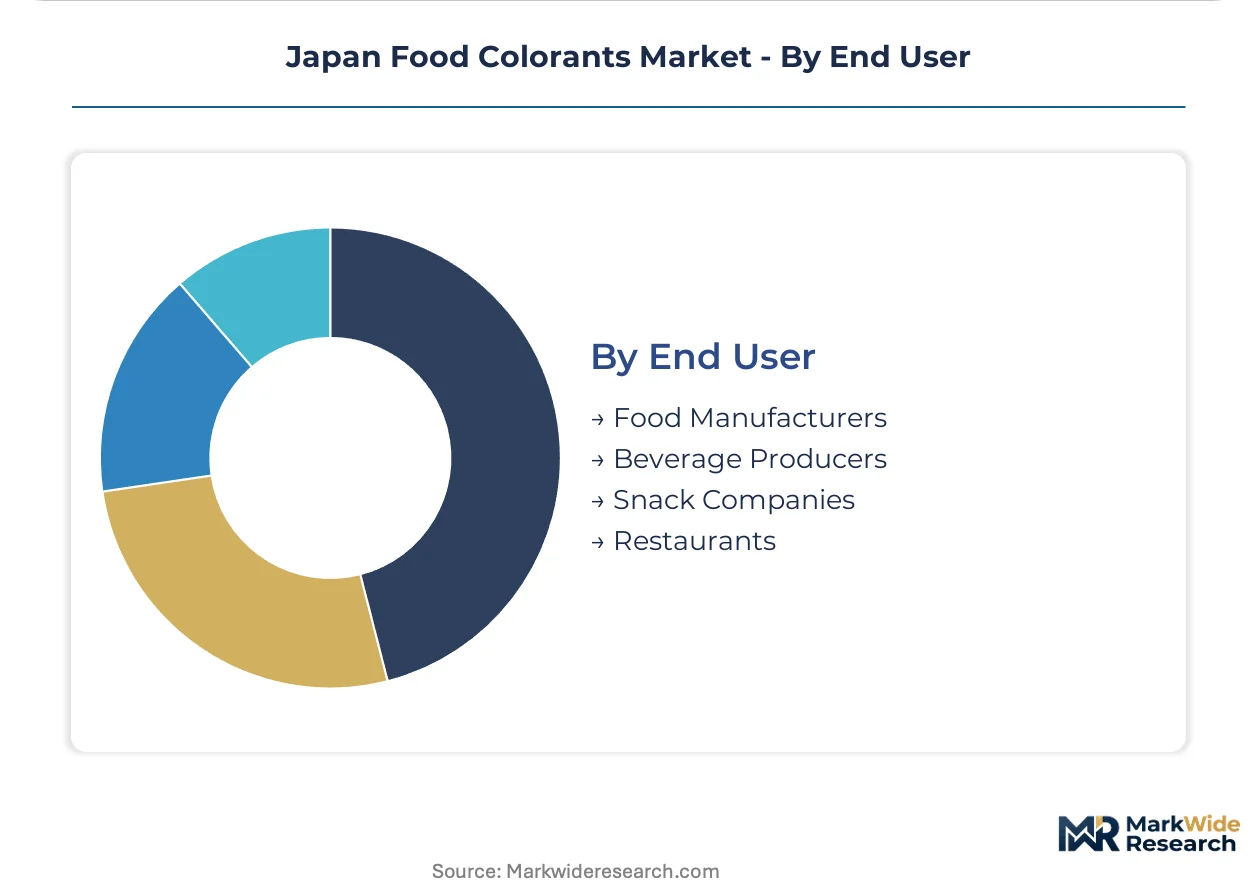
End User:
Buyer scale and technical capability determine direct procurement versus trading house intermediation patterns.
- Food Manufacturers:Integrated processors with in-house formulation laboratories negotiate direct supply relationships bypassing Nagase distribution networks. Meiji and Ajinomoto's spot purchasing via digital platforms supplements annual framework contracts in Kanto's dairy cluster.
- Beverage Producers:Concentrated buyer power among Kirin, Suntory, and Asahi compresses supplier margins while demanding captive fermentation security. Osaka anthocyanin capacity appeals to risk-averse procurement teams seeking domestic supply continuity.
- Snack Companies:Calbee and regional processors balance visual differentiation against clean-label compliance costs.
- Restaurants:Small-batch artisan bakeries in Tokyo's specialty bread segment pilot subscription-based colorant replenishment through digital procurement portals.
Contract scale concentrates with Food Manufacturers; platform disintermediation targets Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's regional industrial policy directs colorant demand toward designated manufacturing clusters, concentrating procurement in prefectures with food processing tax incentives and bonded logistics zones.
Kanto/Tokyo
Calbee's snack processing facilities and Meiji's dairy operations anchor colorant consumption in the Tokyo-Saitama corridor. METI designates this zone as a strategic food manufacturing hub with expedited chemical substance reporting. Cold-chain logistics lanes from Yokohama port reduce spoilage for heat-sensitive natural formulations destined for Okinawa distribution.
Kansai/Osaka
Captive fermentation capacity for anthocyanin production supplies beverage manufacturers across western Japan. San-Ei Gen's bioreactor operations leverage Osaka prefecture's chemical industry infrastructure. PMDA's proximity enables rapid safety consultation for functional food colorant applications in nutraceutical manufacturing.
Chubu/Nagoya
Central Japan's confectionery processors drive synthetic dye demand for vivid gummy and hard candy applications. Aichi prefecture's packaging machinery cluster supports automated colorant dosing systems. METI's manufacturing subsidy programs incentivize azo-free reformulation investments among mid-tier processors.
Kyushu
Fukuoka's underpenetrated functional food sector offers white space for colorant-cosmetic crossover applications. PMDA's regional office streamlines functional claims approval for nutraceutical innovators. Kumamoto's agricultural base supplies raw botanical materials for regional natural extract processing.
Hokkaido
Beetroot cultivation for betalaine extraction faces weather-dependent harvest volatility in northern growing regions. Prefectural agricultural cooperatives coordinate contract farming agreements with colorant processors. Cold-climate logistics constraints elevate storage costs for temperature-sensitive natural pigment shipments to Honshu manufacturing centers.
Japan Food Colorants Market Competitive Landscape
Player mix skews toward domestic chemical specialists with captive fermentation assets and century-old trading house intermediaries. Market structure concentrates supplier relationships among Osaka-based bioprocessors and Kanto distribution networks. Two strategic archetypes dominate: fermentation-integrated natural colorant producers and azo-free synthetic specialists serving reformulation mandates. Competitive moves center on direct procurement relationship-building with top-five food manufacturers and microencapsulation technology licensing for beverage applications.
Among domestic specialists, San-Ei Gen F.F.I., Inc. exemplifies the fermentation-integrated archetype with captive bioreactor operations, while Nagase & Co., Ltd. occupies the trading house intermediary position through its distribution network coverage. Yamaguchi-Gosei Kagaku Co., Ltd. represents the azo-free synthetic specialist tier addressing confectionery sector reformulation requirements. These three anchors illustrate the market's bifurcation between natural extract capacity investments and synthetic alternative development.
| Leading Market Players |
|---|
| San-Ei Gen F.F.I., Inc. |
| Nagase & Co., Ltd. |
| Yamaguchi-Gosei Kagaku Co., Ltd. |
| Lake Foods Co., Ltd. |
| Kishi Kasei Co., Ltd. |
| Hodogaya Chemical Co., Ltd. |
| Japan Food Chemical Co., Ltd. |
| Maruzen Chemicals Co., Ltd. |
| Chr. Hansen Holding AS |
| Others |
Supply & Pricing Matrix
Osaka-based fermentation capacity utilization above 85 percent compresses unit economics for anthocyanin producers while establishing price floors that imported synthetics struggle to match under METI's escalating compliance burdens. This scale concentration simultaneously elevates procurement leverage for Kanto beverage manufacturers and fragments margin capture across upstream botanical suppliers in Hokkaido and Tohoku.
Pricing Analysis
Certification level creates the primary spread between JIS S 0050-qualified natural extracts and uncertified commodity alternatives. Three-tier pricing structure across premium certified, standard food-grade, and economy industrial tiers reflects compliance investment recovery timelines. Pricing pressure intensifies in synthetic dye segments as METI disclosure thresholds trigger reformulation away from azo-based imports. Small-batch artisan bakeries in Tokyo exhibit highest price sensitivity, while Kirin and Suntory procurement teams prioritize supply security over unit cost optimization.
Supply Chain Analysis
Inventory cycles stretching 8-12 weeks for heat-sensitive natural pigments constrain just-in-time delivery commitments to Okinawa and Hokkaido distribution networks. Supply concentrates in Osaka prefecture for fermentation-derived anthocyanins and in Kanto for synthetic blending operations. Raw material dependencies center on Hokkaido beetroot cultivation, imported turmeric oleoresin, and domestic spirulina harvests. Single-source fermentation vulnerability represents the dominant structural risk. Distribution runs through Nagase's century-old trading house network and emerging direct procurement portals serving Meiji and Ajinomoto.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as plant-derived extracts displace synthetic formulations under METI's clean-label mandates and PMDA safety monitoring protocols.
For Market Incumbents: Fortify captive fermentation capacity in Osaka through bioreactor expansion and backward integration into Hokkaido beetroot contract farming. Secure JIS S 0050 certification buffers against imported synthetic price erosion while METI disclosure rules accelerate azo-dye displacement. Channel control through direct procurement relationships with top-five food manufacturers reduces trading house margin extraction. For New Entrants and Emerging Players: Lead with microencapsulation technology licensing to penetrate beverage sector reformulation cycles at Kirin and Asahi Soft Drinks. Kyushu's underpenetrated functional food corridor offers white space for colorant-cosmetic crossover applications under PMDA's regional consultation framework. Digital procurement platforms disintermediate legacy trading house networks for Tokyo artisan bakery subscriptions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation-integrated natural colorant producers with captive bioreactor assets and multi-year supply agreements. Long-term viability hinges on certification moats and regional production clustering that insulates against import volatility. Watch METI's REACH-equivalent alignment timeline as the critical inflection signal for export-facing qualification backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Expansion | Osaka-based bioreactor investments secure domestic anthocyanin supply continuity for risk-averse beverage procurement teams. |
| JIS S 0050 Certification Acceleration | Third-party laboratory qualification timelines compress reformulation windows against fixed product launch schedules at major processors. |
| Direct Procurement Platform Development | Digital disintermediation of Nagase trading house networks captures margin from small-batch artisan bakeries in Tokyo. |
| Microencapsulation Technology Licensing | Sub-50-micron particle formulations reduce cold-chain freight costs for long-haul distribution to Okinawa and Hokkaido. |
| Hokkaido Contract Farming Integration | Backward control over beetroot cultivation hedges weather-dependent harvest volatility for betalaine-dependent confectionery applications. |
Research Methodology
Initial hypotheses were tested against primary input from food manufacturing procurement directors, beverage formulation scientists, trading house account managers, and METI regulatory affairs specialists and refined through secondary validation. Primary fieldwork combined structured interviews with supply chain stakeholders at Calbee, Meiji, and Morinaga facilities with facility visits to Osaka fermentation operations. Secondary sources encompassed JIS standards documentation, METI chemical substance reporting filings, PMDA safety monitoring records, and customs trade data for colorant imports. Bottom-up volume modeling from individual processor consumption patterns was triangulated against top-down market sizing from production value aggregates.
Variance decomposition across color type, application, physical form, and end-user scale dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segmented volume trajectories weighted by price realization trends in natural versus synthetic categories. Forecast inputs incorporated METI regulatory timeline assumptions, PMDA functional claims approval velocity, and regional manufacturing cluster expansion patterns in Kanto and Kyushu.
The analysis sits within stated boundaries; outcomes outside sustained clean-label reformulation momentum or accelerated REACH-equivalent alignment would require recalibration. Forecasts reflect documented assumptions regarding certification backlog resolution and fermentation capacity utilization stability. Beetroot harvest volatility, single-source supply concentration, and customs processing delays at Yokohama represent primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
China Food Colorants Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Flavor Drops Market
Flavorings and Food Additives
Citrus Oil Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market