
 Rose Water Market | 2026-2036
Rose Water Market Size, Share, and Industry Trends Forecast 2026-2036
Rose Water Market Outlook
Buyer concentration in the cosmetic industry is consolidating as multinational skincare brands reduce supplier rosters and demand certified organic traceability. Givaudan SA leverages its integrated fragrance and flavor network to secure long-term rose damascena contracts from Iranian and Bulgarian growers. Alteya Inc anchors its position through USDA organic certification and controlled cultivation in Bulgaria's Rose Valley. Dabur India Ltd competes across Ayurvedic personal care channels with heritage brand equity and pharmacy distribution.
Rose water is a hydrosol produced by steam distillation of Rosa damascena or Rosa centifolia petals, yielding a clear aqueous solution containing trace essential oils, phenylethyl alcohol, and flavonoids used for fragrance, flavoring, and topical applications. Organic rose water commands premium positioning as clean-label cosmetics brands reject synthetic preservatives and solvent-extracted alternatives. The cosmetic industry end-use segment leads volume absorption, while hydrosol grades with higher essential oil retention capture concentrated margin pools in professional spa and pharmaceutical channels.
EU REACH and EFSA frameworks govern cosmetic ingredient safety declarations and food-grade flavoring substance approvals, compelling exporters to maintain batch-level documentation. Iran's national standards body and BIS in India enforce distillation purity benchmarks that determine export eligibility for traditional producers. Stakeholders must monitor regulatory divergence between organic certification regimes as fragmentation in compliance requirements reshapes sourcing strategies and competitive access.
Market Dynamics
Clean-label cosmetic certification is compressing supplier margins while concentrating procurement among vertically integrated fragrance houses that control damascena cultivation through direct grower contracts in Iran and Bulgaria.
Growth Catalysts
- EU REACH compliance mandates:Batch-level ingredient transparency requirements are disqualifying solvent-extracted alternatives and redirecting formulation demand toward certified organic hydrosol grades.
- Steam distillation process optimization:Closed-loop condensation systems are recovering higher essential oil retention rates, enabling professional spa channels to absorb premium-priced concentrated grades.
- Kashan cluster supply security:Centuries-old Iranian distillation infrastructure provides fragrance houses with heritage-protected Rosa damascena provenance that commands price premiums in European markets.
Market Restraints
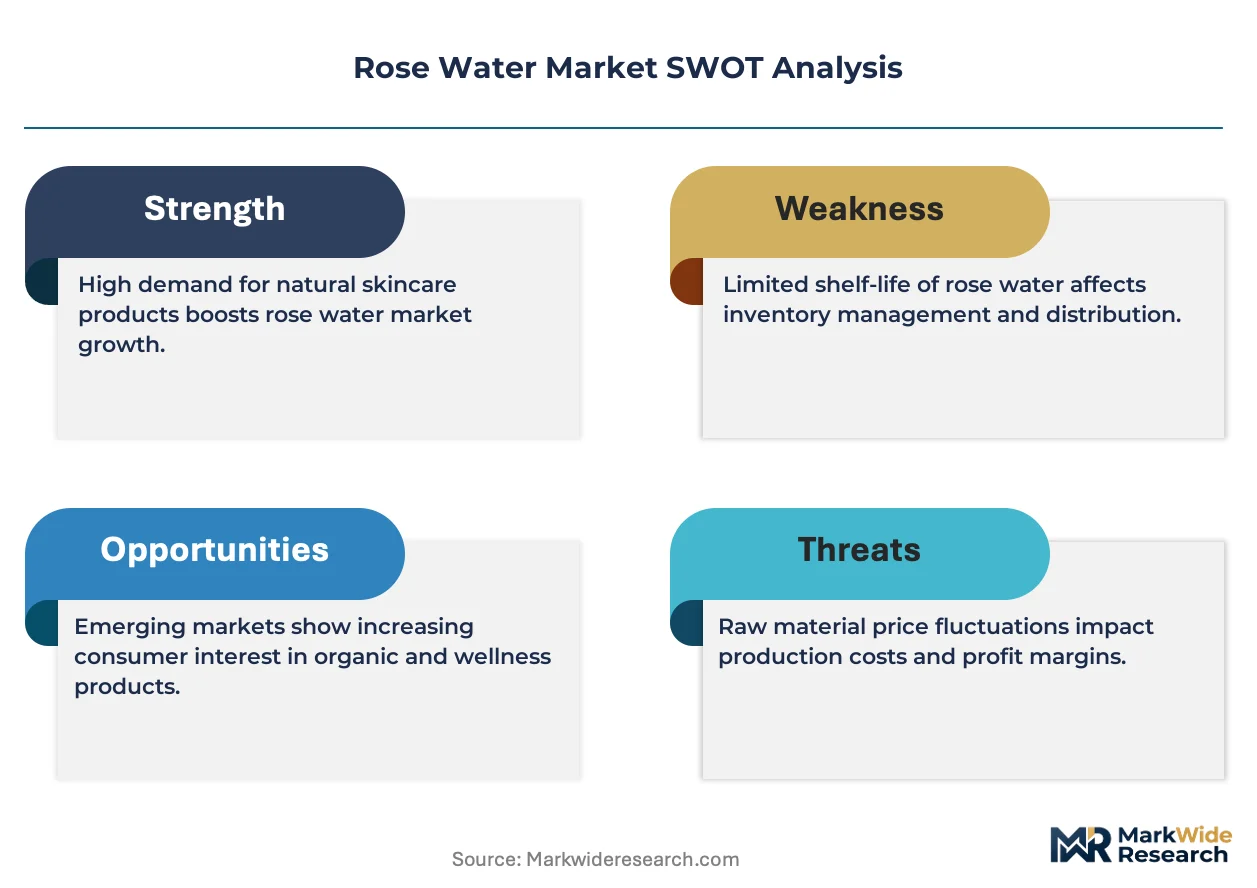
- Damascena petal input volatility:Climate stress on Bulgarian and Iranian rose harvests creates annual yield uncertainty that distorts contract pricing for hydrosol processors.
- Single-region supply concentration:Over-reliance on Iran's Kashan region for premium-grade raw material exposes buyers to geopolitical disruption and export licensing friction.
- Shelf-life technical limitation:Absence of synthetic preservatives in organic-certified grades restricts distribution reach and cold-chain logistics options for mass-market retail.
Strategic Opportunities
- Ayurvedic personal care channel expansion:India's pharmacy distribution networks offer underpenetrated access points for heritage-positioned rose water in therapeutic skincare applications.
- EFSA food-grade flavoring approval pathway:Regulatory tailwind from completed safety dossiers is opening beverage and confectionery formulation demand beyond traditional cosmetic use.
- E-commerce direct-to-consumer channel:Digital native beauty brands are bypassing traditional fragrance house intermediaries to capture margin through subscription-based hydrosol replenishment models.
Industry Challenges
- Organic certification timeline compression:USDA and EU organic audit backlogs are delaying new supplier market entry and freezing capacity expansion timelines for 18-24 month cycles.
- Distillation workforce skill scarcity:Traditional steam distillation expertise concentrated in aging Bulgarian and Iranian technician pools is constraining quality-controlled capacity scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rose Water Market |
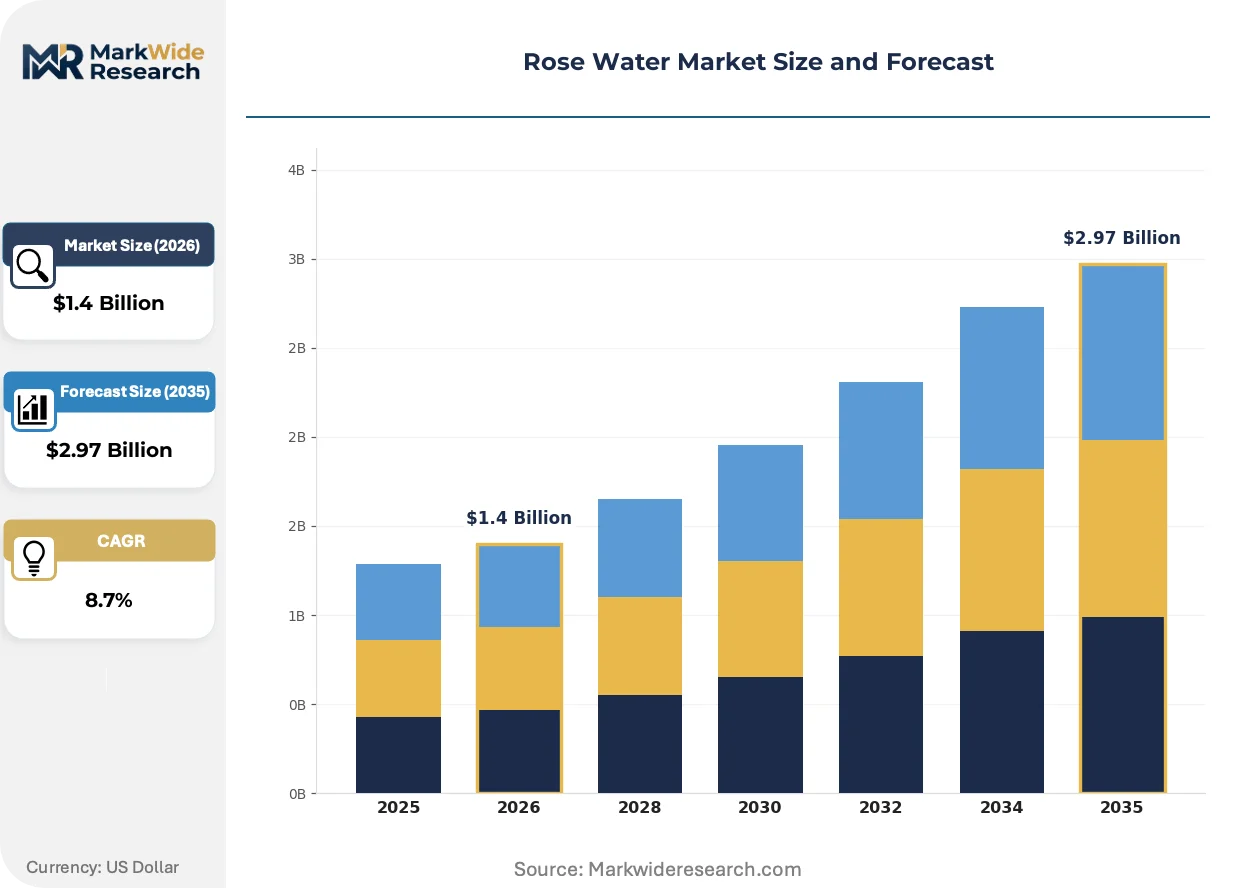
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Rose Water, Distilled Rose Water, Steam Distilled Rose Water, Hydrosol Packaging Type: Glass Bottles, Plastic Bottles, Metal Containers, Sachets End User: Cosmetic Industry, Food & Beverage Sector, Pharmaceutical Sector, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Eve Hansen, Givaudan SA, Alteya Inc, Iran Golab Co., Rose of Bulgaria, Dabur India Ltd, Aadhunik Ayurveda Vitals, SVA Naturals, Poppy Austin Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rose Water Market Strategic Shifts
Traceability technology and regulatory disclosure requirements are restructuring how rose water moves from cultivation clusters to formulation labs, with authentication systems now treated as competitive infrastructure rather than compliance overhead.
Blockchain-enabled provenance tracking is unifying cultivation records, distillation batch data, and certification documentation into single-source transparency platforms. Premium cosmetic brands are adopting these systems to defend clean-label positioning against adulteration scandals. This technology is unifying previously fragmented supply chain documentation and compressing due diligence cycles for multinational procurement teams.
EU Green Deal chemical sustainability frameworks are extending disclosure requirements to natural ingredient supply chains, compelling Iranian and Bulgarian exporters to document water usage and carbon intensity per liter of hydrosol output. Fragrance houses are responding by retrofitting distillation facilities with biomass energy systems to maintain EU market access. Professional spa and pharmaceutical-grade segments face the steepest compliance cost absorption.
Ingredient preference is rotating toward multifunctional hydrosols that deliver both fragrance and active skincare benefits in single formulations. Cosmetic chemists are reformulating toners and essences to replace separate essence-and-toner steps, compressing SKU counts for minimalist beauty lines. This pattern is most visible in South Korean and Japanese skincare markets where routine simplification has become a dominant product positioning axis.
Rose Water Market Segmentation
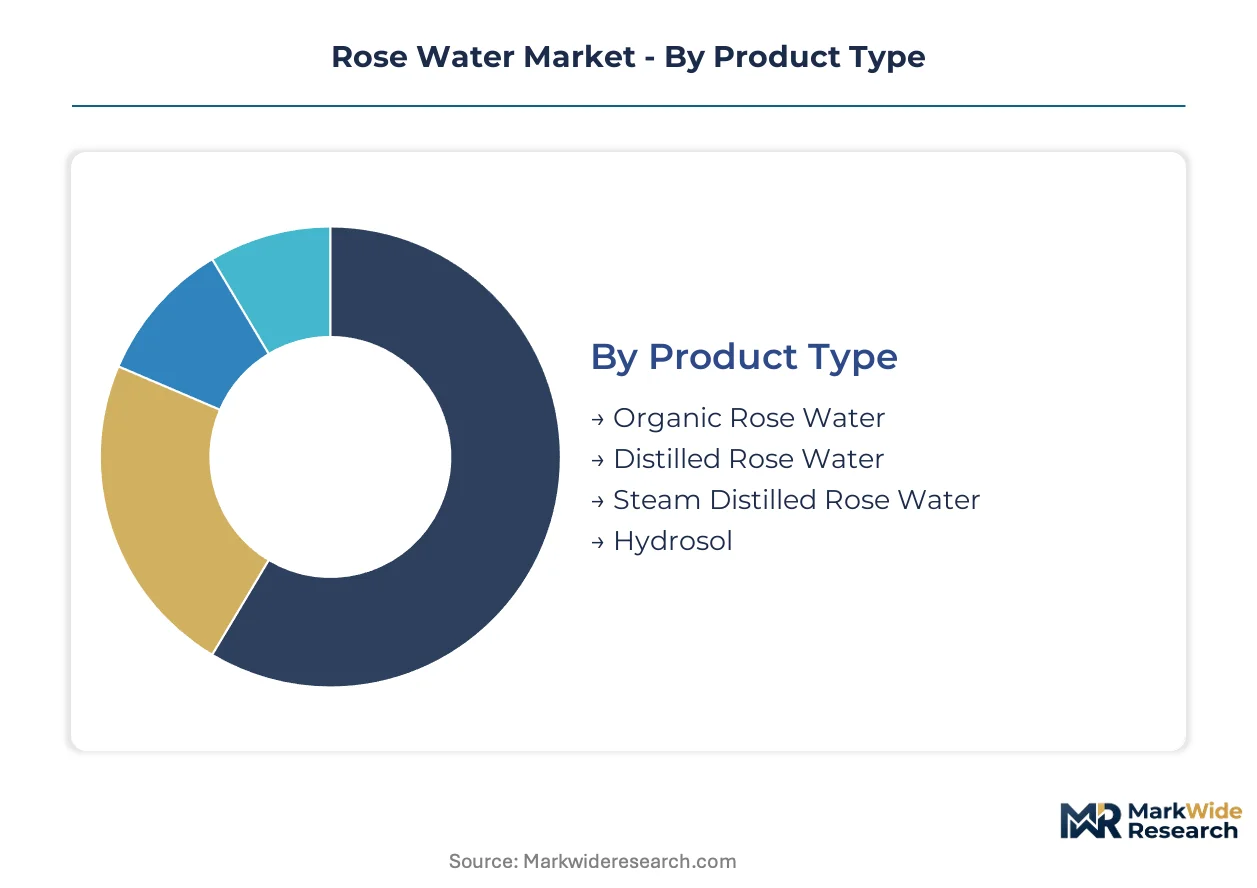
Rose water segmentation reflects divergent purity standards, preservation requirements, and channel economics that shape procurement patterns across cosmetic, pharmaceutical, and food-grade applications. Each category captures distinct buyer priorities—from certification thresholds to shelf-life logistics—that fragment supplier strategies and margin structures.
Product Type:
Buyers in this category differentiate primarily by certification status and essential oil retention rates, which determine formulation eligibility and price positioning.
- Organic Rose Water:USDA or EU organic-certified hydrosol produced from pesticide-free Rosa damascena cultivation. EU REACH compliance mandates are disqualifying solvent-extracted alternatives and redirecting formulation demand toward certified organic hydrosol grades.
- Distilled Rose Water:Traditional steam-distilled product with variable essential oil content depending on condensation efficiency. Cosmetic industry procurement concentrates here for clean-label toners and essences, though batch consistency varies by distillation equipment age.
- Steam Distilled Rose Water:Closed-loop condensation systems are recovering higher essential oil retention rates, enabling professional spa channels to absorb premium-priced concentrated grades.
- Hydrosol:Technical-grade aqueous distillate with standardized phenylethyl alcohol content for pharmaceutical and professional skincare applications.
Volume sits with Distilled Rose Water; growth tilts toward Organic Rose Water.
Packaging Type:
Packaging selection tracks preservation chemistry, logistics cost, and retail channel aesthetics with minimal overlap between premium and mass-market tiers.
- Glass Bottles:Amber or cobalt glass blocks UV degradation for organic-certified grades lacking synthetic preservatives. Specialty store and direct sales channels absorb the majority of unit volume here.
- Plastic Bottles:PET and HDPE formats dominate supermarket and online retail distribution where cost-per-unit and shipping weight drive procurement decisions.
- Metal Containers:Aluminum and tin-plated steel provide light and oxygen barriers for bulk pharmaceutical and food-service quantities.
- Sachets:Single-use foil laminates serve travel retail and sample distribution with minimal unit economics.
Plastic Bottles carry the volume base; Glass Bottles capture the steepest expansion trajectory as clean-label positioning hardens.
End User:
End-use segmentation fragments by regulatory jurisdiction, formulation complexity, and margin tolerance across consumer-facing and industrial buyers.
- Cosmetic Industry:Multinational skincare brands and fragrance houses absorb hydrosol grades for toners, essences, and fragrance bases. Buyer concentration is consolidating as multinational skincare brands reduce supplier rosters and demand certified organic traceability.
- Food & Beverage Sector:EFSA food-grade flavoring approval pathway is opening beverage and confectionery formulation demand beyond traditional cosmetic use.
- Pharmaceutical Sector:GMP-compliant hydrosol for topical antiseptic and wound care applications with documented batch purity.
- Households:Direct-to-consumer channels serve aromatherapy and DIY cosmetic preparation with smaller format packaging.
Cosmetic Industry commands current volume leadership; Food & Beverage Sector is gaining share fastest on regulatory tailwinds.
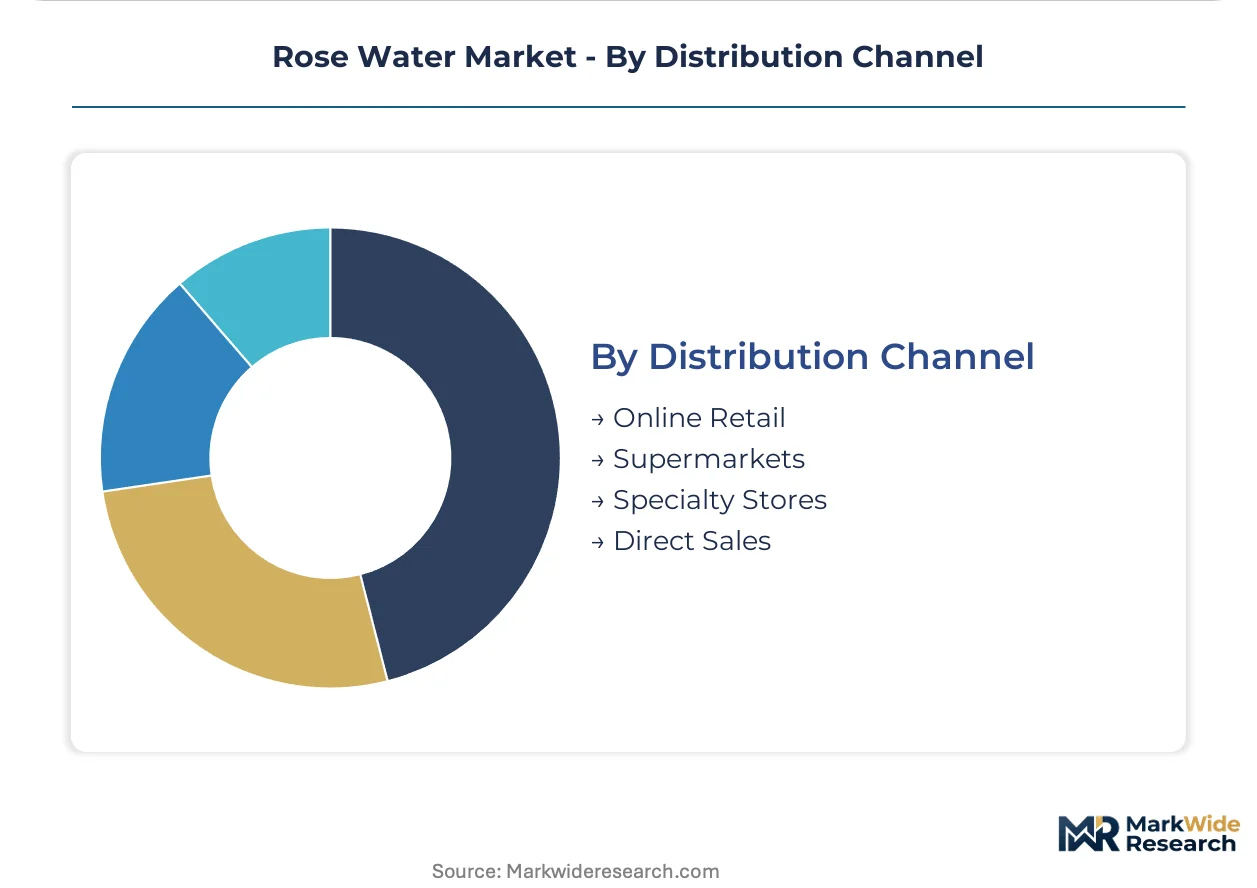
Distribution Channel:
Channel economics diverge sharply between margin-retentive direct models and scale-oriented retail intermediaries.
- Online Retail:Digital native beauty brands are bypassing traditional fragrance house intermediaries to capture margin through subscription-based hydrosol replenishment models.
- Supermarkets:Mass-market retail placement requires extended shelf-life solutions that conflict with organic certification constraints.
- Specialty Stores:Sephora, Douglas, and regional beauty chains curate premium and niche positioning with trained staff consultation.
- Direct Sales:Ayurvedic and heritage brands leverage pharmacy networks in India and spa relationships in Europe for therapeutic positioning.
Supermarkets dominate unit movement; Online Retail is expanding most quickly as DTC infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic formulation demand concentrates in European fragrance houses and Indian Ayurvedic channels, with supply-side clustering in Iran's Kashan region and Bulgaria's Rose Valley driving trade flows.
Iran
Traditional damascena distillation in Kashan supplies heritage-provenanced hydrosol to European fragrance houses. The country's national standards body enforces distillation purity benchmarks that determine export eligibility. Centuries-old infrastructure in the Kashan cluster maintains price premiums through protected cultivation practices.
Bulgaria
Rose Valley cultivation supports organic-certified hydrosol production for clean-label cosmetic brands. EU REACH compliance mandates batch-level documentation that Bulgarian exporters must maintain for market access. Kazanlak-based processors operate closed-loop condensation systems to capture higher essential oil retention rates.
India
Ayurvedic personal care channels absorb heritage-positioned rose water through pharmacy distribution networks. BIS enforces purity standards that shape export eligibility for traditional producers. Maharashtra and Gujarat house concentrated processing capacity serving domestic therapeutic skincare applications.
Germany
Fragrance houses headquartered here consolidate procurement through direct grower contracts in source regions. ECHA administers REACH frameworks governing cosmetic ingredient safety declarations. Hamburg and Frankfurt serve as formulation hubs where hydrosol grades undergo final blending for European distribution.
United States
Clean-label cosmetic brands drive demand for USDA organic-certified grades rejecting synthetic preservatives. FDA oversees cosmetic ingredient safety while USDA manages organic certification audits. Digital native beauty brands in California and New York deploy subscription-based replenishment models bypassing traditional intermediaries.
Rose Water Market Competitive Environment
Iranian and Bulgarian producers anchor the heritage-provenanced tier; Indian Ayurvedic specialists hold pharmacy-channel positions. The vendor base splits between vertically integrated fragrance houses controlling cultivation contracts and independent distillers serving niche cosmetic brands. Three archetypes dominate: integrated fragrance houses with captive supply, certified organic specialists with controlled cultivation, and heritage Ayurvedic brands with pharmacy distribution. Competitive moves concentrate on backward integration into damascena cultivation and blockchain-enabled traceability deployment.
Among heritage-positioned specialists, Givaudan SA represents the integrated fragrance house archetype through its network of direct grower contracts. Alteya Inc exemplifies the certified organic specialist model with controlled cultivation positioning. Dabur India Ltd anchors the Ayurvedic heritage tier with pharmacy distribution infrastructure. These three occupy distinct competitive spaces without direct overlap in procurement channels or certification positioning.
| Leading Market Players |
|---|
| Eve Hansen |
| Givaudan SA |
| Alteya Inc |
| Iran Golab Co. |
| Rose of Bulgaria |
| Dabur India Ltd |
| Aadhunik Ayurveda Vitals |
| SVA Naturals |
| Poppy Austin Ltd |
| Others |
Value Chain & Pricing Dynamics
Damascena petal input costs cascade through three distinct pricing tiers, with Kashan-sourced organic hydrosol commanding premiums over Bulgarian alternatives while solvent-extracted grades face margin compression from EU REACH disqualification. Steam distillation energy intensity and cold-chain logistics requirements for preservative-free grades concentrate margin capture among fragrance houses with captive cultivation contracts.
Pricing Analysis
Volume concentrates in distilled rose water for mass-market cosmetic toners, while organic-certified grades with blockchain traceability capture concentrated margin pools in professional spa and pharmaceutical channels. Price differentiation hinges on essential oil retention rates and USDA/EU organic certification status, with heritage-provenanced Kashan origins supporting additional brand premiums. Pricing pressure intensifies in standard distilled grades as multinational skincare brands consolidate supplier rosters and demand batch-level transparency documentation. Mass-market retail buyers exhibit highest price sensitivity, whereas fragrance houses and pharmaceutical formulators prioritize certification integrity over unit cost.
Supply Chain Analysis
EU organic certification and REACH compliance documentation function as gating mechanisms that filter supplier participation and concentrate procurement among vertically integrated fragrance houses. Supply concentrates in Iran's Kashan region and Bulgaria's Rose Valley, with raw material dependencies on Rosa damascena petal harvests, distillation fuel sources, and amber glass packaging for UV-sensitive organic grades. Single-region concentration in Kashan exposes buyers to geopolitical disruption and export licensing friction. Distribution runs through fragrance house intermediaries for bulk cosmetic formulation, with direct-to-consumer channels expanding through subscription-based replenishment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rose water supply remains structurally constrained by aging distillation technician pools and 18-24 month organic certification timelines, bottlenecks that prop pricing power for incumbent processors with established audit relationships.
For Market Incumbents: Acquire cultivation contracts in Bulgaria's Rose Valley to secure damascena petal supply ahead of climate-stressed harvest volatility. Consolidate blockchain traceability infrastructure to defend clean-label positioning against adulteration scandals and compress due diligence cycles for multinational procurement teams. Certification audit backlogs threaten new capacity entry, reinforcing margin capture for established organic-certified processors.
For New Entrants and Emerging Players: Launch via India's pharmacy distribution networks to access underpenetrated Ayurvedic therapeutic skincare channels with heritage-positioned formulations. Target EFSA food-grade flavoring approvals to capture beverage and confectionery demand beyond saturated cosmetic applications. Direct-to-consumer subscription models bypass fragrance house intermediaries and capture margin through replenishment-based customer relationships.
For Investors and Strategic Acquirers: Completion of EFSA safety dossiers for food-grade applications is the leading indicator that hydrosol demand will expand beyond cosmetic use into higher-margin flavoring segments. Long-term viability rests on backward integration into damascena cultivation and controlled distillation capacity rather than toll-processing arrangements. Monitor EU Green Deal chemical sustainability framework implementation as the signal for accelerated carbon intensity disclosure requirements that will favor biomass-retrofitted facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Damascena Cultivation | Captive petal supply from Kashan or Rose Valley insulates processors from annual yield volatility and contract pricing distortion. |
| Blockchain Provenance Deployment | Single-source transparency platforms unify cultivation records and certification documentation for clean-label cosmetic brand defense. |
| Biomass Energy Retrofit | EU Green Deal carbon intensity disclosure requirements favor distilleries converting to biomass systems for continued market access. |
| EFSA Food-Grade Approval Pursuit | Completed safety dossiers unlock beverage and confectionery formulation demand beyond traditional cosmetic channel saturation. |
| Direct-to-Consumer Channel Launch | Subscription-based replenishment models bypass fragrance house intermediaries and capture margin through digital-native brand building. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving distillation facility operators, cosmetic formulation chemists, fragrance house procurement directors, and organic certification auditors. ECHA REACH documentation, USDA organic audit records, BIS purity benchmarks, and Iranian national standards body filings provided regulatory traceability. Bottom-up volume modeling from cultivation cluster outputs reconciled with top-down demand estimates from end-use sector consumption patterns.
Data-stream reconciliation across supply-side capacity assessments and demand-side procurement surveys enabled forecast construction across the projection horizon. Segmentation dimensions modeled include product type by certification status and essential oil retention, packaging format by preservation chemistry requirements, end-use sector by regulatory jurisdiction, and distribution channel by margin structure. CAGRs derived from trend extrapolation of organic certification penetration rates, EFSA approval timelines, and e-commerce channel expansion trajectories. Climate stress indices for Bulgarian and Iranian harvest zones informed supply-side sensitivity analysis.
Geopolitical disruption in Iran, EU regulatory divergence on organic certification equivalence, and accelerated climate stress on damascena yields are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding certification audit processing timelines, fragrance house supplier consolidation velocity, and cold-chain infrastructure expansion for preservative-free grades. A model refresh is warranted upon material change in EU Green Deal implementation timelines or Kashan export licensing protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Natural and Organic Flavors Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Vanillin Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market