
 North America Food Colorants Market | 2026-2036
North America Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Colorants Market Analytics
Subscription-based color formulation services is shifting how ingredient suppliers monetize their relationships with food manufacturers. Sensient Technologies Corporation leverages its technical service platforms to embed color science directly into client product development cycles. Dohler Group anchors its North American position through integrated beverage ingredient systems that bundle color with flavor and texture. Givaudan SA competes by extending its natural color portfolio through specialized extraction capabilities.
Food colorants comprise pigments and dyes added to consumable products to enhance visual appeal, indicate flavor profiles, or compensate for color loss during processing; these additives must meet strict stability requirements for heat, light, and pH tolerance across diverse food matrices. Natural colors derived from beet anthocyanins, turmeric curcuminoids, and spirulina phycocyanin now command premium positioning as clean-label formulations displace azo-based synthetics in mainstream applications. Synthetic colors retain volume leadership in confectionery and snack segments where vivid hue intensity and batch-to-batch consistency remain non-negotiable. Powder and liquid forms dominate industrial procurement, with powder formats preferred for dry-mix applications and liquids optimized for beverage dosing systems.
FDA color additive regulations under 21 CFR 73 and 74 govern permissible substances and batch certification requirements, while Health Canada's Food and Drug Regulations and the PMRA establish parallel compliance thresholds for cross-border product formulations. The USDA National Organic Program and CFIA organic standards further segment market access by certifying plant-derived color sources for organic-labeled products. Stakeholders must monitor evolving state-level ingredient disclosure laws in California and New York that extend beyond federal minimums.
Market Dynamics
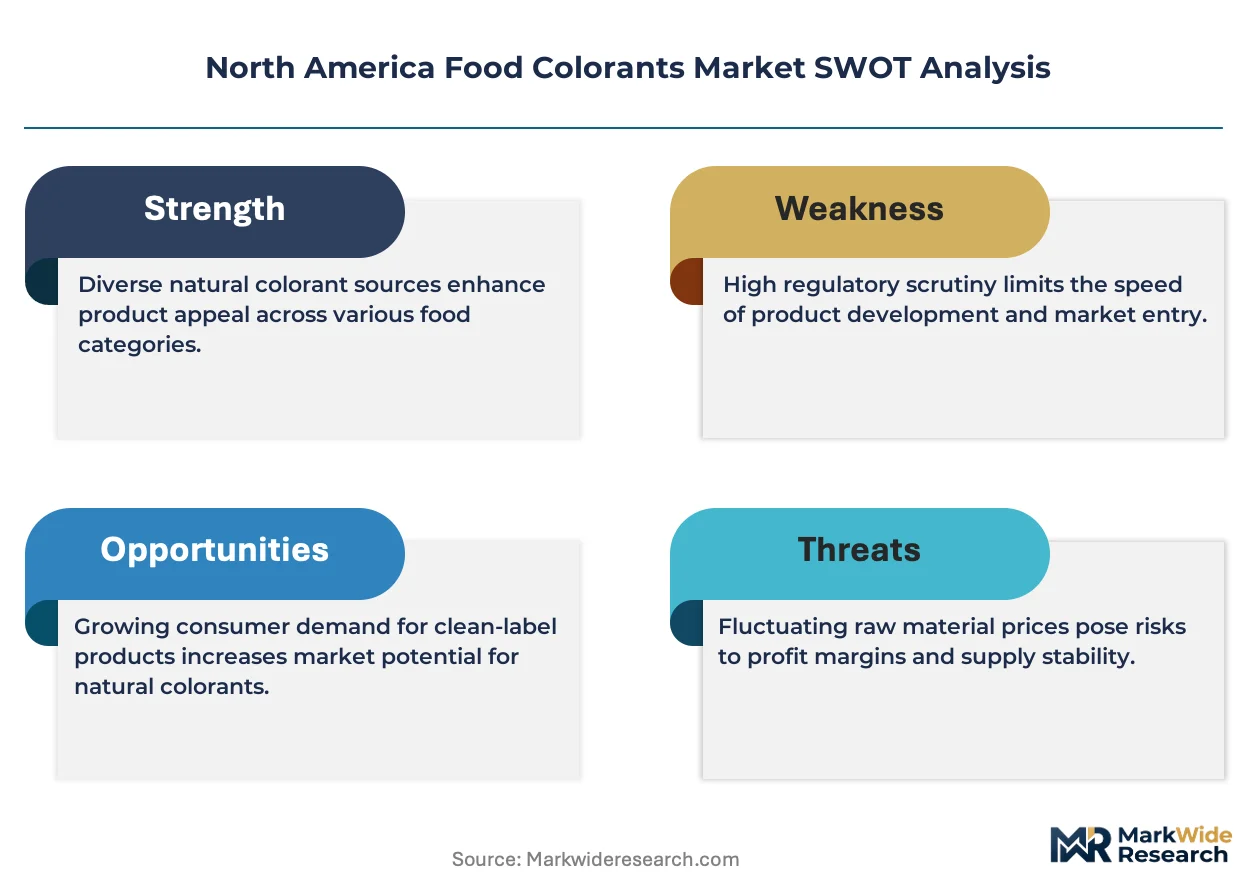
Clean-label mandates from FDA and Health Canada are compressing permissible synthetic additive lists, forcing beverage and confectionery manufacturers to reformulate with plant-derived alternatives while maintaining batch-to-batch color stability.
Growth Catalysts
- Regulatory compression:Health Canada's tightening restrictions on azo dyes under the Food and Drug Regulations are accelerating natural colorant R&D investment across Canadian food manufacturing corridors.
- Beverage system bundling:Integrated color-flavor-texture platforms are displacing standalone pigment procurement as beverage producers consolidate supplier relationships for speed-to-market.
- California manufacturing density:Food processing clusters in the Central Valley and Los Angeles basin concentrate demand for heat-stable natural reds and yellows in plant-based meat and dairy alternatives.
Market Restraints
- Anthocyanin supply volatility:Beet and berry crop yields in the U.S. Midwest and Pacific Northwest fluctuate with irrigation constraints, destabilizing natural red pigment pricing.
- Certification bottlenecks:USDA National Organic Program and CFIA organic colorant approvals require 18-24 month validation cycles, delaying product launches for reformulated clean-label lines.
- Synthetic color lock-in:Confectionery manufacturers in Mexico and the U.S. Southeast retain azo dye dependence for vivid hue intensity that natural alternatives cannot yet replicate at scale.
Strategic Opportunities
- Spirulina extraction scale-up:Phycocyanin production facilities in Texas and Arizona can capture unmet demand for heat-stable blue pigments in sports nutrition and functional beverages.
- Subscription formulation services:Technical service platforms embedding color scientists directly into client NPD cycles are replacing transactional pigment sales with recurring revenue models.
- New York disclosure laws:State-level ingredient transparency mandates extending beyond federal minimums create first-mover advantage for suppliers with pre-validated clean-label portfolios.
Industry Challenges
- Cross-border compliance complexity:Divergent FDA and Health Canada batch certification requirements force dual-track documentation systems for North American product lines.
- Natural color stability engineering:Heat and light degradation of turmeric curcuminoids in retort processing demands specialized encapsulation expertise that remains scarce in the talent pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Colorants Market |
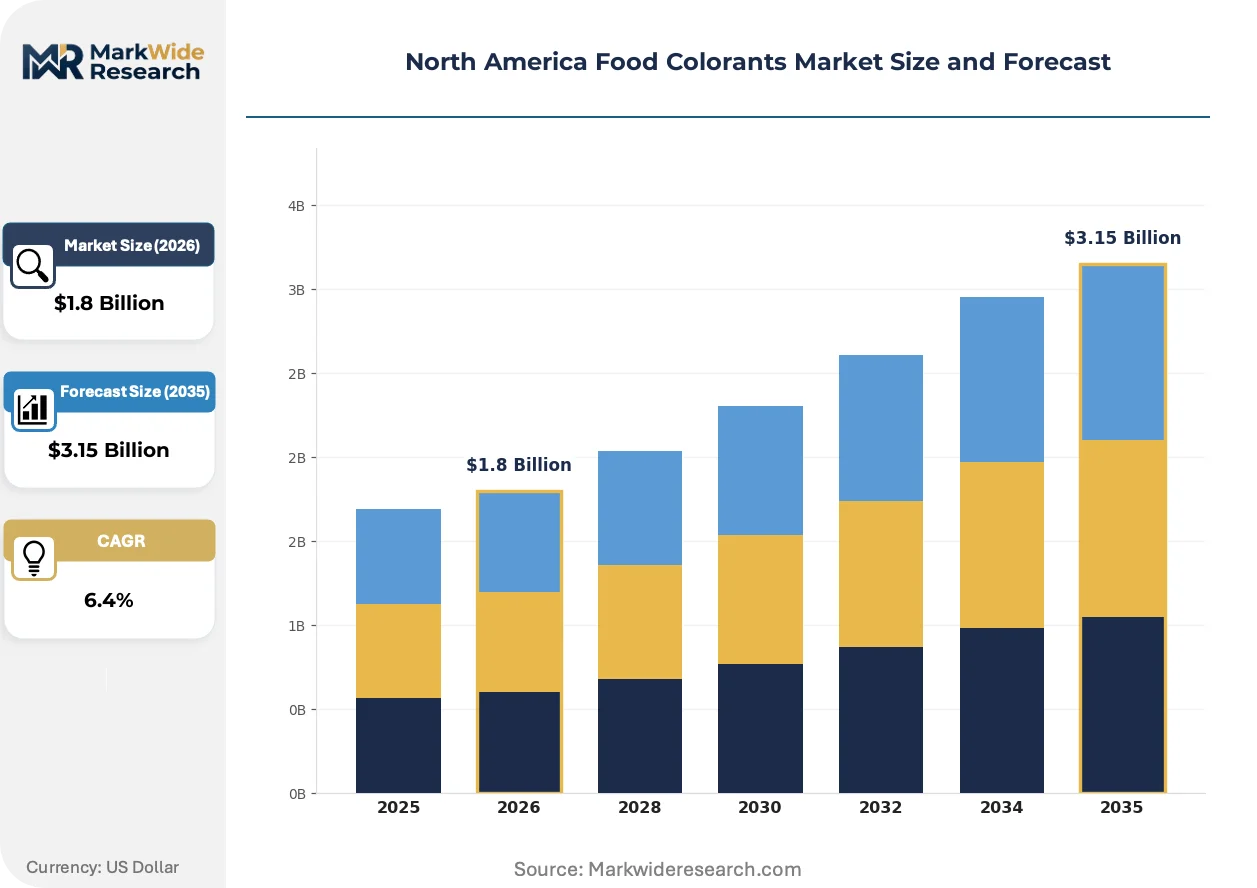
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Colors, Organic Colors, Color Additives End User: Food Manufacturers, Beverage Producers, Confectionery Companies, Bakery Products Application: Snacks, Dairy Products, Sauces, Frozen Foods Form: Liquid, Powder, Gel, Granule |
| Companies Covered | Givaudan SA, Dohler Group, Sensient Technologies Corporation, Naturex SA, Oterra A/S, Chr. Hansen, BASF SE, DSM, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Colorants Market Evolving Landscape
Microencapsulation technologies and fermentation-derived pigments are rewriting stability-performance tradeoffs, while regulatory disclosure mandates and direct-supplier relationships are compressing traditional distribution hierarchies.
Encapsulation systems for turmeric and beet extracts are integrating lipid and alginate barrier layers that extend heat stability through retort and UHT processing. Beverage and sauce manufacturers in the U.S. Midwest are adopting these systems at pilot scale, with full production integration expected within 24 months. This technology is integrating natural colorants into applications previously reserved for synthetic azo dyes, collapsing the performance gap that has sustained artificial pigment volume.
Health Canada's 2023 updates to the Food and Drug Regulations narrowed permissible synthetic color lists and mandated enhanced batch testing documentation. Cross-border food manufacturers now face dual compliance burdens, with reformulation costs concentrated in confectionery and snack segments where vivid hue intensity remains critical. Canadian and U.S. producers are responding by accelerating natural colorant validation programs and consolidating supplier relationships with integrated technical service providers.
Direct technical partnerships between colorant suppliers and mid-sized food manufacturers are displacing traditional ingredient distributor intermediaries. California and New York-based clean-label brands now source pigments through embedded formulation scientists rather than catalog purchasing, compressing supplier margins but securing exclusive access to custom color systems. This channel shift is most visible in plant-based dairy and meat alternatives, where color-performance differentiation drives shelf placement and consumer trial.
North America Food Colorants Market Segmentation
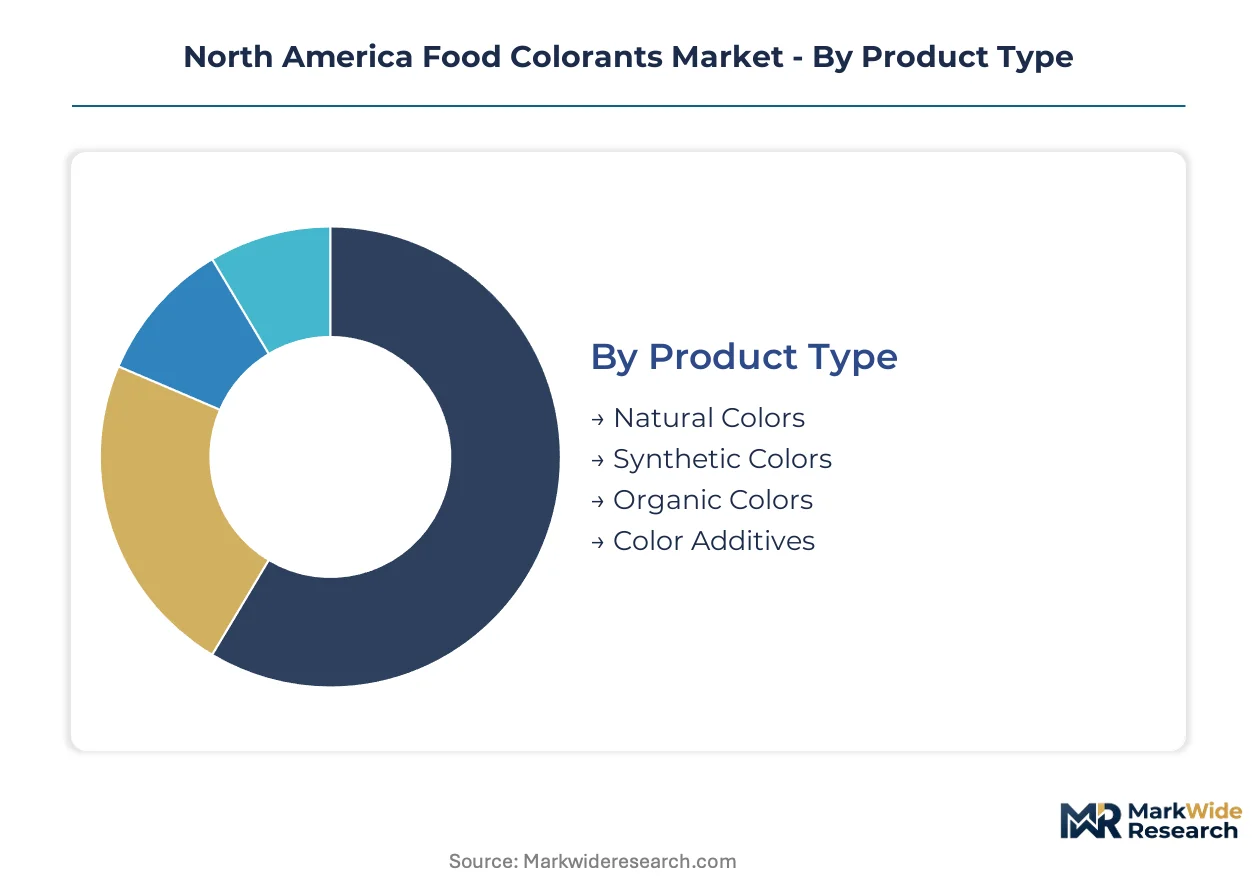
Food colorant procurement patterns in North America diverge sharply across product technologies and end-use specifications. Reformulation cycles driven by FDA and Health Canada regulatory compression are reshaping segment priorities faster than historical replacement timelines.
Product Type:
Upgrade cycles from synthetic to natural platforms now operate on 18-month horizons rather than traditional 3-5 year ingredient contracts.
- Natural Colors:Anthocyanin, carotenoid, and chlorophyll-based extracts from beet, turmeric, and spirulina dominate new product development pipelines. California and Pacific Northwest beverage manufacturers are locking multi-year supply agreements for heat-stable reds and blues as azo dye restrictions tighten.
- Synthetic Colors:FD&C-certified azo dyes and aluminum lakes retain volume leadership in Mexican confectionery and U.S. Southeast snack manufacturing where vivid hue intensity and batch consistency remain non-negotiable. Reformulation cost barriers delay displacement in these corridors.
- Organic Colors:USDA National Organic Program-certified pigments command 40-60% price premiums over conventional natural alternatives. Supply bottlenecks from 18-24 month certification cycles constrain availability for mid-sized clean-label brands.
- Color Additives:Functional blends combining pigment with antioxidant or UV-stabilizer properties address stability gaps in extended-shelf-life applications. Demand concentrates in retort-processed sauces and ready-to-eat meals.
Volume placements concentrate in Synthetic Colors; the faster expansion belongs to Natural Colors.
End User:
Customer procurement sophistication separates consolidated technical partnerships from transactional catalog purchasing.
- Food Manufacturers:Plant-based meat and dairy alternatives in the U.S. Midwest and California Central Valley drive demand for browning agents and fat-mimicking color systems. These producers embed color scientists directly into NPD cycles through subscription formulation services.
- Beverage Producers:Sports nutrition and functional drink specialists in Texas and Arizona prioritize spirulina-derived blues and high-stability yellows for clear-label positioning. Integrated color-flavor-texture platforms displace standalone pigment procurement.
- Confectionery Companies:Mexican and U.S. Southeast manufacturers retain synthetic dye dependence for hard candy and gummy applications where natural alternatives fail to achieve spectral purity. Reformulation investments lag other segments.
- Bakery Products:Artisan and industrial bakers in the Northeast and Pacific Northwest specify natural carmine and turmeric for clean-label cake and pastry decoration. Heat degradation during baking limits viable pigment options.
Procurement sophistication peaks with Food Manufacturers; Beverage Producers are climbing the fastest as functional drink categories expand.
Application:
Processing intensity and shelf-stability requirements dictate colorant technology selection across food matrices.
- Snacks:Extruded and puffed products require heat-stable pigments surviving 150°C+ processing temperatures. Natural color adoption lags here due to thermal degradation of anthocyanins and betalains.
- Dairy Products:Yogurt, cheese, and ice cream applications favor liquid color systems for homogeneous dispersion. Turmeric and annatto dominate yellow-orange segments; spirulina blues penetrate premium functional yogurt lines.
- Sauces:Tomato-based and emulsified dressings demand pH-stable pigments across acidic to neutral ranges. Microencapsulated turmeric and paprika extracts are gaining pilot-scale adoption for retort-processed barbecue and pasta sauces.
- Frozen Foods:Ice crystal formation and freeze-thaw cycling test pigment dispersion stability. Frozen dessert and prepared meal manufacturers specify carotenoid-based systems with proven cryogenic tolerance.
Technology barriers remain steepest in Snacks; Dairy Products are gaining share fastest as clean-label yogurt and functional ice cream segments multiply.
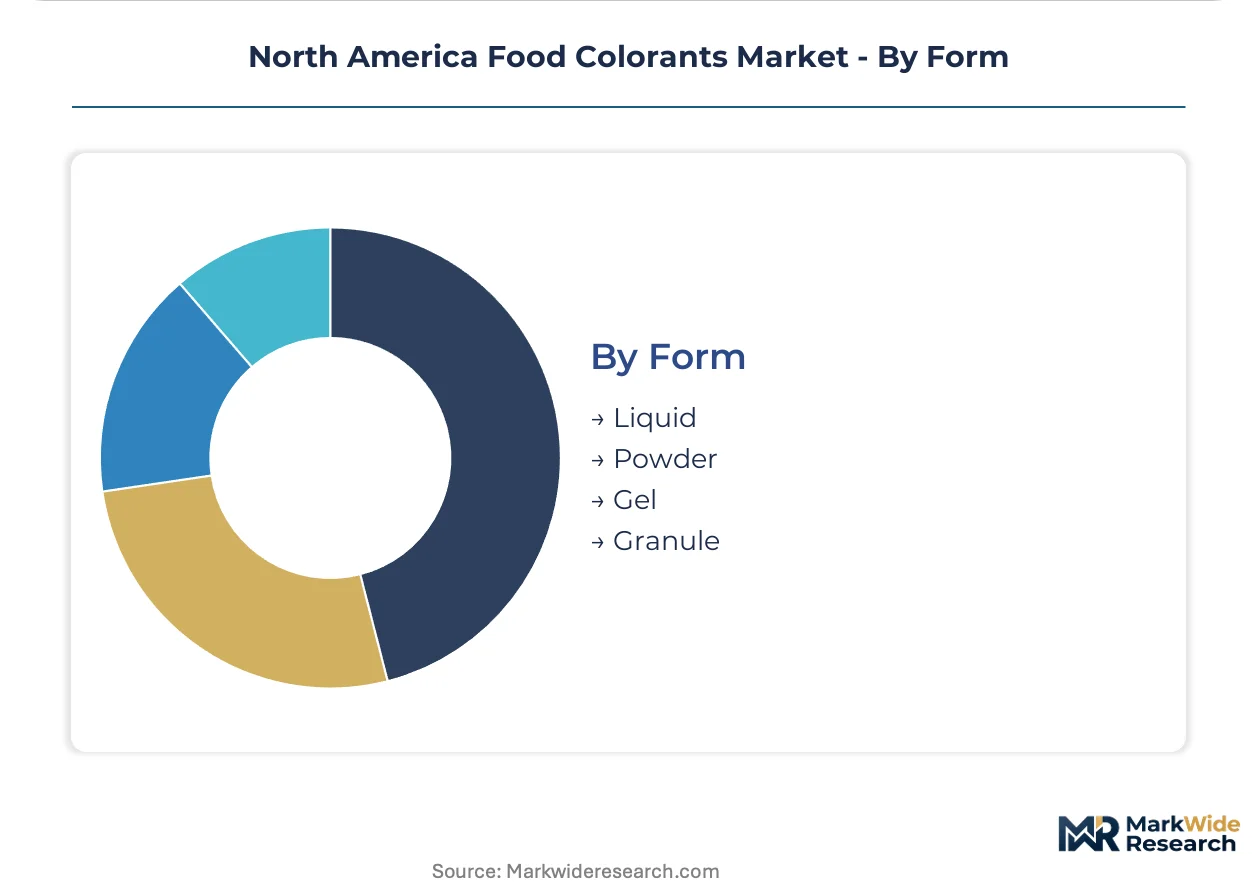
Form:
Manufacturing equipment configuration and dosing precision requirements lock in format preferences by end-use scale.
- Liquid:Pump-dispersed concentrates optimize beverage and sauce production lines with automated dosing systems. High-volume Midwest beverage plants specify liquid formats for continuous processing efficiency.
- Powder:Dry-mix applications in bakery and confectionery favor spray-dried pigments for extended shelf stability and reduced transportation costs. Powder dominates procurement for small-to-mid scale manufacturers.
- Gel:Viscous suspensions suit artisan and specialty producers requiring manual color adjustment. Limited industrial penetration outside decorative icing and fondant applications.
- Granule:Free-flowing agglomerated pigments address dust-control and dispersion challenges in large-scale dry blending. Snack seasoning and instant beverage mix manufacturers specify granule formats for worker safety compliance.
Industrial scale favors Liquid; Powder retains the broadest cross-segment presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in the U.S. Midwest and California generate the bulk of North American food colorant consumption, while Canada and Mexico present divergent regulatory and demand profiles. Cross-border formulation complexity shapes supplier strategies across all three markets.
United States
Beverage manufacturers in Texas and Arizona drive spirulina phycocyanin demand for sports nutrition applications. FDA color additive regulations under 21 CFR 73 and 74 mandate batch certification requirements that complicate multi-product portfolios. The Central Valley and Los Angeles basin concentrate plant-based meat and dairy alternative production, locking in demand for heat-stable natural reds and browning systems.
Canada
Health Canada's 2023 Food and Drug Regulations updates tightened permissible synthetic color lists and enhanced documentation requirements. Toronto and Montreal food manufacturing corridors accelerate natural colorant R&D investment to meet cross-border compliance burdens. Canadian producers face 18-24 month USDA National Organic Program validation cycles that delay clean-label product launches.
Mexico
Confectionery manufacturers in Mexico City and Guadalajara retain azo dye dependence for hard candy and gummy applications where natural alternatives lack spectral purity. Mexican regulators enforce alignment with FDA frameworks for export-oriented production while maintaining domestic formulation flexibility. Northern border states concentrate maquiladora operations that dual-track synthetic and natural colorant inventories.
California
State-level ingredient disclosure laws extend beyond federal minimums, creating first-mover advantage for suppliers with pre-validated clean-label portfolios. San Francisco and Los Angeles clean-label brands source pigments through embedded formulation scientists rather than traditional distributors. Sacramento Valley crop production supplies beet anthocyanins to regional natural colorant extractors.
Texas
Phycocyanin extraction facilities in Texas capture unmet demand for heat-stable blue pigments in functional beverages and sports nutrition. Dallas-Fort Worth distribution hubs serve as consolidation points for liquid colorant shipments to Midwest beverage plants. State regulatory frameworks align with FDA standards while offering faster permitting for novel extraction technologies.
North America Food Colorants Market Competitive Landscape
Capital-heavy producers compete with asset-light formulation specialists across the North American food colorant landscape. Integrated ingredient systems providers bundle color with flavor and texture capabilities, while standalone pigment suppliers defend volume positions in confectionery and snack segments. Three archetypes dominate: technical service platforms embedding scientists into client NPD cycles, integrated beverage ingredient systems bundling multiple functionalities, and specialized extraction houses scaling novel plant-derived pigments. Consolidation pressures concentrate around M&A targeting natural color extraction capabilities and strategic partnerships locking multi-year supply agreements with California and Midwest beverage clusters.
Among Swiss and Danish ingredient specialists, Givaudan SA and Chr. Hansen occupy positions exemplifying premium natural color portfolio extension through specialized extraction capabilities. Sensient Technologies Corporation represents the technical service platform archetype, embedding color science directly into client product development cycles rather than transactional pigment sales. Dohler Group anchors the integrated systems tier, bundling color with flavor and texture for beverage producers consolidating supplier relationships. These three companies illustrate the strategic divergence between formulation-centric and extraction-centric competitive vectors.
| Leading Market Players |
|---|
| Givaudan SA |
| Dohler Group |
| Sensient Technologies Corporation |
| Naturex SA |
| Oterra A/S |
| Chr. Hansen |
| BASF SE |
| DSM |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Beet anthocyanin spot prices in the U.S. Midwest and Pacific Northwest cascade through three distinct procurement tiers, with organic-certified extracts commanding substantial premiums over conventional natural alternatives and synthetic azo dyes anchoring the economy segment.
Pricing Analysis
Margin tightening in the natural colorant tier reflects beet and spirulina crop yield volatility coupled with 18-24 month organic certification cycles. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic pigments from conventional natural extracts and FD&C-certified synthetics. Pricing pressure intensifies in the mid-tier as beverage manufacturers consolidate supplier relationships around bundled color-flavor-texture platforms. Confectionery producers in Mexico and the U.S. Southeast exhibit the highest price sensitivity, while California clean-label brands absorb premiums for pre-validated clean-label portfolios.
Supply Chain Analysis
Direct-to-beverage-manufacturer channels handle hyperscale demand from Texas and Arizona functional drink producers, displacing traditional distributor intermediaries. Raw material extraction concentrates in the U.S. Midwest for beet anthocyanins, California for turmeric and spirulina cultivation, and Texas for phycocyanin processing facilities. Supply chain risk centers on irrigation-dependent crop yields in drought-prone growing regions that destabilize natural pigment availability. Distribution runs through Dallas-Fort Worth liquid colorant consolidation hubs serving Midwest beverage manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technologies are displacing legacy stabilization methods, collapsing the performance gap that previously sustained synthetic azo dye dominance in heat-intensive applications.
For Market Incumbents: Hedge synthetic colorant volume exposure by accelerating backward integration into spirulina and beet extraction capabilities in Texas and Arizona. Lock multi-year supply agreements with California and Midwest beverage clusters before subscription-based formulation services commoditize standalone pigment sales. Prioritize encapsulation R&D partnerships addressing turmeric heat-degradation in retort processing. For New Entrants and Emerging Players: Launch via embedded technical service platforms targeting mid-sized plant-based meat and dairy alternatives in the Central Valley. Capture white-space in organic-certified color additives where 18-24 month validation cycles constrain incumbent responsiveness. Prioritize direct partnerships with New York clean-label brands facing state-level disclosure mandates beyond federal minimums. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized extraction houses with captive spirulina or beet supply agreements in the U.S. Southwest. Long-term viability hinges on fermentation-derived pigment platforms that bypass agricultural yield volatility. Monitor Health Canada regulatory updates as inflection signals for cross-border reformulation spending waves.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Enables turmeric and beet heat stability through retort and UHT processing for sauce manufacturers. |
| Spirulina Extraction Scale-Up | Captures unmet demand for heat-stable blue pigments in Texas and Arizona sports nutrition corridors. |
| Subscription Formulation Services | Replaces transactional pigment sales with recurring revenue from embedded color science partnerships. |
| Organic Certification Investment | Unlocks 40-60% price premiums through USDA National Organic Program validation for clean-label portfolios. |
| Integrated Beverage Systems Bundling | Consolidates supplier relationships by combining color with flavor and texture for speed-to-market. |
Research Methodology
Trade databases, FDA color additive certification records, and agricultural commodity price indices formed the secondary backbone, cross-referenced with primary interviews involving beverage formulation scientists, natural colorant extraction facility managers, and procurement leads at Midwest food manufacturing clusters. Bottom-up and top-down triangulation validated segment-level demand estimates against cross-border import-export flows and Health Canada regulatory filing trends.
Bottom-up modeling built volume projections from individual application segments including beverages, confectionery, dairy, and plant-based alternatives, while top-down analysis anchored aggregate market size against macroeconomic food processing indicators across the projection horizon. Segmentation dimensions encompassed product technology, end-use specification, processing intensity, and geographic manufacturing cluster. CAGRs were derived from fitted growth curves incorporating regulatory compression timelines and natural colorant substitution elasticity estimates.
The model assumes a particular technology adoption path; alternative pathways for fermentation-derived pigments would alter the outlook if biomanufacturing scale-up outpaces agricultural extraction expansion. Forecasts reflect base-case assumptions regarding Health Canada enforcement consistency and FDA batch certification continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Vanilla Extract Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Citrus Oil Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Global Anthocyanin Market
Flavorings and Food Additives
Chicory Extract Market