
 Fractionated Lecithin Market | 2026-2036
Fractionated Lecithin Market Size, Share, and Industry Trends Forecast 2026-2036
Fractionated Lecithin Market Analysis
The fractionated lecithin supply base is restructuring around a widening gap between pharmaceutical-grade phosphatidylcholine concentrates and commodity de-oiled lecithin powders. Cargill, Incorporated leverages its integrated oilseed processing network to secure raw material flows for high-purity fractions. Archer Daniels Midland Company sustains global distribution scale across food and feed channels. Lipoid GmbH differentiates through synthetic and natural phospholipid specialization for injectable-grade applications.
Fractionated lecithin denotes soy, sunflower, or egg-derived phospholipid mixtures that have been separated by solvent extraction, chromatography, or membrane filtration to enrich specific fractions such as phosphatidylcholine above 70% purity, serving primarily as emulsifiers, liposomal carriers, and surfactants in pharmaceutical and nutraceutical formulations. Liquid lecithin dominates volume flows into industrial food processing where cost-efficient emulsification remains paramount, while powder lecithin captures margin pools in dietary supplements and sports nutrition where dosing precision and shelf stability command premium positioning. The pharmaceutical end-user segment channels the highest value per kilogram as liposomal encapsulation technology advances for bioavailability enhancement.
FDA GRAS determinations and EMA pharmaceutical excipient guidelines jointly elevate purity thresholds for fractionated lecithin entering drug formulations, while REACH registration requirements in Europe constrain supply access for non-compliant Asian producers. ISO 10993 biocompatibility standards and USP-NF monographs further segment market access between food-grade and pharmaceutical-grade suppliers. Stakeholders must monitor evolving pharmacopeial specifications and regional purity certifications to align capacity investments with the most defensible margin tiers.
Market Dynamics
Pharmaceutical-grade phosphatidylcholine purity thresholds are bifurcating the fractionated lecithin supply base into defensible premium tiers and commoditized bulk streams, forcing capacity holders to choose between liposomal drug delivery specialization and food emulsification scale.
Growth Catalysts
- Liposomal encapsulation technology:Injectable-grade phospholipid demand from oncology and vaccine formulators in Germany and the United States is pulling high-purity phosphatidylcholine concentrates into chronic supply deficit.
- FDA GRAS status expansion:Broader self-affirmation pathways for novel lecithin fractions are accelerating nutraceutical formulation cycles in North American dietary supplement channels.
- India:CDSCO pharmaceutical excipient harmonization with USP-NF standards is unlocking export qualification for domestic fractionators targeting regulated drug markets.
Market Restraints
- Non-GMO sunflower seed supply volatility:Ukrainian and Black Sea sourcing disruptions are compressing margin predictability for allergen-free lecithin fractions.
- REACH registration cost barriers:ECHA full substance dossier requirements for phospholipid mixtures above one tonne annually are excluding smaller Asian processors from European pharmaceutical supply chains.
- Synthetic phospholipid substitution:Hydrogenated phosphatidylcholine from chemical synthesis routes is displacing natural-derived fractions in stability-critical parenteral applications.
Strategic Opportunities
- Brazil:ANVISA pharmaceutical excipient prequalification pathways remain underpenetrated by established fractionators, creating first-mover positioning for GMP-certified entrants.
- Cell-cultured meat:Phospholipid emulsifier demand from alternative protein startups is emerging as a volume anchor outside traditional food and pharma verticals.
- Green solvent fractionation:Supercritical CO2 extraction convergence with membrane filtration is enabling organic-certified phosphatidylcholine production for clean-label nutraceutical positioning.
Industry Challenges
- Phospholipid analytical chemist scarcity:Specialized HPLC and NMR method expertise for phosphatidylcholine purity quantification is concentrating in German and Swiss contract laboratories, extending pharmaceutical qualification timelines.
- Multi-compendial certification complexity:Simultaneous USP-NF, Ph.Eur., and JP compliance for injectable-grade material is requiring 18-24 month validation cycles that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fractionated Lecithin Market |
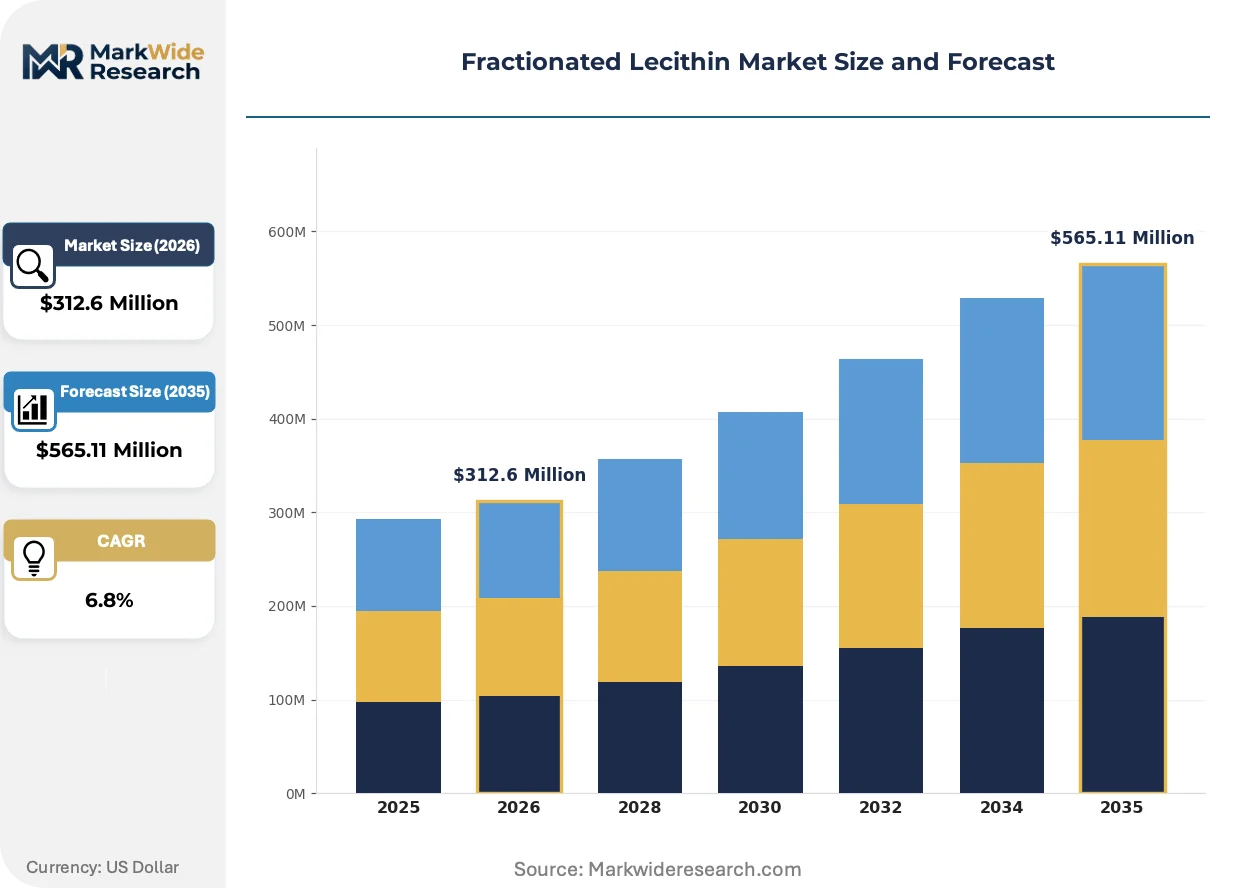
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Lecithin, Powder Lecithin, Granular Lecithin, Emulsified Lecithin End User: Food Industry, Pharmaceuticals, Cosmetics, Animal Feed Application: Baking, Dressing, Confectionery, Dietary Supplements Distribution Channel: Online Sales, Retail Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Bunge Limited, Lecico GmbH, DuPont de Nemours Inc., Stern-Wywiol Gruppe, Lasenor Emul, Austrade Inc., Lipoid GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fractionated Lecithin Market Emerging Trajectories
Membrane filtration advances and green solvent systems are redrawing the technical frontier between artisanal batch phospholipid separation and continuous pharmaceutical-grade production, compressing legacy extraction economics.
Enzymatic phospholipid modification using phospholipase A2 and transphosphatidylation is decentralizing high-purity phosphatidylcholine production away from centralized solvent extraction facilities. Mid-scale nutraceutical compounders in the Netherlands and California are adopting immobilized enzyme reactors for in-house fraction enrichment. This distributed manufacturing model is compressing toll-processing margins for traditional solvent-based fractionators.
EMA pharmaceutical excipient guidelines revision tightening elemental impurity thresholds is forcing phospholipid suppliers to implement ICP-MS trace metal monitoring. European formulators are now requiring certificate of analysis expansion for arsenic, cadmium, and lead at ppb levels. German and Italian injectable manufacturers are consolidating supplier panels to those with in-house elemental testing capability.
Direct-to-formulator digital procurement platforms are fragmenting traditional distributor control over phospholipid specification data. Specialty chemical marketplaces in North America are enabling bench-scale buyers to access pharmaceutical-grade certificates and regulatory files without channel intermediaries. This disintermediation is most visible among Boston and San Francisco biotech startups sourcing liposomal excipients for IND-enabling studies.
Fractionated Lecithin Market Segmentation
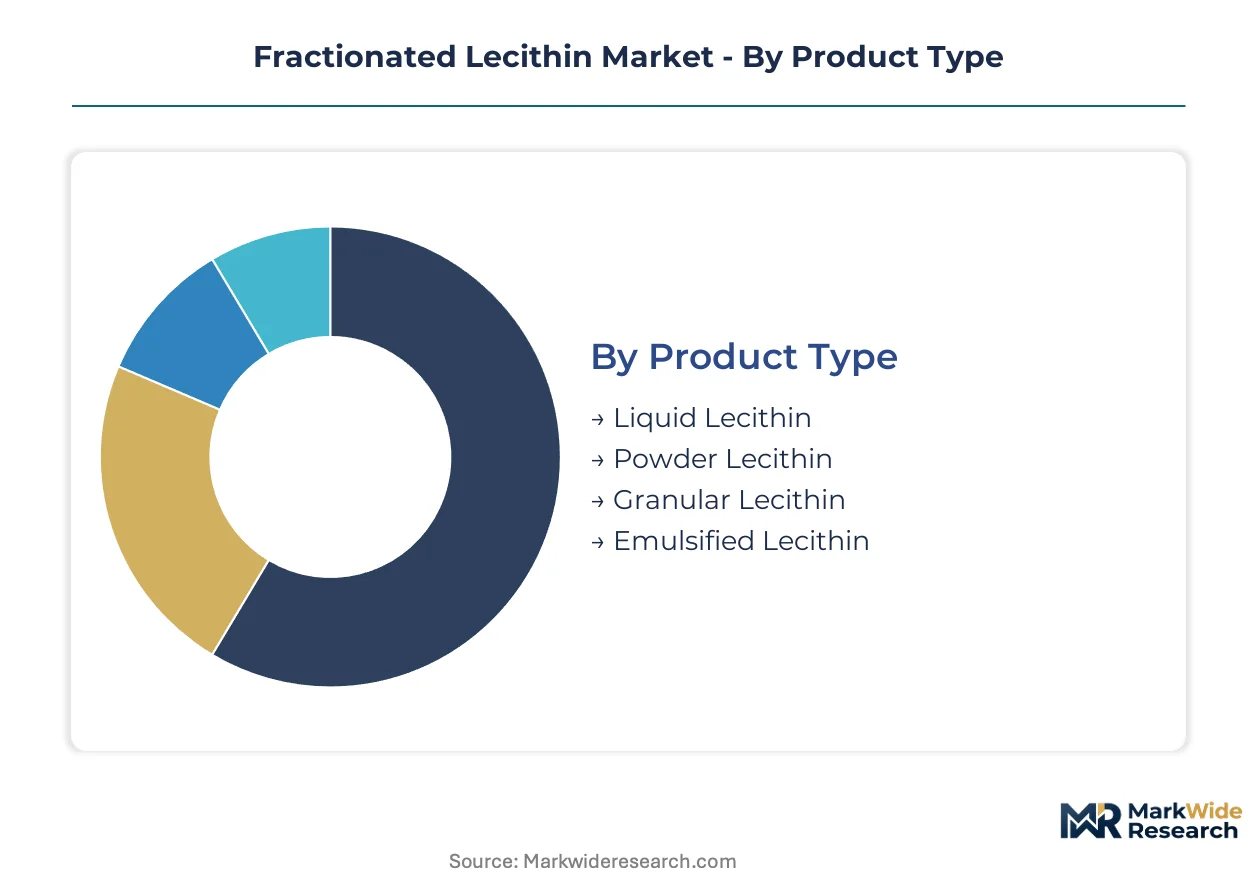
Fractionated lecithin segmentation reflects divergent purity requirements across regulatory jurisdictions. Pharmaceutical-grade specifications in Germany and the United States impose certification burdens that food-grade channels avoid entirely.
Product Type:
FDA GRAS self-affirmation applies universally across all product types, while EMA pharmaceutical excipient guidelines and USP-NF monographs constrain only high-purity fractions destined for injectable applications.
- Liquid Lecithin:Standardized phospholipid mixtures at 60-70% phosphatidylcholine concentration serve industrial food processing where emulsification efficiency outweighs purity premiums. Demand concentrates in German bakery and confectionery manufacturing, constrained by batch-to-batch viscosity inconsistency that complicates automated dosing systems.
- Powder Lecithin:Spray-dried de-oiled fractions achieve 95%+ dry matter content for dietary supplement encapsulation and sports nutrition premixes. United States contract manufacturers favor this format for precise tablet compression and extended shelf stability in multivitamin formulations.
- Granular Lecithin:Agglomerated particles reduce dusting during high-speed blending operations in animal feed mills.
- Emulsified Lecithin:Pre-hydrated dispersions eliminate hydration steps for mayonnaise and dressing producers seeking process simplification.
Liquid lecithin sits at the top of the volume ranking, with powder lecithin climbing the fastest.
End User:
Cost tiers separate commodity food applications from pharmaceutical-grade contracts where analytical validation expenses dominate landed costs.
- Pharmaceuticals:Injectable-grade phosphatidylcholine concentrates above 90% purity command qualification protocols spanning 18-24 months for USP-NF, Ph.Eur., and JP compliance. Liposomal drug delivery formulators in Boston and Basel absorb these delays as unavoidable entry costs for oncology and vaccine pipelines.
- Food Industry:Standardized liquid and de-oiled powders meet FDA GRAS and EFSA food additive specifications without batch-specific elemental impurity testing. German chocolate manufacturers and United States snack food processors drive volume through cost-optimized emulsification.
- Cosmetics:Phospholipid liposomes for topical delivery require cosmetic-grade purity with abbreviated toxicological dossiers compared to parenteral standards.
- Animal Feed:Pellet-binding applications tolerate lower phosphatidylcholine content, sourcing residual fractions from edible oil refining.
Food Industry maintains the largest volume position, while Pharmaceuticals expands most quickly.
Application:
Customer type fragmentation separates industrial compounders from precision-dosing nutraceutical finished goods manufacturers.
- Dietary Supplements:Softgel encapsulation and powder premixes demand de-oiled lecithin with guaranteed phosphatidylcholine content for label claim substantiation. United States supplement brands and Netherlands compounders specify non-GMO sunflower origin to satisfy clean-label positioning.
- Baking:Dough conditioning and crumb softening applications utilize liquid lecithin for cost-efficient gluten network modification.
- Confectionery:Viscosity control in chocolate manufacturing relies on lecithin fractions optimized for fat crystal interaction.
- Dressing:Oil-in-water emulsion stability for mayonnaise and sauces employs pre-hydrated or standard liquid grades.
Baking holds the volume lead, with Dietary Supplements gaining share fastest.
Distribution Channel:
Supply concentration among wholesale distributors with analytical capabilities determines market access for pharmaceutical-grade material.
- Wholesale Distributors:Specialty chemical distributors in Germany and the United States maintain certificate of analysis archives and regulatory file libraries that pharmaceutical formulators require for excipient qualification. Their technical service teams bridge supplier quality systems with customer specification demands.
- Direct Sales:Large-volume food processors and multinational pharmaceutical companies negotiate long-term supply agreements with fractionators, bypassing distributor margins for predictable raw material flows.
- Online Sales:Digital procurement platforms serve bench-scale buyers and nutraceutical startups with small-batch pharmaceutical-grade access.
- Retail Stores:Consumer-packaged lecithin supplements reach end-users through health food and pharmacy channels.
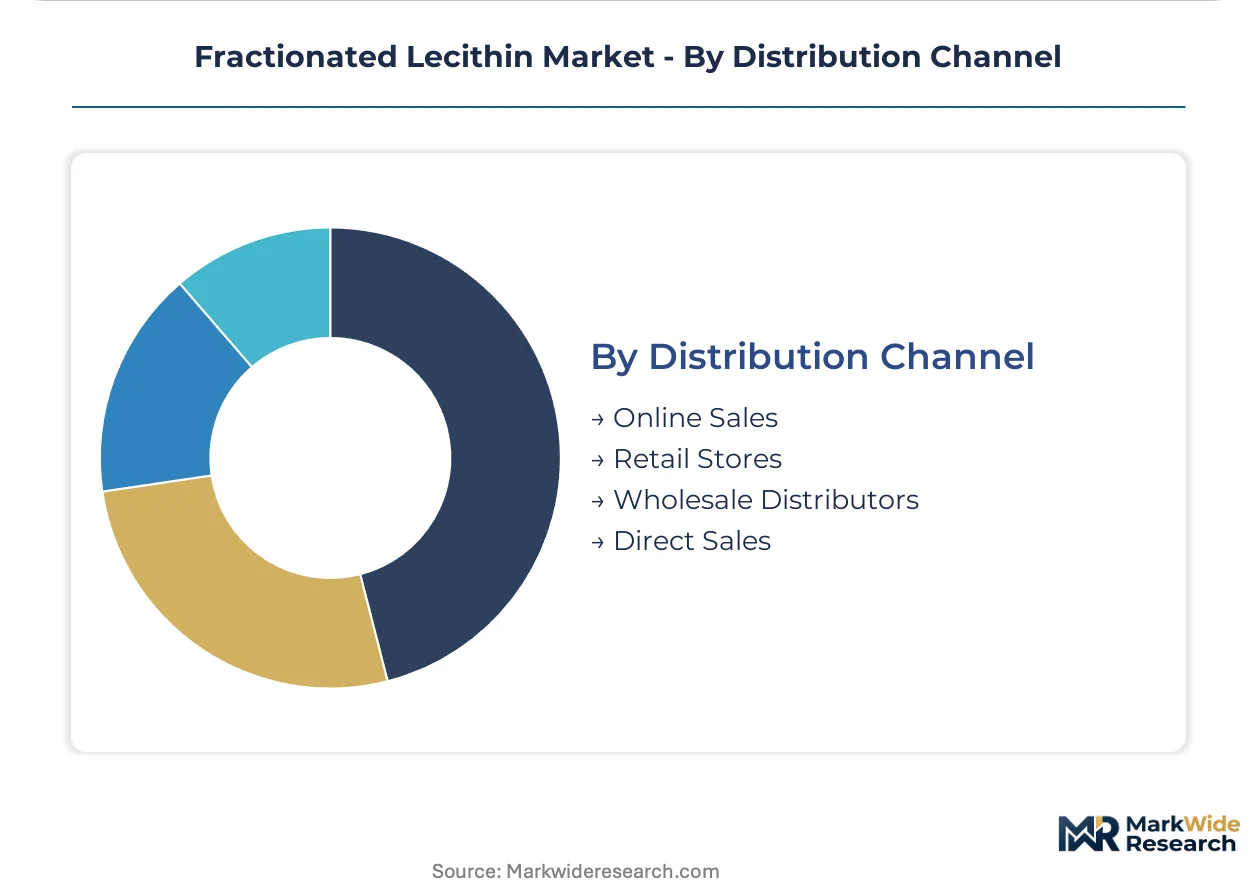
Wholesale Distributors dominates volume flows, with Direct Sales showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized phospholipid chemists and analytical methodologists cluster in Basel, Boston, and Hyderabad, anchoring regional capacity for pharmaceutical-grade fractionation. Their concentration determines where liposomal drug delivery innovation translates into commercial manufacturing.
United States
FDA GRAS self-affirmation pathways accelerate nutraceutical formulation cycles, while CDER pharmaceutical excipient guidelines enforce USP-NF monograph compliance for injectable-grade material. Greater Boston biotech startups and San Francisco Bay Area gene therapy formulators pull high-purity phosphatidylcholine concentrates into chronic supply deficit.
Germany
EMA pharmaceutical excipient guidelines and REACH registration requirements jointly elevate purity thresholds for drug formulation entry. The Rhine-Main cluster around Frankfurt and the Upper Bavaria pharmaceutical corridor host GMP-certified fractionators serving oncology liposome developers in Basel and Berlin.
India
CDSCO pharmaceutical excipient harmonization with USP-NF standards unlocks export qualification for domestic fractionators targeting regulated drug markets. Hyderabad and Ahmedabad house specialized phospholipid processors building multi-compendial certification capability for parenteral supply chains.
Switzerland
Swissmedic pharmaceutical manufacturing guidelines and proximity to Basel's injectable drug cluster position the country as a qualification hub for European liposomal applications. The Basel-Landschaft canton concentrates contract manufacturing organizations demanding elemental impurity testing at ppb thresholds.
Brazil
ANVISA pharmaceutical excipient prequalification pathways remain underpenetrated by established fractionators, creating first-mover positioning for GMP-certified entrants. São Paulo state's nutraceutical manufacturing base drives food-grade demand while pharmaceutical qualification lags regional peers.
Fractionated Lecithin Market Vendor Landscape
Capital-heavy integrated oilseed processors compete with asset-light phospholipid specialists for control of premium pharmaceutical-grade streams. The supply base concentrates among three tiers: agricultural commodity houses with captive crushing capacity, dedicated phospholipid fractionators with chromatographic purification expertise, and enzyme-based modification startups decentralizing production. Dominant competitive moves include backward integration into non-GMO seed sourcing and multi-compendial certification investments spanning 18-24 month validation cycles.
Among integrated agricultural processors, Cargill, Incorporated and Archer Daniels Midland Company exemplify the scale-driven archetype leveraging global oilseed networks. Lipoid GmbH occupies the specialist tier, representing pharmaceutical-grade phospholipid purification expertise for injectable applications. These three anchors illustrate the structural divergence between commodity emulsification scale and liposomal drug delivery specialization reshaping competitive positioning.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Bunge Limited |
| Lecico GmbH |
| DuPont de Nemours Inc. |
| Stern-Wywiol Gruppe |
| Lasenor Emul |
| Austrade Inc. |
| Lipoid GmbH |
| Others |
Supply Flow & Price Mechanics
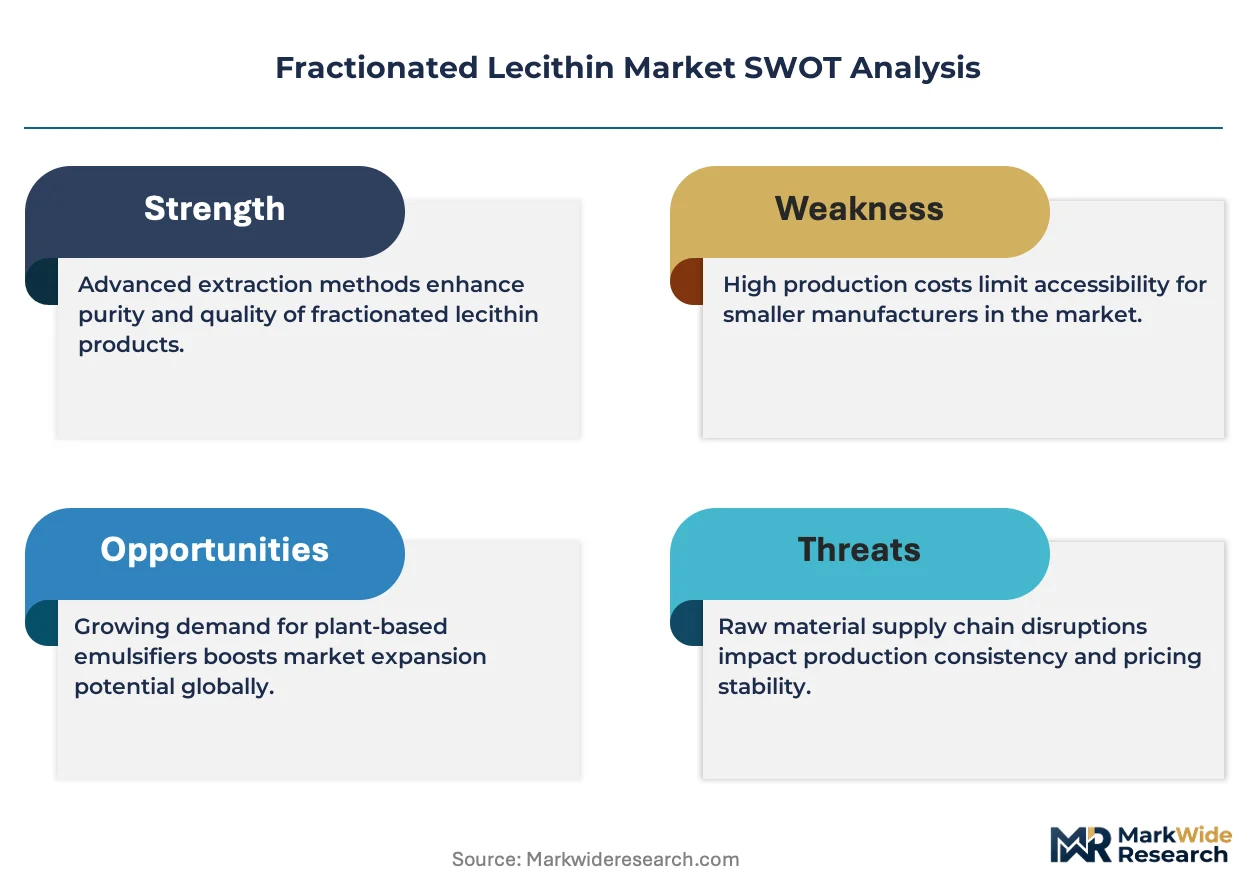
REACH registration mandates gate qualified supply access for European pharmaceutical-grade material while simultaneously compressing margin pools for non-compliant processors. This regulatory filter bifurcates pricing power between certified fractionators commanding premium positioning and commodity suppliers trapped in spot-market volatility.
Pricing Analysis
Service bundling separates pharmaceutical-grade contracts from commodity transactions. Pharmaceutical formulators in Germany absorb bundled analytical validation and regulatory file preparation into landed costs, while food processors in the United States negotiate unbundled spot pricing for standard liquid grades. Price differentiation hinges on USP-NF certification tier and volume commitment scale. Pricing pressure stems from synthetic phospholipid substitution in parenteral applications. Animal feed compounders exhibit highest price sensitivity; oncology liposome developers show lowest.
Supply Chain Analysis
Freight cost volatility from Black Sea sunflower seed corridors is compressing margin predictability for allergen-free lecithin fractions. Supply concentrates in Germany, the United States, and India as specialized fractionation capacity expands. Raw material flows draw from Ukrainian non-GMO sunflower, Brazilian soy crushing, and Indian domestic oilseed processing. Single-source vulnerability runs through Black Sea logistics chokepoints. Distribution runs through wholesale distributors with analytical capability in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA pharmaceutical excipient guideline revisions tighten elemental impurity thresholds and pull capital toward certified capacity.
For Market Incumbents: To counter synthetic phospholipid displacement in parenteral applications, deepen backward integration into non-GMO seed sourcing in Ukraine and Brazil. Prioritize multi-compendial certification investments spanning USP-NF, Ph.Eur., and JP compliance to defend premium-tier positioning. For New Entrants and Emerging Players: Begin with ANVISA pharmaceutical excipient prequalification in Brazil, the most underpenetrated regulated market among established fractionators. Target cell-cultured meat phospholipid demand as a volume anchor outside traditional verticals. Deploy green solvent fractionation capability as a clean-label differentiation angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Indian fractionators building CDSCO harmonized export capability. Long-term viability favors asset-light enzyme-based modification specialists over legacy solvent extraction facilities. Watch EMA elemental impurity threshold enforcement as the inflection signal for supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-compendial Certification Investment | USP-NF, Ph.Eur., and JP compliance unlocks access to Basel and Boston oncology formulators. |
| Backward Integration into Non-GMO Seed Sourcing | Ukrainian and Brazilian captive supply secures allergen-free raw material flows against Black Sea volatility. |
| Green Solvent Fractionation Scale-Up | Supercritical CO2 extraction enables organic-certified positioning for Netherlands nutraceutical compounders. |
| Enzymatic Phospholipid Modification Adoption | Immobilized phospholipase A2 reactors decentralize production and compress toll-processing margins. |
| Direct-to-Formulator Digital Platform Launch | Bypassing distributor control fragments specification data access for Boston biotech startups. |
Methodological Framework
Bottom-up pharmaceutical and nutraceutical formulation modeling reconciled against top-down oilseed processing capacity tracking forms the analytical core. Primary interviews with phospholipid procurement managers at German injectable manufacturers, regulatory affairs leads at Indian fractionators, quality directors at United States dietary supplement brands, and technical R&D heads at Netherlands compounders combined with secondary validation from EMA excipient guidelines, USP-NF monographs, FDA GRAS notifications, and customs trade data.
Historical phospholipid price trendlines and capacity utilization patterns anchored projection frameworks across the analysis window. Segmentation dimensions modeled include product type, end-user industry, purity grade tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating liposomal drug delivery pipeline expansion and synthetic substitution rates.
Caveats apply where REACH registration cost escalation or Black Sea logistics disruption could materially shift the outlook. Forecasts reflect assumptions about EMA guideline enforcement timing and CDSCO harmonization progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Liquid Flavors Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Flavored Salt Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Flavor Modulators Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Maple Extracts Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
Global Flavors Market