
 Chocolate Flavoring Compounds Market | 2026-2036
Chocolate Flavoring Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Flavoring Compounds Market Outlook
The EU Green Deal is repositioning procurement priorities across European flavor houses. Givaudan SA leverages its botanical extraction network to secure supply chain resilience for natural cocoa derivatives. Kerry Group plc anchors its competitive stance through integrated flavor systems tailored for clean-label confectionery clients. Firmenich SA differentiates via biotechnology platforms that reduce water intensity in flavor compound production.
Chocolate flavoring compounds comprise concentrated aromatic formulations—typically 0.1% to 5% usage rates—derived from cocoa solids, vanilla oleoresins, and Maillard reaction precursors, designed to impart characteristic chocolate taste and aroma to finished food matrices. Natural extracts command premium positioning as beverage manufacturers reformulate away from synthetic additives. Flavoring pastes capture expanding share in dairy applications where viscosity and suspension stability prove critical. Powdered flavors retain dominance in bakery goods, though margin compression intensifies amid commodity cocoa price volatility.
EFSA purity standards and EU F-Gas Regulation govern solvent recovery systems in extraction facilities, while FDA GRAS determinations shape transatlantic export compliance for American compound manufacturers. REACH chemical registration requirements constrain artificial flavoring portfolios, accelerating R&D redirection toward botanical-identical molecules. Stakeholders must weigh certification investments against the pace of retailer-driven clean-label mandates.
Market Dynamics
REACH chemical registration requirements are forcing European flavor houses to purge artificial molecules from their portfolios and redirect R&D budgets toward botanical-identical extraction methods. This regulatory compression is restructuring supplier capabilities across the entire value chain.
Growth Catalysts
- EU Green Deal procurement mandates:Public sector food procurement specifications now prioritize clean-label natural extracts, accelerating reformulation timelines for institutional bakery and beverage contracts across Germany and France.
- Maillard reaction precursor innovation:Advanced thermal processing technologies enable more authentic cocoa aroma profiles from non-cocoa sources, expanding raw material flexibility for compound manufacturers.
- Belgium:Concentrated artisanal chocolate consumption patterns in Flanders and Wallonia drive premium natural extract demand for heritage confectionery brands seeking protected designation compliance.
Market Restraints
- Commodity cocoa price volatility:Futures market swings in Côte d'Ivoire and Ghana supply corridors compress margins for natural extract producers locked into long-term fixed-price contracts.
- EFSA purity standard compliance costs:Solvent recovery system upgrades required for extraction facilities impose capital burdens that disproportionately affect mid-scale European flavor houses.
- Vanilla oleoresin supply concentration:Madagascar and Indonesian harvest disruptions create single-source dependency risks for natural chocolate flavoring formulations.
Strategic Opportunities
- Precision fermentation platforms:Biotechnology convergence with traditional extraction enables biosynthesis of cocoa-specific pyrazines and lactones without agricultural land use constraints.
- Plant-based dairy expansion:Oat and almond milk manufacturers require specialized chocolate flavoring systems with enhanced emulsion stability, creating formulation service revenue streams.
- EU F-Gas Regulation phase-down:Supercritical CO2 extraction infrastructure investments qualify for green transition financing mechanisms in France and the Netherlands.
Industry Challenges
- Flavor chemist talent scarcity:Shortage of professionals trained in both classical perfumery techniques and modern analytical chemistry limits R&D throughput for botanical-identical molecule programs.
- Clean-label certification timelines:Organic and non-GMO verification processes for natural extract supply chains extend new product introduction cycles by 8-14 months.
- Legacy ERP integration:Batch tracking systems for REACH-compliant artificial flavoring phase-outs require costly middleware development to maintain inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Flavoring Compounds Market |
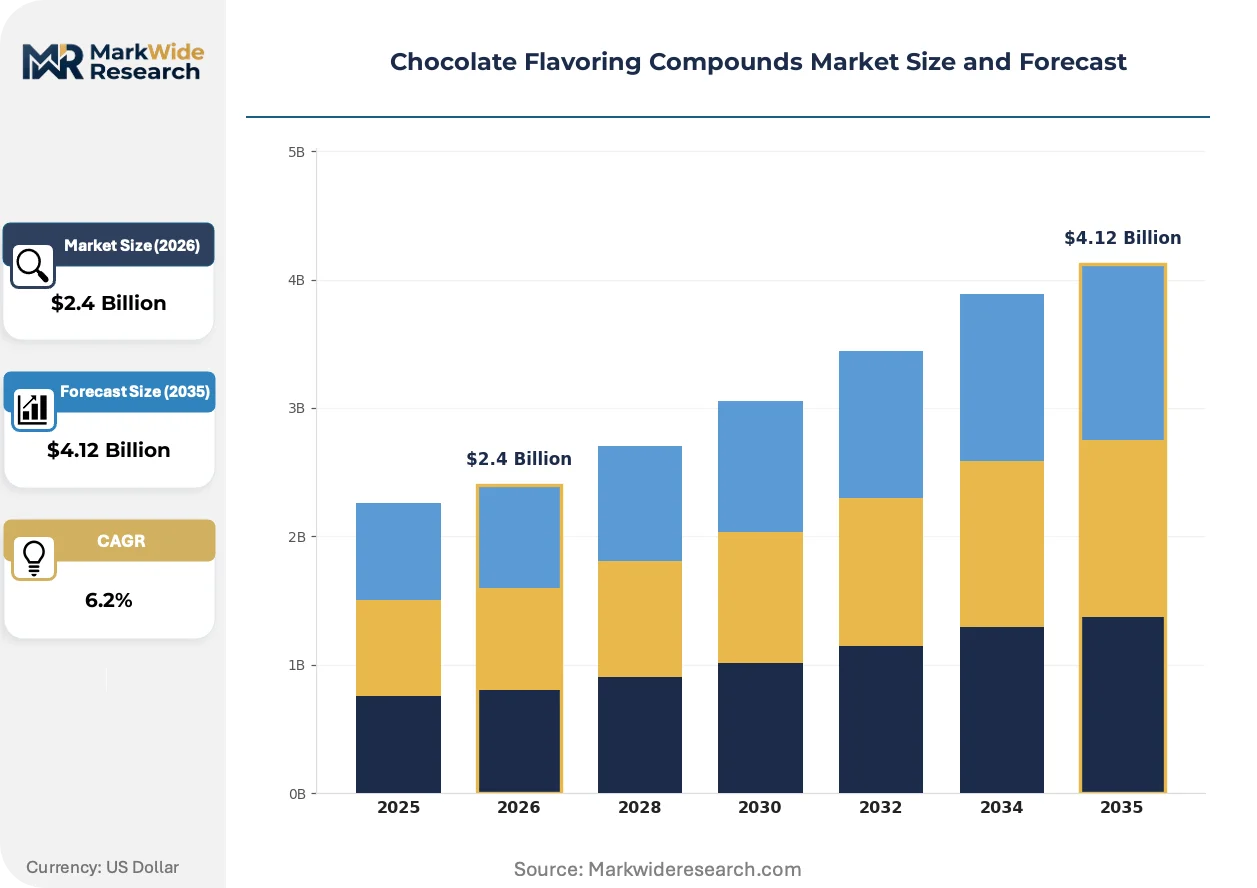
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Artificial Flavorings, Flavoring Pastes, Powdered Flavors Application: Beverages, Confectionery, Dairy Products, Bakery Goods Ingredient Source: Cocoa Beans, Vanilla Beans, Sugar, Others Form: Liquid, Powder, Paste, Granule |
| Companies Covered | Symrise AG, Takasago International Corporation, Givaudan SA, Mane SA, Kerry Group plc, International Flavors & Fragrances Inc. (IFF), Sensient Technologies Corporation, Barry Callebaut, Firmenich SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Flavoring Compounds Market Strategic Shifts
Biotechnology platforms are displacing conventional solvent extraction as the primary innovation vector in chocolate flavoring compound production. This shift is compressing water intensity metrics while expanding molecular precision capabilities.
Supercritical CO2 extraction systems are electrifying natural cocoa derivative processing by eliminating thermal degradation of volatile aromatic compounds. Premium confectionery manufacturers in Switzerland and Belgium are adopting these systems at accelerated procurement cycles. The technology is electrifying competitive differentiation around carbon footprint disclosures and clean-label credibility.
EU F-Gas Regulation mandates are phasing down hydrofluorocarbon use in extraction facility cooling systems. Industrial consequence includes forced capital redeployment toward ammonia-based or transcritical CO2 refrigeration architectures. German and Dutch extraction facilities face the most compressed compliance timelines, with several operators consolidating batch processing to amortize upgrade costs across multiple product lines.
Direct sourcing contracts between flavor houses and cocoa cooperatives are displacing commodity exchange intermediation in procurement patterns. Specialty chocolate manufacturers in France and Italy now require provenance documentation as a standard tender qualification. This behavioral shift is most visible in the premium artisanal segment, where single-origin claims command shelf price premiums and retailer listing priority.
Chocolate Flavoring Compounds Market Segmentation
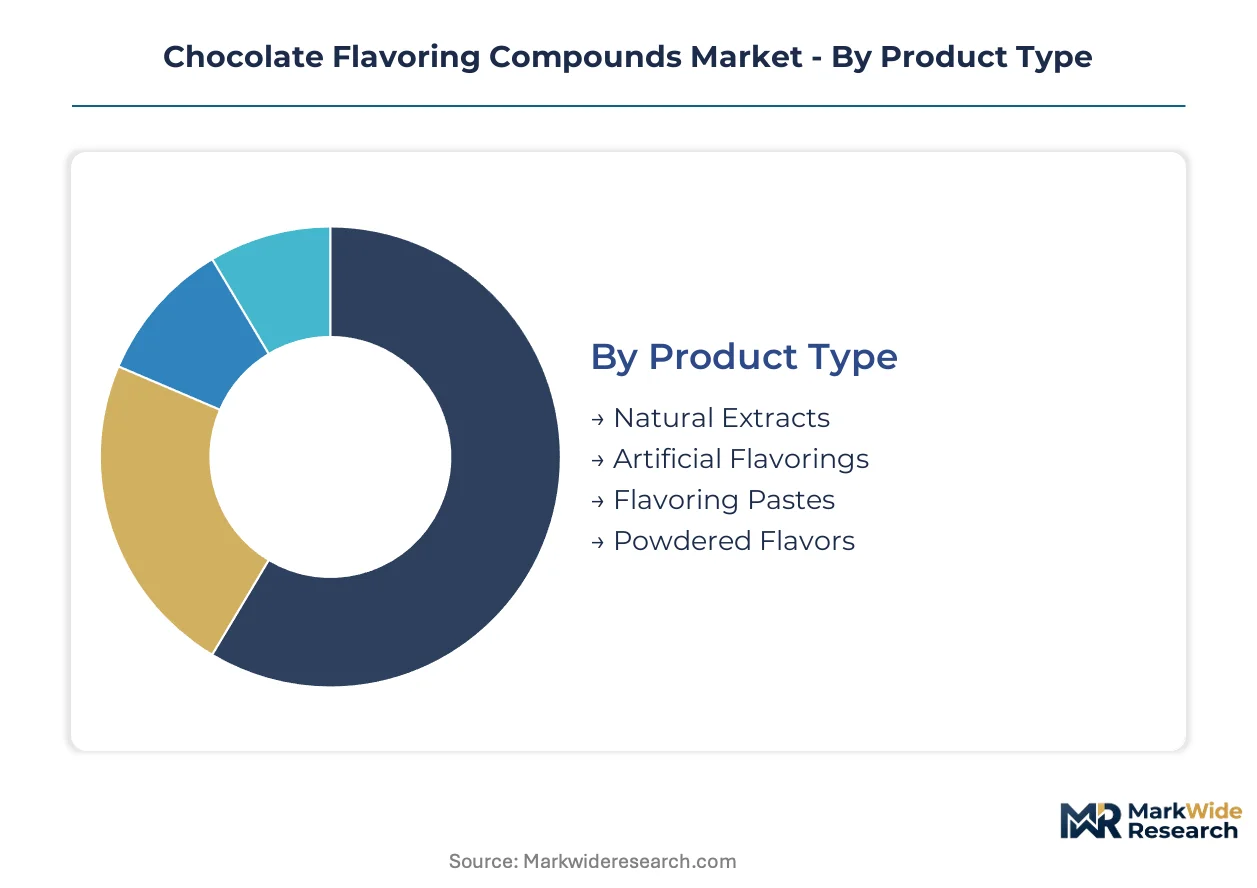
Chocolate flavoring compounds fragment across four distinct classification axes. Product type and application dimensions drive procurement decisions, while ingredient source and form specifications dictate manufacturing process selection and supply chain configuration.
Product Type:
Standardization intensity varies sharply across this category, from commodity-grade synthetic formulations to bespoke botanical extractions requiring provenance documentation.
- Natural Extracts:Concentrated aromatic compounds derived from cocoa solids, vanilla oleoresins, and Maillard precursors through solvent or supercritical CO2 extraction. Premium confectionery manufacturers in Belgium and Switzerland specify these for protected designation heritage products, though Madagascar vanilla supply disruptions constrain formulation flexibility.
- Artificial Flavorings:Synthetic molecules engineered to replicate cocoa pyrazines and lactones at precise dosage rates. REACH registration requirements are forcing European flavor houses to purge these from portfolios, redirecting R&D toward botanical-identical alternatives.
- Flavoring Pastes:Viscous suspensions designed for dairy applications where emulsion stability proves critical. Oat and almond milk manufacturers specify these for plant-based chocolate formulations.
- Powdered Flavors:Spray-dried or encapsulated aromatic matrices dominating bakery goods applications. Commodity cocoa price volatility compresses margins for producers locked into fixed-price contracts.
Most installed capacity flows through Powdered Flavors. Expansion is steepest in Natural Extracts.
Application:
Volume concentration clusters in mass-market bakery and confectionery, while margin capture concentrates in beverage reformulation and premium dairy.
- Beverages:Clean-label mandates from institutional procurement programs in Germany and France accelerate natural extract adoption. Thermal stability requirements differentiate specifications between ready-to-drink and powdered mix applications.
- Confectionery:Artisanal chocolate consumption in Flanders and Wallonia drives premium natural extract demand for heritage brands seeking protected designation compliance.
- Dairy Products:Plant-based milk expansion creates specialized formulation requirements for emulsion-stable chocolate flavoring systems.
- Bakery Goods:Powdered flavors retain dominance though margin compression intensifies amid commodity input price swings.
Confectionery absorbs the largest volume share. Beverage applications are climbing the fastest.
Ingredient Source:
Supply geography directly constrains formulation options, with single-origin dependency risks concentrated in tropical commodity corridors.
- Cocoa Beans:Fermented and dried seeds from Côte d'Ivoire and Ghana supply corridors, processed into cocoa solids, liquor, and butter for extraction. Direct sourcing contracts between flavor houses and cooperatives are displacing commodity exchange intermediation.
- Vanilla Beans:Cured pods from Madagascar and Indonesia providing oleoresins for aromatic complexity. Harvest disruptions create single-source dependency risks for natural chocolate flavoring formulations.
- Sugar:Maillard reaction substrate for thermal processing aroma generation.
- Others:Caramel, malt, and nut-derived precursors for compound flavor layering.
Cocoa Beans anchor the majority of extraction throughput. Vanilla Beans present the steepest supply security challenges.
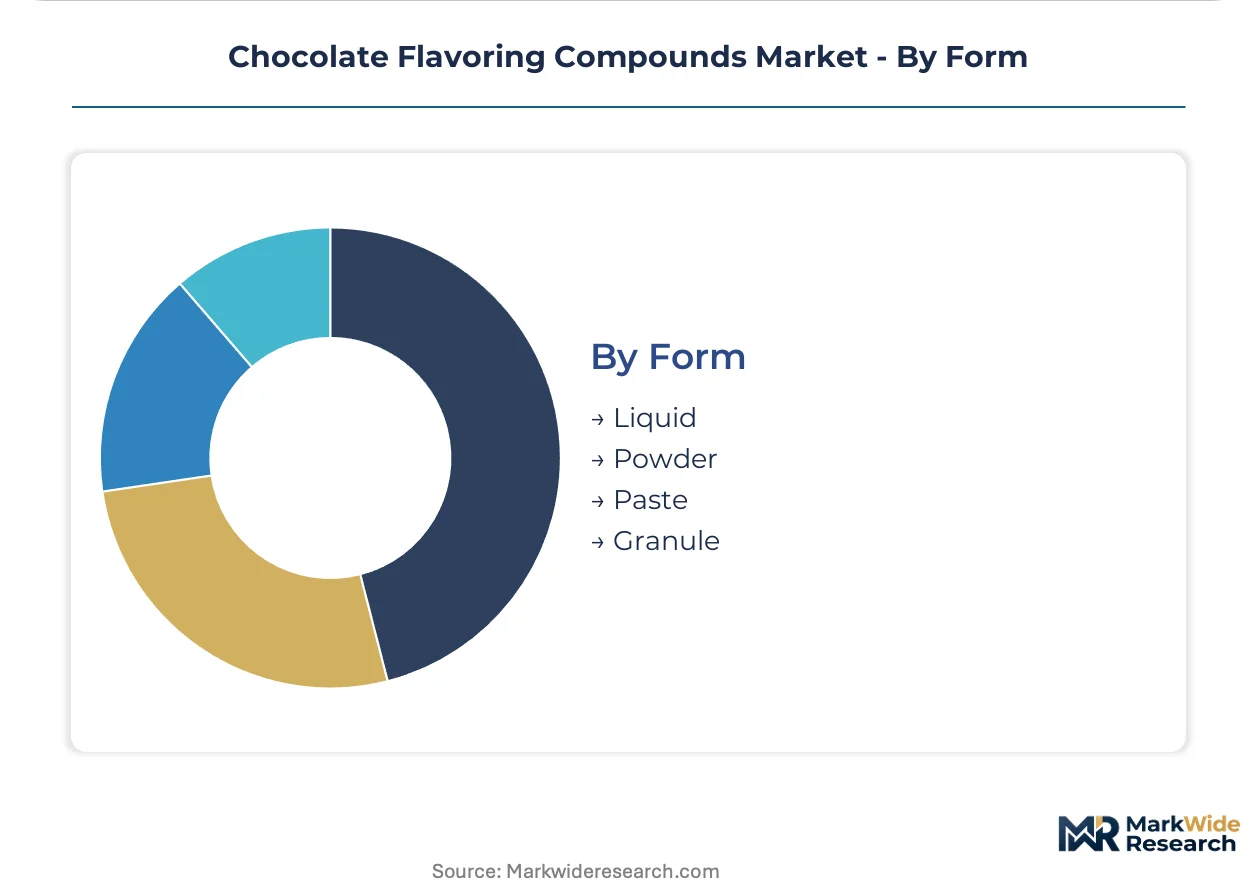
Form:
Physical state selection hinges on downstream process integration, with liquid and powder formats commanding opposing ends of the automation spectrum.
- Liquid:Solvent-based or aqueous solutions for beverage and dairy injection systems. Supercritical CO2 extraction infrastructure investments in France and Netherlands qualify for green transition financing.
- Powder:Encapsulated or spray-dried matrices for dry mix applications. Retains dominance in bakery goods despite thermal degradation risks during high-temperature processing.
- Paste:High-viscosity suspensions for confectionery enrobing and dairy blending operations.
- Granule:Agglomerated formats for controlled-release applications in functional foods.
Powder formats handle the greatest throughput volume. Liquid formats are expanding most quickly on clean-label beverage demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale chocolate flavoring production first achieved commercial scale in Switzerland and Belgium during the late nineteenth century, establishing technical standards that persist across European extraction facilities today.
Germany
Artisanal bakery sectors in Bavaria and North Rhine-Westphalia drive concentrated demand for natural cocoa extracts. EFSA purity standards govern solvent recovery system upgrades across extraction facilities in Hamburg and Cologne. Supercritical CO2 infrastructure investments in the Frankfurt-Rhine-Main cluster qualify for EU Green Deal transition financing mechanisms.
France
Premium confectionery manufacturers in Île-de-France and Provence-Alpes-Côte d'Azur specify provenance-documented natural extracts for heritage brand compliance. EU F-Gas Regulation mandates accelerate refrigeration architecture replacements in extraction plants near Lyon and Marseille. Direct sourcing contracts between flavor houses and Ivorian cooperatives displace commodity exchange intermediation in procurement patterns.
Belgium
Heritage chocolate consumption in Flanders and Wallonia sustains protected designation demand for botanical-identical formulations. REACH chemical registration requirements constrain artificial flavoring portfolios, redirecting R&D budgets toward extraction methods. Brussels-based flavor houses consolidate batch processing to amortize compliance upgrade costs across multiple product lines.
Switzerland
Premium confectionery procurement specifications prioritize carbon footprint disclosures and clean-label credibility in Zurich and Geneva markets. Supercritical CO2 extraction systems eliminate thermal degradation of volatile aromatic compounds in processing facilities near Basel. Swissmedic standards shape transatlantic export compliance frameworks for compound manufacturers.
United States
Beverage reformulation timelines accelerate natural extract adoption as FDA GRAS determinations shape clean-label mandates. Institutional bakery contracts across California and New York Metro prioritize procurement specifications aligned with EU-equivalent standards. Midwest flavor houses develop emulsion-stable systems for plant-based dairy expansion in oat and almond milk categories.
Chocolate Flavoring Compounds Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and extraction technology sophistication. The vendor base clusters around three strategic archetypes: integrated flavor houses with captive botanical networks, biotechnology platforms leveraging precision fermentation, and regional extraction specialists serving heritage confectionery brands. Dominant competitive moves include supercritical CO2 infrastructure investments qualifying for green transition financing, and direct sourcing contract negotiations with cocoa cooperatives displacing commodity intermediation.
Within the integrated flavor house tier, Givaudan SA and Kerry Group plc anchor competitive positioning through supply chain control over natural cocoa derivatives. Firmenich SA occupies a distinct position via biotechnology platforms that reduce water intensity in production processes. Among Swiss and Belgian heritage specialists, Barry Callebaut exemplifies the protected designation compliance archetype serving premium artisanal segments. Symrise AG represents the diversified extraction technology approach spanning solvent-based and supercritical CO2 methods.
| Leading Market Players |
|---|
| Symrise AG |
| Takasago International Corporation |
| Givaudan SA |
| Mane SA |
| Kerry Group plc |
| International Flavors & Fragrances Inc. (IFF) |
| Sensient Technologies Corporation |
| Barry Callebaut |
| Firmenich SA |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap extraction specialists in Belgium and Switzerland anchor premium pricing discipline through multi-generational supplier relationships and protected designation heritage contracts. These ownership structures resist commodity spot-market volatility by locking in provenance-documented cocoa sourcing, creating pricing power that rolls up specialists cannot replicate through financial engineering alone.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates botanical-identical extracts from legacy artificial formulations and commodity synthetics. Price differentiation rests on certification depth—EU organic and protected designation status command 40-60% premiums over conventional grades—and volume scale, with institutional bakery contracts compressing per-unit rates. Cost compression in the standard tier is intensifying because REACH compliance upgrades force artificial flavoring phase-outs. Beverage manufacturers show least price sensitivity, prioritizing clean-label credibility for institutional procurement mandates.
Supply Chain Analysis
EU F-Gas Regulation domestic-content mandates for green transition financing are reshaping sourcing toward French and Dutch supercritical CO2 extraction infrastructure. Geographic supply concentration centers on Côte d'Ivoire and Ghana for fermented cocoa solids, Madagascar for vanilla oleoresins, and Indonesia for secondary aromatic inputs. Single-source vulnerability in Madagascar vanilla harvests threatens formulation flexibility for natural extract portfolios. Distribution runs through integrated flavor houses with captive botanical networks, regional extraction specialists serving heritage brands, and biotechnology platforms displacing conventional solvent methods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU REACH compliance costs and US FDA GRAS determination flexibility, with European flavor houses bearing heavier regulatory capital burdens while American compound manufacturers capture faster clean-label reformulation timelines.
For Market Incumbents: Hedge against artificial flavoring portfolio obsolescence by accelerating supercritical CO2 infrastructure investments in France and the Netherlands, where EU Green Deal transition financing softens capital deployment. Consolidate batch processing across multiple product lines to amortize EFSA-mandated solvent recovery upgrades. Backward integration into direct sourcing contracts with Ivorian cooperatives displaces commodity exchange intermediation and secures provenance documentation for protected designation compliance. For New Entrants and Emerging Players: Capture white-space in plant-based dairy chocolate flavoring systems, where oat and almond milk manufacturers require specialized emulsion-stable formulations absent from incumbent portfolios. Target precision fermentation platforms for biosynthesis of cocoa-specific pyrazines without agricultural land-use constraints. Lead with formulation service revenue models rather than commodity compound sales to bypass entrenched supply relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional extraction specialists with REACH-compliant artificial flavoring legacy assets requiring costly phase-out execution. Long-term viability favors biotechnology platforms with water-intensity reduction capabilities and supercritical CO2 infrastructure qualifying for green transition financing. Watch for Madagascar vanilla supply disruption severity as the inflection signal for natural extract pricing spikes and synthetic substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Infrastructure Investment | Qualifies for EU Green Deal financing in France and Netherlands while eliminating thermal degradation. |
| Direct Sourcing Contract Negotiation | Displaces commodity exchange intermediation between flavor houses and Ivorian cooperatives. |
| Precision Fermentation Platform Development | Enables biosynthesis of cocoa pyrazines without Madagascar vanilla supply dependency risks. |
| REACH-Compliant Artificial Flavoring Phase-Out | Forces R&D redirection toward botanical-identical molecules across European flavor houses. |
| Plant-Based Dairy Formulation Service Launch | Captures oat and almond milk manufacturer demand for emulsion-stable chocolate systems. |
Study Parameters
Coverage spans Western Europe and North America, with primary inputs from each region combining structured interviews with extraction facility technical directors, procurement leads at premium confectionery manufacturers, regulatory affairs specialists at flavor houses, and plant-based dairy formulation scientists. Secondary validation draws from EFSA purity standard filings, EU REACH registration databases, FDA GRAS determination notices, and customs trade data for cocoa derivative flows. Bottom-up capacity modeling and top-down demand triangulation cross-verify volume estimates across the analysis window.
Granularity-level modeling disaggregates volume and value projections by product type—natural extracts, artificial flavorings, flavoring pastes, powdered flavors—application segment, ingredient source geography, and physical form specification. CAGRs derive from segment-specific growth trajectories weighted by installed capacity shares and reformulation timeline acceleration from institutional procurement mandates. Forecast inputs include commodity cocoa futures volatility patterns, Madagascar vanilla harvest yield projections, and biotechnology platform commercialization readiness assessments.
Regulatory enforcement variance, commodity supply corridor disruptions, and precision fermentation scale-up delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding REACH compliance timeline adherence and EU Green Deal financing mechanism continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Naringin Market
Flavorings and Food Additives
Original and Flavored Syrup Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market