
 Mock Meat Market | 2026-2036
Mock Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Mock Meat Market Analytics
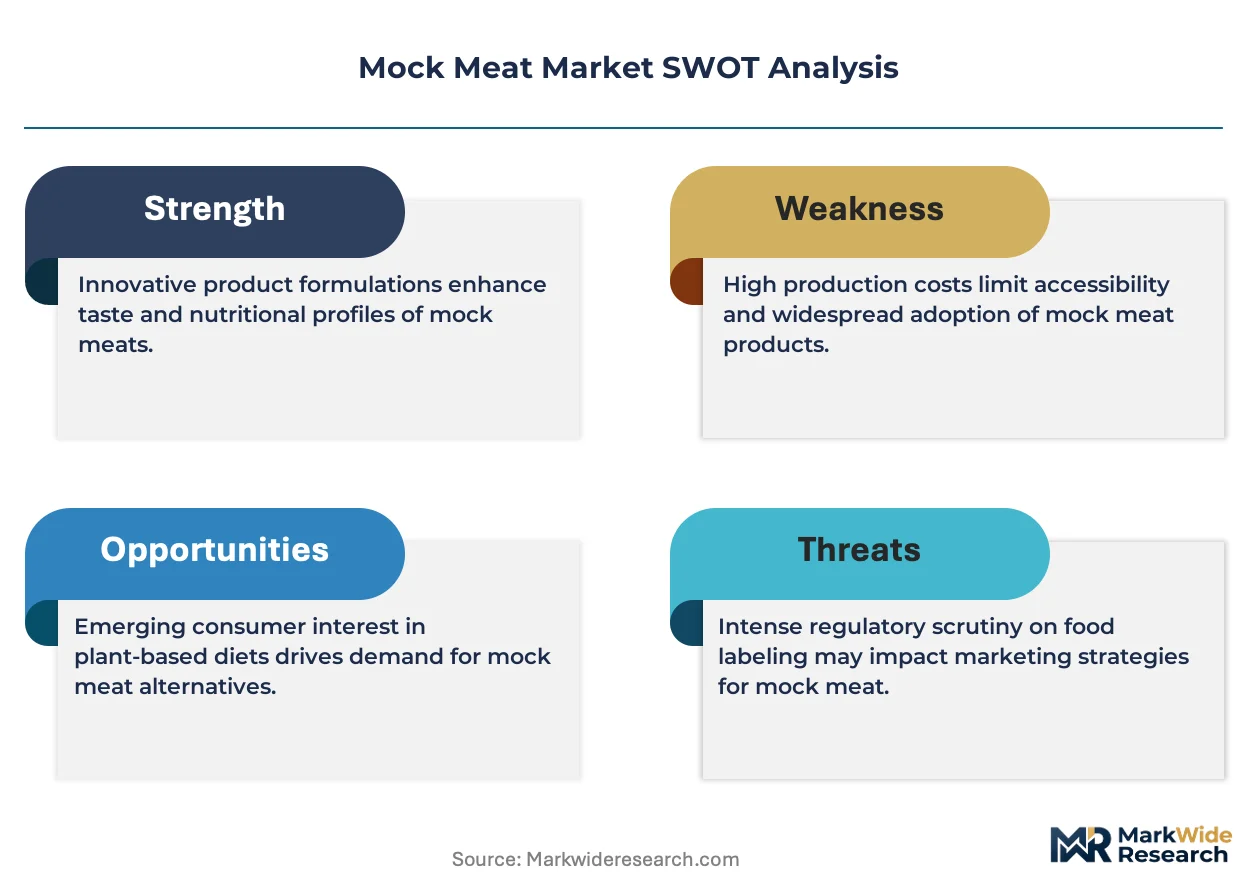
Precision fermentation of heme proteins is tilting product development toward biomimetic texture replication. Beyond Meat leverages extrusion technology to sustain its position in retail fresh-meat cases across the United States. Impossible Foods anchors its supply chain through in-house heme production, while Quorn Foods differentiates via mycoprotein fermentation expertise developed over decades in the United Kingdom.
Mock meat comprises formulated protein products engineered to replicate the sensory properties of conventional animal meat, typically achieving moisture retention above 60 percent and chew profiles measured by Warner-Bratzler shear force. These formulations serve commercial food manufacturing and direct consumer preparation as functional substitutes in recipes requiring browning, binding, or structural integrity. Plant-based burgers occupy the dominant margin pool due to premium pricing and brand recognition, while vegan sausages represent the fastest-expanding category within European retail. Tofu segments remain mature across East Asian markets where soy processing infrastructure supports cost-competitive supply.
The FDA regulates novel ingredient safety through GRAS notifications, while EFSA mandates comprehensive allergen labeling for plant-protein isolates under EU food law. REACH compliance affects European manufacturers using textured vegetable protein imports. The EU Green Deal's protein diversification targets are redirecting agricultural subsidies toward legume cultivation for domestic ingredient sourcing. Stakeholders must monitor evolving nomenclature rules that determine whether products qualify for meat-adjacent shelf placement versus segregated alternative sections.
Market Dynamics
Precision fermentation of heme proteins is compressing R&D timelines and forcing capital reallocation toward bioreactor infrastructure, fundamentally altering how texture replication capabilities concentrate among well-capitalized processors.
Growth Catalysts
- EU Green Deal protein diversification:Agricultural subsidies redirect toward legume cultivation, expanding domestic ingredient sourcing capacity for textured vegetable protein manufacturers.
- Quick-service restaurant integration:North American and European chains expand plant-based menu placement, creating pull-through demand for high-volume extruded patty supply.
- Refrigerated retail shelf expansion:German supermarkets allocate additional linear footage to fresh-meat-alternative cases, normalizing premium positioning adjacent to conventional proteins.
Market Restraints
- Soy and pea protein isolate cost volatility:Agricultural commodity swings compress formulation margins, particularly for mid-tier producers lacking long-term supply contracts.
- Textured vegetable protein supply concentration:European manufacturers face REACH compliance burdens on imports, creating dependency on limited certified Asian suppliers.
- Biomimetic texture technical ceilings:Current extrusion and fermentation methods struggle to replicate intramuscular fat deposition in whole-muscle cuts, constraining premium positioning.
Strategic Opportunities
- East Asian tofu segment premiumization:Mature soy processing infrastructure supports cost-competitive supply of clean-label alternatives for export markets seeking minimal-ingredient positioning.
- Vegan sausage European retail acceleration:Fastest-expanding category benefits from cultural acceptance of encased meat formats and established casing technology transfer.
- EFSA allergen labeling clarity:Comprehensive plant-protein isolate disclosure requirements create competitive advantage for processors with robust traceability systems.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates among pharmaceutical-trained specialists, creating recruitment bottlenecks for food-sector employers.
- GRAS notification timeline uncertainty:FDA safety review variability for novel heme proteins delays product launch windows and ties up regulatory affairs resources.
- Nomenclature rule fragmentation:Evolving meat-adjacent shelf placement criteria across jurisdictions force packaging and marketing adaptation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mock Meat Market |
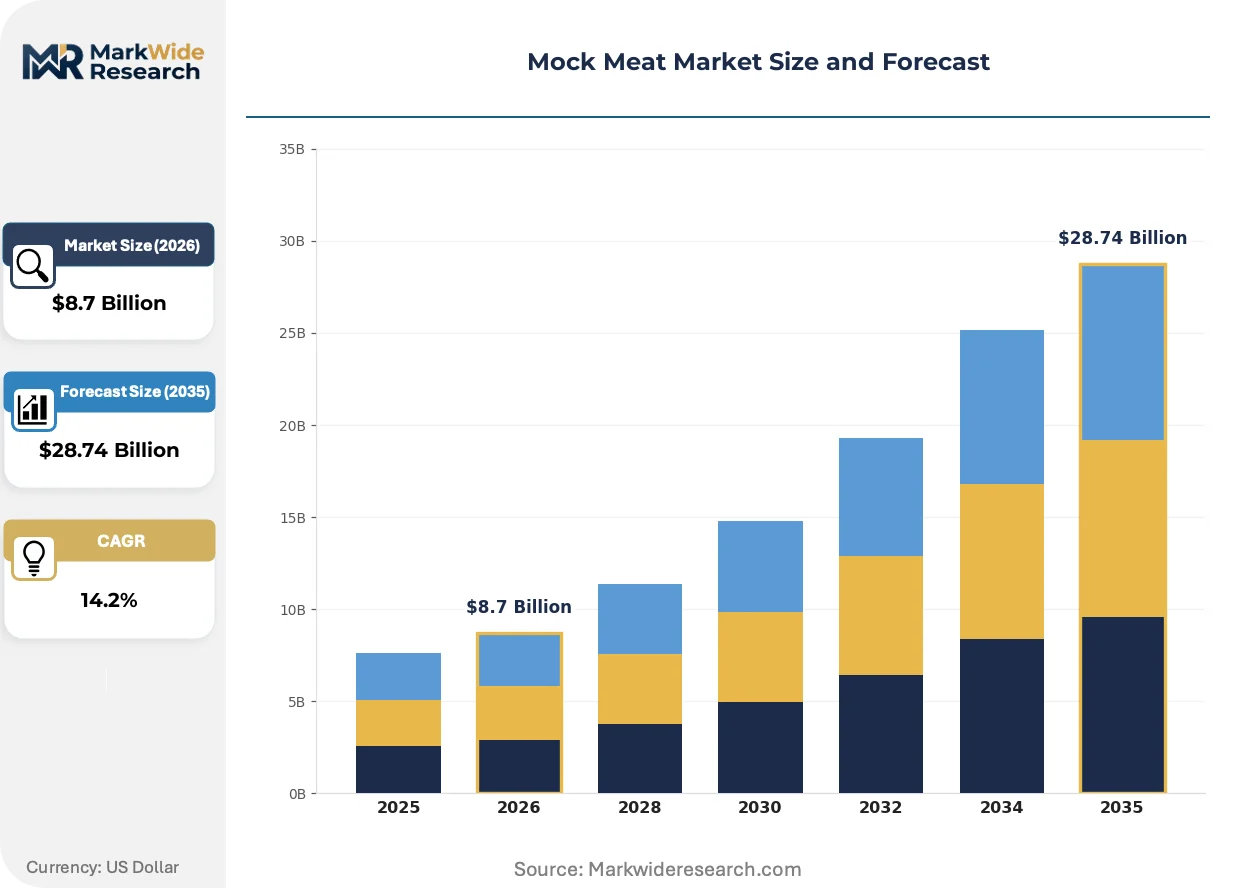
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Burgers, Vegan Sausages, Meat Alternatives, Tofu End User: Restaurants, Supermarkets, Food Service Providers, Home Consumers Distribution Channel: Online Retail, Wholesale, Direct Sales, Physical Stores Application: Meal Replacement, Snack Food, Culinary Ingredient, Ready-to-Eat Meals |
| Companies Covered | Beyond Meat, Impossible Foods, Quorn Foods, Tyson Foods, Maple Leaf Foods, Conagra Brands, Kellogg Company, Tofurky, Amy's Kitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mock Meat Market Evolving Landscape
Active protein sourcing strategies and processing technology maturation are converging to redefine competitive differentiation in texture replication and clean-label positioning.
Extrusion technology is migrating from high-moisture twin-screw systems toward shear-cell processing that aligns protein fibers without elevated temperatures. Quick-service restaurant suppliers adopt these platforms to reduce energy intensity while achieving Warner-Bratzler shear force targets comparable to conventional ground beef. The shift is compressing capital requirements for mid-scale entrants previously blocked by equipment cost barriers.
EFSA's evolving novel protein labeling standards are forcing reformulation transparency across European retail. Manufacturers must disclose processing aids and allergen cross-contact risks previously buried in supply chain opacity. Vegan sausage and burger segments face the steepest compliance costs, driving consolidation toward integrated processors with in-house regulatory affairs capabilities.
Clean-label procurement patterns now prioritize ingredient list brevity over protein concentration metrics in premium European and North American retail. Buyers reject methylcellulose and modified starches in favor of native binding systems from potato, tapioca, or fungal sources. German and Dutch supermarkets lead this filtration, using shelf placement algorithms that penalize additive-heavy formulations regardless of sensory performance scores.
Mock Meat Market Segmentation
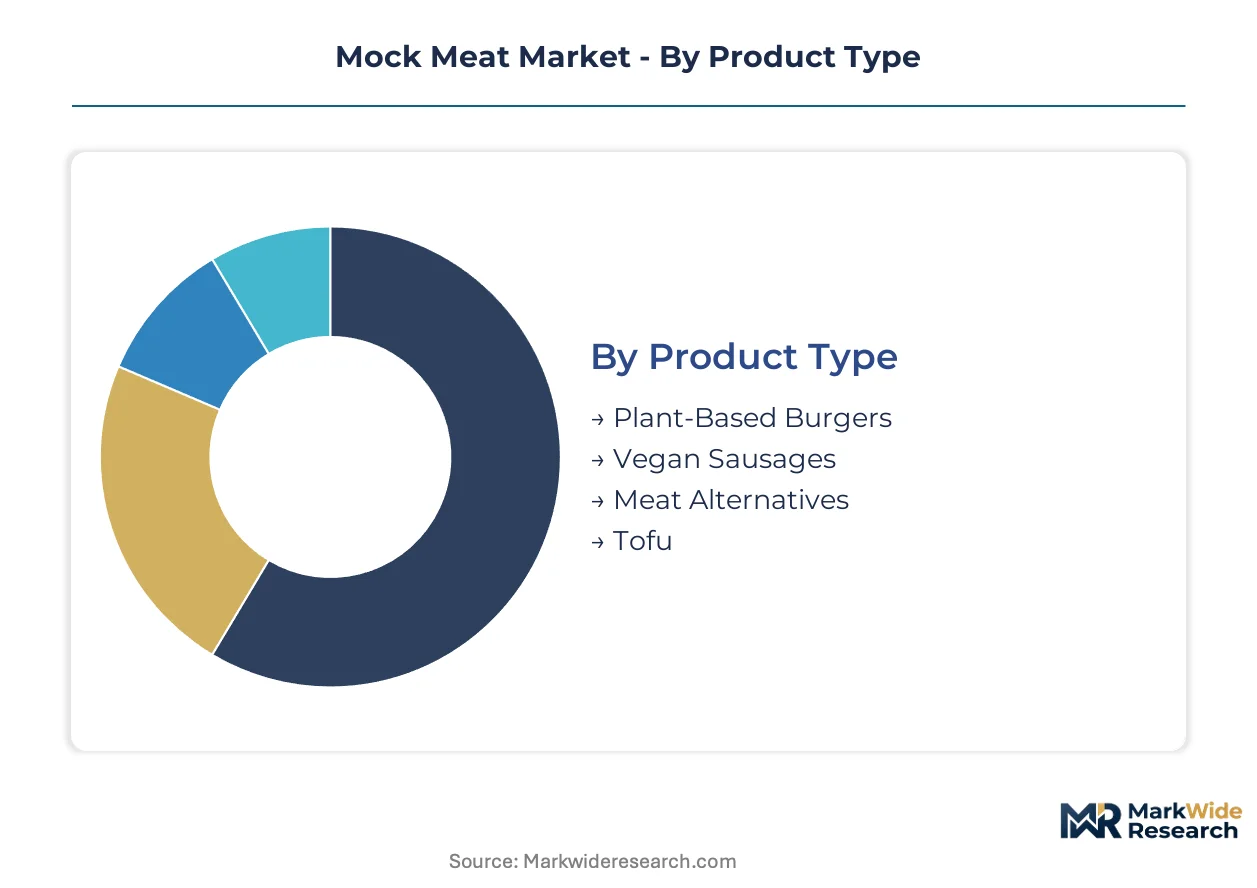
Segmentation in the mock meat market determines formulation priorities, shelf placement negotiations, and capital allocation across distinct demand pockets. Each dimension reveals divergent margin structures and regulatory exposure that shape processor strategy.
Product Type:
After-sales service intensity varies sharply across formats, with refrigerated fresh-meat alternatives demanding cold-chain technical support that frozen or shelf-stable formats avoid.
- Plant-Based Burgers:Extruded protein matrices achieve moisture retention above 60 percent and Warner-Bratzler shear force targets matching conventional ground beef. Quick-service restaurants in the United States drive volume through high-turnover patty supply contracts with strict texture consistency specifications.
- Vegan Sausages:Encased formats leverage established cellulose and alginate casing technology with mycoprotein or pea-protein fills. German retail expansion accelerates fastest here due to cultural familiarity with sausage consumption and existing meat-case adjacency.
- Meat Alternatives:Broad category spanning nuggets, grounds, and strips with formulation flexibility for food service bulk procurement.
- Tofu:Mature segment anchored by East Asian soy processing infrastructure supporting cost-competitive clean-label supply for export markets.
By volume, Plant-Based Burgers leads. By growth pace, Vegan Sausages is ahead.
End User:
Cost tier stratification separates premium branded positioning from commodity supply, with procurement sophistication varying dramatically across buyer types.
- Restaurants:Independent and chain operators specify custom extrusion parameters and binding systems for menu-specific applications. European quick-service integration creates pull-through demand for high-volume, consistent-supply agreements with penalty clauses for texture deviation.
- Supermarkets:German refrigerated case expansion exemplifies retail buyer power, with shelf placement algorithms penalizing additive-heavy formulations regardless of sensory scores. Clean-label procurement mandates compress acceptable ingredient lists.
- Food Service Providers:Institutional and contract caterers prioritize price-stable supply contracts with frozen format durability for inventory flexibility.
- Home Consumers:Direct preparation demands drive recipe-ready positioning and single-serve packaging formats.
Restaurants command the steepest technical specifications. Supermarkets are gaining procurement leverage fastest.
Distribution Channel:
Volume concentration in wholesale and physical retail shapes logistics infrastructure investment, while emerging channels force packaging and pricing adaptation.
- Online Retail:Direct-to-consumer platforms require frozen or shelf-stable formats with insulated shipping compatibility. German and Dutch markets show strongest penetration where subscription models lock in recurring revenue.
- Wholesale:Food service and retail redistribution dominates tonnage, with pallet-scale procurement favoring processors with extrusion capacity above 5,000 metric tons annually.
- Direct Sales:Limited to specialty manufacturers with established food service relationships or proprietary fermentation platforms.
- Physical Stores:Refrigerated case placement remains the margin anchor, with linear footage allocation decisions made at headquarters level for multinational chains.
Wholesale moves the most tonnage. Online Retail is climbing the fastest.
Application:
Customer type segmentation separates reformulation service requirements, with industrial buyers demanding technical collaboration that retail-ready formats bypass.
- Meal Replacement:Complete nutrition positioning drives protein concentration targets and micronutrient fortification. Ready-to-eat formats in European retail face EFSA allergen labeling compliance costs that favor integrated processors.
- Snack Food:Bite-sized formats with extended shelf stability prioritize moisture management and packaging barrier properties over texture fidelity.
- Culinary Ingredient:Unformed grounds and strips allow end-user browning and binding control, serving recipe-flexible positioning in food manufacturing.
- Ready-to-Eat Meals:Pre-cooked formats with sauce compatibility require thermal stability and freeze-thaw resilience for prepared food manufacturing.
Meal Replacement captures premium positioning. Snack Food is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in mock meat ingredients show net exporters in East Asian soy processing economies balancing against net importers in European and North American retail markets. Supply chain reconfiguration is accelerating as regional fermentation capacity and extrusion infrastructure mature.
United States
Quick-service restaurant chains drive volume through high-turnover patty contracts with strict texture specifications. FDA GRAS notification pathways for novel heme proteins create regulatory timeline uncertainty for new entrants. California hosts the densest cluster of precision fermentation facilities developing biomimetic protein platforms.
Germany
Supermarket refrigerated case expansion allocates premium linear footage adjacent to conventional meat, normalizing plant-based positioning. EU Green Deal agricultural subsidies redirect toward domestic legume cultivation for textured vegetable protein sourcing. Berlin anchors regulatory affairs expertise for EFSA allergen labeling compliance across European markets.
China
East Asian soy processing infrastructure supports cost-competitive tofu supply for export markets seeking clean-label alternatives. SAMR novel protein safety standards are evolving alongside GB standards for plant-based food categorization. Yangtze River Delta clusters concentrate extrusion equipment manufacturing and mycoprotein fermentation scale-up.
United Kingdom
Retail buyer power in supermarkets penalizes additive-heavy formulations through shelf placement algorithms regardless of sensory scores. EFSA comprehensive allergen disclosure mandates favor integrated processors with traceability systems. Quorn Foods anchors mycoprotein fermentation expertise developed over decades in the East Midlands.
Netherlands
Subscription-based direct-to-consumer platforms lock in recurring revenue for frozen format alternatives with insulated shipping compatibility. REACH compliance burdens on textured vegetable protein imports create dependency pressure on certified Asian suppliers. Randstad logistics infrastructure supports redistribution hub functions for Northern European retail networks.
Mock Meat Market Competitive Landscape
On the supply side, the industry is bifurcating between well-capitalized integrated processors with captive fermentation capacity and specialized ingredient suppliers serving contract manufacturing relationships. Strategic archetypes include precision fermentation platform operators, extrusion technology licensors, and legacy meat industry diversifiers. Dominant competitive moves center on backward integration into heme protein production and bioreactor infrastructure expansion.
Among North American platform developers, Beyond Meat exemplifies extrusion-focused scale positioning, while Impossible Foods occupies the integrated fermentation archetype with in-house heme capabilities. Quorn Foods represents the European mycoprotein specialist model with decades of fermentation expertise. These three anchors illustrate divergent capital allocation strategies between equipment-heavy extrusion, bioreactor-dependent protein platforms, and fungal biomass cultivation.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Quorn Foods |
| Tyson Foods |
| Maple Leaf Foods |
| Conagra Brands |
| Kellogg Company |
| Tofurky |
| Amy's Kitchen |
| Others |
Value Network & Pricing Analysis
Undercapacity in European precision fermentation facilities is compressing supplier margins while amplifying pricing power for extrusion-capable processors with captive heme production. This utilization asymmetry forces mid-tier formulators toward contract manufacturing relationships that surrender margin to integrated players.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across quick-service restaurant supply chains. Three-tier pricing structure across premium, standard, and economy levels separates clean-label formulations with native binders from additive-dependent alternatives. Cost compression in mid-tier extruded patties is intensifying because soy and pea protein isolate contracts face agricultural commodity swings. Quick-service chains exhibit highest price sensitivity due to volume scale penalties, while German supermarkets prioritize sensory consistency over unit cost.
Supply Chain Analysis
Tariff exposure between United States and Chinese extrusion equipment imports dominates capital expenditure planning for mid-scale entrants. Supply concentrates in China for soy protein isolate, Germany for mycoprotein fermentation infrastructure, and Netherlands for redistribution logistics. Raw material dependencies center on pea protein isolate, heme protein concentrates, and cellulose casings. Single-source vulnerability in certified Asian textured vegetable protein suppliers creates REACH compliance bottlenecks. Distribution runs through wholesale redistribution to quick-service restaurant chains and supermarket headquarters procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-chain technical support contracts for refrigerated fresh-meat alternatives are expanding faster than base product sales, creating service-attach revenue pools that outpace hardware margins.
For Market Incumbents: Build regulatory affairs moats through in-house EFSA allergen labeling compliance systems and GRAS notification expertise. Defend against precision fermentation entrants by securing long-term legume supply contracts under EU Green Deal subsidy flows. Add extrusion capacity in Germany to capture refrigerated case expansion. For New Entrants and Emerging Players: Pursue vegan sausage white space in European retail where cultural acceptance and casing technology transfer lower barriers. Target Netherlands subscription-based direct-to-consumer platforms as the most penetrable channel with insulated shipping infrastructure. Lead with clean-label native binder formulations to bypass supermarket algorithmic penalties. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation bioreactor infrastructure, favoring platform operators with pharmaceutical-trained scale-up teams. Five-to-ten-year viability hinges on backward integration into heme protein production. Target integrated processors with captive fermentation and extrusion capabilities. Watch FDA GRAS notification timeline variability as inflection signal for new entrant launch windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heme Production | Captive supply of precision-fermented proteins reduces dependency on external bioreactor capacity and compresses R&D timelines. |
| Shear-Cell Processing Technology Adoption | Lower-temperature extrusion reduces energy intensity while achieving Warner-Bratzler shear force targets for quick-service specifications. |
| EU Green Deal Legume Cultivation Partnerships | Domestic sourcing agreements under protein diversification subsidies secure cost-stable textured vegetable protein feedstock. |
| Refrigerated Case Adjacency Negotiations | Meat-case placement in German supermarkets normalizes premium positioning and drives pull-through demand. |
| Clean-Label Reformulation Investment | Native potato and tapioca binding systems bypass shelf placement algorithms that penalize methylcellulose-heavy formulations. |
Research Methodology
Desk research of FDA GRAS notification databases, EFSA allergen guidance documents, and EU agricultural subsidy flows preceded structured interviews with extrusion technology licensors, quick-service restaurant procurement directors, and supermarket category buyers. Primary fieldwork with precision fermentation platform operators and mycoprotein fermentation specialists validated secondary trade flow data. Bottom-up capacity modeling triangulated against top-down retail audit estimates from Nielsen and Circana.
Assumptions held fixed include EU Green Deal protein diversification subsidy continuity and FDA GRAS review timeline distributions. Variable conditions spanned soy and pea protein commodity price trajectories and quick-service restaurant menu integration rates across the projection horizon. Segmentation dimensions modeled include product type, end user procurement sophistication, distribution channel logistics requirements, and application-specific texture specifications. CAGRs derived from iterative reconciliation of volume forecasts with value estimates using protein concentration and premium positioning tiers.
Sensitivities concentrate around regulatory timeline shifts for novel heme proteins and REACH compliance burden changes on textured vegetable protein imports. Forecasts reflect documented assumptions regarding extrusion capacity expansion and fermentation scale-up expertise availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Black Soldier Fly (BSF) Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
North America Edible Insects Market