
 Europe Algae Protein Market | 2026-2036
Europe Algae Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Algae Protein Market Analysis
Ingredient licensing revenue is reshaping margin distribution between raw biomass suppliers and finished-goods formulators in the European algae protein value chain. Corbion Biotech leverages its Dutch fermentation infrastructure to dominate pharmaceutical-grade chlorella supply. Roquette Klotze GmbH & Co. KG anchors its position through backward integration into German pea-and-algae protein blending facilities. Phycom BV specializes in photobioreactor cultivation systems that sustain premium pricing for whole-cell spirulina powders.
Europe algae protein encompasses dried, milled, or extracted cellular biomass from cyanobacteria and microalgae species, typically containing 50-70% crude protein by dry weight with complete essential amino acid profiles and bioactive pigments such as phycocyanin and chlorophyll. Industrial processors deploy closed photobioreactor or open raceway pond systems to cultivate, harvest, and spray-dry biomass for human nutrition, animal feed, and cosmetic applications. Spirulina powder occupies the largest volume share among product types due to decades of consumer familiarity and established supply chains across Iberian and Mediterranean markets. Nutritional supplements and food and beverages represent the fastest-expanding application clusters as EFSA-approved novel food dossiers accumulate for chlorella and dunaliella extracts in dairy alternatives and sports nutrition bars.
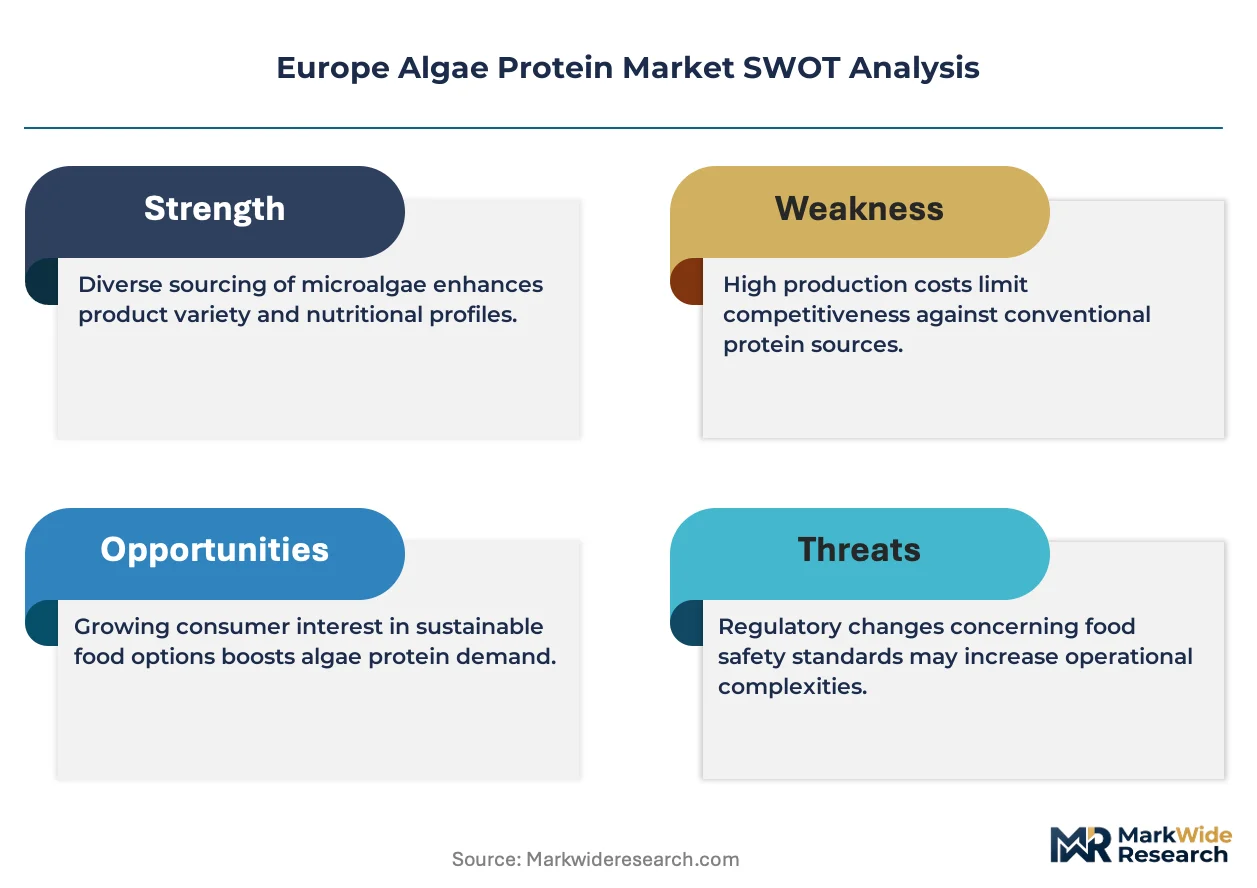
EFSA novel food regulations, EU Green Deal sustainability benchmarks, and REACH chemical safety standards collectively determine which algae strains and extraction solvents gain commercial authorization across member states. The F-Gas Regulation indirectly shapes cultivation economics by restricting synthetic refrigerants used in temperature-controlled bioreactor operations. Stakeholders must monitor pending EFSA opinions on aphanizomenon flos-aquae protein isolates and assess whether national bioeconomy strategies in France and Germany will subsidize domestic algae cultivation capacity.
Market Dynamics
EFSA novel food authorization timelines are compressing from 18 months to 9 months for chlorella and spirulina isolates, redrawing competitive barriers between established EU suppliers and new fermentation entrants.
Growth Catalysts
- EU Green Deal sustainability benchmarks:Mandatory carbon footprint disclosures for food ingredients are pushing dairy and meat alternative formulators toward algae protein with verified low-emission cultivation credentials.
- German plant-based meat procurement:Industrial buyers in Berlin and Hamburg are scaling spirulina isolate volumes for burger and sausage applications, creating anchored demand that justifies capacity expansion.
- Photobioreactor automation:Closed-system cultivation technology is reducing contamination rates and labor intensity, enabling consistent pharmaceutical-grade biomass output at commercial scale.
Market Restraints
- Energy input cost volatility:LED lighting and temperature-controlled bioreactor operations consume 35-45% of cultivation opex, exposing Dutch and German producers to electricity price spikes.
- Spirulina supply concentration:Iberian and Mediterranean growers control 60% of EU whole-cell powder volume, creating geographic vulnerability to drought and heat stress events.
- REACH solvent restrictions:Approved extraction solvents for protein isolates remain limited, constraining yield optimization and functional property tuning for bakery applications.
Strategic Opportunities
- French bioeconomy subsidies:National algae cultivation capacity expansion programs in Brittany and Normandy offer capital grants for photobioreactor installations serving cosmetic and nutraceutical offtake.
- Dairy alternative reformulation:Unsweetened oat and pea milks in Spain and Italy are integrating chlorella extracts for color stability and amino acid fortification, opening white-space positioning.
- Direct-to-brand ingredient platforms:Bypassing traditional distributors, biomass suppliers are building captive e-procurement portals for mid-size European food manufacturers seeking traceable supply.
Industry Challenges
- Novel food dossier preparation:EFSA-compliant toxicology and nutritional equivalence studies require specialized regulatory affairs talent that remains scarce across Lisbon, Madrid, and Milan clusters.
- Downstream integration complexity:Biomass suppliers building in-house spray-drying and extraction capabilities face 24-36 month commissioning timelines and GMP certification backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Algae Protein Market |
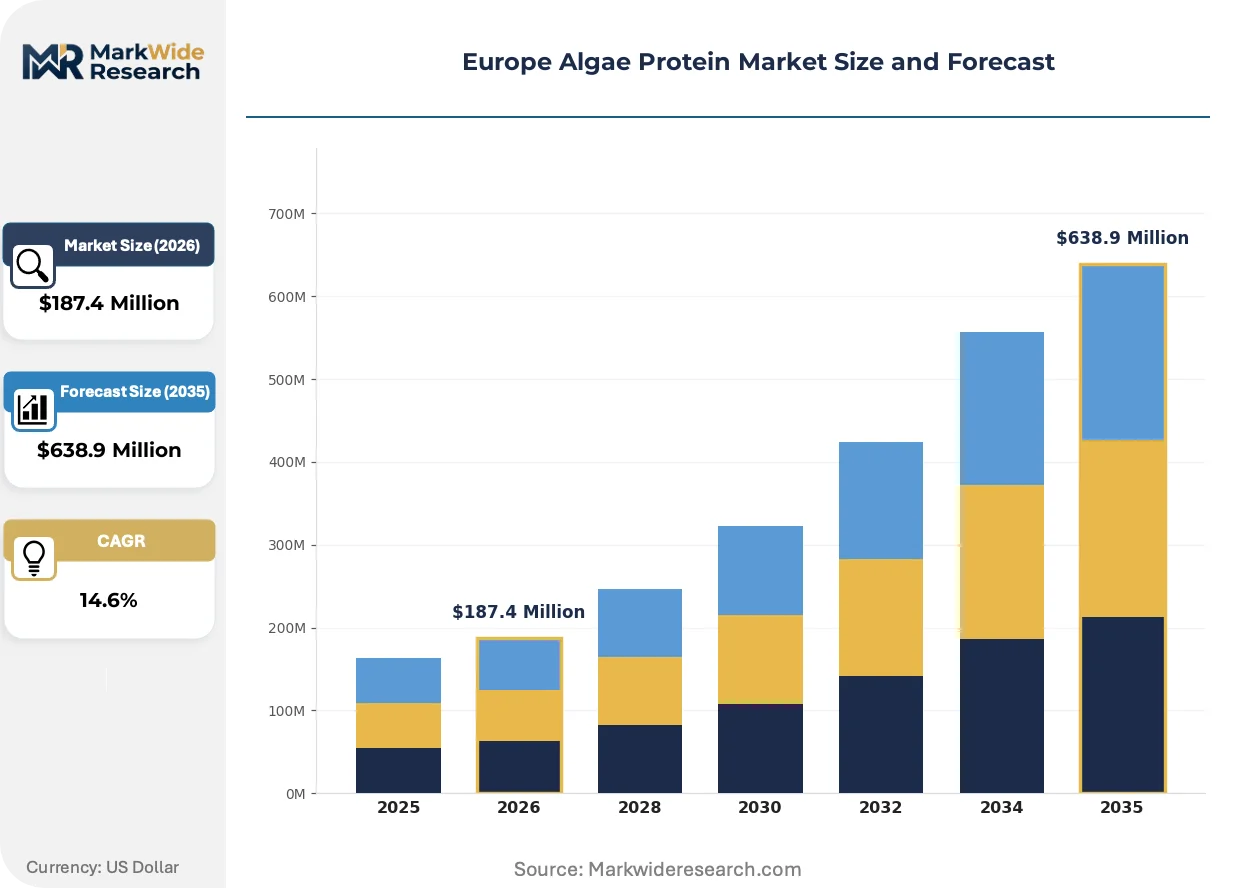
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Aphanizomenon, Dunaliella Application: Nutritional Supplements, Food & Beverages, Animal Feed, Cosmetics End User: Health-Conscious Consumers, Athletes, Pet Owners, Food Manufacturers Form: Powder, Tablet, Liquid, Granules |
| Companies Covered | Corbion Biotech, Roquette Klotze GmbH & Co. KG, Phycom BV, Duplaco BV, Algama Foods, Allmicroalgae, Aliga Microalgae, Bretagne Spiruline SARL, Ecospirulina S.L., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Algae Protein Market Emerging Trajectories
Computational biology and precision fermentation are converging to produce algae protein without photosynthetic cultivation, collapsing the traditional link between geography and biomass quality.
Precision fermentation of heterotrophic chlorella strains is virtualizing the production location constraint that historically tied premium protein supply to Mediterranean solar availability. Pharmaceutical and cosmetic formulators in the Netherlands and Germany are adopting these isolates for batch-to-batch consistency. The technology is virtualizing regional supply advantages, enabling Nordic and Central European facilities to compete on cost and quality metrics previously dominated by southern EU growers.
EFSA's streamlined novel food evaluation pathway for established microalgae species is accelerating authorization velocity for chlorella and dunaliella extracts. Industrial food manufacturers are front-loading dossier investments to secure 18-24 month competitive moats before pathway saturation. Dairy alternative and sports nutrition verticals in France and Spain are responding fastest, locking in exclusive supply arrangements ahead of competitor approvals.
Ingredient procurement through digital B2B marketplaces is displacing traditional broker relationships for mid-volume algae protein buyers. European specialty food manufacturers are sourcing certified organic spirulina through verified supplier platforms that embed CO2 footprint data and EFSA compliance documentation. This channel shift is most visible in Italian and German bakery reformulation projects, where procurement teams prioritize audit-ready traceability over price negotiation leverage.
Europe Algae Protein Market Segmentation
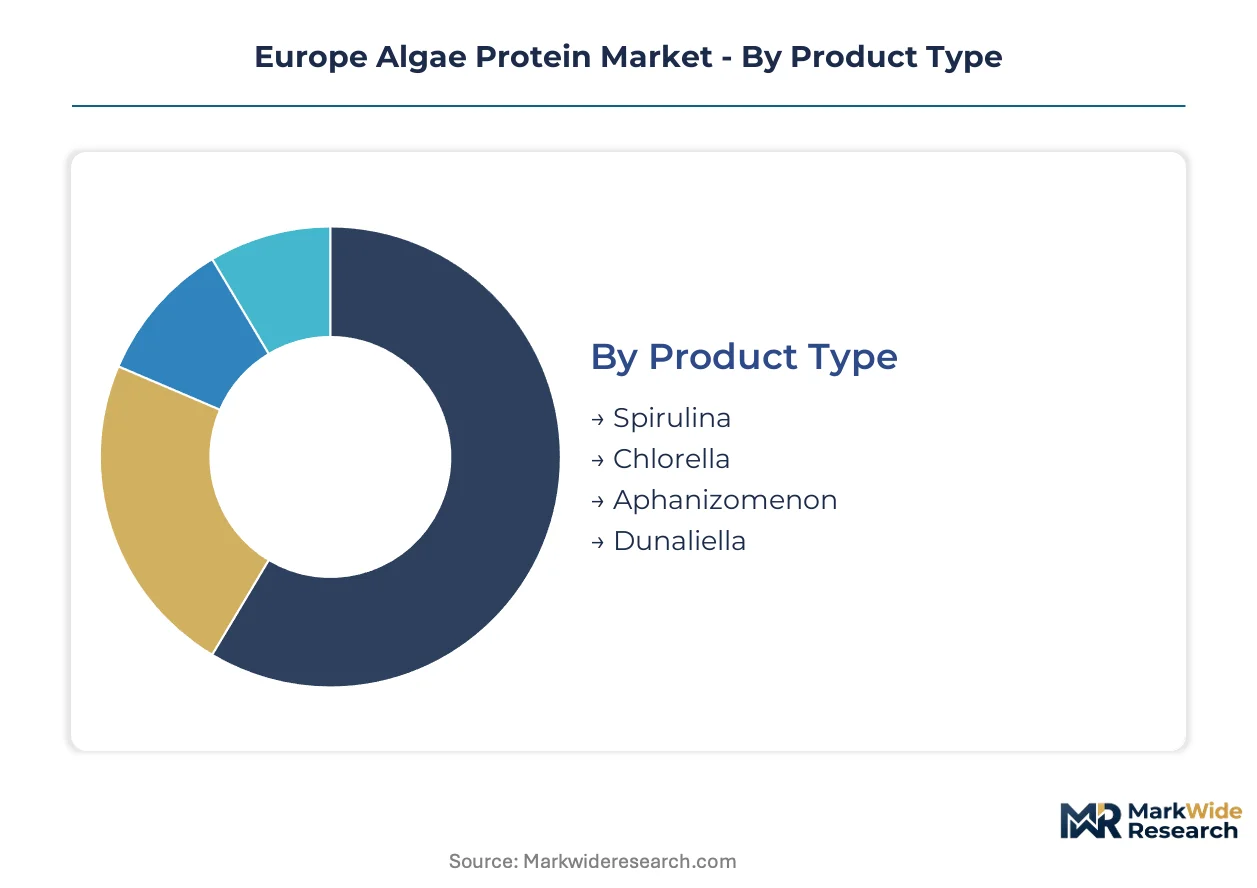
Segmentation in the Europe algae protein market reveals how cultivation biology, regulatory authorization velocity, and end-use formulation requirements create distinct commercial battlegrounds. Each dimension—species chemistry, application processing standards, and delivery format—commands different margin structures and capital intensity thresholds.
Product Type:
Mature commercial species anchor near-term revenue while emerging strains await EFSA clearance to unlock premium positioning.
- Spirulina:Cyanobacterial biomass containing 60-70% protein with established phycocyanin extraction protocols for natural colorant applications. German and Dutch plant-based meat manufacturers are locking in multi-year isolate contracts for burger and sausage formulations, though Iberian supply concentration creates drought exposure.
- Chlorella:Chlorophyte microalgae with superior digestibility and chlorophyll content driving pharmaceutical-grade demand. French and Spanish dairy alternative producers are accelerating chlorella extract procurement for amino acid fortification and color stability in oat and pea milk reformulations.
- Aphanizomenon:Filamentous cyanobacterium with bioactive compound profiles pending EFSA novel food evaluation. Klamath Lake sourcing constraints limit European supply scalability.
- Dunaliella:Halotolerant green microalgae prized for beta-carotene and glycerol accumulation. Cosmetic formulators in Italy are piloting dunaliella isolates for premium skincare antioxidant claims.
Spirulina retains volume leadership; Dunaliella holds the steepest expansion curve pending EFSA authorization completion.
Application:
Processing temperature tolerance and label claim permissibility stratify addressable margin pools across downstream verticals.
- Nutritional Supplements:Capsule and tablet formats requiring GMP-certified biomass with heavy metal and microcystin documentation. Dutch and German direct-to-consumer brands are driving demand for organic-certified spirulina powders with embedded CO2 footprint verification.
- Food & Beverages:Bakery, dairy alternative, and sports nutrition applications demanding heat-stable protein isolates with neutral flavor profiles. Spanish and Italian manufacturers are reformulating bread and pasta with chlorella for protein fortification claims.
- Animal Feed:Aquaculture and pet food segments accepting whole-cell biomass with lower purity thresholds. Norwegian salmon feed producers are evaluating algae protein as fishmeal displacement.
- Cosmetics:Topical formulations requiring solvent-extracted bioactives with REACH-compliant safety dossiers. French photobioreactor operators in Brittany are targeting cosmetic offtake with premium pricing.
Food & Beverages applications are climbing the fastest; Nutritional Supplements maintain the deepest buyer concentration.
End User:
Purchasing sophistication and traceability requirements create four distinct customer archetypes with diverging procurement behaviors.
- Health-Conscious Consumers:Retail purchasers prioritizing organic certification and origin transparency over price. Italian and German consumers are shifting toward verified supplier platforms with embedded compliance documentation.
- Athletes:Sports nutrition buyers demanding batch-tested protein content with banned substance screening. Spanish sports nutrition brands are locking in chlorella supply for amino acid completeness claims.
- Pet Owners:Premium pet food purchasers seeking novel protein sources for allergy-sensitive formulations. Limited dedicated supply infrastructure constrains segment scaling.
- Food Manufacturers:Industrial buyers with technical procurement teams negotiating multi-year contracts with quality guarantees. Berlin and Hamburg plant-based meat producers are anchoring spirulina demand through volume commitments.
Food Manufacturers retain volume leadership; Athletes represent the steepest expansion trajectory as sports nutrition brands accelerate reformulation.
Form:
Processing economics and shelf stability requirements determine format selection across end-use applications.
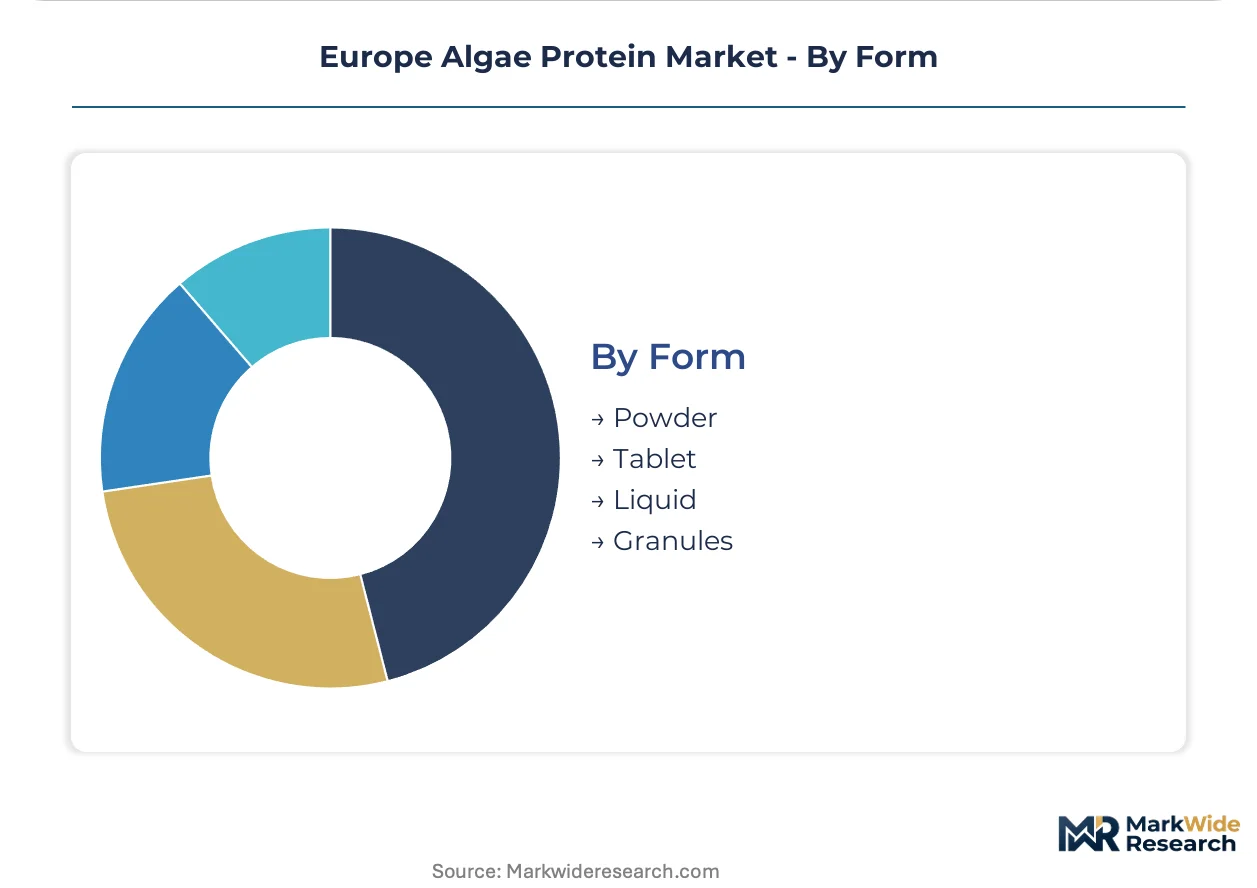
- Powder:Spray-dried biomass dominating bulk ingredient trade with lowest per-kilogram logistics cost. Mediterranean growers supply 60% of EU whole-cell powder volume through established Iberian processing infrastructure.
- Tablet:Compressed formulations for supplement retail with excipient and disintegration specifications. German contract manufacturers are expanding tableting capacity for organic spirulina brands.
- Liquid:Aqueous extracts and suspensions for beverage fortification requiring cold chain or aseptic packaging. Limited commercial scale due to stability and transport cost constraints.
- Granules:Agglomerated formats for instant dissolution in functional drinks. Emerging format with pilot production in Dutch fermentation facilities.
Powder retains volume leadership; Liquid formats are gaining share fastest as beverage manufacturers seek clean-label fortification solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity splits sharply across the continent. German and Dutch industrial buyers absorb premium isolates for plant-based meat reformulation, while Mediterranean food manufacturers remain acutely sensitive to spirulina powder cost fluctuations.
Germany
Berlin and Hamburg anchor spirulina isolate procurement for burger and sausage applications, with industrial buyers locking multi-year volume commitments. The EU Green Deal carbon disclosure mandates push dairy alternative formulators toward verified low-emission algae credentials. Bavaria's fermentation clusters are scaling pharmaceutical-grade chlorella capacity through automated photobioreactor installations.
Netherlands
Rotterdam and Amsterdam harbor zones concentrate precision fermentation facilities producing heterotrophic chlorella strains independent of solar geography. The F-Gas Regulation restricts synthetic refrigerants in temperature-controlled bioreactor operations, reshaping cultivation economics. Dutch cosmetic formulators in Utrecht are adopting these isolates for batch-to-batch consistency in premium skincare.
France
Brittany and Normandy cultivation clusters target cosmetic and nutraceutical offtake through national bioeconomy subsidy programs. EFSA novel food authorization timelines are compressing for chlorella extracts used in dairy alternative reformulation. Paris-based sports nutrition brands are front-loading dossier investments to secure competitive moats before pathway saturation.
Spain
Catalonia and Andalusia control the majority of EU whole-cell spirulina powder volume through established Iberian processing infrastructure. Unsweetened oat and pea milk producers in Barcelona are integrating chlorella extracts for color stability and amino acid fortification. REACH solvent restrictions constrain yield optimization for bakery protein isolate applications.
Italy
Lombardy and Emilia-Romagna manufacturers lead bakery and pasta reformulation with chlorella protein fortification claims. Italian procurement teams prioritize audit-ready traceability through digital B2B marketplaces over price negotiation leverage. Milan-based cosmetic formulators are piloting dunaliella isolates for premium skincare antioxidant positioning.
Europe Algae Protein Market Vendor Landscape
Capability concentration sits with fermentation technology specialists; scale advantage sits with integrated biomass processors with captive drying infrastructure. The vendor base stratifies across three tiers: pharmaceutical-grade specialists commanding premium isolates, commodity powder suppliers serving feed and bulk nutrition markets, and precision fermentation entrants collapsing geographic supply constraints. Dominant competitive moves include backward integration into cultivation-drying-extraction capabilities and strategic partnerships with EFSA regulatory affairs specialists to accelerate novel food dossier preparation.
Within the integrated processing tier, Corbion Biotech leverages its Dutch fermentation infrastructure to anchor pharmaceutical-grade supply positioning. Roquette Klotze GmbH & Co. KG exemplifies backward integration through German pea-and-algae protein blending facilities. Phycom BV occupies a specialist position in photobioreactor cultivation systems that sustain premium pricing for whole-cell spirulina powders.
| Leading Market Players |
|---|
| Corbion Biotech |
| Roquette Klotze GmbH & Co. KG |
| Phycom BV |
| Duplaco BV |
| Algama Foods |
| Allmicroalgae |
| Aliga Microalgae |
| Bretagne Spiruline SARL |
| Ecospirulina S.L. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Iberian spirulina cultivation concentrates pricing power among Mediterranean growers while exposing German and Dutch buyers to drought-driven cost spikes and contract renegotiation cycles. This geographic tethering compresses margin buffers for mid-volume food manufacturers and forces tiered supply strategies that stratify procurement costs across pharmaceutical-grade isolates and commodity whole-cell powders.
Pricing Analysis
Ingredient licensing revenue streams from EFSA novel food dossiers anchor lifetime value for biomass suppliers with regulatory affairs capabilities. Three-tier pricing structure across pharmaceutical-grade isolates, food-grade extracts, and feed-grade whole-cell powders reflects certification intensity and extraction solvent compliance. Cost compression in standard-grade spirulina powders intensifies as Dutch precision fermentation entrants collapse solar-dependent cultivation premiums. Food manufacturers in Berlin and Hamburg exhibit lowest price sensitivity due to anchored plant-based meat procurement commitments, while Italian bakery reformulators remain acutely responsive to powder cost fluctuations.
Supply Chain Analysis
Tariff exposure between Iberian raw biomass suppliers and Central European processing facilities amplifies landed cost volatility for Dutch and German formulators. Cultivation concentrates in Spain and Portugal for whole-cell spirulina, with France and Germany hosting downstream extraction and spray-drying infrastructure. Raw material dependencies include LED lighting systems, temperature-controlled bioreactor vessels, and REACH-compliant protein isolation solvents. Single-source vulnerability runs through Mediterranean solar-dependent cultivation for premium-grade biomass. Distribution runs through verified digital B2B platforms embedding EFSA compliance documentation for mid-volume buyers, alongside traditional broker relationships for commodity feed-grade offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA novel food authorization velocity fragments competitive positioning by rewarding early dossier investors with 18-24 month exclusive supply windows before pathway saturation erodes differentiation. Dairy alternative reformulation in France and Spain, plus sports nutrition fortification across the continent, creates addressable niches for specialized isolate suppliers.
For Market Incumbents: Pre-empt precision fermentation displacement by deepening captive cultivation-drying-extraction capabilities in Brittany and Normandy subsidy zones. Secure multi-year volume commitments from Berlin and Hamburg plant-based meat manufacturers before heterotrophic chlorella strains achieve cost parity. Prioritize EFSA regulatory affairs talent acquisition in Lisbon, Madrid, and Milan clusters to accelerate novel food dossier velocity and defend licensing revenue streams. For New Entrants and Emerging Players: Pursue unsweetened oat and pea milk reformulation in Barcelona and Milan as the most penetrable white-space target, where chlorella extract demand for color stability outstrips qualified supplier availability. Target French cosmetic formulators in Utrecht and Brittany with batch-consistent photobioreactor isolates. Lead with direct-to-brand e-procurement platforms offering embedded CO2 footprint verification and REACH-compliant solvent documentation. For Investors and Strategic Acquirers: EFSA's pending opinions on aphanizomenon flos-aquae protein isolates reshape the acquisition landscape by determining which strain portfolios capture premium positioning. Long-term viability hinges on regulatory authorization velocity rather than cultivation scale alone. Target integrated processors with captive GMP-certified drying infrastructure and established EFSA consultant relationships. Monitor EFSA opinion publication schedules as the critical inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation-Drying Infrastructure | Captures margin from raw biomass through pharmaceutical-grade isolate output in subsidy-eligible French clusters. |
| EFSA Novel Food Dossier Front-Loading | Secures competitive moats before streamlined evaluation pathways saturate with competitor submissions. |
| Precision Fermentation Scale-Up | Virtualizes solar geography constraints and enables Nordic facilities to compete on Mediterranean quality metrics. |
| Direct-to-Brand Digital Platform Launch | Bypasses traditional distributors for mid-volume Italian and German bakery reformulation procurement. |
| Cosmetic-Nutraceutical Co-Location | Leverages Brittany photobioreactor installations for premium skincare antioxidant and sports nutrition dual offtake. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA novel food dossier databases, EU trade customs records, and national bioeconomy subsidy program disclosures. Primary interviews engaged cultivation technology directors at photobioreactor operators, procurement leads at German plant-based meat manufacturers, regulatory affairs specialists at Dutch fermentation facilities, and category buyers at French dairy alternative brands. Secondary validation drew from REACH solvent restriction filings, F-Gas Regulation implementation guidance, and EFSA scientific opinion archives. Bottom-up biomass volume estimates triangulated against top-down ingredient demand projections from food and beverage reformulation pipelines.
Forecast inputs span species chemistry segmentation, application processing standards, and delivery format economics across the projection horizon. Modeled dimensions include spirulina versus chlorella versus emerging strain portfolios, nutritional supplement versus food and beverage versus cosmetic end-uses, and powder versus liquid versus tablet formats. CAGRs derived from penetration curve analysis of EFSA authorization velocity and industrial buyer procurement commitment timelines. Industry-specific inputs incorporate EU Green Deal carbon disclosure mandate compliance costs and photobioreactor automation capital expenditure trajectories.
Sensitivities concentrate around EFSA opinion delays for aphanizomenon and dunaliella strains, Iberian drought frequency affecting spirulina yields, and electricity price volatility impacting Dutch and German bioreactor operating economics. Forecasts reflect assumptions regarding subsidy program continuity and REACH solvent list expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Global Meal Replacement Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
South America Fat Replacers Market