
 Vegetable Waste Products Market | 2026-2036
Vegetable Waste Products Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Waste Products Market Analytics
Asset-light leasing models for anaerobic digestion infrastructure is reconfiguring capital barriers for mid-scale waste processors. Veolia leverages its integrated collection-to-compost network across European municipalities. Republic Services anchors its position through long-term municipal contracts that guarantee feedstock volumes. SUEZ competes by specializing in in-vessel composting systems designed for supermarket and hotel chains.
Vegetable waste products encompass the residual biomass from agricultural harvesting, food processing, and retail distribution, typically comprising cellulose, hemicellulose, lignin, and moisture content exceeding sixty percent before processing; these materials undergo controlled biological or thermal conversion to produce soil amendments, feed ingredients, or energy feedstocks. Compost dominates volume flows due to mature aerobic digestion infrastructure and established agricultural demand, while biochar commands premium positioning in carbon-sequestering soil applications where buyers pay for permanence certification. Anaerobic digestion is expanding fastest as biogas offtake agreements create dual revenue streams from both digestate sales and energy credits.
The EU Green Deal and REACH frameworks mandate organic waste diversion from landfills while setting contaminant thresholds for processed outputs, directly shaping product certification requirements and cross-border trade eligibility. The EPA in the United States enforces pathogen reduction standards under Part 503 rules that determine whether compost qualifies for unrestricted agricultural use. Stakeholders must monitor evolving carbon accounting methodologies that could reclassify biochar and digestate value propositions under compliance and voluntary offset markets.
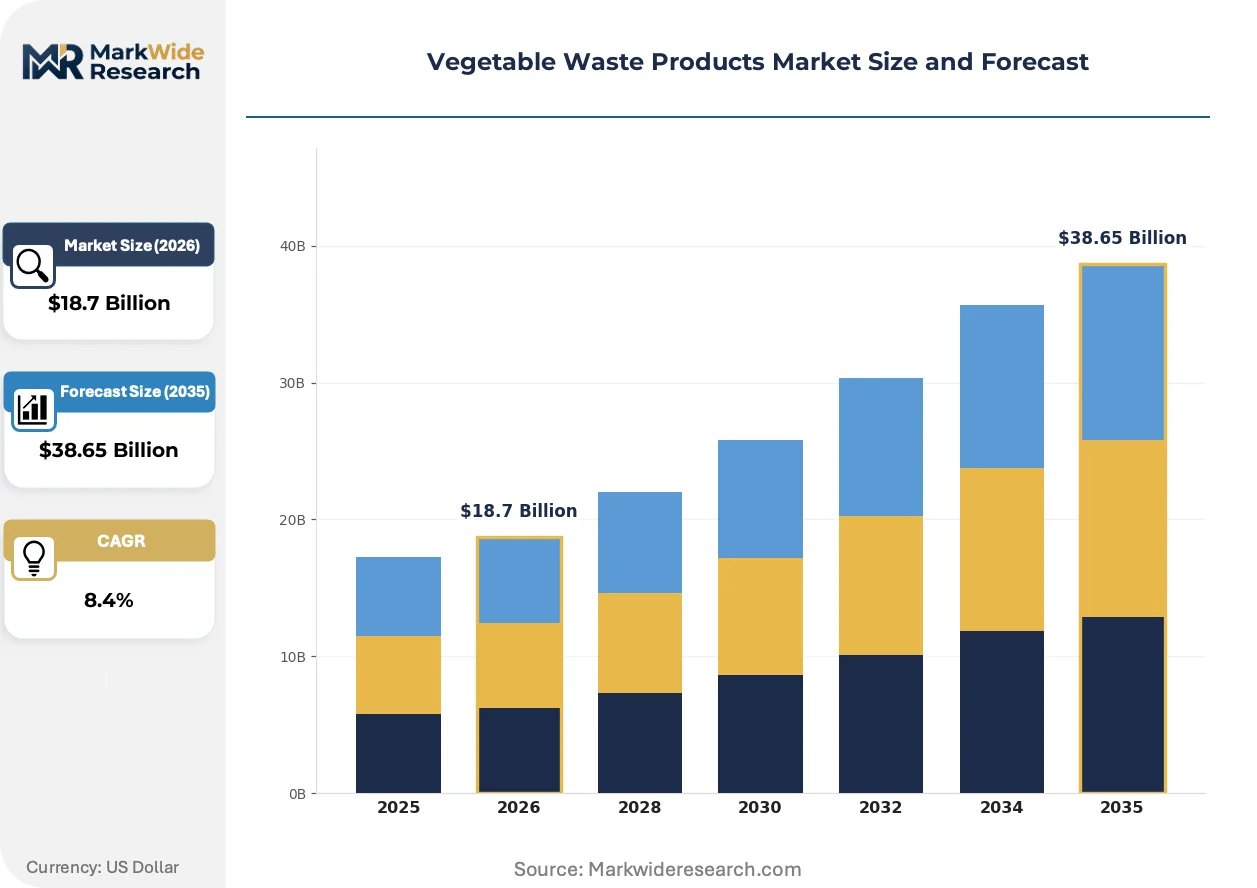
Market Dynamics
EU Green Deal organic waste diversion mandates are forcing industrial food producers to secure certified waste-derived inputs, reconfiguring procurement relationships between processors and agricultural offtake buyers across Germany, France, and the Netherlands.
Growth Catalysts
- EU Green Deal landfill diversion targets:Mandatory organic waste separation in member states creates guaranteed feedstock pipelines for anaerobic digestion facilities and composting operations.
- Agricultural soil amendment demand:German arable farming cooperatives are locking in multi-year digestate supply contracts to replace synthetic nitrogen fertilizers under national climate neutrality commitments.
- Anaerobic digestion technology maturation:Continuous stirred-tank reactor designs now achieve higher biogas yields per ton of vegetable waste, improving unit economics for mid-scale processors.
Market Restraints
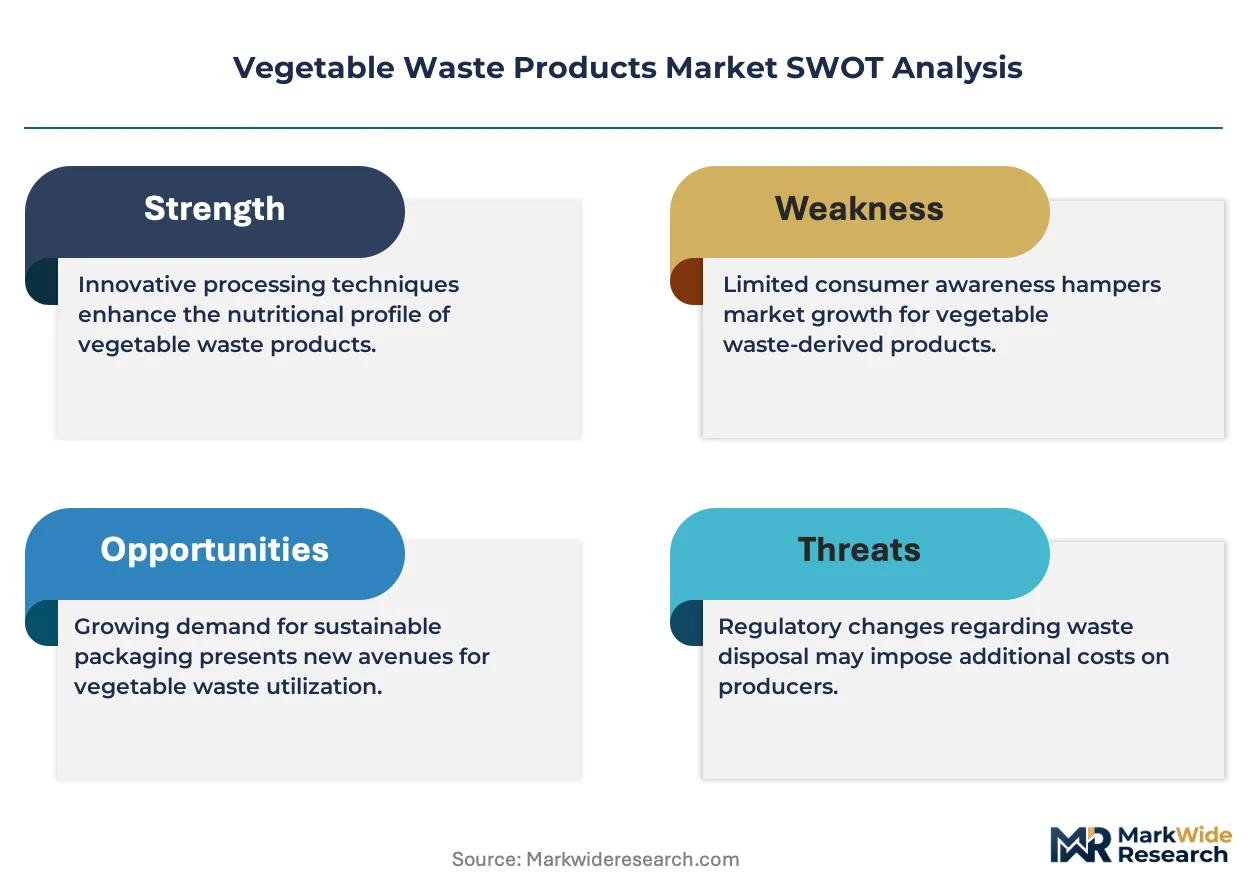
- Feedstock contamination thresholds:EU REACH framework sets strict limits on plastic and heavy metal content in processed outputs, requiring costly pre-sorting infrastructure at collection points.
- Seasonal supply volatility:Vegetable waste generation concentrates during harvest windows in Spain and Italy, creating year-round processing capacity underutilization in Northern European facilities.
- Natural gas price linkage:Biogas offtake agreements typically index to wholesale natural gas benchmarks, compressing margins when fossil fuel prices collapse.
Strategic Opportunities
- Carbon credit certification for biochar:Emerging voluntary offset methodologies in Germany and France allow permanence-certified biochar to command premium pricing in corporate net-zero procurement programs.
- Supermarket chain direct partnerships:French retail consolidation creates centralized waste streams that bypass municipal collection, enabling processor control over feedstock quality and volume.
- In-vessel composting retrofitting:Hotels and institutional caterers in the Netherlands are installing on-site systems to meet corporate ESG targets and reduce disposal costs.
Industry Challenges
- Microbiological certification timelines:EPA Part 503 pathogen reduction testing extends product release cycles by 30-60 days, tying up working capital in inventory.
- Digestate nutrient variability:Inconsistent feedstock composition complicates agricultural sales, requiring batch testing and blending investments to meet fertilizer labeling requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Waste Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biochar, Compost, Fertilizers, Animal Feed End Use Industry: Agriculture, Landscaping, Bioenergy, Food Processing Processing Method: Aerobic Digestion, Fermentation, In-vessel Composting, Anaerobic Digestion Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesalers |
| Companies Covered | Veolia, Renewi, SUEZ, Waste Management, Inc., Republic Services, Biffa, FCC Environment, Waste Connections, Covanta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Waste Products Market Evolving Landscape
Processing technology convergence and regulatory carbon accounting refinements are compressing the gap between waste disposal cost centers and revenue-generating resource recovery operations across European food supply chains.
Pyrolysis reactor systems for biochar production are hybridizing with anaerobic digestion facilities to enable sequential extraction of biogas and stable carbon from the same feedstock stream. German agricultural cooperatives are piloting these integrated configurations to maximize revenue per ton of incoming vegetable waste. The technology is hybridizing capital deployment models, allowing processors to access carbon removal credits alongside traditional digestate sales.
EU CSRD corporate sustainability reporting requirements are mandating Scope 3 emissions disclosure for food manufacturers, directly increasing traceability demands on waste-derived input suppliers. Industrial buyers now require chain-of-custody documentation from collection through processing to claim supply chain decarbonization credits. French and Dutch food processors are responding by consolidating supplier relationships with certified composting and biochar facilities that can provide audit-ready carbon accounting.
Long-term offtake contracting is displacing spot market transactions as the dominant procurement mechanism for processed vegetable waste outputs. Agricultural buyers in Germany are locking in five to seven-year digestate supply agreements with price escalation clauses tied to synthetic fertilizer benchmarks. This shift is most visible in the Rhine-Ruhr corridor, where anaerobic digestion clusters have achieved sufficient scale to underwrite dedicated pipeline infrastructure to surrounding farmland.
Vegetable Waste Products Market Segmentation
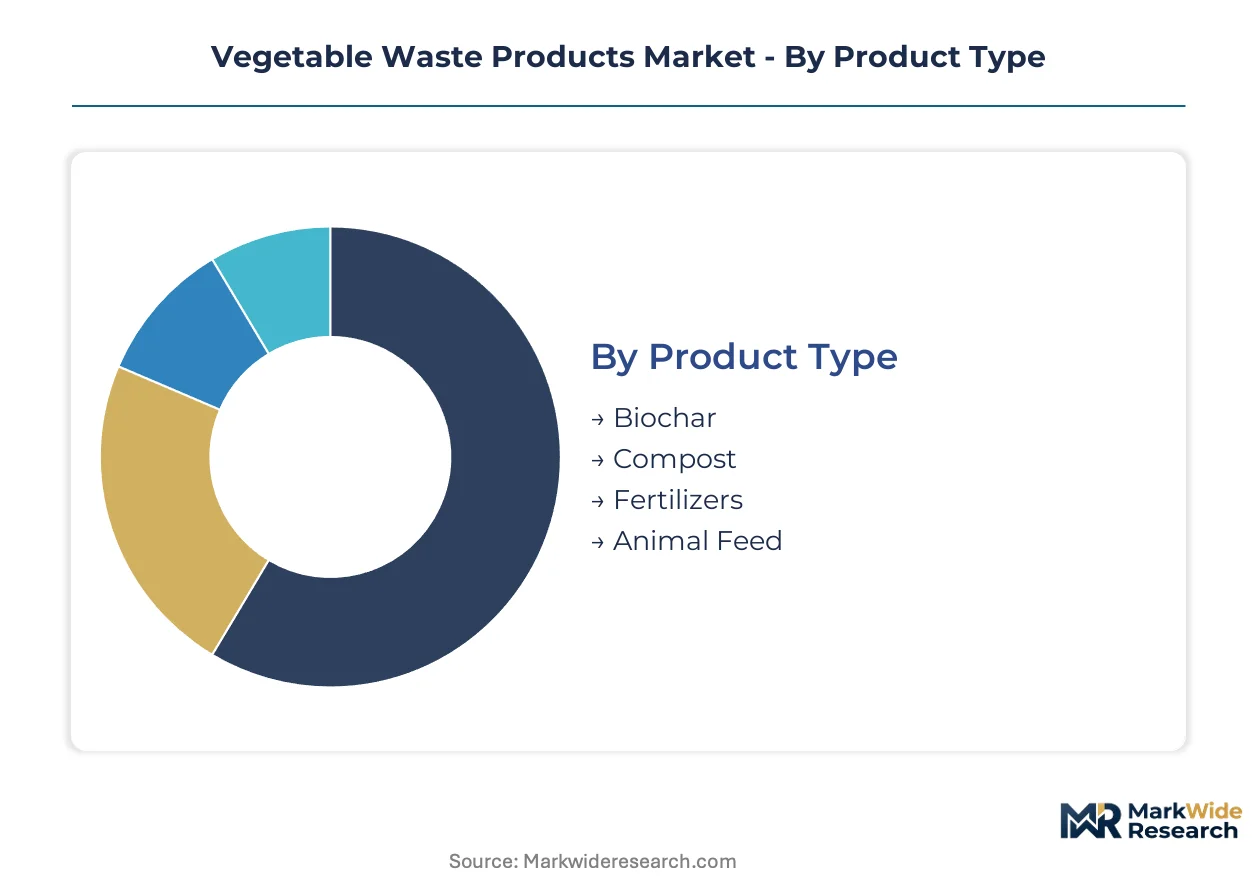
Vegetable waste processing creates divergent value streams depending on conversion pathway and buyer sophistication. Segmentation reveals where infrastructure investments concentrate versus where premium pricing emerges from carbon certification and soil health premiums.
Product Type:
Use-case spectrum spans soil amendment commodity markets through specialized carbon removal credit generation.
- Compost:Mature aerobic digestion infrastructure produces standardized soil amendments with established agricultural offtake. German arable farming cooperatives lock in multi-year supply contracts to replace synthetic nitrogen under national climate neutrality commitments.
- Biochar:Pyrolysis-derived stable carbon commands permanence certification premiums in corporate net-zero procurement. French and Dutch food processors consolidate supplier relationships with certified biochar facilities that provide audit-ready carbon accounting under EU CSRD requirements.
- Fertilizers:Processed digestate with standardized N-P-K labeling serves commercial agriculture requiring predictable nutrient delivery.
- Animal Feed:Dehydrated and pelletized vegetable residues meet livestock nutrition specifications in regions with feed grain price volatility.
Established volume favors Compost; emerging adoption favors Biochar.
End Use Industry:
Customer sophistication tiers separate commodity bulk buyers from premium-seeking corporate sustainability officers.
- Agriculture:Arable farming cooperatives in the Rhine-Ruhr corridor underwrite dedicated pipeline infrastructure to anaerobic digestion clusters. Five to seven-year digestate supply agreements with synthetic fertilizer benchmark escalation clauses displace spot market transactions.
- Bioenergy:Biogas offtake agreements indexed to wholesale natural gas benchmarks create dual revenue streams from energy credits and digestate sales. German facilities achieve highest unit economics where grid connection costs are lowest.
- Landscaping:Municipal parks departments and golf courses procure certified compost for turf management with lower contaminant threshold requirements than food-crop applications.
- Food Processing:Industrial producers under EU Green Deal organic waste diversion mandates secure certified waste-derived inputs, reconfiguring procurement relationships with agricultural offtake buyers.
Agriculture commands absolute tonnage; Bioenergy captures steepest expansion trajectory from energy credit monetization.
Processing Method:
Capital intensity and throughput velocity determine processor scale economics and geographic deployment patterns.
- Anaerobic Digestion:Continuous stirred-tank reactor designs achieve higher biogas yields per ton of vegetable waste, improving unit economics for mid-scale processors. Asset-light leasing models reconfigure capital barriers across European municipalities.
- Aerobic Digestion:Open windrow composting dominates volume flows due to mature infrastructure and lowest capital requirements. Seasonal supply volatility in Southern European harvest windows creates year-round processing capacity underutilization in Northern facilities.
- In-vessel Composting:Hotels and institutional caterers in the Netherlands install on-site systems to meet corporate ESG targets and reduce disposal costs. SUEZ specializes in these systems designed for supermarket and hotel chains.
- Fermentation:Controlled microbial conversion produces specialized feed ingredients and biochemical precursors with higher value capture than energy or amendment pathways.
Aerobic Digestion holds installed base dominance; Anaerobic Digestion attracts incremental capital deployment.
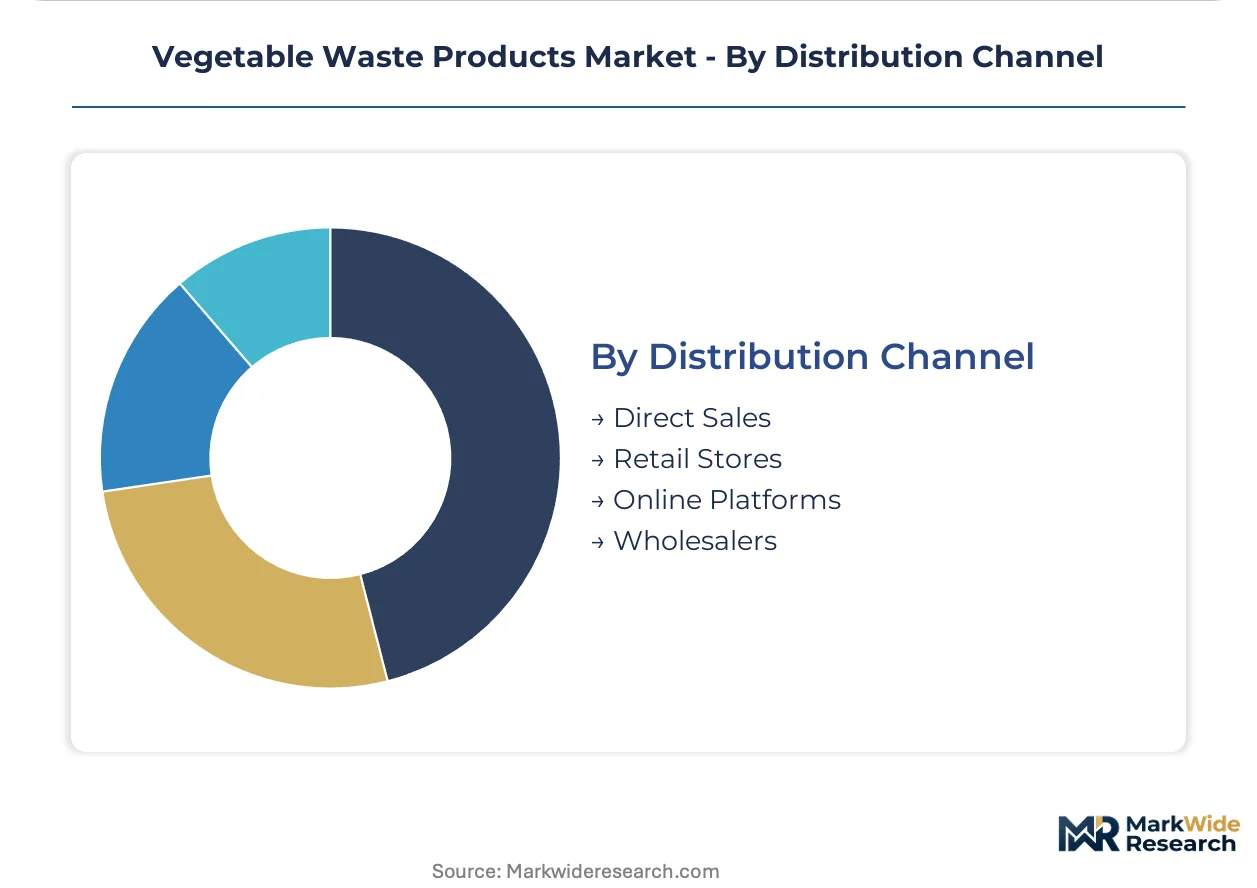
Distribution Channel:
Channel control determines feedstock quality assurance and carbon accounting traceability for Scope 3 disclosure.
- Direct Sales:French retail consolidation creates centralized waste streams that bypass municipal collection, enabling processor control over feedstock quality and volume. Long-term contracting displaces spot transactions.
- Wholesalers:Aggregate compost and digestate from multiple processors for agricultural supply cooperatives with less stringent chain-of-custody requirements.
- Retail Stores:Bagged consumer compost serves home gardening markets with premium pricing per kilogram but minimal aggregate volume.
- Online Platforms:Emerging channel for specialized biochar products targeting urban gardeners and carbon-conscious consumers seeking delivery convenience.
Direct Sales concentrate industrial procurement; Wholesalers intermediate commodity agriculture supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal organic waste diversion mandates are reconfiguring procurement relationships between processors and agricultural offtake buyers across Germany, France, and the Netherlands. National climate neutrality commitments lock in multi-year digestate supply contracts that displace spot market transactions. Processing capacity concentrates in industrial corridors with direct pipeline infrastructure to surrounding farmland.
Germany
Arable farming cooperatives in the Rhine-Ruhr corridor underwrite dedicated pipeline infrastructure to anaerobic digestion clusters. The Federal Immission Control Act enforces strict biogas facility emissions standards that shape technology selection. Continuous stirred-tank reactor designs in Lower Saxony achieve higher biogas yields per ton of vegetable waste, improving unit economics for mid-scale processors.
France
Retail consolidation creates centralized waste streams that bypass municipal collection, enabling processor control over feedstock quality and volume. The national energy regulator certifies biogas injection into natural gas grids under renewable energy purchase obligations. French food processors consolidate supplier relationships with certified composting and biochar facilities that provide audit-ready carbon accounting under EU CSRD requirements.
Netherlands
Hotels and institutional caterers install on-site in-vessel composting systems to meet corporate ESG targets and reduce disposal costs. The national waste management framework mandates source separation of organic waste from commercial generators. Amsterdam-Rotterdam corridor facilities achieve highest unit economics where grid connection costs for biogas offtake remain lowest.
Italy
Seasonal supply volatility during Mediterranean harvest windows creates year-round processing capacity underutilization in Northern European facilities. The national biogas decree establishes feed-in tariff mechanisms for agricultural waste-derived energy. Po Valley agricultural cooperatives pilot integrated pyrolysis-anaerobic digestion configurations to maximize revenue per ton of incoming vegetable waste.
United States
EPA Part 503 pathogen reduction testing extends product release cycles by 30-60 days, tying up working capital in inventory. State-level organic waste bans in California and Massachusetts mirror EU landfill diversion targets. Republic Services anchors position through long-term municipal contracts that guarantee feedstock volumes across Southwest and Southeast collection territories.
Vegetable Waste Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent scale and certification requirements. Integrated waste management conglomerates leverage collection infrastructure to secure captive feedstock pipelines. Three archetypes dominate: municipal-contract anchor firms, supermarket-chain specialists, and carbon-certification premium processors. Competitive moves concentrate on long-term offtake contracting and in-vessel system retrofit partnerships.
Within the integrated infrastructure tier, Veolia and Waste Management, Inc. represent channel-controlling archetypes that leverage collection-to-processing networks. SUEZ occupies a specialist position exemplifying the supermarket-and-hotel-chain focus. Republic Services anchors the municipal-contract model with guaranteed volume structures. These three firms collectively illustrate how feedstock security separates sustainable operations from spot-market-dependent competitors.
| Leading Market Players |
|---|
| Veolia |
| Renewi |
| SUEZ |
| Waste Management, Inc. |
| Republic Services |
| Biffa |
| FCC Environment |
| Waste Connections |
| Covanta |
| Others |
Value Network & Pricing Analysis
Overcapacity in Northern European anaerobic digestion facilities during Mediterranean off-seasons compresses spot-market digestate prices while contract premiums widen. German processors leverage guaranteed feedstock pipelines from municipal collection networks to sustain pricing power against seasonal volatility.
Pricing Analysis
Permanence certification grade creates the primary spread between commodity digestate and premium biochar. Contract-based long-term offtake agreements dominate, with five to seven-year synthetic fertilizer benchmark escalations locking in agricultural buyers. Price differentiation rests on carbon credit eligibility and contaminant thresholds under EU REACH. Cost compression in standard compost runs through energy-indexed biogas offtake exposure. Smallholder cooperatives exhibit highest price sensitivity; corporate net-zero procurement programs show lowest.
Supply Chain Analysis
Export-control regimes on pyrolysis reactor technology limit biochar production equipment flows into Southern European markets. Geographic supply concentrates in Germany, France, and the Netherlands where anaerobic digestion clusters anchor feedstock collection. Raw material dependencies include agricultural harvesting residues, food processing slurry, and supermarket retail waste. Single-source vulnerability concentrates in specialized in-vessel composting system manufacturing. Distribution runs through direct sales to agricultural cooperatives and municipal contract networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in vegetable waste valorization accelerates as EU Green Deal landfill diversion mandates force industrial food producers into certified procurement relationships.
For Market Incumbents: Entrench feedstock security through backward integration into municipal collection contracts before supermarket chain direct partnerships consolidate. Expand in-vessel composting retrofit capacity in the Netherlands and France where corporate ESG targets drive on-site adoption. Counter anaerobic digestion technology leasing models with dedicated pipeline infrastructure investments in the Rhine-Ruhr corridor.
For New Entrants and Emerging Players: Establish a beachhead in carbon credit certification services for biochar permanence verification where audit-ready documentation commands premium pricing. Target Italian and Spanish seasonal harvest surplus aggregation to feed Northern European processing capacity during peak windows. Pursue French retail consolidation partnerships as the primary go-to-market angle for guaranteed volume contracts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light anaerobic digestion leasing models, improving returns for mid-scale processor rollups. Long-term viability hinges on regulatory carbon accounting permanence that sustains biochar premium structures. Acquire specialist firms with EU CSRD-compliant chain-of-custody systems. Monitor biogas grid injection tariff revisions as the critical inflection signal for digestate project economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Rhine-Ruhr corridor agricultural cooperatives underwrite dedicated pipeline infrastructure to anaerobic digestion clusters. |
| Backward Integration | Veolia leverages collection-to-compost networks to secure captive feedstock pipelines across European municipalities. |
| Green Certification Program | French and Dutch food processors consolidate supplier relationships with biochar facilities providing audit-ready carbon accounting. |
| Capacity Expansion | German facilities achieve highest unit economics where continuous stirred-tank reactor designs improve biogas yields per ton. |
| Joint Venture | Italian Po Valley cooperatives pilot integrated pyrolysis-anaerobic digestion configurations to maximize revenue per ton. |
Research Methodology
A spread of perspectives from anaerobic digestion facility operators, agricultural cooperative procurement managers, supermarket sustainability officers, and municipal waste collection directors converged on the working assumptions. Primary fieldwork combined with secondary validation from EU Green Deal implementation reports, EPA Part 503 regulatory filings, national biogas decree documentation, and agricultural supply cooperative contract databases. Bottom-up processor capacity modeling triangulated against top-down organic waste generation estimates.
Demand-supply balance dynamics across compost, biochar, and digestate output categories shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, processing method, end-use industry, and distribution channel complexity. CAGRs were derived from feedstock volume growth trajectories and unit economics evolution. Industry-specific forecast inputs incorporated biogas grid injection tariff structures and synthetic fertilizer price benchmarks.
Stress conditions across natural gas price volatility, seasonal feedstock availability, and REACH contaminant threshold enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU CSRD disclosure timeline adherence and carbon credit methodology permanence certification. Material shifts in EU Green Deal landfill diversion enforcement or biogas offtake tariff structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Fish Oil Alternatives Market
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Gluten Substitute Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Vegetable Proteins Market