
 Belgium POS Terminals Market | 2026-2036
Belgium POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium POS Terminals Market Outlook
Buyer concentration among Belgian hospitality chains is restructuring procurement patterns across the POS terminal supply base. Worldline leverages its entrenched banking relationships to sustain dominance in large-format retail deployments. SumUp competes aggressively on subscription-based pricing for independent merchants and food-service operators. Ingenico anchors the high-velocity transit segment with ruggedized terminal portfolios designed for Brussels Metro and De Lijn networks.
Belgium POS terminals comprise electronic payment acceptance devices integrating secure chip readers, NFC antennas, and encrypted communication modules for transaction authorization. These systems process card-present and contactless payments through certified hardware-software stacks that interface with acquiring banks and payment networks. Fixed POS terminals occupy the mature volume tier in Belgian supermarkets and department stores, while mobile terminals represent the fastest-expanding category as tableside payment and curbside delivery models proliferate across Flemish and Walloon hospitality venues. All-in-one systems concentrate margin pools through integrated inventory software and loyalty program management that commands premium pricing from mid-market retail chains.
The National Bank of Belgium enforces PSD2 compliance and strong customer authentication protocols that mandate biometric-capable terminal upgrades across the merchant base. GDPR requirements govern transaction data storage and customer consent architectures, compelling vendors to redesign cloud-based deployment offerings. Belgium's implementation of EU Digital Operational Resilience Act standards will impose additional cybersecurity certification burdens on terminal firmware and remote management platforms. Stakeholders must weigh cloud migration timelines against on-premises control priorities as regulatory complexity intensifies.
Market Dynamics
Belgian hospitality chains are consolidating procurement power, forcing terminal vendors to abandon transactional hardware sales in favor of integrated software-subscription bundles that lock in multi-year merchant relationships.
Growth Catalysts
- PSD2 Strong Customer Authentication:The National Bank of Belgium mandates biometric-capable terminal upgrades, compelling merchants across Flemish and Walloon regions to refresh installed bases.
- Contactless Payment Infrastructure:Brussels Metro and De Lijn transit networks are deploying NFC-enabled terminals at velocity, normalizing tap-to-pay behavior among commuters.
- Tableside Payment Models:Independent restaurants in Antwerp and Ghent are adopting mobile POS terminals to eliminate checkout friction and reduce labor allocation at payment terminals.
Market Restraints
- Semiconductor Component Volatility:Secure element chip supply concentrates among Asian foundries, exposing Belgian terminal assemblers to input cost swings and allocation rationing.
- GDPR Data Architecture Burden:Transaction storage and consent management requirements impose firmware redesign costs that compress margins on entry-level terminal SKUs.
- Cloud Migration Hesitation:Mid-market retailers in Wallonia retain on-premises transaction processing due to latency sensitivity and perceived cybersecurity exposure.
Strategic Opportunities
- EU Digital Operational Resilience Act:Upcoming cybersecurity certification mandates for terminal firmware create first-mover advantage for vendors pre-certifying remote management platforms.
- All-in-One System Convergence:Inventory software and loyalty program integration commands premium pricing from Brussels retail chains seeking unified commerce stacks.
- Curbside Delivery Payment:Flemish quick-service operators are unbundling fixed countertop terminals in favor of ruggedized mobile units for outdoor transaction capture.
Industry Challenges
- Embedded Systems Engineering Talent:Secure firmware development and PCI-DSS compliance expertise concentrates among experienced hires, constraining vendor R&D velocity.
- Legacy Terminal Integration:Belgian supermarkets operate heterogeneous terminal fleets spanning three certification generations, complicating unified reporting and remote update deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium POS Terminals Market |
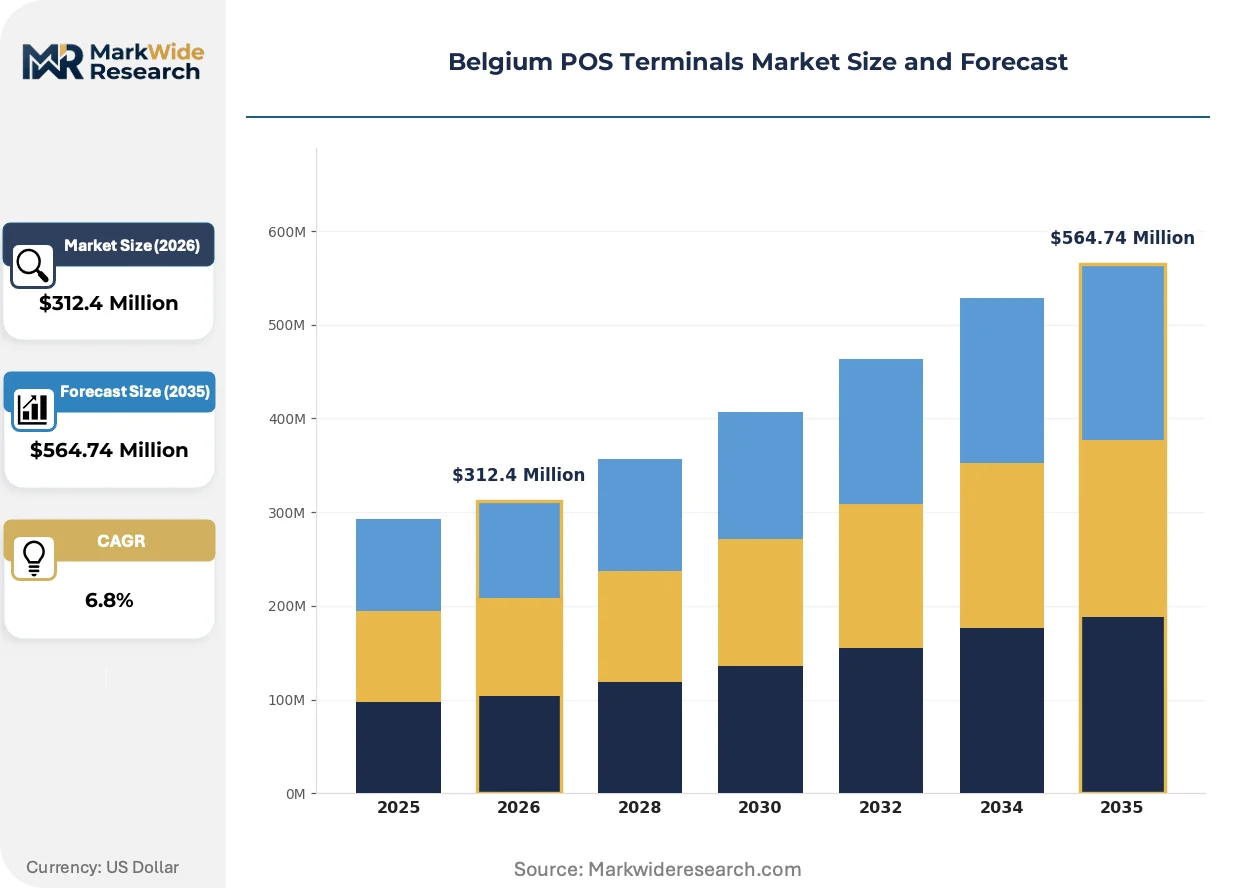
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Terminals, Fixed POS, All-in-One Systems, Self-Service Kiosks Technology: Contactless Payment, Magnetic Stripe, Chip-and-PIN, NFC End User: Retail, Hospitality, Transportation, Healthcare Deployment: Cloud-based, On-premises, Hybrid Solutions, Subscription Model |
| Companies Covered | Elavon, myPOS, Worldline, Viva Wallet, Payconiq by Bancontact, Ingenico, CCV, Loyaltek, SumUp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium POS Terminals Market Strategic Shifts
Belgian POS terminal architecture is pivoting from dedicated payment hardware toward software-defined platforms that absorb adjacent commerce functions. This convergence is compressing vendor differentiation and elevating ecosystem integration as the primary competitive battleground.
SoftPOS technology is electrifying merchant acquisition economics by converting standard Android devices into certified payment terminals without dedicated hardware. Flemish food-truck operators and pop-up retailers are adopting SoftPOS at pace, bypassing traditional terminal procurement cycles entirely. This capability is compressing addressable market volume for conventional mobile terminal manufacturers while expanding total payment acceptance penetration.
GDPR and the EU AI Act are imposing algorithmic transparency requirements on fraud detection modules embedded in terminal software stacks. Belgian vendors must now document automated decision-making logic for transaction risk scoring, adding compliance documentation burdens to product development timelines. Mid-market retail chains are responding by demanding vendor-provided liability indemnification for AI-driven chargeback decisions.
Subscription-based hardware-as-a-service contracts are displacing outright terminal purchases among independent Belgian merchants. Worldline and SumUp are unbundling device costs into monthly per-terminal fees that include software updates and warranty coverage. This shift is most visible in Brussels' dense hospitality corridor, where cash-flow-constrained operators prioritize operational expenditure predictability over capital ownership.
Belgium POS Terminals Market Segmentation
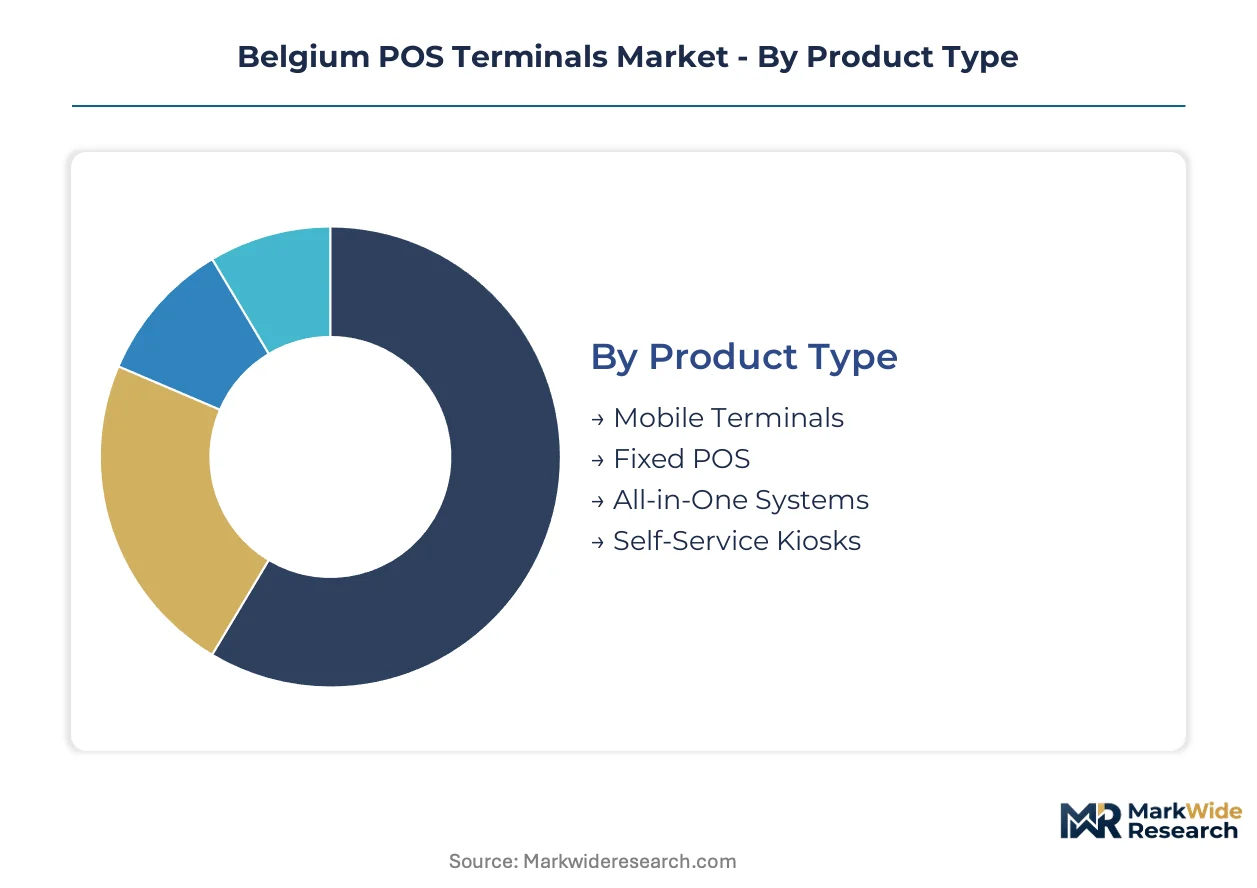
Belgian POS terminal procurement decisions pivot on payment velocity requirements, regulatory compliance burdens, and total cost of ownership across hardware generations. Terminal vendors must align product portfolios with distinct operational constraints in Brussels retail corridors versus Flemish hospitality clusters.
Product Type:
Merchant cash-flow sensitivity and tableside service intensity drive hardware format selection across Belgian commercial districts.
- Mobile Terminals:Battery-powered units with integrated receipt printers and 4G connectivity enable curbside payment capture. Antwerp and Ghent restaurants deploy these for tableside settlement to reduce labor friction at fixed checkout points. This segment gains share fastest as subscription pricing lowers entry barriers for independent operators.
- Fixed POS:Countertop devices with Ethernet tethering and high-throughput thermal printers anchor supermarket and department store checkout lanes. Brussels retail chains prioritize these for transaction reliability under peak load conditions. Volume concentrates here due to replacement cycles in established big-box formats.
- All-in-One Systems:Integrated inventory software and loyalty program management command premium positioning.
- Self-Service Kiosks:Customer-facing touchscreen units with integrated payment acceptance reduce staffed checkout requirements.
Volume sits with Fixed POS; growth tilts toward Mobile Terminals.
Technology:
Authentication mandates from the National Bank of Belgium are forcing infrastructure refresh decisions across merchant categories.
- Contactless Payment:NFC antenna arrays with sub-400ms transaction latency process tap-to-pay cards and mobile wallets. Brussels Metro and De Lijn transit networks normalize this behavior among daily commuters. This technology climbs the fastest as biometric authentication requirements render magnetic stripe obsolete.
- Chip-and-PIN:EMV-certified secure elements with PIN entry pads remain mandatory for high-value transactions. Belgian supermarkets retain these for fraud liability protection on purchases exceeding contactless limits. Deployment concentrates in established retail formats with legacy terminal estates.
- Magnetic Stripe:Legacy swipe readers persist only in transitional merchant environments.
- NFC:Near-field communication modules enable peer-to-peer and wearable payment acceptance.
Chip-and-PIN holds installed base dominance; contactless infrastructure expands most quickly.
End User:
Vertical-specific transaction patterns and customer throughput requirements shape terminal specification demands.
- Retail:Multi-lane checkout environments with barcode scanner integration and high-volume receipt printing. Brussels department stores and Flemish supermarket chains prioritize throughput reliability and remote management capabilities.
- Hospitality:Tableside and curbside payment scenarios with tip-adjustment workflows and split-bill functionality. Antwerp and Ghent independent restaurants drive mobile terminal adoption for service efficiency.
- Transportation:Ruggedized terminals with rapid transaction cycling for high-velocity fare collection.
- Healthcare:HIPAA-aligned data architectures with patient billing integration and insurance card reading.
Retail commands procurement volume; hospitality shows steepest expansion trajectory.
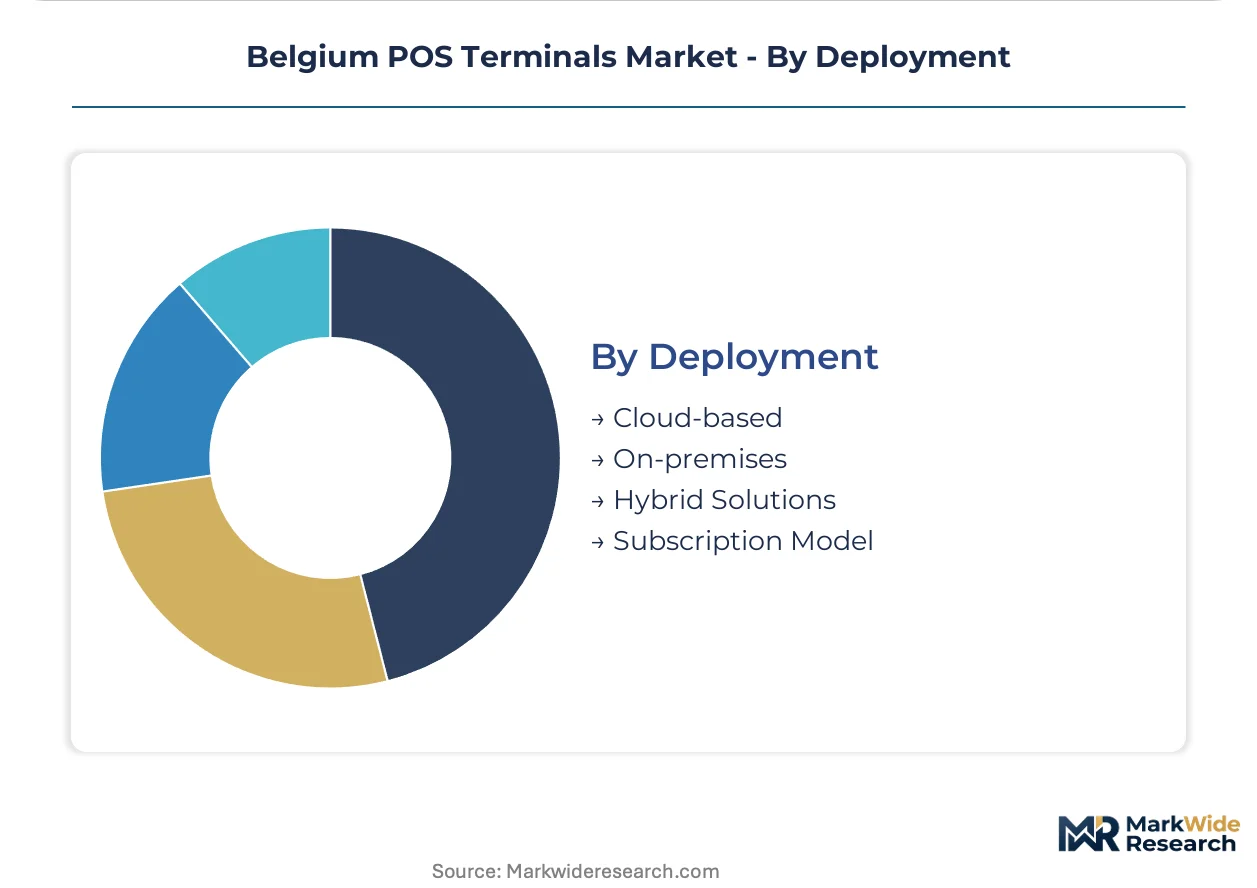
Deployment:
Data sovereignty preferences and latency sensitivity fragment cloud migration timelines across Belgian merchant segments.
- Cloud-based:Remote firmware management and real-time transaction analytics reduce on-site IT overhead. Brussels hospitality chains favor these for multi-location visibility and centralized reporting.
- On-premises:Local transaction processing with offline authorization capability satisfies Wallonia mid-market retailers concerned with connectivity resilience and perceived cybersecurity exposure.
- Hybrid Solutions:Edge processing with cloud synchronization balances latency and analytics requirements.
- Subscription Model:Hardware-as-a-service contracts bundle devices, software, and warranty into monthly per-terminal fees.
On-premises retains Wallonia merchant preference; subscription pricing gains traction in Brussels hospitality corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's semiconductor supply chain feeds into terminal assembly operations across Flanders and Wallonia. The country's dense retail corridor concentrates demand in Brussels while transit networks in Flemish cities drive contactless infrastructure deployment.
Flanders
Antwerp and Ghent hospitality clusters are accelerating mobile terminal adoption for tableside payment workflows. The Flemish Government's digital economy incentives subsidize contactless infrastructure upgrades for independent merchants. De Lijn transit authority is deploying NFC-enabled terminals across bus and tram networks, normalizing tap-to-pay behavior among daily commuters.
Wallonia
Liège and Namur retail operators retain on-premises transaction processing due to latency sensitivity and data sovereignty preferences. The National Bank of Belgium's PSD2 enforcement mandates biometric-capable terminal refreshes across the region. Charleroi manufacturing zones host terminal assembly operations serving mid-market retail chains with hybrid deployment models.
Brussels-Capital Region
Brussels' dense retail corridor commands premium all-in-one systems with integrated inventory and loyalty management. The region's implementation of EU Digital Operational Resilience Act standards imposes cybersecurity certification burdens on terminal firmware. Ixelles and Saint-Gilles hospitality districts are unbundling fixed countertop terminals in favor of subscription-based mobile units.
Netherlands
Amsterdam and Rotterdam retail chains influence Belgian procurement patterns through cross-border supply chain integration. The Dutch central bank's alignment with ECB payment oversight creates regulatory coherence for terminal vendors operating in both markets. Eindhoven semiconductor clusters supply secure element components to Belgian terminal assemblers.
France
Lille and French border retail operators create spillover demand for Belgian terminal vendors with bilingual service capabilities. The French Prudential Supervision and Resolution Authority's payment oversight parallels Belgian regulatory frameworks, easing vendor compliance burdens. Lille metropolitan area transit networks are deploying compatible contactless systems that interoperate with Brussels Metro infrastructure.
Belgium POS Terminals Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-defined platforms and SoftPOS alternatives. The vendor base stratifies across banking-integrated incumbents, subscription-native challengers, and transit-specialized operators. Three archetypes dominate: legacy acquirer-integrated providers, mobile-first subscription platforms, and ruggedized hardware specialists. Competitive moves center on integrated software-subscription bundling and pre-certification for EU cybersecurity mandates.
Within the banking-integrated tier, Worldline and Ingenico exemplify entrenched positioning through financial institution relationships. SumUp occupies the subscription-native challenger archetype with aggressive per-terminal pricing for independent hospitality operators. Among transit-specialized providers, CCV represents ruggedized deployment expertise across Belgian public transport networks.
| Leading Market Players |
|---|
| Elavon |
| myPOS |
| Worldline |
| Viva Wallet |
| Payconiq by Bancontact |
| Ingenico |
| CCV |
| Loyaltek |
| SumUp |
| Others |
Value Chain & Pricing Dynamics
Belgian hospitality chain procurement consolidation is forcing terminal vendors to absorb firmware redesign costs for GDPR-compliant data architectures, compressing margins on entry-level SKUs while elevating premium all-in-one system pricing power. This demand-side pressure reshapes how supply must configure—vendors now prioritize subscription bundling over transactional hardware sales to lock in multi-year merchant relationships and stabilize revenue streams.
Pricing Analysis
Warranty coverage and remote firmware management unbundling distinguishes vendor positioning across Belgian merchant tiers. Three-tier pricing structure across premium, standard, and economy levels separates all-in-one inventory-integrated systems from fixed countertop units and basic mobile terminals. Price differentiation hinges on PCI-DSS certification grade and after-sales service bundling. Cost compression in entry-level mobile SKUs is intensifying because GDPR firmware redesign burdens concentrate there. Independent Antwerp and Ghent restaurants exhibit highest price sensitivity; Brussels retail chains commanding multi-location deployments show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Belgian supermarket chains and transit authorities, while value-added resellers serve independent hospitality operators. Secure element chip supply concentrates in Taiwan, South Korea, and China, exposing Belgian terminal assemblers to allocation rationing. NFC antenna modules and EMV-certified processors draw from these Asian foundries. Single-source vulnerability in secure element fabrication presents structural risk. Distribution runs through banking-integrated acquirers for large-format retail and subscription-native platforms for independent merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where EU Digital Operational Resilience Act cybersecurity certification mandates will force sub-scale firmware vendors to exit, concentrating share among pre-certified platform operators.
For Market Incumbents: Deepen banking relationship moats by pre-certifying remote management platforms for EU Digital Operational Resilience Act standards before enforcement deadlines. Anchor cloud-based deployment offerings with biometric-capable terminal portfolios to capture PSD2-mandated refresh cycles. Threat substitution from SoftPOS technology demands defensive software-subscription bundling that absorbs adjacent commerce functions beyond payment acceptance. For New Entrants and Emerging Players: Wallonia mid-market retailers retaining on-premises transaction processing represent an underserved buyer archetype with distinct latency sensitivity and data sovereignty preferences. Flemish food-truck operators and pop-up retailers adopting SoftPOS bypass traditional procurement entirely, creating white-space for Android-native payment platforms without dedicated hardware. Curbside delivery payment workflows in Flemish quick-service operators offer the most penetrable entry point. Go-to-market through subscription-native mobile-first positioning avoids direct confrontation with banking-integrated incumbents. For Investors and Strategic Acquirers: The window for entry favors firmware pre-certification specialists with EU cybersecurity compliance expertise. Long-term viability hinges on software-defined platform convergence that absorbs inventory, loyalty, and analytics functions. Acquisition target archetype: ruggedized hardware specialists with transit network relationships and embedded systems engineering talent. Signal to watch: National Bank of Belgium enforcement intensity on PSD2 biometric upgrade timelines as merchant refresh inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EU Cybersecurity Pre-Certification | First-mover positioning for Digital Operational Resilience Act compliance captures mandated refresh demand from Belgian merchants. |
| Software-Subscription Bundling | Integrated inventory and loyalty management commands premium pricing from Brussels retail chains seeking unified commerce stacks. |
| SoftPOS Platform Development | Android-native payment acceptance bypasses hardware procurement cycles for Flemish food-truck and pop-up retail segments. |
| Transit Network Specialization | Ruggedized terminal portfolios for Brussels Metro and De Lijn networks normalize tap-to-pay behavior among daily commuters. |
| GDPR-Compliant Cloud Migration | Redesigned data architectures satisfy National Bank of Belgium oversight while reducing on-site IT overhead for hospitality chains. |
Study Parameters
Independent corroboration across terminal vendor product managers, Belgian hospitality chain procurement directors, and National Bank of Belgium regulatory affairs specialists underwrites the qualitative findings. Primary interviews with payment network integration engineers, secure firmware developers, and De Lijn transit authority technology officers combined with secondary validation. Secondary sources include National Bank of Belgium PSD2 implementation guidance, EU Digital Operational Resilience Act draft standards, PCI Security Standards Council certification databases, and Belgian retail federation merchant surveys. Bottom-up terminal shipment modeling and top-down payment transaction volume analysis triangulate market sizing.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon. Segmentation dimensions modeled include product type, authentication technology, end-user vertical, and deployment architecture. CAGRs derive from terminal refresh cycle analysis, merchant adoption curve fitting, and subscription pricing penetration assumptions. Industry-specific forecast inputs incorporate National Bank of Belgium enforcement timelines for biometric-capable terminal mandates and De Lijn transit network deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to secure element chip supply allocation and EU cybersecurity certification timeline shifts. Forecasts reflect assumptions about merchant cloud migration willingness and SoftPOS technology substitution rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Germany POS Terminal Market
Payments
Japan POS Terminals Market
Payments
Wearable Payments Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Latin America Payment Gateway Market
Payments
Social Media Payment Solution Market
Payments
Bitcoin Payments Market
Payments
Cloud Billing Market
Payments
Mobile Wallet Market
Payments
UAE Card Payments Market
Payments
Money Transfer Agencies Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
US Virtual Cards Market
Payments
North America Real Time Payment Market
Payments
Australia Payments Market
Payments
US Buy Now Pay Later Services Market