
 Middle East and Africa Real Time Payments Market | 2026-2036
Middle East and Africa Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Real Time Payments Market Foresight
The capability gap between cloud-native infrastructure and legacy core banking systems is rotating competitive advantage toward fintech specialists. Network International Holdings Plc leverages its merchant-acquiring scale across the Gulf Cooperation Council to dominate cross-border settlement corridors. Safaricom Plc anchors mobile money ubiquity through its M-Pesa platform, while Interswitch Ltd competes across West African banking integrations with API-first switching architecture.
Real time payments denote electronic fund transfers settled within seconds through continuous gross settlement or deferred net settlement rails, operating on ISO 20022 messaging standards with 24/7 availability and irrevocable finality. Their primary commercial purpose is eliminating float periods between payer debit and payee credit, thereby reducing working capital friction for businesses and enabling just-in-time liquidity for consumers. Mobile banking channels lead transaction volume growth due to smartphone penetration and USSD fallback compatibility, while payment aggregators capture expanding margin pools by unifying fragmented banking APIs for merchant acceptance. Government agencies represent the fastest-growing end-user segment as fiscal digitization replaces cash-based social transfers and procurement.
Saudi Arabia's Saudi Arabian Monetary Authority and South Africa's South African Reserve Bank mandate real-time gross settlement participation for licensed banks, tightening interoperability standards and accelerating infrastructure investment. Nigeria's Central Bank enforces tiered KYC requirements through its National Financial Inclusion Strategy, shaping product design for micro-transaction wallets. Stakeholders must monitor regulatory divergence between Gulf Cooperation Council open-banking frameworks and sub-Saharan mobile-money licensing regimes to anticipate compliance cost trajectories.
Market Dynamics
Central bank mandates for instant settlement infrastructure are compressing float periods and forcing incumbent banks to modernize core systems or cede transaction volume to API-native aggregators.
Growth Catalysts
- SAMA Real-Time Payments System:Saudi Arabia's central bank mandates 24/7 gross settlement participation for licensed banks, tightening interoperability standards and accelerating infrastructure investment across the Gulf.
- Unbanked mobile wallet adoption:Smartphone penetration combined with USSD fallback compatibility is concentrating transaction volume growth among previously cash-dependent populations in Nigeria and Kenya.
- Fiscal digitization mandates:Government agencies across the region are replacing cash-based social transfers and procurement with instant disbursement rails, creating the fastest-expanding end-user category.
Market Restraints
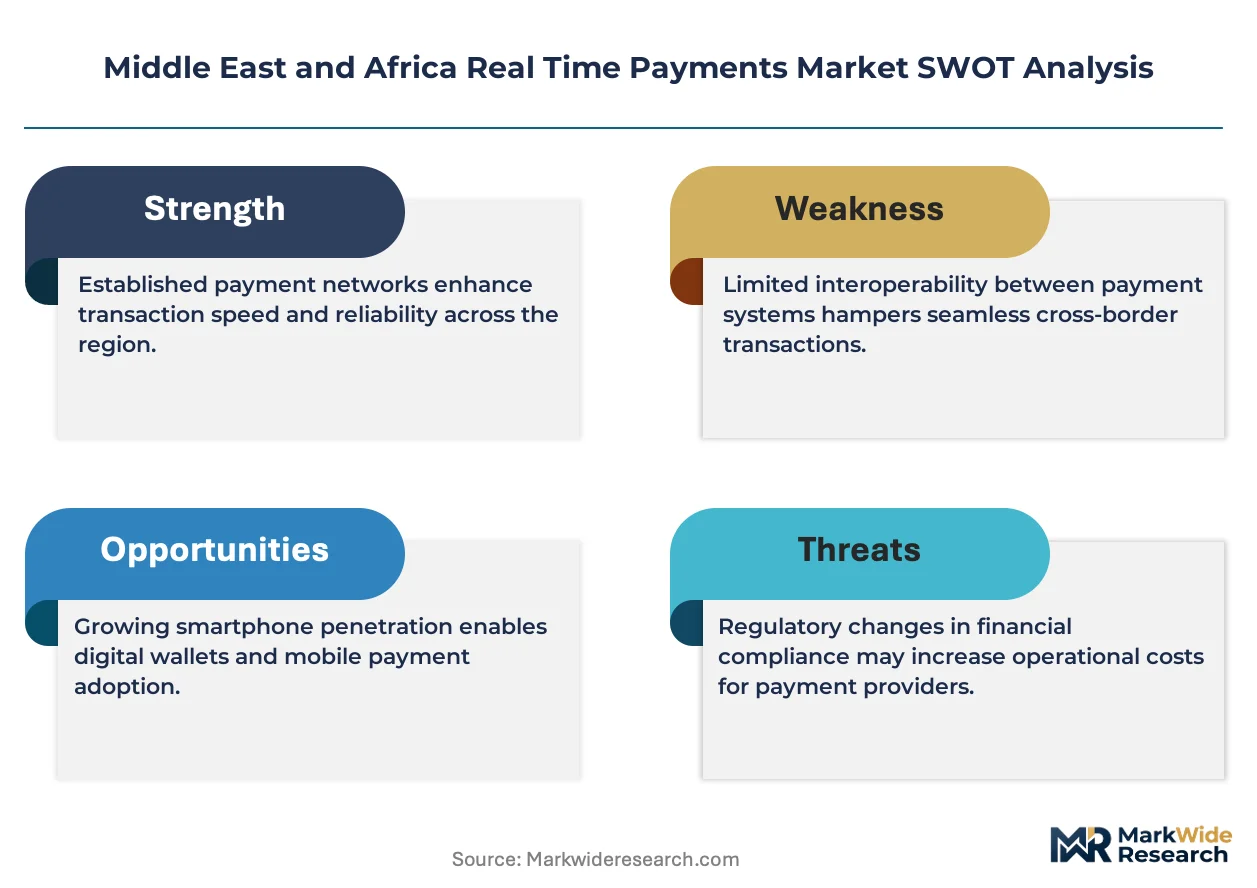
- Legacy core banking debt:Incumbent institutions face prohibitive modernization costs to achieve ISO 20022 messaging compliance, creating a capability gap that favors cloud-native specialists.
- Regulatory divergence friction:Gulf Cooperation Council open-banking frameworks operate on divergent timelines from sub-Saharan mobile-money licensing regimes, elevating compliance cost trajectories for cross-regional operators.
- Interoperability fragmentation:Nigeria's tiered KYC requirements through its National Financial Inclusion Strategy create product design constraints that limit wallet functionality at lower verification tiers.
Strategic Opportunities
- Cross-border settlement corridors:Merchant-acquiring scale across the Gulf Cooperation Council creates white space for unified clearing infrastructure connecting GCC rails with East African mobile money networks.
- API-first switching architecture:West African banking integrations remain fragmented, creating opportunity for unified aggregator platforms that normalize disparate bank APIs for merchant acceptance.
- Just-in-time liquidity products:Consumer demand for instant fund availability is enabling new credit and savings products built on real-time balance visibility and irrevocable settlement finality.
Industry Challenges
- ISO 20022 migration complexity:Banks must overhaul messaging infrastructure while maintaining 24/7 uptime, straining operational teams and requiring specialized integration expertise that remains scarce regionally.
- Talent scarcity in cloud-native architecture:The capability gap between legacy mainframe operations and containerized settlement systems is forcing institutions to compete for finite DevOps and API engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Real Time Payments Market |
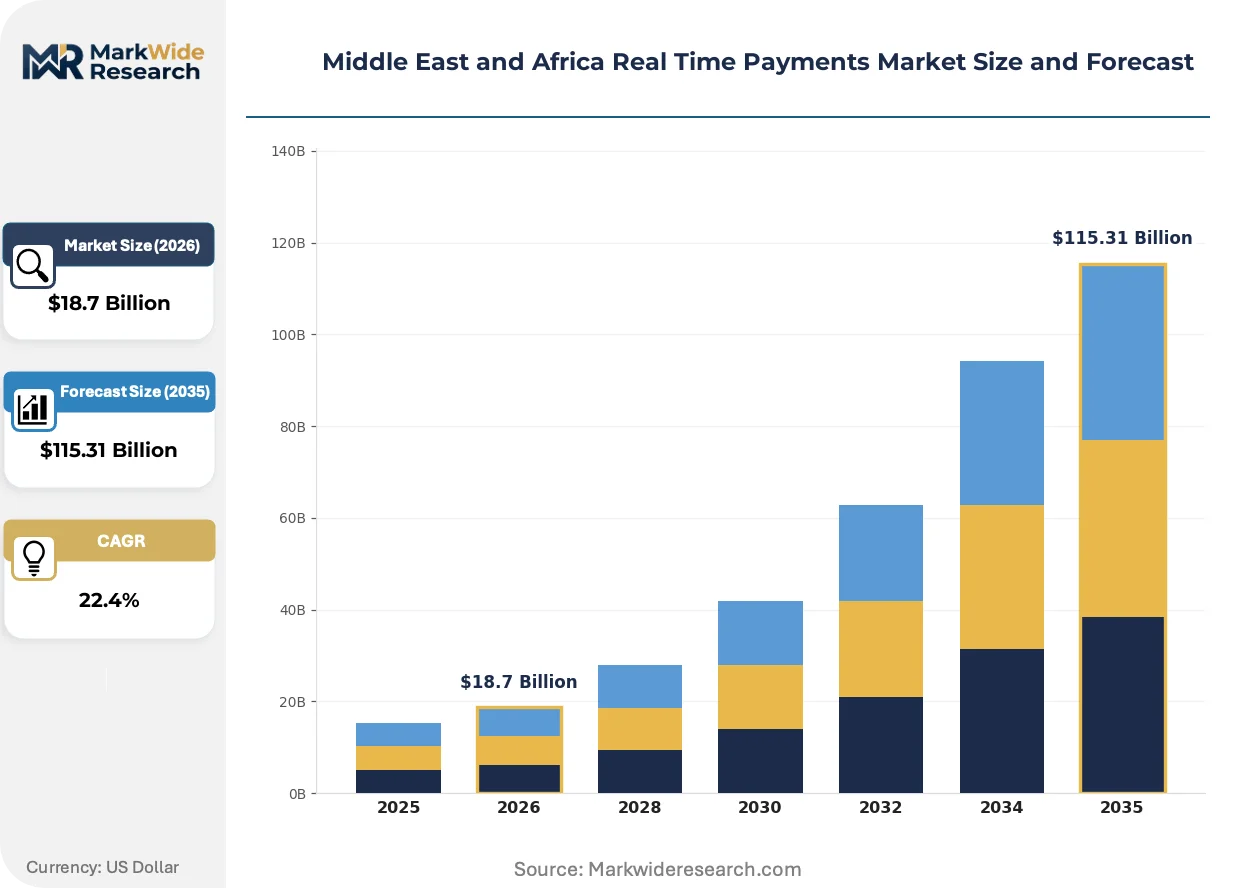
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Channel: Instant Messaging, Mobile Banking, Online Banking, POS Terminal Service Provider: Banking Institutions, Fintech Companies, Payment Aggregators, Card Networks End User: Consumers, Small Businesses, Enterprises, Government Agencies Transaction Size: Micro Transactions, Small Transactions, Medium Transactions, Large Transactions |
| Companies Covered | Network International Holdings Plc, Interswitch Ltd, Safaricom Plc, Opay, PalmPay Technology Co. Ltd, Paytabs, ACI Worldwide Inc, Fiserv Inc, Mastercard Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Real Time Payments Market Shifts & Advancements
Cloud-native settlement infrastructure is actively compressing the competitive window for incumbent processors, while regulatory mandates for instant finality are reshaping product architecture across both banking and fintech segments.
Deferred net settlement rails built on containerized microservices are supplanting batch-processed legacy mainframes that previously dominated high-value clearing. Tier-1 banks in South Africa and the UAE are adopting these architectures fastest, pressured by central bank deadlines for 24/7 availability. This shift is compressing vendor consolidation timelines as institutions abandon multi-year core replacement projects in favor of API-overlay strategies.
South Africa's Reserve Bank mandates for real-time gross settlement participation are forcing licensed institutions to achieve continuous processing capability or face exclusion from high-value payment clearing. The industrial consequence is accelerated outsourcing of settlement infrastructure to specialized cloud providers. Smaller banks and payment service providers are responding fastest, leveraging managed service arrangements to meet compliance deadlines without capital-intensive core modernization.
Merchant acceptance patterns are rotating toward unified aggregator platforms that normalize fragmented banking APIs into single integration points. Traditional direct bank integrations are losing share among mid-market retailers and digital commerce platforms that prioritize development velocity over bilateral commercial terms. This behavioral shift is most visible in Nigeria's Lagos corridor and Kenya's Nairobi tech cluster, where payment aggregators capture expanding margin pools by unifying access to multiple settlement rails.
Middle East and Africa Real Time Payments Market Segmentation
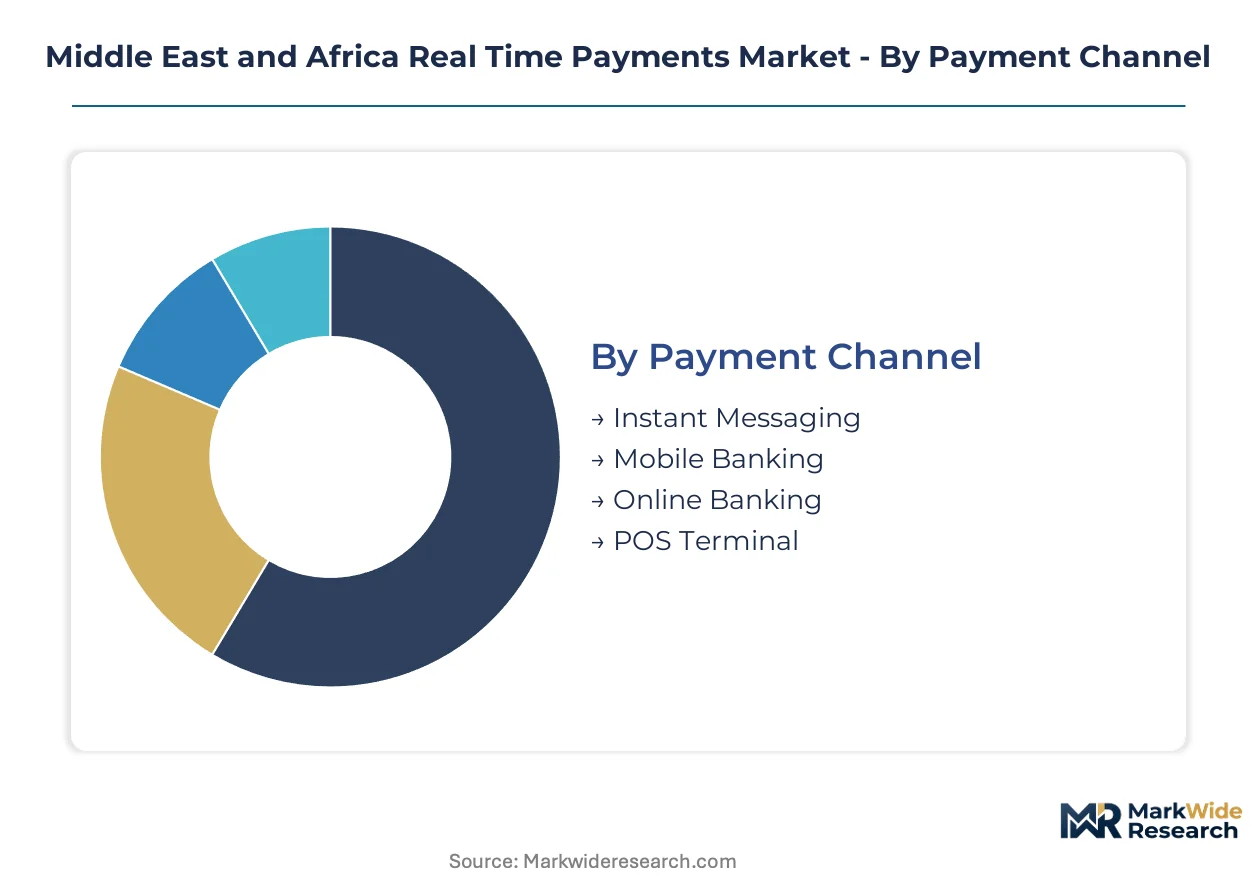
Segmentation reveals how regulatory mandates and infrastructure maturity concentrate demand across distinct operational layers in Middle East and Africa real time payments. Channel preferences diver sharply between Gulf Cooperation Council banking modernization and sub-Saharan mobile-first adoption, while end-user digitization timelines reshape provider competitive positioning.
Payment Channel:
Saudi Arabian Monetary Authority and South African Reserve Bank mandates for 24/7 settlement availability are compressing channel migration timelines, with compliance deadlines forcing institutional choices between native infrastructure and third-party aggregation.
- Mobile Banking:Smartphone penetration combined with USSD fallback compatibility enables transaction growth among previously cash-dependent populations. Demand concentrates in Nigeria's Lagos corridor and Kenya's Nairobi tech cluster, where tiered KYC requirements through the National Financial Inclusion Strategy shape wallet functionality at lower verification tiers.
- Instant Messaging:Embedded payment interfaces within messaging platforms leverage existing user authentication and network effects for peer-to-peer transfers. Nigeria and Kenya lead deployment velocity, driven by unbanked population onboarding and social transfer digitization mandates from government agencies.
- Online Banking:Browser-based interfaces remain dominant for corporate treasury operations and high-value settlements across Gulf Cooperation Council institutions.
- POS Terminal:Merchant-acquiring hardware supports card-present real time settlement, with Network International Holdings Plc leveraging scale across UAE and Saudi Arabia corridors.
Mobile Banking handles the majority of throughput; Instant Messaging is expanding most quickly on share.
Service Provider:
Cost tier differentiation separates capital-intensive infrastructure operators from lean API-overlay specialists, with central bank compliance deadlines accelerating outsourcing decisions among smaller institutions.
- Payment Aggregators:Unified platforms normalizing fragmented banking APIs into single integration points capture expanding margin pools among mid-market retailers and digital commerce platforms. Nigeria's Lagos corridor and Kenya's Nairobi tech cluster show the fastest behavioral shift toward aggregator-led merchant acceptance, prioritizing development velocity over bilateral bank terms.
- Fintech Companies:Cloud-native specialists exploit the capability gap between legacy core banking systems and modern settlement infrastructure, offering managed service arrangements that meet ISO 20022 compliance without capital-intensive core replacement. South African Reserve Bank deadlines are forcing accelerated outsourcing to these providers.
- Banking Institutions:Licensed banks face prohibitive modernization costs for continuous processing capability, with tier-1 institutions in South Africa and UAE adopting containerized microservices fastest.
- Card Networks:Existing rails adapt to real time finality requirements through overlay services, maintaining relevance in cross-border settlement corridors.
Banking Institutions retain the dominant share of settlement volume; Payment Aggregators are climbing the fastest on merchant acceptance penetration.
End User:
Application urgency varies across user categories, with government fiscal digitization creating the steepest demand expansion trajectory as cash-based social transfers and procurement convert to instant disbursement rails.
- Government Agencies:Fiscal digitization mandates are replacing cash-based social transfers and procurement with instant disbursement rails, creating concentrated demand for high-volume, low-value settlement infrastructure. Nigeria's Central Bank enforces tiered KYC requirements that shape product design for micro-transaction wallets serving beneficiary populations.
- Small Businesses:Working capital friction reduction drives adoption of just-in-time liquidity products built on real-time balance visibility and irrevocable settlement finality. Lagos and Nairobi tech clusters show concentrated demand among digitally native merchants seeking cashless settlement velocity.
- Consumers:Individual users demand instant fund availability for peer-to-peer transfers and retail purchases, with smartphone penetration enabling wallet adoption among previously unbanked populations.
- Enterprises:Corporate treasury operations require continuous gross settlement for high-value supplier payments and cross-border remittances.
Government Agencies represent the fastest-expanding category; Consumers maintain the largest absolute transaction count.
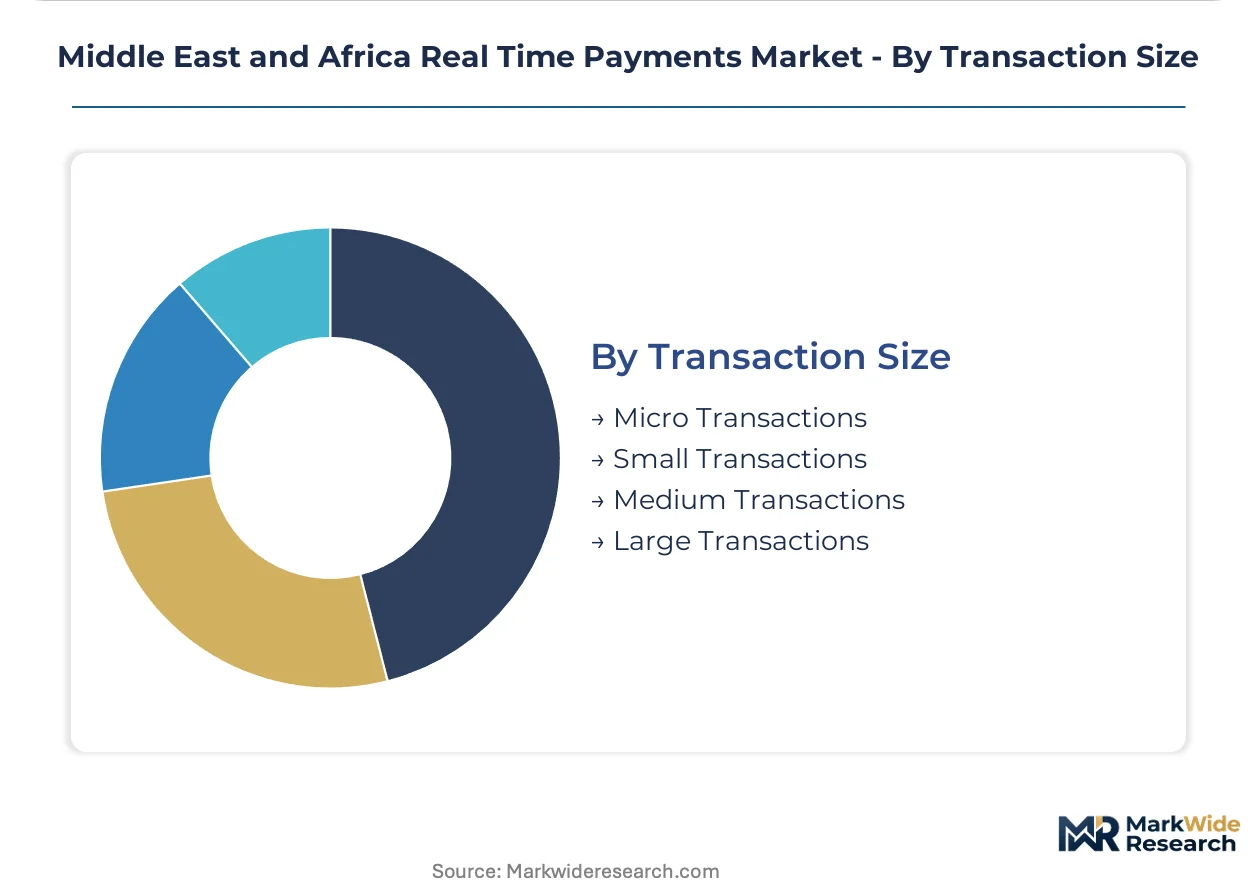
Transaction Size:
Volume distribution across size tiers reflects the bimodal structure of regional economies, with high-frequency micro-transactions coexisting alongside concentrated large-value corporate settlements.
- Micro Transactions:Sub-dollar value transfers dominate mobile money volume in Kenya and Nigeria, enabled by tiered KYC wallets with reduced functionality at lower verification levels. National Financial Inclusion Strategy requirements shape product constraints that limit use cases while expanding access.
- Large Transactions:High-value corporate and government settlements require real-time gross settlement rails with irrevocable finality, with Saudi Arabian Monetary Authority mandates forcing 24/7 availability compliance across licensed banks.
- Small Transactions:Retail purchases and small merchant payments occupy the middle tier, with aggregators capturing margin by unifying access to multiple settlement rails.
- Medium Transactions:SME supplier payments and mid-market commercial settlements bridge the gap between consumer and institutional infrastructure.
Micro Transactions carry the highest volume frequency; Large Transactions generate the steepest revenue per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sub-Saharan economies concentrate transaction volume in mobile-first wallet architectures, while Gulf Cooperation Council markets anchor settlement value in corporate banking modernization. This consumption-mix differential reflects divergent infrastructure maturity and regulatory sequencing across the region.
Saudi Arabia
Merchant-acquiring scale and cross-border settlement corridors concentrate demand in Riyadh and Jeddah corridors. The Saudi Arabian Monetary Authority mandates 24/7 gross settlement participation for licensed banks, compressing compliance timelines. Corporate treasury operations in the Eastern Province oil belt are migrating from batch-processed legacy systems to continuous processing infrastructure.
Nigeria
Mobile wallet adoption among unbanked populations and small business cashless settlement velocity drive Lagos corridor concentration. The Central Bank enforces tiered KYC requirements through its National Financial Inclusion Strategy, shaping micro-transaction product design. Payment aggregators capture expanding margin pools by normalizing fragmented banking APIs for merchant acceptance across the Lagos tech cluster.
Kenya
Peer-to-peer transfer volume and social transfer digitization anchor Nairobi tech cluster growth. The central bank's mobile money licensing regime enables wallet functionality expansion beyond basic remittance. M-Pesa platform ubiquity supports just-in-time liquidity products built on real-time balance visibility for digitally native merchants.
South Africa
Corporate high-value settlements and SME supplier payment modernization concentrate demand in Johannesburg and Cape Town financial centers. The South African Reserve Bank mandates real-time gross settlement participation, forcing licensed institutions toward continuous processing capability. Tier-1 banks are adopting containerized microservices fastest under compliance pressure.
United Arab Emirates
Cross-border remittance corridors and merchant-acquiring scale drive Dubai and Abu Dhabi infrastructure investment. The central bank's open-banking framework operates on accelerated timelines relative to sub-Saharan regimes. Fintech specialists exploit the capability gap through managed service arrangements that meet ISO 20022 compliance without capital-intensive core replacement.
Middle East and Africa Real Time Payments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with merchant-acquiring scale and mobile money ubiquity separating strategic positions. Gulf Cooperation Council markets favor infrastructure operators with cross-border settlement density, while sub-Saharan corridors reward API-native aggregators unifying fragmented bank access. Three archetypes dominate: cloud-native fintech specialists, legacy processor incumbents modernizing through overlay strategies, and telecommunications carriers leveraging subscriber bases for wallet distribution. Competitive moves concentrate on strategic partnerships bridging mobile money networks with banking rails, and geographic expansion across contiguous settlement corridors.
Within the infrastructure tier, Network International Holdings Plc represents merchant-acquiring scale concentration across Gulf Cooperation Council corridors. Safaricom Plc anchors mobile money ubiquity through platform subscriber density in East African markets. Interswitch Ltd occupies a position within West African banking integration specialists, normalizing disparate APIs for unified merchant acceptance. These three exemplify how geographic footprint and channel specialization determine competitive positioning across divergent regulatory environments.
| Leading Market Players |
|---|
| Network International Holdings Plc |
| Interswitch Ltd |
| Safaricom Plc |
| Opay |
| PalmPay Technology Co. Ltd |
| Paytabs |
| ACI Worldwide Inc |
| Fiserv Inc |
| Mastercard Inc |
| Others |
Supply & Pricing Matrix
Cloud-native settlement infrastructure substitution for legacy mainframe systems simultaneously concentrates vendor geography around South African and UAE specialist providers while compressing pricing premiums for continuous processing capability. This input replacement dynamic reshapes procurement economics as tier-1 banks abandon multi-year core replacement projects in favor of API-overlay strategies.
Pricing Analysis
Long-term managed service contracts dominate enterprise procurement, with tier-1 institutions locking in multi-year arrangements to meet SAMA and South African Reserve Bank compliance deadlines. Price differentiation separates ISO 20022-certified providers from uncertified competitors, with geographic delivery cost premiums attaching to Gulf Cooperation Council deployment. Pricing pressure intensifies as smaller banks and payment service providers accelerate outsourcing to avoid capital-intensive core modernization. Government agencies exhibit highest price sensitivity due to fiscal digitization budget constraints, while corporate treasury operations show lowest sensitivity given working capital friction reduction value.
Supply Chain Analysis
Inventory lead times for specialized DevOps and API engineering talent extend across the region, constraining deployment velocity for containerized settlement infrastructure. Geographic supply concentration centers on South Africa, UAE, and Kenya for cloud-native architecture expertise. Raw material dependencies include container orchestration platforms, ISO 20022 messaging libraries, and continuous availability hardware. Single-source vulnerability attaches to scarce regional integration specialists capable of 24/7 uptime maintenance. Distribution runs through managed service arrangements and direct vendor relationships with tier-1 banking institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of cloud-native settlement architecture expertise concentrates competitive advantage among providers capable of delivering continuous processing capability without capital-intensive core replacement. This capability gap justifies premium positioning for API-overlay specialists serving compliance-pressured institutions.
For Market Incumbents: Secure ISO 20022 certification investment as defensive priority against API-native aggregator displacement. Establish backward integration into containerized microservices development through UAE and South African talent acquisition. Channel control over merchant-acquiring relationships represents critical lever against payment aggregator margin capture. For New Entrants and Emerging Players: Differentiate on unified API normalization for West African banking fragmentation, targeting Nigeria's Lagos corridor merchant acceptance expansion. White-space opportunity concentrates in cross-border settlement corridors connecting Gulf Cooperation Council rails with East African mobile money networks. Go-to-market angle should emphasize development velocity over bilateral bank commercial terms. For Investors and Strategic Acquirers: Saudi Arabian Monetary Authority real-time gross settlement mandates reshape the acquisition landscape toward cloud-native infrastructure specialists with proven 24/7 deployment capability. Long-term viability framing favors providers capable of spanning regulatory divergence between Gulf Cooperation Council open-banking frameworks and sub-Saharan mobile-money licensing regimes. Signal to monitor: central bank compliance deadline acceleration forcing accelerated outsourcing decisions among tier-2 institutions.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Unifies fragmented Nigerian banking APIs for Lagos corridor merchant acceptance velocity. |
| Cross-Border Settlement Partnership | Connects GCC merchant-acquiring density with Kenya M-Pesa network ubiquity. |
| ISO 20022 Compliance Certification | Enables South African Reserve Bank deadline participation for outsourced infrastructure. |
| Cloud-Native Architecture Acquisition | Addresses DevOps talent scarcity constraining tier-1 bank modernization timelines. |
| Government Disbursement Integration | Captures fastest-expanding end-user segment through fiscal digitization mandate alignment. |
Research Methodology
Cross-validation between central bank regulatory filings and payment processor operational disclosures anchors the qualitative findings across the analysis window. Primary interviews with central bank policy officers, payment aggregator platform engineers, merchant-acquiring relationship managers, and government fiscal digitization leads combined with secondary validation from SAMA circulars, South African Reserve Bank payment system reports, Central Bank of Nigeria financial inclusion strategy documents, and mobile money licensing regime disclosures. Bottom-up transaction volume modeling and top-down infrastructure investment triangulation inform segmentation outputs.
Sensitivity analysis around regulatory deadline acceleration and cloud infrastructure adoption curves shapes the analytical framework. Segmentation dimensions modeled include payment channel, service provider archetype, end-user category, transaction size tier, and regional regulatory cluster. CAGRs derive from infrastructure deployment timelines and wallet adoption velocity patterns. Forecast inputs incorporate central bank mandate compliance schedules and mobile penetration trajectory assumptions.
The analysis sits within stated boundaries; outcomes outside maintained central bank enforcement of real-time settlement participation would require recalibration. Forecasts reflect documented assumptions regarding ISO 20022 migration pace and regional talent availability. Regulatory divergence friction and legacy core replacement abandonment risk could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Transit Cards Market
Payments
North America Accounts Payable Automation Market
Payments
E-Commerce Payments Market
Payments
Cash Management Software Market
Payments
Africa Mobile Money Market
Payments
India Mobile Payments Market
Payments
Digital Debit Market
Payments
Japan Credit Cards Market
Payments
Bitcoin Payments Market
Payments
Global Utility Billing Software Market
Payments
Global Master Card Market
Payments
Mpos Terminals Market
Payments
Blockchain Payments Software Market
Payments
Italy Payments Market
Payments
Fuel and Convenience Store POS Market
Payments
Electronic Toll Collection (ETC) Market