
 Saudi Arabia Mobile Payments Market | 2026-2036
Saudi Arabia Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Mobile Payments Market Analytics
Asset-light platform licensing is rewriting competitive entry rules for fintech challengers in the Kingdom. STC Pay leverages its telecom subscriber base to anchor merchant acquisition costs below standalone rivals. AlinmaPay sustains Sharia-compliant product architecture that differentiates its wallet from conventional banking apps. Google Pay navigates foreign operator restrictions by partnering with local issuers rather than seeking direct SAMR licensing.
Saudi Arabia mobile payments encompass digital fund transfers initiated through smartphones using NFC, QR codes, or biometric authentication, primarily enabling cash displacement across consumer and commercial transactions. The technical stack requires PCI-DSS compliance for tokenized card data and real-time integration with the Saudi Payments Network for settlement finality. E-wallet solutions lead transaction volume growth as unbanked populations bypass traditional card infrastructure entirely. Peer-to-peer transfers represent the fastest-expanding service type, fueled by remittance corridors and informal labor settlements. NFC technology dominates in-store acceptance at major retail chains, while QR code adoption accelerates among small merchants seeking zero-hardware deployment.
SAMA mandates operational risk frameworks and capital reserves for non-bank payment providers, tightening market access since its 2020 Payment Services Provider Regulations. SFDA consumer protection standards extend to digital wallet disclosures, while anti-money laundering protocols from the Financial Intelligence Unit shape transaction monitoring architecture. Stakeholders must track SAMA's evolving open banking directives to determine whether account aggregation will consolidate wallet functionality or fragment user interfaces across competing platforms.
Market Dynamics
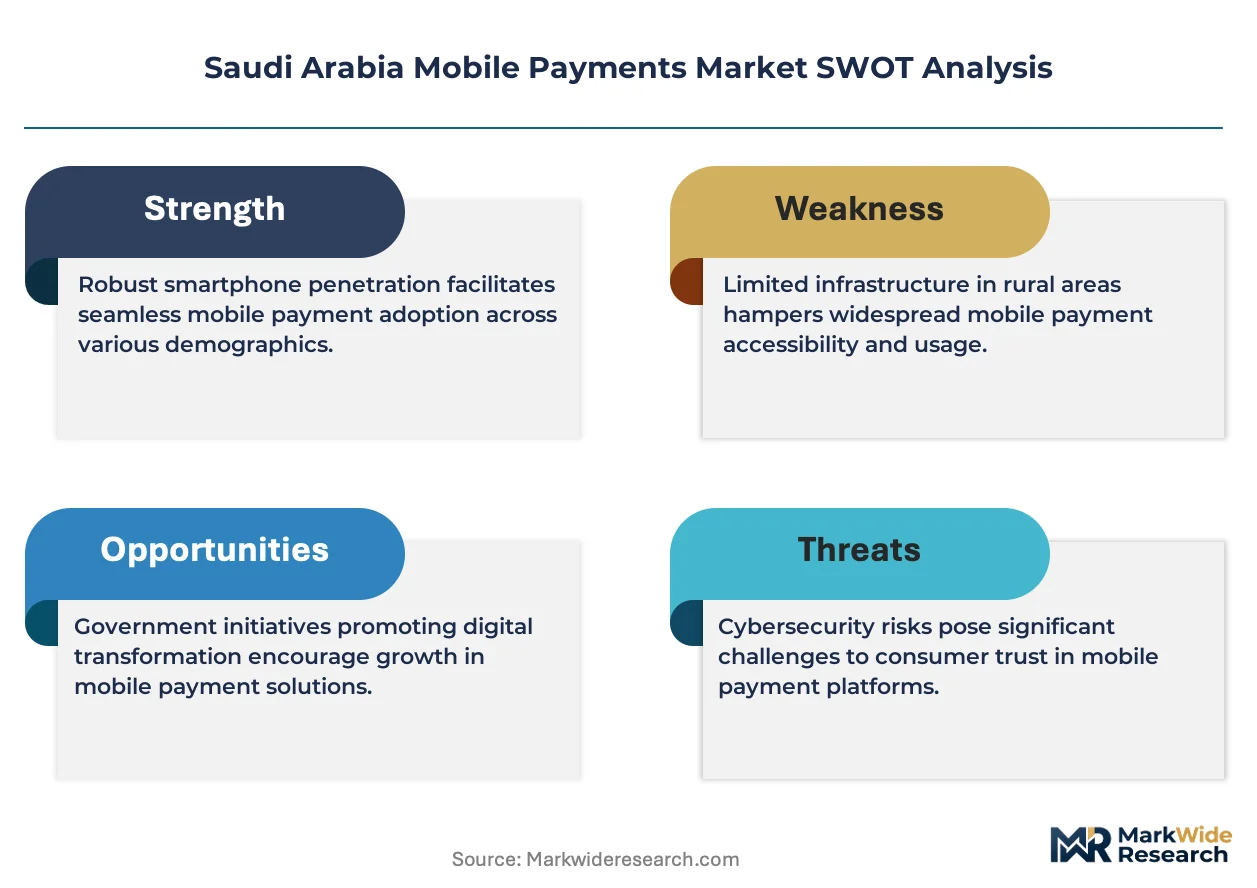
SAMA's 2020 Payment Services Provider Regulations triggered a structural consolidation wave, forcing non-bank wallet operators to maintain operational risk frameworks and capital reserves that standalone fintechs struggle to fund.
Growth Catalysts
- SAMA Open Banking Directives:The central bank's account aggregation mandates enable wallet providers to pull real-time balance data, deepening user engagement beyond transactional utility.
- NFC Infrastructure Rollout:Point-of-sale terminal upgrades across Riyadh and Jeddah retail chains eliminate cash-handling friction for smartphone-enabled shoppers.
- Unbanked Youth Demographics:Secondary city populations under age 35 bypass traditional card issuance entirely, creating first-mover capture opportunities for e-wallet platforms.
Market Restraints
- Capital Reserve Requirements:SAMA mandates minimum operational reserves that compress challenger fintech margins against telecom-backed incumbents with captive funding.
- Merchant Acquisition Cost Concentration:Dense urban retail clusters in Riyadh and Jeddah saturate quickly, pushing customer acquisition spend toward lower-conversion secondary markets.
- Biometric Authentication Fragmentation:Incompatible facial recognition standards across Android and iOS devices force redundant SDK integrations.
Strategic Opportunities
- Eastern Province SME Corridors:Dammam and Khobar merchant density remains underpenetrated by QR-code payment networks despite high smartphone penetration.
- Cross-Border Remittance Rails:SAMA's alignment with Gulf Cooperation Council payment protocols enables wallet-to-wallet transfers across Bahrain and UAE corridors.
- Sharia-Compliant Savings Products:SAMA regulatory sandbox permits profit-sharing wallet features that differentiate from conventional interest-bearing accounts.
Industry Challenges
- PCI-DSS Certification Timelines:Tokenized card data compliance requires 12-18 month audit cycles that delay product launches for non-bank entrants.
- Legacy Core Banking Integration:Saudi Payments Network real-time settlement protocols demand middleware development that strains fintech engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Mobile Payments Market |
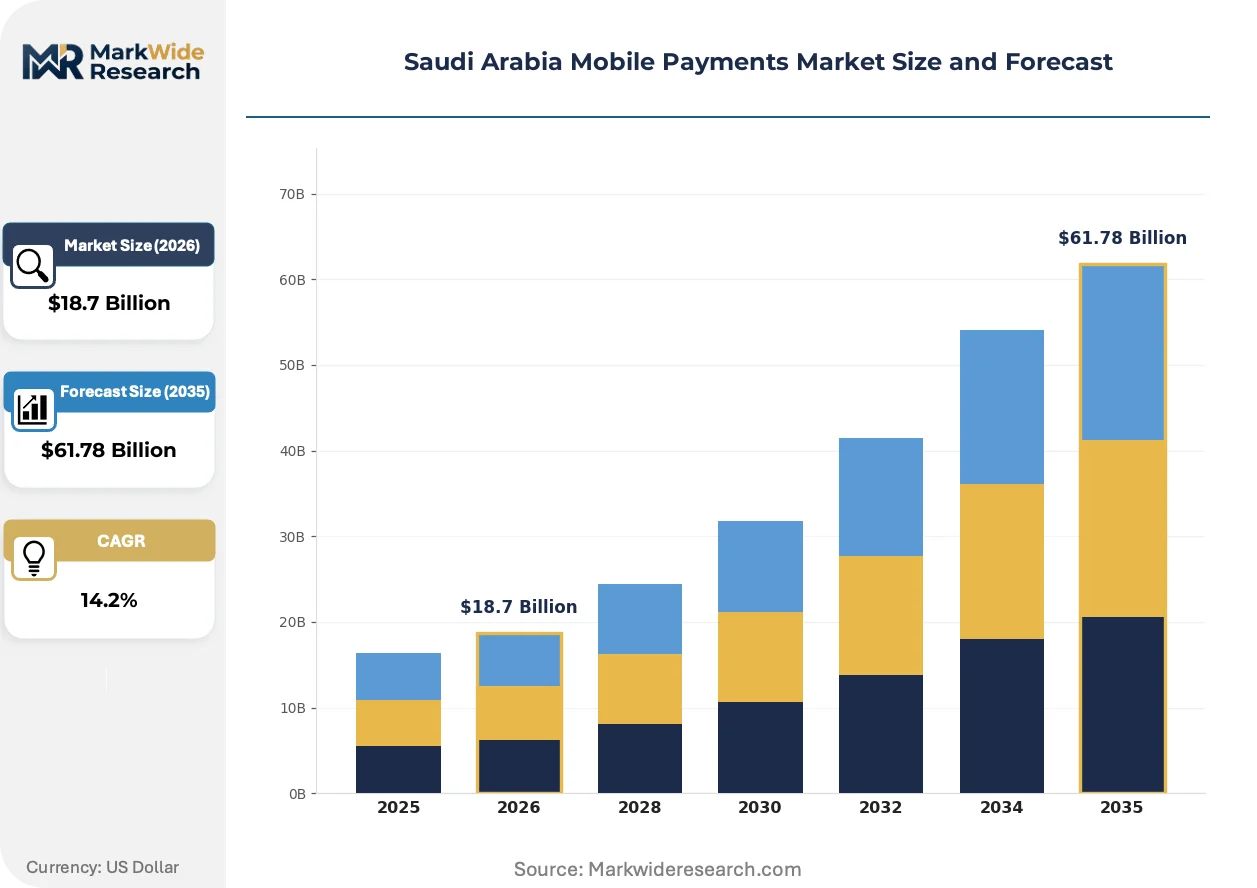
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, E-Wallets, Bank Transfers Service Type: In-Store Payments, Online Transactions, Peer-to-Peer Transfers, Bill Payments End User: Retail Shoppers, Small Businesses, Corporates, Government Agencies Technology: NFC, QR Codes, Mobile Apps, Biometrics |
| Companies Covered | Mada Pay (Saudi Payments), Bayan Pay (Bayan Payments Ltd.), AlinmaPay (Alinma Bank), Saudi Digital Payments Company (SCT Pay), Google Pay (Google LLC), Apple Pay (Apple Inc.), STC Pay, Al Rajhi Wallet, PayPal Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Mobile Payments Market Evolving Landscape
Payment infrastructure in the Kingdom is converging around biometric identity verification and merchant-side zero-hardware deployment, compressing the traditional acquiring value chain.
Biometric authentication is hybridizing transaction security protocols across the Saudi wallet ecosystem. Facial recognition and fingerprint tokenization replace static PIN entry for high-value transfers. Major retail chains in Riyadh and Jeddah now mandate biometric verification for purchases above threshold limits. This convergence is compressing fraud liability exposure while raising hardware requirements for merchant terminals.
SAMA's evolving open banking framework is reshaping data access permissions for non-bank payment providers. Account aggregation APIs now permit wallet applications to display consolidated balances from multiple banking relationships. E-wallet operators with SAMR licensing leverage this to anchor daily active user metrics. The regulatory tailwind most benefits challengers seeking to displace standalone banking apps through interface consolidation.
Informal labor settlements are rotating demand toward instant peer-to-peer transfer protocols. Construction and domestic worker segments in Jeddah bypass formal banking hours through smartphone-based wage disbursement. QR-code acceptance among small merchants displaces traditional POS terminal dependence. This behavioral shift concentrates transaction volume growth in secondary cities where branch banking penetration lags smartphone adoption.
Saudi Arabia Mobile Payments Market Segmentation
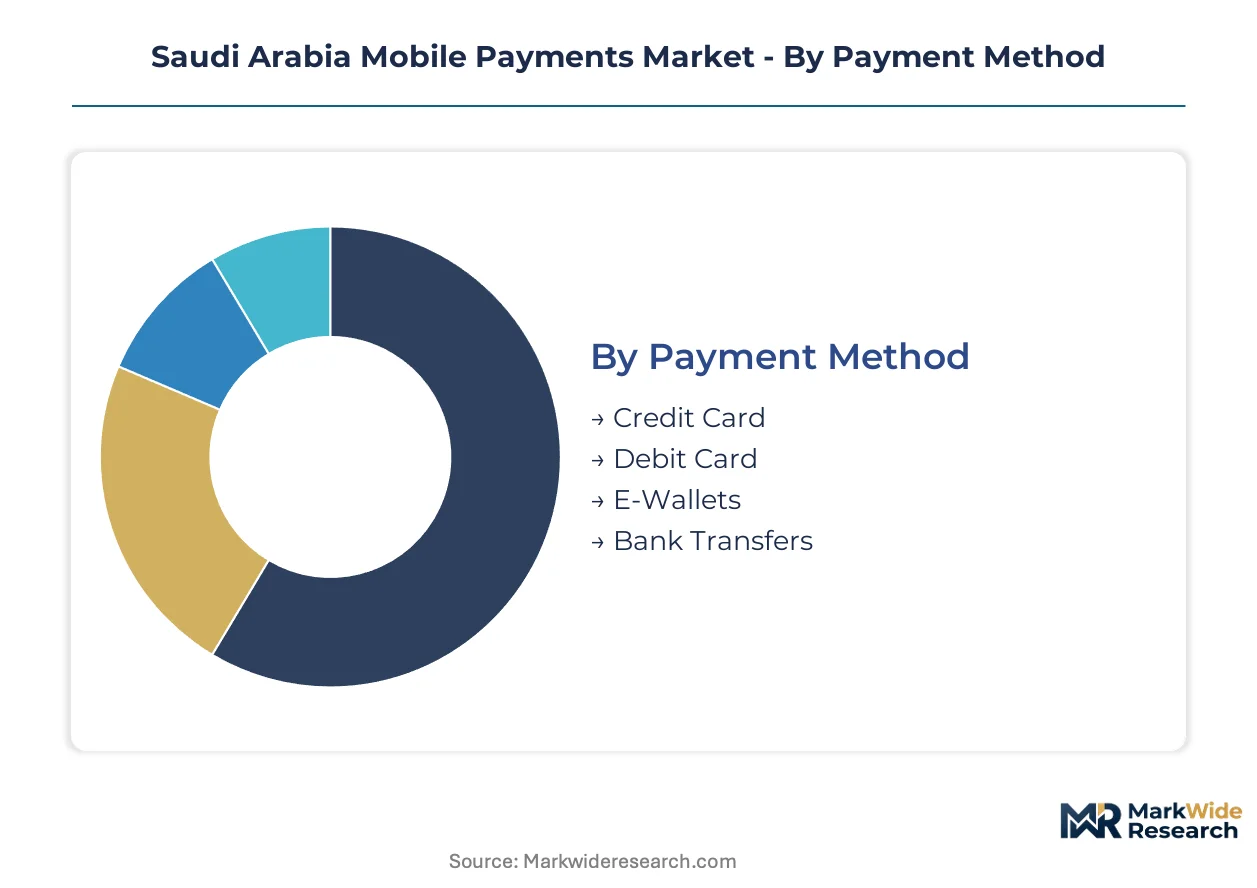
Mobile payment architectures in the Kingdom fragment across transaction modalities, user contexts, and authentication layers. SAMA's licensing framework creates divergent compliance burdens across these boundaries, reshaping where fintech capital concentrates.
Payment Method:
Use-case spectrum spans from card-linked tokenization to closed-loop wallet ecosystems, each carrying distinct capital reserve and settlement risk profiles under central bank supervision.
- E-Wallets:Closed-loop digital accounts store value locally, enabling instant settlement without card network rails. Unbanked youth in Dammam and Tabuk drive volume as primary banking alternatives.
- Debit Card:Direct linkage to Saudi Payments Network settlement protocols dominates salary disbursement corridors. Corporate payroll integrations in Riyadh anchor recurring transaction density.
- Credit Card:Revolving credit lines attached to mobile interfaces concentrate among premium retail segments. Jeddah luxury merchants leverage tokenized credentials for high-value authentication.
- Bank Transfers:Real-time account-to-account protocols via the national payment infrastructure serve B2B settlement needs. SME procurement clusters in the Eastern Province favor this rail for invoice reconciliation.
Established volume favors Debit Card; emerging adoption favors E-Wallets.
Service Type:
Transaction context determines infrastructure requirements, from merchant-present NFC terminals to remote authentication protocols for recurring obligations.
- Peer-to-Peer Transfers:Smartphone-based fund movement between individuals bypasses formal banking hours. Informal labor settlements in construction and domestic work segments across Jeddah and Mecca propel volume expansion.
- Online Transactions:E-commerce checkout flows integrate wallet APIs and tokenized credentials. Cross-border merchant acceptance gaps in the Kingdom drive local wallet preference over international card brands.
- In-Store Payments:Physical retail checkout via NFC tap or QR scan concentrates in Riyadh and Jeddah mall networks. SAMA-mandated terminal upgrades accelerate hardware penetration.
- Bill Payments:Recurring utility and government fee settlements anchor daily active user metrics. SADAD integration requirements shape wallet feature roadmaps for all licensed providers.
Legacy infrastructure anchors In-Store Payments; behavioral shift momentum concentrates in Peer-to-Peer Transfers.
End User:
Customer scale and transaction value distribution create tiered service requirements, from individual consumer convenience to enterprise treasury management.
- Retail Shoppers:Individual consumers executing purchases across physical and digital channels. Smartphone penetration above 95% in urban centers enables near-universal addressability.
- Small Businesses:Merchant acquirer relationships and working capital needs shape platform selection. QR-code acceptance without hardware investment accelerates adoption among neighborhood retailers.
- Corporates:Treasury management and supplier payment automation demand API-integrated solutions. Multi-user permission structures and audit trails differentiate B2B wallet offerings.
- Government Agencies:Public sector disbursement and collection mandates drive large-scale platform procurement. SAMA's national digital payment strategy prioritizes interoperability with state financial systems.
Transaction density peaks with Retail Shoppers; revenue per user concentrates among Corporates.
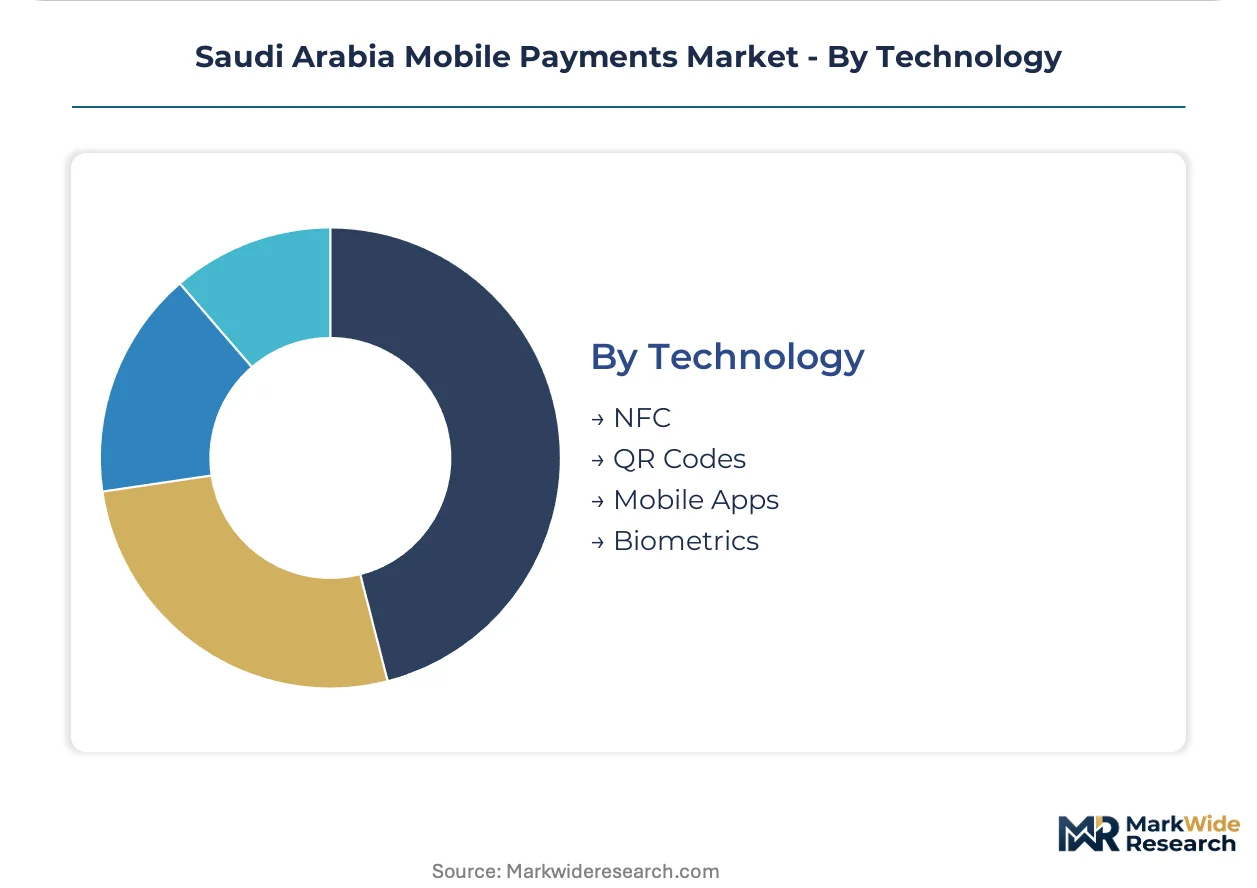
Technology:
Authentication and acceptance infrastructure choices determine merchant-side deployment costs and consumer friction profiles.
- NFC:Near-field communication enables tap-to-pay at upgraded POS terminals. Major retail chains in Riyadh and Jeddah mandate this protocol for sub-second checkout latency.
- QR Codes:Optical scanning eliminates hardware requirements for merchant acceptance. Small merchants in secondary cities adopt this modality fastest due to zero capital expenditure.
- Mobile Apps:Native application interfaces aggregate multiple payment rails and value-added services. SAMA open banking APIs deepen functionality beyond transactional utility.
- Biometrics:Facial recognition and fingerprint tokenization replace static credentials for high-value transfers. SFDA consumer protection standards shape disclosure requirements for biometric data handling.
Merchant coverage breadth favors QR Codes; authentication security elevation favors Biometrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's mobile payments market demonstrates net import dependency for core payment infrastructure technology, while domestic wallet platforms increasingly export service architectures to Gulf Cooperation Council neighbors. The Kingdom's position as a regional fintech hub creates cross-border capital flows that reshape competitive dynamics across Middle Eastern payment corridors.
Riyadh
The capital region concentrates corporate headquarters and government digital transformation mandates that drive enterprise wallet procurement. SAMA's regulatory sandbox operates from Riyadh, channeling fintech licensing approvals toward operators with local incorporation. King Abdullah Financial District anchors B2B payment platform development for corporate treasury solutions.
Eastern Province
Dammam and Khobar industrial zones generate SME procurement demand for invoice reconciliation via real-time bank transfers. Aramco supplier payment digitization mandates accelerate API-integrated wallet adoption among contractor networks. The Dammam metropolitan corridor remains underpenetrated by QR-code merchant networks despite smartphone saturation above 90 percent.
Western Region
Jeddah's construction and domestic labor segments propel peer-to-peer transfer volume for informal wage settlements. Mecca pilgrimage corridors create seasonal spikes in cross-border remittance flows through smartphone-based rails. Red Sea coastal merchant clusters favor zero-hardware QR acceptance over NFC terminal deployment.
NEOM Northwest
The giga-project zone mandates cashless infrastructure from ground-up development, bypassing legacy POS terminal retrofitting constraints. NEOM's regulatory autonomy permits experimental biometric authentication protocols outside SAMA's standard framework. Tabuk province secondary cities serve as testing grounds for unbanked youth wallet penetration strategies.
Saudi Arabia Mobile Payments Market Competitive Landscape
On the supply side, the industry is bifurcated between telecom-backed incumbents with captive subscriber bases and licensed fintech challengers dependent on venture funding cycles. SAMA's capital reserve requirements compress standalone operator margins while reinforcing incumbent positions. Two strategic archetypes dominate: asset-light platform licensors leveraging existing infrastructure, and full-stack wallet operators building proprietary merchant networks. Competitive moves concentrate on merchant acquisition cost reduction and open banking API integration partnerships.
Within the domestic banking tier, AlinmaPay and Al Rajhi Wallet exemplify Sharia-compliant product differentiation strategies that separate them from conventional payment apps. STC Pay anchors the telecom-integrated archetype, leveraging its parent company's subscriber base to compress customer acquisition economics. Among international platform operators, Google Pay and Apple Pay occupy positions as card-network-linked alternatives that bypass direct SAMR licensing through local issuer partnerships.
| Leading Market Players |
|---|
| Mada Pay (Saudi Payments) |
| Bayan Pay (Bayan Payments Ltd.) |
| AlinmaPay (Alinma Bank) |
| Saudi Digital Payments Company (SCT Pay) |
| Google Pay (Google LLC) |
| Apple Pay (Apple Inc.) |
| STC Pay |
| Al Rajhi Wallet |
| PayPal Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in QR-code acceptance infrastructure across Jeddah's Red Sea corridor compresses merchant-side pricing power while accelerating zero-hardware deployment economics for wallet providers. SAMA's capital reserve mandates simultaneously inflate fixed-cost burdens for non-bank entrants, bifurcating pricing postures between telecom-backed incumbents and venture-funded challengers.
Pricing Analysis
Industrial OEM buyers anchor transaction-based pricing structures across B2B payment corridors. Three-tier pricing structure across premium API-integrated, standard SaaS-licensed, and economy white-label deployment levels stratifies wallet platform offerings. Cost compression in the challenger fintech tier intensifies because SAMA-mandated operational reserves strain standalone operator margins. Small merchants in secondary cities exhibit highest price sensitivity; corporate treasury clients in Riyadh's King Abdullah Financial District demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates core payment infrastructure sourcing risks for terminal hardware and semiconductor components. Taiwan, South Korea, and Vietnam anchor NFC chip and POS terminal manufacturing concentration. Tokenization software and biometric SDKs draw from US and European intellectual property licensors. Single-source vulnerability in EMV certification testing creates bottleneck risk. Distribution runs through Saudi Payments Network settlement rails for finality, with STC Pay and AlinmaPay operating captive merchant acquisition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAMA's open banking API framework is reconfiguring platform economics toward interface consolidation, where wallet operators capturing account aggregation permissions displace standalone banking applications through embedded finance ecosystems.
For Market Incumbents: Build data-network moats through exclusive SADAD integration partnerships and biometric authentication standard-setting. STC Pay should deepen merchant lock-in via working capital lending products tethered to transaction history. AlinmaPay must defend Sharia-compliant differentiation against conventional bank wallet convergence. Threat vector: Google Pay's issuer-partnership model bypasses direct SAMR licensing while capturing premium user segments. For New Entrants and Emerging Players: Establish a beachhead in Eastern Province SME corridors where Dammam and Khobar merchant density remains underpenetrated by QR-code networks despite smartphone saturation above 90 percent. Target construction payroll digitization in Jeddah's informal labor settlements through instant peer-to-peer settlement protocols. Go-to-market angle: zero-hardware merchant onboarding with same-day KYC completion via SFDA-aligned biometric verification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across full-stack wallet operators building proprietary merchant networks versus asset-light platform licensors. Long-term viability favors telecom-backed incumbents with captive funding and regulatory sandbox access over standalone fintechs facing venture cycle dependency. Acquisition target archetype: licensed non-bank PSPs with SAMR approval and established SADAD integration. Signal to watch: SAMA open banking directive expansion into payment initiation services.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Wallet operators embedding SADAD bill payment APIs capture daily active user retention across utility settlements. |
| Strategic Partnership | Biometric authentication vendors partnering with SAMA sandbox participants accelerate facial recognition SDK deployment timelines. |
| Geographic Expansion | QR-code networks penetrating Tabuk and Hail secondary cities capture unbanked youth demographics before incumbent saturation. |
| Product Launch | Sharia-compliant profit-sharing wallet features differentiate AlinmaPay from conventional interest-bearing competitor architectures. |
| Acquisition of Specialist Firm | Merchant acquirers purchasing POS terminal distributors compress hardware deployment costs in Riyadh mall networks. |
Research Methodology
Operator-level perspectives from wallet platform executives, SAMA regulatory affairs leads, merchant acquirer relationship managers, and SADAD integration specialists anchored the qualitative base. Primary interview insights combined with secondary validation from SAMA Payment Services Provider Regulations filings, Saudi Payments Network technical protocol documentation, and SFDA consumer protection standards. SEC filings from listed fintech parents, regional venture capital deployment databases, and GCC cross-border remittance corridor analyses furnished quantitative benchmarks. Bottom-up transaction volume modeling and top-down GDP-attribution approaches triangulated market sizing.
Scenario-bracketing across conservative, baseline, and accelerated adoption pathways informed projection robustness without year-specific anchoring. Segmentation dimensions modeled encompass payment method modality, service type context, end-user scale tier, and authentication technology layer across the analysis window. CAGRs derived from cohort-based user adoption curves and merchant acceptance density trajectories. Industry-specific forecast inputs included SAMA licensing approval timelines and NFC terminal upgrade penetration rates.
Stress conditions across regulatory enforcement intensity, biometric authentication fragmentation, and cross-border remittance corridor stability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SAMA open banking directive implementation pace and unbanked youth smartphone penetration sustainability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe Accounts Payable Automation Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
US Buy Now Pay Later Services Market
Payments
Smart Payment Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Credit Card Issuance Services Market
Payments
Digital Payment in Healthcare Market
Payments
Remittance Market
Payments
Electronic Payment System for Transportation Market
Payments
Mobile Payment Transaction Market
Payments
Europe Credit Cards Market
Payments
Money Transfer Agencies Market
Payments
Indonesia Prepaid Cards Market
Payments
United States Payments Market
Payments
Middle East and Africa Payment Gateway Market
Payments
Uganda Mobile Money Market