
 Japan Real Time Payment Market | 2026-2036
Japan Real Time Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Real Time Payment Market Foresight
Small business owners are collapsing the historical dominance of large corporate treasuries in transaction volume share. PayPay leverages its QR infrastructure to anchor merchant acceptance density across convenience retail. Mitsubishi UFJ Financial Group sustains institutional trust through direct bank account integration with real-time rails. LINE Pay competes by embedding payment flows within super-app messaging ecosystems.
Real time payment systems execute fund transfers between accounts with settlement finality under thirty seconds, typically operating on ISO 20022 messaging protocols and API orchestration layers. These networks eliminate interbank float and reduce counterparty risk for commercial transactions. QR code payments lead consumer-facing adoption due to minimal merchant hardware requirements, while cloud-based solutions represent the fastest-expanding technology layer as banks outsource core infrastructure. API connectivity sits at the center of margin concentration, since interoperability licensing generates recurring revenue streams for platform providers.
METI promotes cashless adoption targets that expand terminal infrastructure requirements, while the FSA enforces open banking API standards that dictate data-sharing protocols between incumbent banks and fintech entrants. JIS standards for security authentication shape product certification thresholds for domestic deployment. Stakeholders must monitor how regulatory pressure on interoperability merges with cloud migration timelines to determine partnership versus build strategies for infrastructure scale.
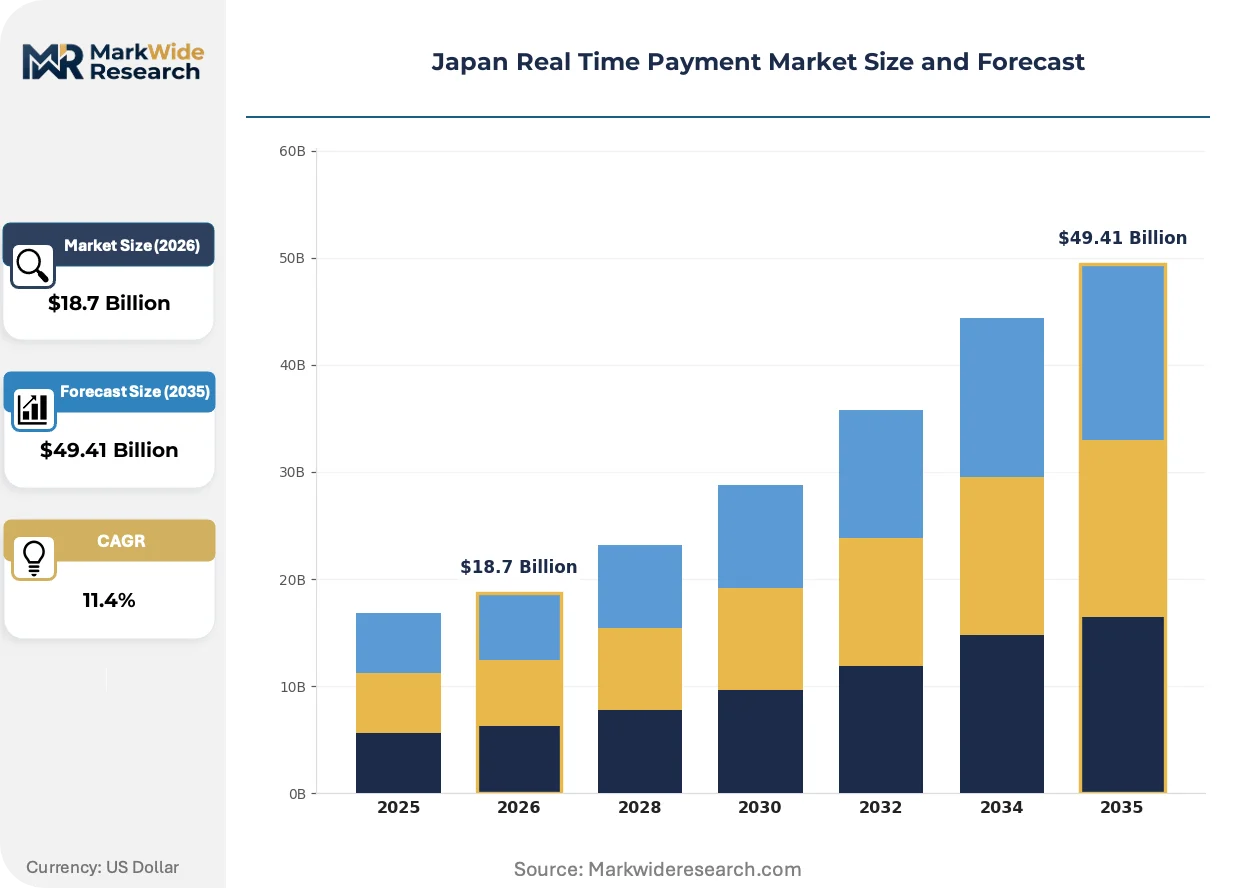
Market Dynamics
Japan's FSA open banking mandates are forcing incumbent banks to expose core payment rails through standardized APIs, eroding historical data monopolies and redistributing transaction economics toward fintech orchestrators.
Growth Catalysts
- METI cashless adoption targets:Government-mandated terminal infrastructure expansion compels merchants across convenience retail and food service to activate real-time acceptance capabilities.
- QR code payment ubiquity:Minimal hardware requirements accelerate merchant onboarding density, particularly among Osaka's SME clusters where legacy POS penetration remained historically low.
- Cloud infrastructure migration:Regional banks are outsourcing core payment processing to API-native platforms, collapsing time-to-market for real-time product deployment.
Market Restraints
- Interoperability licensing costs:Recurring API access fees concentrate margin extraction with platform providers, compressing net yields for smaller financial institutions.
- Cash preference persistence:Demographic concentration among aging populations in rural prefectures sustains paper-based settlement habits that resist digital conversion.
- Legacy core banking systems:Cobol-dependent infrastructure at major city banks imposes integration friction that delays real-time rail connectivity.
Strategic Opportunities
- Hokkaido and Tohoku merchant corridors:Underpenetrated regional economies outside Tokyo-Osaka axes present first-mover advantages for QR infrastructure deployment.
- Super-app payment convergence:Messaging-platform embedding of financial services creates captive user ecosystems that reduce customer acquisition costs.
- JIS security certification streams:Accelerated authentication standard approvals enable faster product launches for biometric-enabled payment solutions.
Industry Challenges
- ISO 20022 messaging expertise scarcity:Specialized engineering talent for next-generation protocol implementation commands premium compensation that strains mid-tier bank budgets.
- Multi-rail integration complexity:Synchronous operation across Zengin, JCB, and international schemes requires architectural overhaul of settlement engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Real Time Payment Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Transfers, Mobile Wallets, Instant Debit, QR Code Payments End User: Retail Customers, Small Businesses, Corporations, Financial Institutions Technology: Blockchain, API, NFC, Cloud-Based Solutions Service Provider: Banks, Fintechs, Payment Processors, Telecom Operators |
| Companies Covered | Mitsubishi UFJ Financial Group, Mizuho Financial Group, PayPay, FIS Global, ACI Worldwide, LINE Pay, Sumitomo Mitsui Financial Group, Fiserv, Rakuten Pay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Real Time Payment Market Shifts & Advancements
API orchestration layers are collapsing traditional bank-fintech boundaries, enabling third-party developers to build directly atop regulated payment infrastructure without core system ownership.
Cloud-native core banking platforms are decomposing monolithic legacy architectures into modular microservices. Regional banks in Fukuoka and Nagoya are migrating settlement engines to these environments within eighteen-month windows. This decomposition is compressing vendor lock-in durations and enabling swap-out of individual payment components without full-stack replacement.
METI's revised open banking implementation timeline tightens data-sharing compliance deadlines for Tier 1 institutions. The regulation forces simultaneous API standardization across credit, deposit, and payment products. Tokyo-based money center banks are responding by consolidating vendor relationships to reduce interoperability testing overhead.
Merchant acquiring patterns are fragmenting as convenience store chains bypass traditional bank partners for direct fintech integration. Lawson and FamilyMart operations in Kansai now route QR transactions through platform-native settlement. This channel disintermediation is most visible among retail verticals where transaction velocity justifies dedicated technical integration teams.
Japan Real Time Payment Market Segmentation
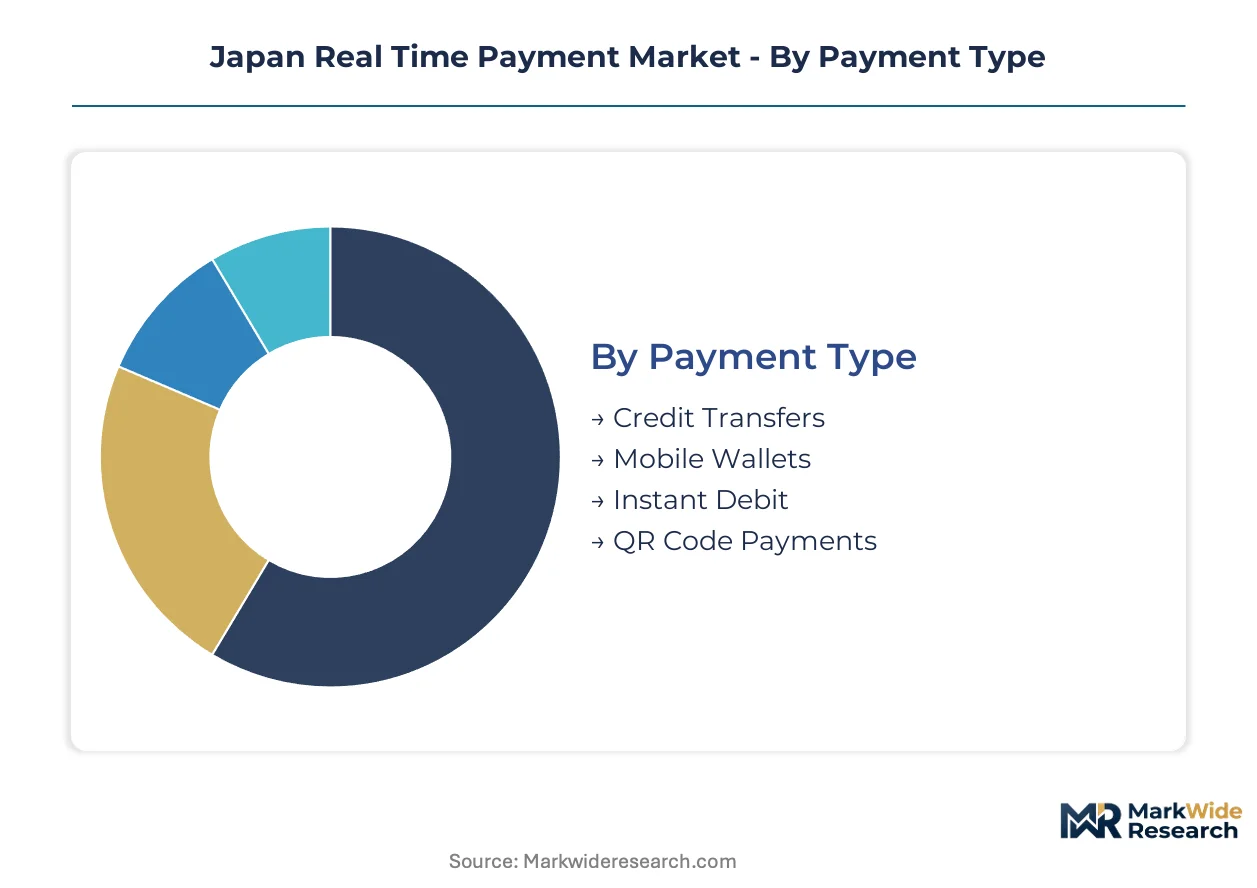
Japan's real-time payment infrastructure fragments across four distinct dimensions that determine commercial access patterns and technology deployment priorities. Payment type and end-user concentration in Tokyo-Osaka corridors diverge sharply from regional adoption curves. Technology choices reflect the tension between legacy bank systems and cloud-native fintech architectures.
Payment Type:
Domestic demand concentrates in merchant-facing instruments with minimal hardware requirements, while institutional flows favor rails with direct bank integration. Export-oriented fintech platforms increasingly embed Japanese payment methods into cross-border commerce tools.
- Credit Transfers:Direct account-to-account settlement through Zengin Net and BoJ-Net rails executes with immediate finality for high-value B2B transactions. Corporate treasuries in Tokyo's financial district dominate volume concentration as they displace legacy batch-based wire systems for supplier payments and liquidity management.
- Mobile Wallets:Smartphone-native applications store tokenized credentials for tap-to-pay and in-app purchases, operating through device secure elements or host card emulation. Younger demographics in Fukuoka and Sapporo urban cores drive adoption velocity, attracted by loyalty program integration and transit fare interoperability.
- Instant Debit:Real-time authorization against checking account balances eliminates card network interchange for merchant cost reduction.
- QR Code Payments:Static and dynamic matrix codes encode transaction data readable by standard smartphone cameras, requiring no dedicated terminal hardware.
QR code payments command the established base. The steepest expansion runs through mobile wallets.
End User:
Customer type determines interface complexity requirements and settlement speed expectations. Small business adoption is climbing fastest as METI terminal subsidies reduce activation barriers.
- Small Businesses:Osaka's SME clusters and Nagoya manufacturing subcontractors prioritize low-friction onboarding and same-day settlement to manage working capital cycles. These merchants bypass traditional acquiring relationships for direct fintech platform integration.
- Retail Customers:Individual consumers transacting through convenience retail, transit, and e-commerce channels demand sub-30-second confirmation with biometric authentication. Tokyo's dense merchant corridor produces the highest per-capita transaction frequency as cashless habits concentrate in metropolitan wards.
- Corporations:Large enterprises with dedicated treasury operations require multi-bank aggregation and automated reconciliation against ERP systems.
- Financial Institutions:Banks and credit unions seek white-label infrastructure to deploy real-time products without core system replacement.
Retail customers anchor transaction volume. Small businesses are gaining share fastest.
Technology:
Architecture choices separate incumbent banks maintaining legacy stacks from challengers building cloud-native from inception. API and cloud deployments concentrate development talent in Tokyo's fintech district.
- API:RESTful and gRPC interfaces expose core banking functions to third-party developers, enabling orchestration layers that abstract underlying rail complexity. FSA open banking mandates accelerate standardization as Tier 1 institutions expose payment initiation and account information endpoints.
- Cloud-Based Solutions:Distributed infrastructure replaces on-premise mainframes for processing elasticity and disaster recovery, with regional banks in Tohoku and Kyushu migrating settlement engines to API-native platforms. These deployments collapse time-to-market from years to months for real-time product launches.
- Blockchain:Distributed ledger prototypes explore cross-border settlement efficiency and programmable money applications.
- NFC:Near-field communication enables contactless tap-to-pay through device proximity, competing with QR for in-person transaction share.
API infrastructure commands the established base. Cloud-based solutions are climbing the fastest.
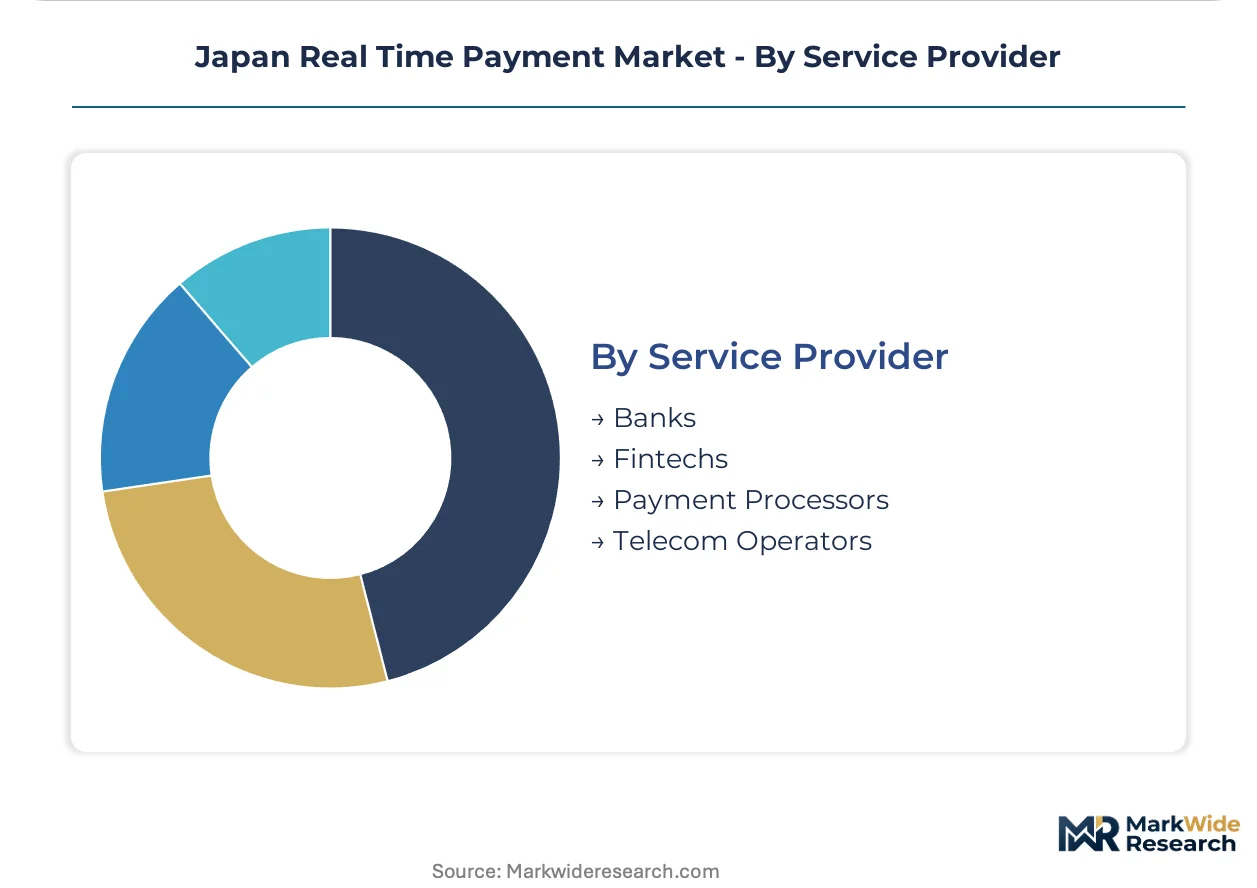
Service Provider:
Provider type shapes margin structure and customer relationship ownership. Fintechs are capturing merchant-facing innovation while banks retain institutional trust for high-value flows.
- Fintechs:Technology-first platforms unburdened by legacy infrastructure build merchant-centric user experiences with rapid feature iteration, dominating QR payment acceptance density in convenience retail and food service verticals.
- Banks:Regulated deposit-taking institutions leverage trust anchors and direct account access to serve corporate treasury and high-net-worth segments with integrated cash management.
- Payment Processors:Acquiring specialists manage technical routing and settlement across multiple schemes for merchant clients.
- Telecom Operators:Mobile network carriers exploit subscriber identity and billing relationships to embed financial services within connectivity contracts.
Banks command the established base. Fintechs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Zengin Net payment infrastructure underwrites Kanto's dominance in real-time transaction processing, connecting Tokyo's financial district to regional clearing systems across Japan's archipelago.
Kanto/Tokyo
Corporate treasury demand and dense merchant corridors drive adoption velocity. METI cashless targets accelerate terminal deployment in convenience retail clusters. Chiyoda and Minato wards concentrate the highest per-capita transaction frequency as financial institutions co-locate settlement operations.
Kansai/Osaka
SME manufacturing subcontractors prioritize same-day settlement for working capital management. FSA open banking mandates force regional banks to expose payment rails through standardized APIs. Osaka's SME clusters bypass traditional acquiring relationships for direct fintech platform integration.
Chubu/Nagoya
Automotive supply chain payments demand real-time liquidity visibility. JIS security certification requirements shape authentication product deployment timelines. Nagoya's industrial belt generates concentrated B2B transaction volume as tier-one suppliers displace batch-based wire systems.
Kyushu
Regional banks migrate core settlement engines to cloud-native platforms for processing elasticity. Fukuoka's fintech district attracts API development talent from Tokyo. Younger demographics in urban cores drive mobile wallet adoption velocity through transit fare interoperability.
Hokkaido
Underpenetrated merchant corridors present first-mover advantages for QR infrastructure deployment. Cash preference persists among aging rural populations. Sapporo's urban core diverges sharply from prefectural averages as metropolitan wards achieve cashless parity with southern metros.
Japan Real Time Payment Market Competitive Landscape
Listed megabanks compete with private fintech specialists across merchant acquisition and infrastructure orchestration. The market structure fragments across three tiers: deposit-taking institutions with trust anchors, technology-first platforms with user experience advantages, and global infrastructure vendors with API-native architectures. Two strategic archetypes dominate: banks leveraging direct account access for institutional flows, and fintechs capturing merchant-facing innovation through rapid feature iteration. Competitive moves concentrate on cloud migration partnerships and interoperability licensing consolidation.
Within the bank archetype, Mitsubishi UFJ Financial Group and Mizuho Financial Group exemplify institutions sustaining institutional relationships through core system integration with real-time rails. Among fintech platforms, PayPay occupies a position representing merchant acceptance density strategies anchored to QR infrastructure deployment across convenience retail verticals. These three entities illustrate the competitive tension between regulated deposit-taking trust and technology-first user experience capture.
| Leading Market Players |
|---|
| Mitsubishi UFJ Financial Group |
| Mizuho Financial Group |
| PayPay |
| FIS Global |
| ACI Worldwide |
| LINE Pay |
| Sumitomo Mitsui Financial Group |
| Fiserv |
| Rakuten Pay |
| Others |
Supply & Pricing Matrix
FSA open banking API certification tiers gate both infrastructure vendor qualification and price differentiation across the Japanese real-time payment stack, forcing regional banks into premium licensing arrangements while cloud-native entrants exploit standardized middleware to undercut legacy integration costs.
Pricing Analysis
Volume-discount tiering structures dominate API licensing arrangements, with per-transaction fees collapsing for merchants processing above threshold volumes through PayPay and LINE Pay ecosystems. Price differentiation rests on ISO 20022 messaging complexity and JIS security certification grade, where biometric-enabled solutions command substantial premiums over basic QR infrastructure. Pricing pressure intensifies as fintech platforms absorb upfront integration costs to capture merchant density, squeezing net yields for smaller financial institutions. Retail SMEs exhibit acute price sensitivity, while corporate treasuries prioritize settlement finality and ERP integration over marginal cost differentials.
Supply Chain Analysis
Inventory and lead-time compression distinguishes cloud-native platform deployment from legacy core banking overhauls, with regional banks in Kyushu and Tohoku collapsing implementation windows from years to months. Supply concentration centers on Japan, the United States, and Singapore for API orchestration layers and cloud infrastructure. Critical dependencies include semiconductor components for secure element manufacturing, fiber-optic connectivity for low-latency settlement, and specialized engineering talent for ISO 20022 protocol implementation. Single-source vulnerability looms in legacy COBOL-dependent core systems maintained by shrinking talent pools. Distribution runs through direct fintech partnerships and consolidated vendor relationships at Tier 1 institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's real-time payment infrastructure fragments across regulatory compliance layers, cloud migration timelines, and regional adoption gaps, creating multiple white-space opportunities as METI cashless targets force merchant terminal upgrades and FSA mandates accelerate API standardization.
For Market Incumbents: Shield core deposit relationships by accelerating cloud-native core banking migration ahead of fintech disintermediation in merchant acquiring. Prioritize direct Zengin Net integration with automated reconciliation modules for corporate treasury clients, consolidating vendor relationships to reduce interoperability testing overhead as METI compliance deadlines tighten.
For New Entrants and Emerging Players: Anchor in Hokkaido and Tohoku merchant corridors where QR infrastructure penetration lags Tokyo-Osaka benchmarks by substantial margins. Target aging regional bank partnerships desperate for white-label real-time products without core system replacement, leveraging API-native architectures to compress time-to-market against legacy integrators.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based payment infrastructure as platform economics displace bespoke core banking builds, favoring asset-light orchestration models over hardware-heavy terminal deployment. Monitor JIS security certification approval velocity as the critical signal distinguishing viable acquisition targets from compliance-strapped laggards in biometric authentication solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Migration | Regional banks in Fukuoka and Nagoya compress deployment timelines from years to months through API-native settlement engines. |
| QR Infrastructure Expansion | PayPay leverages minimal hardware requirements to capture merchant density in convenience retail and food service verticals. |
| ISO 20022 Protocol Implementation | Corporate treasuries in Tokyo's financial district displace batch-based wire systems for immediate settlement finality. |
| Biometric Authentication Certification | JIS security standard approvals enable faster product launches for fingerprint and facial recognition payment solutions. |
| Super-App Payment Convergence | LINE Pay embeds financial flows within messaging ecosystems to reduce customer acquisition costs through captive user bases. |
Research Methodology
The analysis maps payment type segments, technology deployment layers, and regional adoption corridors, each validated through primary interviews with payment platform executives, regional bank technology officers, merchant acquiring specialists, and FSA regulatory affairs leads. Secondary sources include METI cashless adoption reports, FSA open banking implementation guidelines, Zengin Net transaction flow disclosures, and cloud infrastructure vendor SEC filings. Bottom-up merchant terminal deployment counts triangulate against top-down banking sector technology expenditure estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include payment instrument type, end-user archetype, technology architecture, and service provider category, with particular attention to cloud migration velocity and API standardization compliance. CAGRs derive from historical adoption curve analysis and regulatory deadline impact assessment, incorporating ISO 20022 messaging protocol deployment timelines and METI terminal infrastructure subsidy trajectories as industry-specific forecast inputs.
Material uncertainties — regulatory implementation delays, legacy system integration failures, and demographic resistance to cashless conversion in rural prefectures — sit outside the modeled envelope. Forecasts reflect assumptions about FSA enforcement consistency and cloud vendor pricing stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Telecom Billing and Revenue Management Market
Payments
North America POS Terminal Market
Payments
Japan POS Terminals Market
Payments
South Korea Payments Market
Payments
Romania POS Terminals Market
Payments
Norway POS Terminals Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Canada POS Terminal Market
Payments
Electronic Bill Presentment and Payment (EBPP) Market
Payments
Mobile Wallet Market
Payments
Indonesia Prepaid Cards Market
Payments
United Arab Emirates Real Time Payments Market
Payments
Germany POS Terminal Market
Payments
Social Media Payment Solution Market
Payments
Accelerator Card Market
Payments
Singapore Payments Market