
 France Payments Market | 2026-2036
France Payments Market Size, Share, and Industry Trends Forecast 2026-2036
France Payments Market Foresight
Modularization of payment acceptance stacks is repositioning how French merchants select providers. Worldline S.A. anchors its position through deep integration with domestic banking infrastructure. Stripe Inc. competes by specializing in developer-first APIs that simplify embedded finance deployment for mid-market software platforms.
France Payments encompasses electronic fund transfer systems, card networks, and digital wallet infrastructure that enable commercial transactions between consumers, businesses, and government entities. These systems rely on ISO 8583 messaging protocols, tokenization standards, and real-time gross settlement mechanisms to ensure interoperability across banking and non-banking channels. Mobile Wallet and Contactless Payment segments lead transaction volume growth as NFC penetration saturates urban retail environments. Payment Gateways and Merchant Aggregators concentrate margin pools by capturing software-layer value above commoditized acquiring rails.
CNIL enforces data protection standards that constrain how transaction data flows between payment service providers and third-party analytics platforms. The French Prudential Supervision and Resolution Authority (ACPR) and the EU's PSD2 framework jointly mandate strong customer authentication and open banking interfaces, reshaping issuer-processor relationships. Stakeholders must monitor how the EU AI Act intersects with automated fraud scoring systems to anticipate compliance-driven product redesigns.
Market Dynamics
The French payments sector is undergoing a fundamental reconfiguration as embedded finance architectures dismantle traditional merchant-acquirer relationships. PSD2-mandated open banking interfaces have forced incumbent processors to expose their rails to third-party fintech orchestrators, eroding historical control over customer touchpoints.
Growth Catalysts
- PSD2 Strong Customer Authentication:Regulatory mandates for SCA have accelerated tokenization infrastructure deployment across French retail banking networks. Issuers now compete on authentication friction reduction.
- Paris Fintech Cluster Density:Concentrated engineering talent in Station F and La Défense ecosystems enables rapid embedded checkout experimentation. Merchant aggregators leverage this proximity for co-development partnerships.
- NFC Terminal Saturation:Contactless hardware penetration in urban French retail now enables biometric card pilots. Transit authority partnerships drive habitual contactless behavior expansion into grocery and fuel segments.
Market Restraints
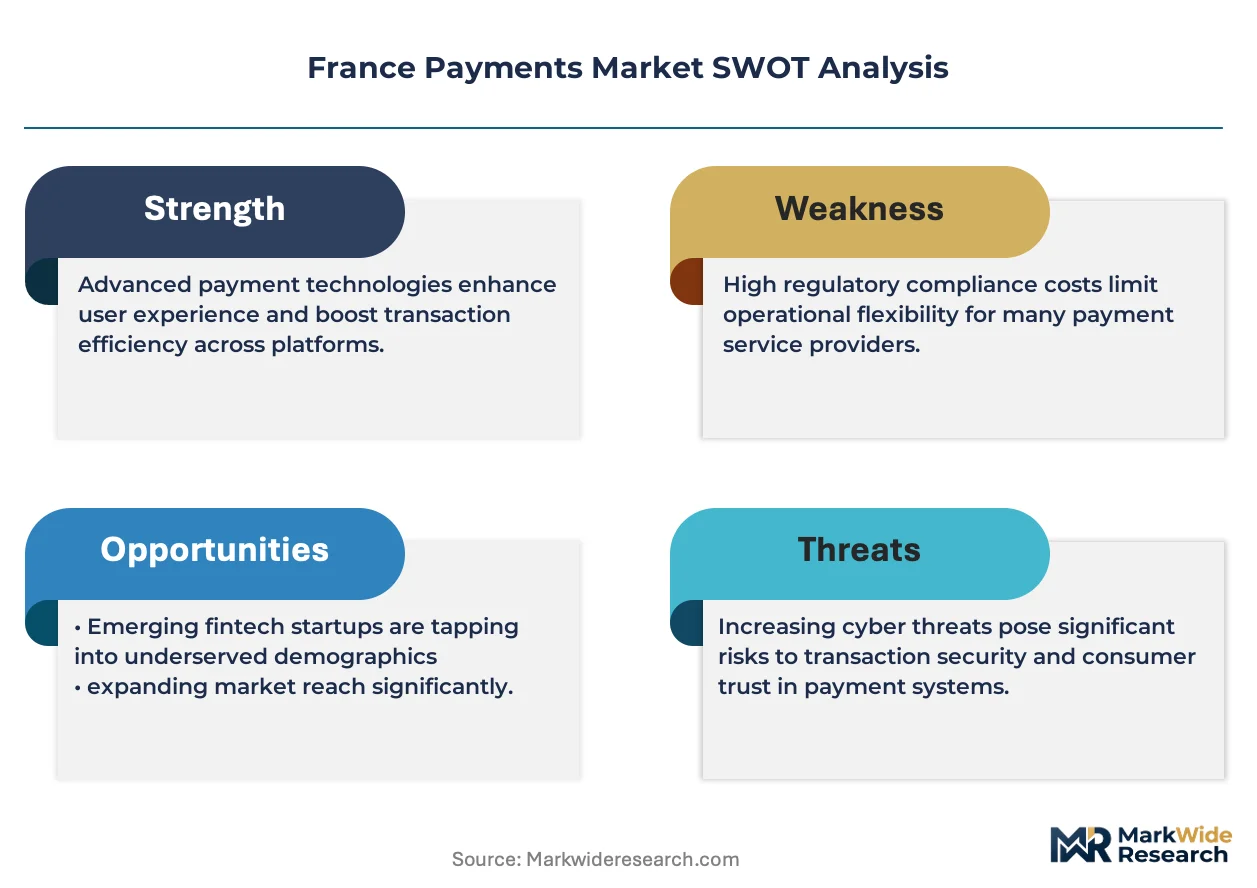
- CNIL Data Localization Requirements:Transaction analytics flowing to non-EU cloud infrastructure face consent-layer friction. Cross-border payment service providers incur compliance architecture duplication costs.
- ACPR Capital Reserve Rules:Payment institutions holding client funds must maintain prudential reserves that compress net interest margin capture. Smaller e-money issuers face balance sheet scaling constraints.
- Legacy Core Banking Integration:Domestic clearing infrastructure modernization lags API-native competitors. Batch-based settlement windows constrain real-time payment product feature parity.
Strategic Opportunities
- B2B Embedded Finance:French SaaS platforms serving SME verticals lack native payment orchestration. White-label acquiring modules represent attach-rate expansion potential for software vendors.
- EU AI Act Convergence:Automated fraud scoring systems face explainability mandates. Providers investing in interpretable machine learning architectures gain procurement preference among regulated French banks.
- Provincial Merchant Digitization:Retail banking branch networks in Lyon, Marseille, and Toulouse retain SME relationships underserved by API-first competitors. Hybrid advisory-digital models capture this gap.
Industry Challenges
- SCA Engineering Talent Scarcity:Biometric authentication and cryptographic key management expertise concentrates among Paris-based specialists. Regional payment service providers face recruitment premiums.
- ISO 20022 Migration Complexity:French banks must reconcile legacy MT messaging with structured XML formats. Dual-stack operation periods strain operational technology budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Payments Market |
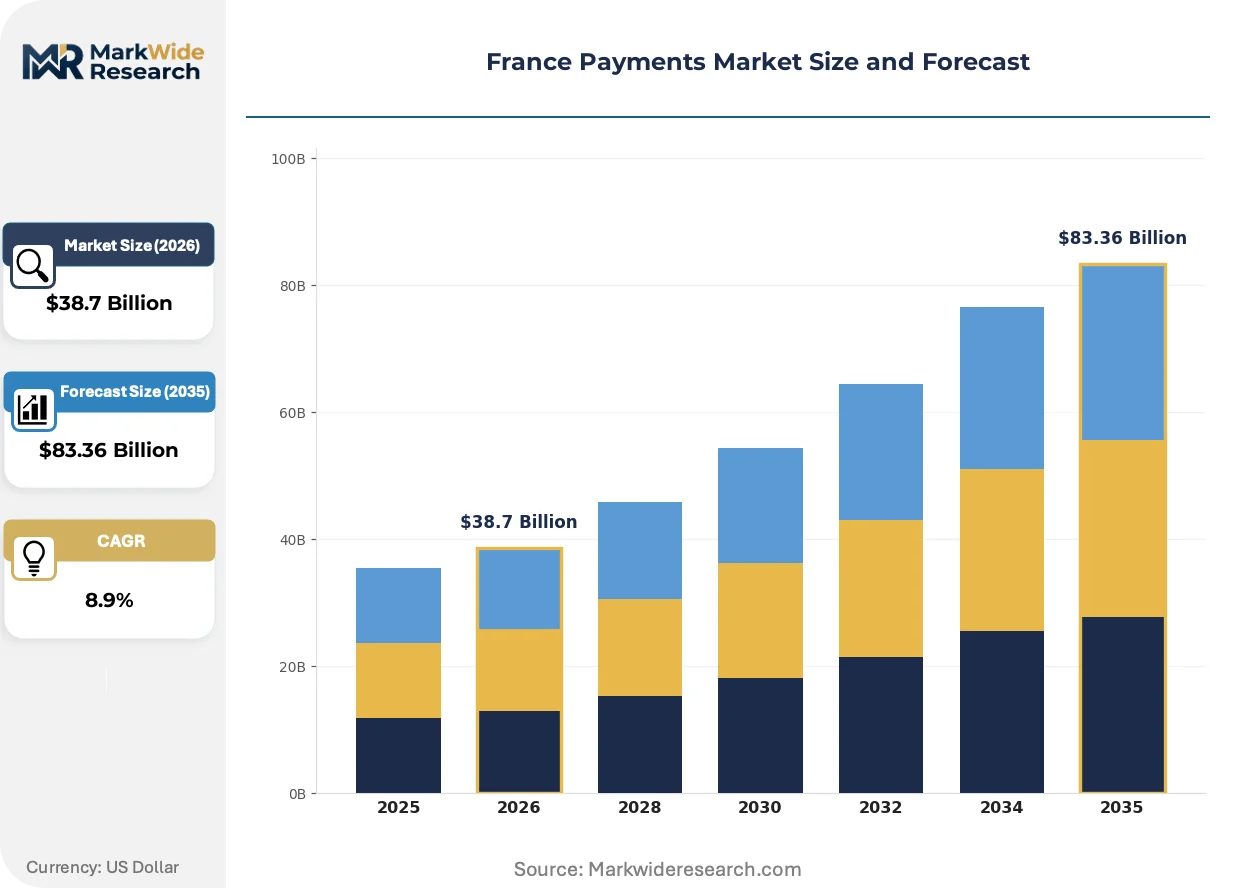
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $83.36 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer, Prepaid Card, Contactless Payment End User Category: Retail Consumers, Small & Medium Enterprises, Corporates, Government Agencies, Nonprofit Organizations Transaction Channel: Online, Point-of-Sale Terminals, Mobile Apps, Telephone, Mail Order, Kiosk Service Provider Type: Payment Gateways, Acquirers, Issuers, Payment Processors, Merchant Aggregators, Technology Vendors |
| Companies Covered | Mastercard Inc., Worldline S.A., Apple Inc., PayPal Holdings Inc., Adyen N.V., Google LLC, Samsung Electronics Co., Ltd., Stripe Inc., Visa Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Payments Market Shifts & Advancements
Payment acceptance is fragmenting into modular, API-composable layers that separate transaction processing from merchant-facing software. French market participants now compete on orchestration sophistication rather than proprietary network scale.
Biometric card authentication is overtaking PIN entry at French point-of-sale terminals. Fingerprint sensors embedded in payment cards eliminate terminal contact for high-value transactions. Major French retail banking networks are piloting these cards with premium customer segments, compressing fraud liability exposure while accelerating checkout throughput in hypermarket environments.
CNIL guidance on transaction data secondary use is tightening consent requirements for payment service providers. The regulator's 2024 clarifications restrict behavioral analytics sharing with merchant marketing platforms. French acquirers are responding by partitioning data architectures and investing in on-premise analytics infrastructure to preserve value-added service revenue streams.
Merchant procurement of payment acceptance now favors usage-based SaaS models over traditional blended-rate contracts. French mid-market retailers are unbundling gateway, risk, and acquiring services to optimize per-transaction economics. This pattern is most pronounced among digitally native brands in the CAC 40 e-commerce ecosystem, where finance teams negotiate component pricing transparency.
France Payments Market Segmentation
Payment infrastructure in France fragments across four intersecting dimensions that determine provider economics and regulatory exposure. Each segmentation layer reveals distinct margin pools and competitive dynamics that shape how Worldline, Stripe, and domestic banking networks allocate capital.
Payment Method:
Acquiring rail concentration varies sharply by payment instrument, with contactless hardware deployment and tokenization infrastructure creating divergent cost structures.
- Credit Card:Interchange fee regulation under EU MIF caps compresses issuer margins while sustaining high authorization volumes. Paris-based retail banking networks leverage credit card portfolios to cross-sell revolving credit products to affluent consumer segments.
- Debit Card:Instant payment rails displace traditional debit clearing for low-value transactions. French neobanks compete on debit card foreign exchange margins rather than domestic interchange.
- Mobile Wallet:Apple Pay and Google Pay dominate credential provisioning. Domestic alternatives like Lydia and Paylib retain share through P2P transfer network effects.
- Bank Transfer:SEPA Instant Credit Transfer penetration accelerates for B2B invoice settlement. ACPR oversight of payment initiation service providers shapes open banking API economics.
- Prepaid Card:Corporate expense management and gift card verticals sustain niche demand. E-money issuers face balance sheet reserve requirements that constrain pricing flexibility.
- Contactless Payment:NFC terminal saturation in urban French retail enables biometric card pilots. Transit authority partnerships drive habitual tap-to-pay behavior expansion.
Contactless payment absorbs the bulk of installed terminal capacity; mobile wallet is expanding most quickly.
End User Category:
Customer procurement sophistication determines pricing model adoption, with SaaS-embedded acceptance gaining traction among digitally native segments.
- Retail Consumers:Authentication friction reduction drives wallet selection. PSD2 SCA exemptions for low-risk transactions concentrate demand on biometric and tokenized credentials.
- Small & Medium Enterprises:Component-based payment stack procurement accelerates. French SaaS platforms serving SME verticals embed white-label acquiring modules to capture attach-rate expansion.
- Corporates:Treasury management integration requirements favor bank-owned payment factories. Real-time cash visibility demands strain legacy batch-based settlement infrastructure.
- Government Agencies:Procurement compliance mandates favor domestic payment service providers with ACPR authorization. CNIL data localization requirements constrain cloud-based analytics deployment.
- Nonprofit Organizations:Donation processing economics favor low-cost acquiring over feature-rich orchestration. Simplified SCA flows for recurring micro-payments reduce donor abandonment.
Retail consumers absorb the bulk of transaction volume; small and medium enterprises are climbing the fastest on embedded finance adoption.
Transaction Channel:
Channel infrastructure investment reflects urban-rural digitization gaps and merchant technical sophistication distributions.
- Online:Gateway unbundling enables merchant optimization of authorization rates and fraud scoring. French e-commerce merchants accelerate adoption of embedded checkout solutions.
- Point-of-Sale Terminals:Worldline S.A. anchors domestic terminal estate through banking network partnerships. SoftPOS migration threatens hardware refresh cycles.
- Mobile Apps:In-app provisioning of payment credentials bypasses traditional acquiring relationships. Super-app ambitions from retail banking consortia compete with standalone fintech wallets.
- Telephone:MOTO (mail order/telephone order) fraud exposure sustains premium interchange tiers. PCI DSS compliance costs concentrate among legacy merchant segments.
- Mail Order:Catalog retail decline compresses absolute volume while sustaining high-margin exception handling services.
- Kiosk:Unattended retail expansion in parking and vending drives unattended payment terminal demand. Aix-en-Provence and Lyon municipal deployments pilot transit integration.
Point-of-sale terminals absorb the bulk of installed acceptance infrastructure; mobile apps are gaining share fastest on software-layer value capture.
Service Provider Type:
Vertical margin capture concentrates at orchestration layers above commoditized clearing and settlement rails.
- Payment Gateways:API-native competitors displace legacy hosted payment pages. Developer experience and webhook reliability determine platform selection.
- Acquirers:Blended-rate contract erosion accelerates as merchants unbundle services. Net interest margin on merchant float faces ACPR capital reserve compression.
- Issuers:Token vault provisioning and biometric authentication differentiate consumer value propositions. PSD2-mandated open banking interfaces expose legacy control over customer data.
- Payment Processors:Real-time authorization infrastructure investments strain smaller regional providers. ISO 20022 migration complexity favors scaled technology vendors.
- Merchant Aggregators:Sub-merchant onboarding automation enables micro-merchant capture. Liability concentration and chargeback exposure constrain risk appetite.
- Technology Vendors:Core banking modernization lags API-native competitors. Dual-stack operation during ISO 20022 transition strains operational technology budgets.
Acquirers absorb the bulk of transaction economics; payment gateways are expanding most quickly on software-layer margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment infrastructure production concentrates among Paris-based technology vendors while consumption spreads across French metropolitan and provincial retail networks. Domestic clearing modernization lags demand for real-time settlement capabilities.
Île-de-France
Paris hosts dense fintech engineering clusters at Station F and La Défense that accelerate embedded checkout experimentation. CNIL enforces data localization requirements constraining cross-border analytics flows. Worldline S.A. anchors its domestic terminal estate through banking network partnerships concentrated in the capital region.
Auvergne-Rhône-Alpes
Lyon's retail banking branch networks retain SME relationships underserved by API-first competitors. ACPR capital reserve rules compress net interest margin capture for payment institutions holding client funds. Transit authority partnerships in the metropolitan area drive habitual contactless behavior expansion into grocery segments.
Provence-Alpes-Côte d'Azur
Marseille merchant aggregators target provincial digitization gaps with hybrid advisory-digital models. PSD2-mandated open banking interfaces force incumbent processors to expose rails to third-party fintech orchestrators. Aix-en-Provence municipal deployments pilot unattended payment terminal integration with transit systems.
Hauts-de-France
Lille-based logistics and e-commerce fulfillment centers generate B2B invoice settlement demand on SEPA Instant Credit Transfer rails. EU AI Act explainability mandates reshape automated fraud scoring procurement preferences among regulated banking networks. Regional payment service providers face recruitment premiums for biometric authentication expertise.
Nouvelle-Aquitaine
Bordeaux wine and tourism merchants accelerate adoption of usage-based SaaS payment models over traditional blended-rate contracts. ISO 20022 migration complexity strains operational technology budgets during dual-stack operation periods. SoftPOS migration threatens hardware refresh cycles in smaller urban retail environments.
France Payments Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across orchestration, acquiring, and issuer-processor layers. The vendor base clusters around three strategic archetypes: domestic banking network anchors, API-native fintech orchestrators, and global card network rails. Incumbent processors defend merchant relationships through deep core banking integration while challengers capture software-layer value. M&A activity concentrates on embedded finance capabilities and regional payment institution licenses.
Among France-based payment service providers, Worldline S.A. occupies a position representing domestic infrastructure consolidation. API-native competitors exemplified by Stripe Inc. sit within the developer-first orchestration tier. Global network anchors including Mastercard Inc. and Visa Inc. represent the rail-layer concentration that underpins transaction economics across French merchant segments.
| Leading Market Players |
|---|
| Mastercard Inc. |
| Worldline S.A. |
| Apple Inc. |
| PayPal Holdings Inc. |
| Adyen N.V. |
| Google LLC |
| Samsung Electronics Co., Ltd. |
| Stripe Inc. |
| Visa Inc. |
| Others |
Supply & Pricing Matrix
French merchant procurement of embedded checkout solutions forces acquirers to unbundle gateway, risk, and acquiring services while compressing blended-rate contracts toward usage-based SaaS economics.
Pricing Analysis
Margin tightening in merchant acquiring reflects PSD2-mandated open banking interfaces that expose legacy rails to third-party orchestrators. Three-tier pricing structure across premium biometric authentication, standard tokenized credentials, and economy-grade batch settlement separates Worldline's terminal-integrated merchants from Stripe's API-native mid-market platforms from neobank debit specialists. Cost compression accelerates because CNIL data localization requirements force compliance architecture duplication for cross-border providers. SME software platforms exhibit highest price sensitivity; large retail banking networks serving CAC 40 e-commerce ecosystems prioritize authorization rate optimization over per-transaction cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries fabricating NFC terminal chipsets and cryptographic security modules. Payment hardware draws from Taiwan, China, and South Korea; tokenization infrastructure hinges on AWS, Google Cloud, and Microsoft Azure data center concentration in EU jurisdictions. Tariff exposure on terminal hardware imports from Asian manufacturing hubs threatens hardware refresh cycle economics. Distribution runs through Worldline's banking network partnerships, Stripe's direct API sales, and merchant aggregator sub-merchant onboarding platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France Payments Market consolidation accelerates as ACPR capital reserve rules compress net interest margins and squeeze smaller e-money issuers from viable scale.
For Market Incumbents: Lock in core banking integration depth with domestic clearing infrastructure to defend against API-native orchestrators. Prioritize ISO 20022 migration completion before dual-stack operational costs erode technology budgets. Threatened by Stripe's developer-first embedded finance deployment, Worldline must deepen vertical control over terminal estate refresh cycles. For New Entrants and Emerging Players: Launch via white-label acquiring modules embedded in French SaaS platforms serving underserved SME verticals. Target provincial merchant digitization gaps in Lyon, Marseille, and Toulouse where hybrid advisory-digital models capture branch-network relationships API-first competitors neglect. Go-to-market angle: real-time SEPA Instant Credit Transfer treasury integration for B2B invoice settlement. For Investors and Strategic Acquirers: The window for entry favors payment institutions with ACPR authorization and established CNIL-compliant data architectures. Long-term viability rests on embedded finance capability stacks that attach to software platforms rather than standalone acquiring relationships. Watch biometric card pilot expansion among premium French retail banking segments as inflection indicator for authentication infrastructure replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Partnership | White-label acquiring modules attach to French SaaS platforms, capturing SME payment orchestration demand. |
| Biometric Authentication Deployment | Fingerprint-sensor card pilots with ACPR-supervised issuers compress fraud liability while accelerating checkout throughput. |
| ISO 20022 Migration Completion | Structured XML messaging reconciliation eliminates dual-stack operational cost strain during clearing modernization. |
| CNIL-Compliant Data Architecture | On-premise analytics infrastructure preserves value-added service revenue under tightened consent requirements. |
| Provincial Branch Network Digitization | Hybrid advisory-digital models capture SME relationships in Lyon, Marseille, and Toulouse underserved by API-first competitors. |
Research Methodology
Independent corroboration across payment processor executives, ACPR regulatory affairs leads, merchant aggregator platform engineers, and retail banking technology directors underwrites the qualitative findings. Primary fieldwork combined with secondary validation from ACPR authorization registers, CNIL enforcement guidance, SEPA Instant Credit Transfer volume disclosures, and EU PSD2 implementation reports. Bottom-up merchant adoption modeling and top-down clearing infrastructure capacity analysis triangulate segment sizing.
Historical reference periods anchored the projection horizon to observed PSD2 SCA implementation trajectories and NFC terminal saturation curves across French urban retail environments. Segmentation dimensions modeled include payment method, end user category, transaction channel, and service provider type alongside regional fintech cluster density. CAGRs derived from embedded finance adoption elasticity and open banking API penetration rates. Forecast inputs incorporated ACPR capital reserve rule impacts and EU AI Act explainability mandate compliance costs.
The model assumes a particular technology adoption path; alternative pathways for biometric card authentication or softPOS terminal displacement would alter the outlook. Forecasts reflect assumptions regarding PSD2 SCA exemption thresholds and CNIL consent-layer enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Transaction Monitoring Market
Payments
E-Wallet Market
Payments
3D Secure Pay Authentication Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Latin America Payment Gateway Market
Payments
Global Payments As a Service Market
Payments
Payment Instruments Market
Payments
South Korea POS Terminals Market
Payments
Canada POS Terminal Market
Payments
Electronic Bill Presentment and Payment (EBPP) Market
Payments
South Africa Gift Card and Incentive Card Market
Payments
Canada Buy Now Pay Later Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Retail POS Terminals Market
Payments
Indonesia Payments Infrastructure Market
Payments
Online Charging System (OCS) Market