
 UAE POS Terminal Market | 2026-2036
UAE POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
UAE POS Terminal Market Analytics
EMV-certified terminal specifications is rotating demand toward higher-security hardware tiers. Network International leverages its acquiring license and local data center infrastructure to dominate merchant onboarding across the Emirates. PAX Technology competes on manufacturing scale, shipping Android-based terminals with integrated NFC modules. Adyen anchors the premium segment through unified commerce APIs that connect online and in-store payment flows.
A POS terminal constitutes an electronic device that captures payment card data through embedded chip readers, near-field communication antennas, or optical scanners, typically running on ARM-based processors with PCI PTS 6.x security certification, and routes encrypted transaction payloads to payment processors for authorization and settlement. Its primary commercial purpose is to reduce cash handling costs while accelerating checkout velocity for merchants. Mobile terminals lead volume shipments among product types as UAE food delivery fleets and pop-up retail operators prioritize Bluetooth-connected, battery-powered units. NFC technology captures the fastest growth trajectory as contactless limits rise and tap-to-pay behavior normalizes among consumers. Cloud-based installation types concentrate margin pools through recurring software subscription revenue layered atop hardware sales.
The UAE Central Bank mandates PCI DSS compliance for all payment service providers, while SAMR-aligned terminal certification requirements enforce hardware security module standards for devices processing domestic dirham transactions. TRAI-equivalent telecommunications standards govern 4G and 5G connectivity modules embedded in portable terminals, shaping product design cycles for manufacturers seeking UAE market access. Stakeholders must monitor evolving stored value facility licensing as the Central Bank expands oversight to wallet-integrated POS ecosystems and buy-now-pay-later terminal plugins.
Market Dynamics
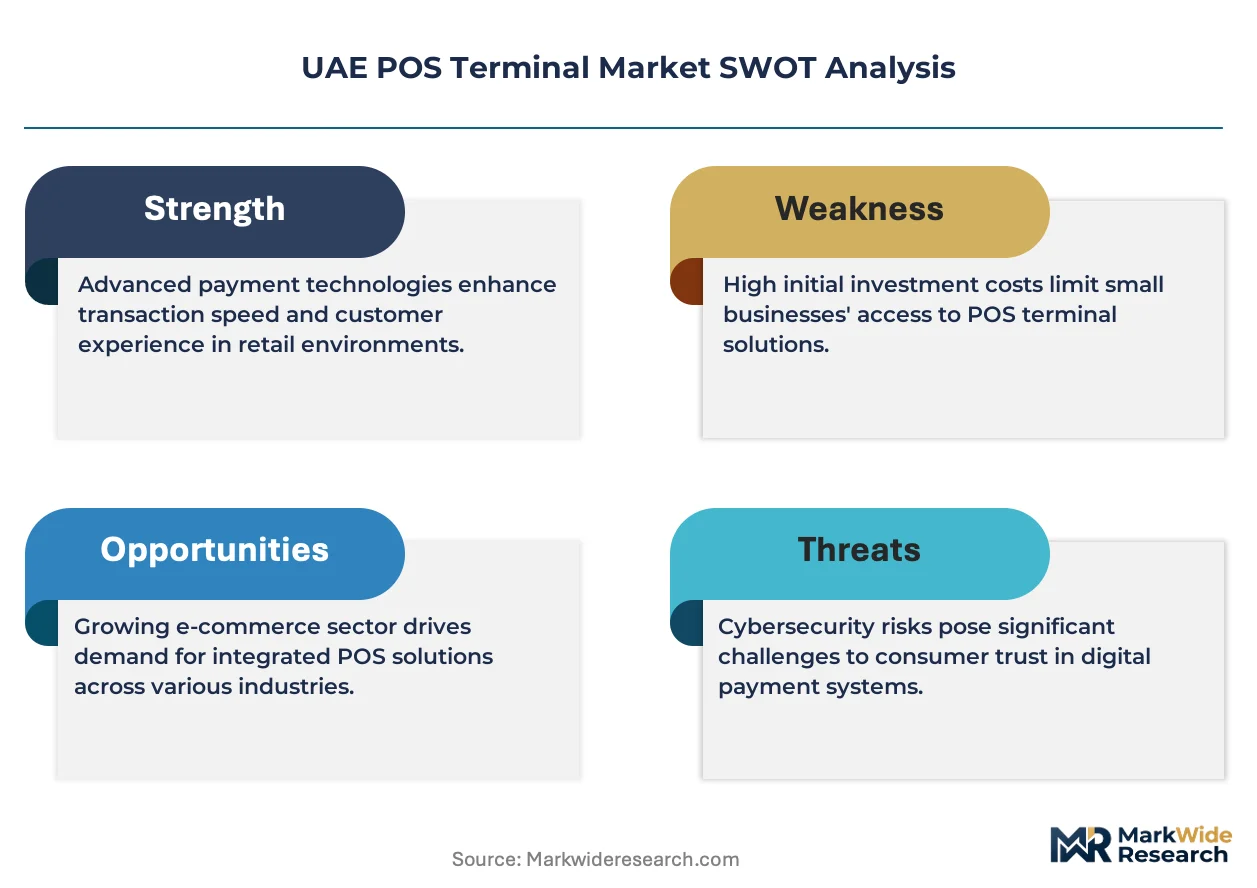
Contactless payment infrastructure is compressing hardware replacement cycles across UAE merchant estates, as tap-to-pay mandates from the Central Bank force terminal refreshes ahead of depreciation schedules.
Growth Catalysts
- Stored Value Facility Regulations:UAE Central Bank licensing requirements for wallet-integrated terminals are expanding addressable hardware demand beyond traditional card acceptance.
- Hospitality Digitization:Dubai and Abu Dhabi F&B chains are deploying NFC-enabled terminals to capture tourist spending and reduce checkout friction.
- Food Delivery Fleet Expansion:Bluetooth-connected mobile terminals are penetrating last-mile logistics as delivery platforms mandate digital payment capture for driver reconciliation.
Market Restraints
- Hardware Security Module Costs:PCI PTS 6.x certification requirements inflate bill-of-materials for domestic dirham-processing terminals.
- Acquiring License Concentration:Network International's dominance in merchant onboarding creates dependency risk for terminal distributors seeking route-to-market access.
- Smartphone Substitution:SoftPOS applications on Android and iOS devices threaten dedicated terminal volumes among micro-merchants.
Strategic Opportunities
- Abu Dhabi SME Corridors:Merchant digitization campaigns in the capital's retail zones remain underpenetrated relative to Dubai's mature infrastructure.
- Buy-Now-Pay-Later Terminal Plugins:BNPL provider integrations into POS software layers create recurring revenue streams atop hardware sales.
- Cloud-Native Terminal Management:Remote device monitoring and software-over-the-air updates are displacing on-premise estate management in franchise networks.
Industry Challenges
- EMV Certification Backlogs:SAMR-aligned terminal approval timelines extend product launch windows for manufacturers seeking UAE market entry.
- Legacy Estate Integration:Property management system interoperability with next-generation terminals requires custom middleware development for hotel and retail chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE POS Terminal Market |
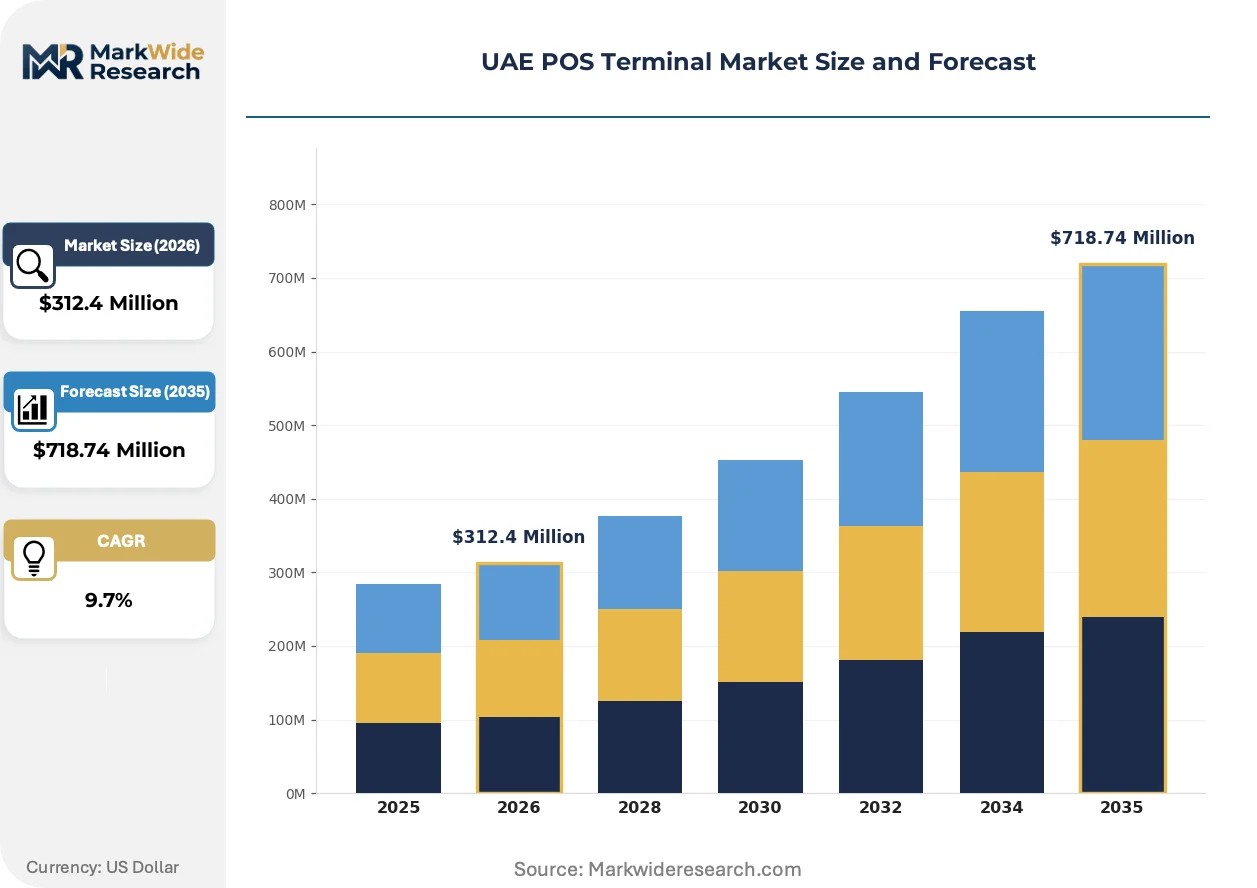
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Terminals, Countertop Terminals, Self-Service Kiosks, Integrated POS Systems Technology: EMV, NFC, Magnetic Stripe, QR Code End User: Retail, Hospitality, Healthcare, Transportation Installation Type: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | Network International, Worldline, Ingenico Group, Adyen, PayTabs, Verifone Systems, FIS Global, Diebold Nixdorf, PAX Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE POS Terminal Market Evolving Landscape
Android-based terminal operating systems are unlocking application marketplaces that transform payment hardware into commerce platforms, embedding inventory management and loyalty programs directly at the point of interaction.
SoftPOS technology is displacing dedicated hardware among pop-up retailers and independent contractors who prioritize smartphone convenience over standalone device procurement. Dubai's event economy and seasonal retail operators are adopting these solutions fastest, compressing addressable demand for entry-level terminals while forcing manufacturers to defend position through integrated peripheral ecosystems.
UAE Central Bank stored value facility regulations are mandating enhanced audit trails and real-time transaction reporting for wallet-integrated terminals. This policy shift is elevating software subscription attach rates as merchants purchase compliance dashboards alongside hardware, with hospitality chains in Dubai Marina and Downtown Dubai facing the steepest adaptation requirements.
Merchant procurement patterns are fragmenting as cloud-based terminal-as-a-service models separate hardware ownership from payment processing relationships. Abu Dhabi government contractor supply chains and Dubai free zone enterprises are piloting subscription models that bundle devices, connectivity, and support into per-transaction fees, reducing upfront capital deployment for seasonal or expansionary operations.
UAE POS Terminal Market Segmentation
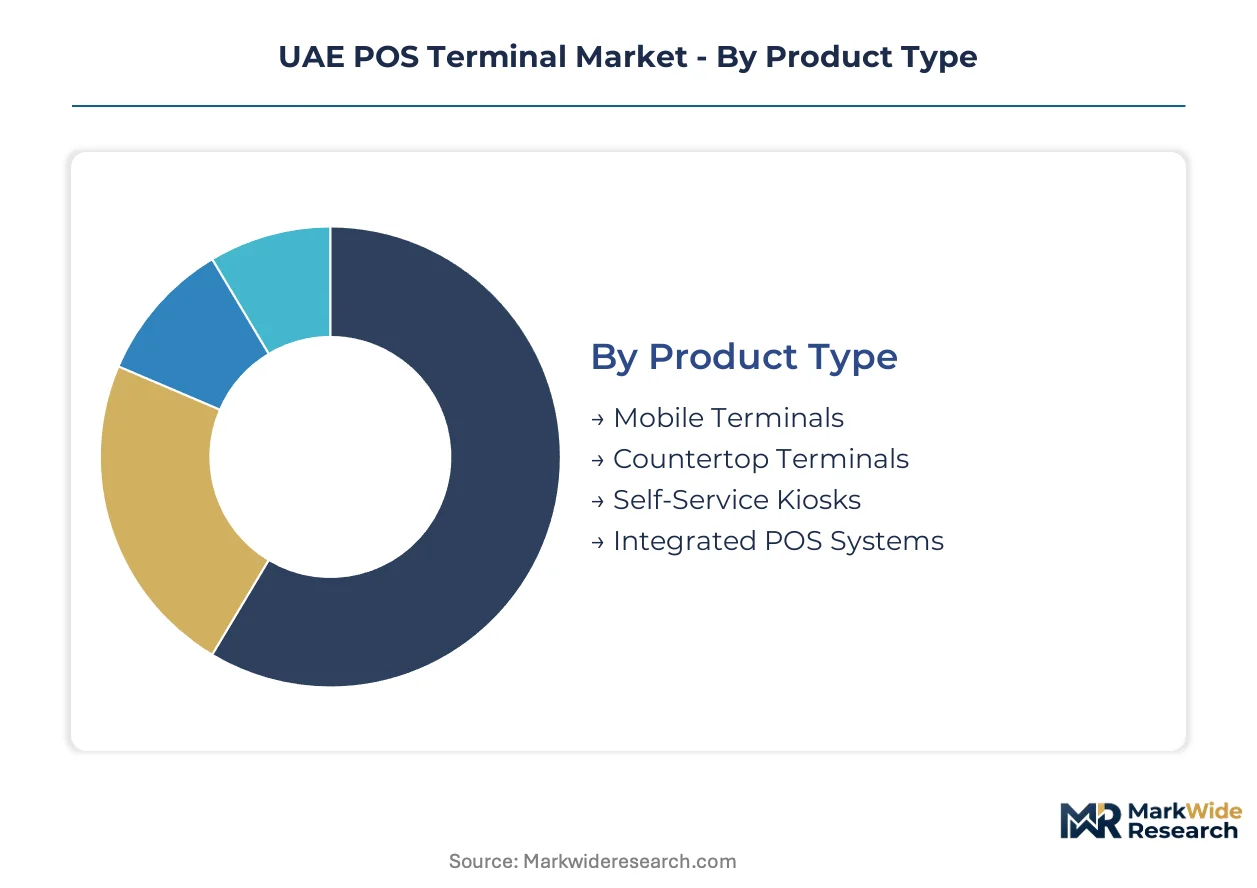
UAE POS terminal segmentation reflects divergent compliance burdens and hardware procurement patterns across merchant tiers. Product type and technology choices map directly to Central Bank certification requirements and SAMR-aligned security standards, while end-user verticals concentrate demand in Dubai's retail corridors and Abu Dhabi's emerging SME zones.
Product Type:
UAE Central Bank tap-to-pay mandates and PCI PTS 6.x certification tiers create distinct hardware procurement tracks for merchant segments with varying transaction volumes and mobility requirements.
- Mobile Terminals:Battery-powered units with Bluetooth connectivity and embedded 4G modules enable payment capture outside fixed locations. UAE food delivery fleets and pop-up retail operators in Dubai's event economy prioritize these for driver reconciliation and seasonal operations, though PCI PTS 6.x certification inflates unit costs.
- Countertop Terminals:Fixed-location devices with integrated receipt printers and Ethernet connectivity anchor permanent retail installations. Dubai Marina and Downtown Dubai hospitality chains deploy these for high-throughput checkout, with EMV-certified hardware rotating demand toward higher-security tiers under Central Bank compliance timelines.
- Self-Service Kiosks:Customer-facing touchscreen units with integrated payment modules and order management software.
- Integrated POS Systems:Full-stack solutions combining terminal hardware with inventory, loyalty, and back-office software layers.
Countertop terminals handle the majority of throughput; mobile terminals are climbing the fastest on share.
Technology:
Hardware security module requirements and contactless limit adjustments are reconfiguring technology deployment priorities across UAE merchant estates.
- EMV:Chip-card authentication protocols with cryptographic transaction processing meet UAE Central Bank minimum security baselines. All domestic dirham-processing terminals require EMV certification, making this the default technology layer for Network International's merchant onboarding and hospitality chain deployments in Abu Dhabi.
- NFC:Near-field communication antennas enable tap-to-pay transactions with sub-500 millisecond latency. Dubai's tourist-facing retail and F&B corridors drive fastest adoption as contactless limits rise and visitor spending patterns normalize toward frictionless checkout.
- Magnetic Stripe:Legacy card-swipe readers with minimal encryption for backward compatibility with non-chip cards.
- QR Code:Optical scanning modules for wallet-integrated and account-to-account payment flows.
EMV underpins all certified deployments; NFC is expanding most quickly as contactless infrastructure compresses replacement cycles.
End User:
Vertical-specific compliance dashboards and property management system integration requirements fragment procurement patterns across UAE merchant categories.
- Retail:High-volume transaction environments with multi-terminal estate management and real-time inventory synchronization. Dubai's mall operators and free zone enterprises concentrate demand here, with cloud-native terminal management displacing on-premise systems in franchise networks.
- Hospitality:F&B and hotel operations requiring tableside payment, split-check functionality, and tipping workflows. Abu Dhabi government contractor supply chains and Dubai's luxury hotel corridors drive premium segment procurement, with stored value facility regulations mandating enhanced audit trail software.
- Healthcare:Clinics and pharmacies with HIPAA-equivalent patient data protection and insurance integration requirements.
- Transportation:Fleet operators and transit authorities prioritizing ruggedized hardware and rapid transaction throughput.
Retail commands the largest installed base; hospitality is gaining share fastest through tourism recovery and digitization campaigns.
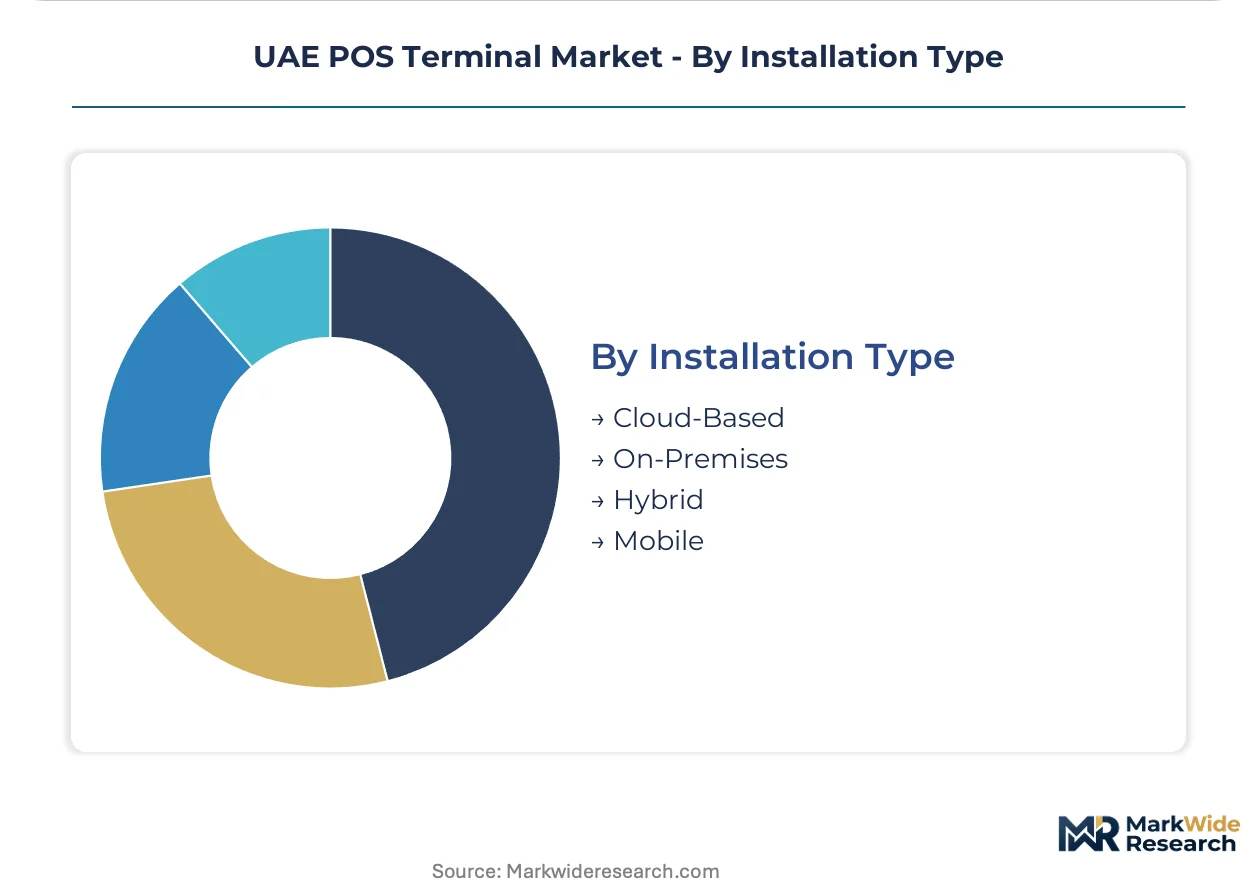
Installation Type:
Capital deployment preferences and IT infrastructure maturity determine whether merchants own hardware outright or subscribe to terminal-as-a-service models.
- Cloud-Based:Remote device monitoring with software-over-the-air updates and per-transaction fee structures. Abu Dhabi SME corridors and Dubai free zone enterprises pilot these subscription bundles to reduce upfront hardware procurement, with recurring revenue pools concentrating margin for distributors.
- On-Premises:Local server infrastructure with dedicated estate management and custom middleware development. Legacy hotel and retail chains in Dubai maintain these for property management system interoperability, though integration costs extend deployment timelines.
- Hybrid:Mixed cloud-local architectures balancing real-time processing with offline transaction buffering.
- Mobile:Purely portable deployments with cellular connectivity and no fixed infrastructure dependency.
On-premises retains the deepest legacy footprint; cloud-based models are expanding most quickly among capital-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-manufactured terminals flow primarily into Saudi Arabia and Kuwait as Gulf Cooperation Council payment infrastructure harmonizes around SAMA-aligned certification standards.
Dubai
Dubai Marina and Downtown Dubai hospitality corridors drive premium terminal procurement for high-throughput checkout environments. The UAE Central Bank's tap-to-pay mandates compress hardware replacement cycles for merchant estates. Dubai International Airport retail zones and Mall of the Emirates anchor demand concentration for NFC-enabled devices.
Abu Dhabi
Abu Dhabi's SME digitization campaigns target retail corridors with underpenetrated terminal infrastructure relative to Dubai's mature base. Stored value facility regulations from the UAE Central Bank mandate enhanced audit trail software for wallet-integrated deployments. Yas Island entertainment districts and government contractor supply chains pilot cloud-based terminal-as-a-service models.
Sharjah
Sharjah's industrial free zones and logistics hubs generate demand for ruggedized mobile terminals with extended battery life. SAMR-aligned certification requirements govern hardware security module standards for dirham-processing devices. Sharjah International Airport retail clusters and Al Qasba commercial districts concentrate mid-tier merchant procurement.
Northern Emirates
Ras Al Khaimah and Fujairah tourism developments are accelerating contactless payment adoption for visitor-facing retail and F&B operations. TRAI-equivalent telecommunications standards shape 4G and 5G connectivity module design for portable terminals. Jebel Jais mountain resorts and Fujairah beachfront properties anchor emerging demand pockets.
Saudi Arabia
Saudi Arabia imports UAE-certified terminals as SAMA regulations harmonize with UAE Central Bank frameworks across the Gulf Cooperation Council. Riyadh and Jeddah hospitality chains deploy NFC-enabled hardware for tourism sector growth. Red Sea Project developments and Diriyah Gate entertainment zones concentrate premium segment demand.
UAE POS Terminal Market Competitive Landscape
Listed leaders compete with private specialists across acquiring license access and local data center infrastructure. Network International leverages its acquiring license dominance to control merchant onboarding routes, while manufacturing-scale competitors ship Android-based terminals with integrated NFC modules. Three archetypes define positioning: acquiring-license holders with captive distribution, manufacturing-scale hardware vendors with cost advantages, and unified-commerce platforms with API-driven premium offerings. Competitive moves concentrate on strategic partnerships with hospitality chains and cloud-native terminal management subscriptions.
Among acquiring-license holders, Network International anchors the domestic distribution tier with local data center infrastructure and merchant onboarding control. PAX Technology exemplifies the manufacturing-scale archetype with Android-based terminal production and integrated NFC module capabilities. Adyen occupies the unified-commerce position, connecting online and in-store payment flows through API-driven software layers. These three represent the dominant competitive vectors shaping procurement patterns across Dubai's retail corridors and Abu Dhabi's emerging SME zones.
| Leading Market Players |
|---|
| Network International |
| Worldline |
| Ingenico Group |
| Adyen |
| PayTabs |
| Verifone Systems |
| FIS Global |
| Diebold Nixdorf |
| PAX Technology |
| Others |
Value Network & Pricing Analysis
Per-transaction fee bundling locks in hardware access and price visibility for UAE merchants seeking to avoid upfront capital deployment. This contract structure concentrates procurement leverage with acquiring-license holders while compressing margin pools for standalone terminal distributors.
Pricing Analysis
Next-generation NFC-enabled terminals command substantial premiums over prior-generation EMV-only hardware and aging magnetic-stripe units. Three-tier pricing structure across premium, standard, and economy levels segments by PCI PTS certification grade and after-sales service bundling. Cost compression in entry-level tiers is intensifying because SoftPOS substitution threatens dedicated device volumes among micro-merchants. Food delivery fleets and pop-up operators exhibit highest price sensitivity; luxury hospitality chains in Dubai Marina show lowest.
Supply Chain Analysis
Strategic stockpiling of ARM-based processors and hardware security modules dominates procurement patterns as manufacturers buffer against EMV certification backlogs. China, Taiwan, and South Korea anchor component sourcing for terminal chipsets and NFC antenna modules. Bill-of-materials inflation rests on semiconductor foundry capacity constraints and precious metal price volatility in connector assemblies. Single-source vulnerability concentrates in payment processor gateway dependencies. Distribution runs through Network International's acquiring infrastructure and hospitality chain direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of SAMR-aligned certification expertise and local data center infrastructure constrains competitive entry for hardware vendors lacking UAE Central Bank relationships. This capability gap favors incumbents with established regulatory navigation capacity.
For Market Incumbents: Secure cloud-native terminal management subscriptions to lock in recurring revenue streams and defend against SoftPOS displacement. Deepen backward integration into hardware security module sourcing to offset PCI PTS 6.x certification cost inflation. Prioritize acquiring-license renewal negotiations ahead of regulatory tightening on stored value facility oversight. For New Entrants and Emerging Players: Anchor in Abu Dhabi's underpenetrated SME corridors where merchant digitization campaigns lag Dubai's mature infrastructure. Target food delivery fleet operators with ruggedized mobile terminal offerings bundled with driver reconciliation software. Pursue white-label partnerships with regional payment processors lacking hardware manufacturing scale. For Investors and Strategic Acquirers: Android-based terminal specialists with integrated application marketplace capabilities represent the most defensible acquisition profile for long-term positioning. Terminal-as-a-service platform operators with established UAE Central Bank compliance dashboards offer recurring revenue visibility across the analysis window. Watch for inflection when BNPL provider terminal plugin adoption crosses hospitality chain procurement thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Terminal Management Deployment | Remote software-over-the-air updates displace on-premise estate management in franchise networks. |
| Buy-Now-Pay-Later Terminal Plugin Integration | BNPL provider software layers create recurring revenue streams atop hardware sales. |
| Hardware Security Module Backward Integration | In-house production of PCI PTS 6.x components offsets certification-driven bill-of-materials inflation. |
| Abu Dhabi SME Corridor Market Entry | Government contractor supply chains and retail zones remain underpenetrated relative to Dubai. |
| SoftPOS Application Platform Launch | Smartphone-based payment capture threatens dedicated terminal volumes among micro-merchants. |
Research Methodology
Desk research of UAE Central Bank regulatory filings, payment processor annual disclosures, and customs import records preceded structured interviews with terminal hardware procurement managers, hospitality chain IT directors, payment gateway integration specialists, and fintech product executives. Primary fieldwork with Network International distribution partners and PAX Technology regional representatives combined with secondary validation against SAMR certification databases and PCI SSC compliance registries. Bottom-up shipment estimates triangulated against top-down payment transaction volume projections.
Variance decomposition across product type, technology generation, end-user vertical, and installation model segmentation dimensions structured the analytical framework. CAGRs derived from logistic adoption curves fitted to contactless payment infrastructure deployment timelines. Hardware replacement cycle compression and stored value facility licensing expansion anchored industry-specific forecast inputs throughout the projection horizon.
Material uncertainties — EMV certification backlog durations, SoftPOS substitution velocity, and UAE Central Bank stored value facility enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory harmonization continuity and hospitality sector tourism recovery trajectory. Revision becomes warranted when contactless transaction share crosses merchant estate refresh decision thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Electronic Payment System for Transportation Market
Payments
Europe POS Terminal Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Kenya Mobile Money Market
Payments
Payment Analytics Software Market
Payments
Wireless POS Terminals Market
Payments
Indonesia Mobile Payments Market
Payments
Latin America Mobile Payment Market
Payments
Payment Card Market
Payments
Retail Cash Management Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Finland POS Terminals Market
Payments
Italy POS Terminals Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
B2B Payments Platform Market
Payments
Transaction Monitoring Market