
 Mexico Payments Market | 2026-2036
Mexico Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Payments Market Outlook
Mexican fintech infrastructure is rebalancing as digital payment rails replace legacy cash dependence. Banco Santander México leverages its branch network to anchor corporate treasury services. BBVA México competes through mobile-first banking interfaces targeting underbanked populations. Mercado Pago dominates merchant onboarding with integrated e-commerce and credit offerings.
Mexico Payments encompass electronic fund transfer systems, card networks, and digital wallets that facilitate commercial transactions between consumers, businesses, and financial entities. These systems rely on real-time gross settlement protocols, tokenized credentials, and interoperable switching infrastructure to clear peso-denominated flows. Mobile Wallet adoption accelerates fastest among unbanked segments, where QR code acceptance bypasses terminal hardware costs. Credit Card transaction volume sustains margin pools in affluent urban centers, while NFC contactless rails expand through transit and quick-service retail integration.
Banco de México governs systemic payment stability through SPEI oversight and liquidity provision mandates. CNBV licensing requirements shape fintech market access, dictating capital reserves and consumer protection standards. COFECE scrutiny of interchange fees constrains pricing power across card networks. Stakeholders must monitor regulatory divergence between centralized bank mandates and decentralized crypto asset frameworks.
Market Dynamics
SPEI real-time settlement rails are compressing transaction clearing windows from T+1 to near-instant, forcing legacy batch-processing systems into obsolescence across Mexican financial infrastructure.
Growth Catalysts
- CNBV Open Banking Framework:Mandated data portability is unlocking API-based financial services for third-party fintech developers.
- QR Code Interoperability Standards:Unified merchant acceptance protocols are eliminating terminal hardware barriers for informal commerce segments.
- Guadalajara E-commerce Cluster:Digital marketplace concentration is accelerating wallet onboarding velocity among SME merchants.
Market Restraints
- Cash Infrastructure Sunk Costs:Mexico's extensive ATM and branch networks create path dependency for incumbent deposit-taking institutions.
- Telecom Coverage Asymmetry:Rural connectivity gaps limit real-time payment penetration in southern states like Chiapas and Oaxaca.
- Biometric Verification Requirements:CNBV identity authentication mandates impose compliance friction on thin-file customer segments.
Strategic Opportunities
- Cross-border Remittance Rails:SPEI linkage with US correspondent banking networks targets $60 billion annual flows from diaspora workers.
- Embedded Finance Convergence:API orchestration between accounting software and payment acceptance is penetrating mid-market enterprise segments.
- CNBV Fintech Sandbox:Regulatory experimentation permits are accelerating novel credit-underwriting models for unbanked populations.
Industry Challenges
- Legacy Core System Integration:Mainframe architecture at traditional banks constrains real-time API deployment timelines.
- Fraud Detection Talent Scarcity:Machine-learning model development for transaction monitoring outpaces available data science capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Payments Market |
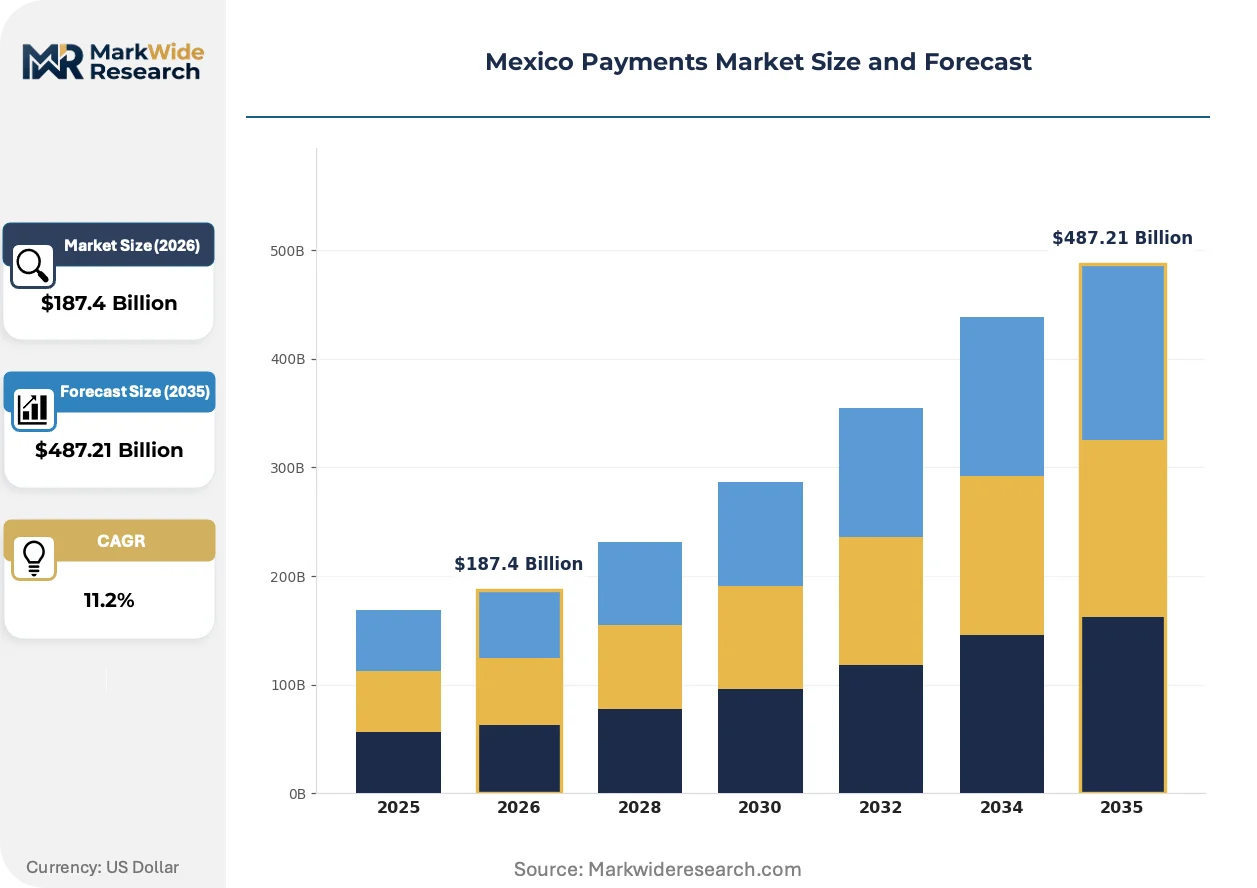
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $487.21 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Card, Debit Card, Mobile Wallet, Bank Transfer End User: Retailers, E-Commerce Platforms, Service Providers, Financial Institutions Transaction Volume: Low, Medium, High, Very High Technology: QR Code, NFC, Blockchain, Traditional POS |
| Companies Covered | Banco Santander México, Visa, Banco de México, PayPal, Mastercard, BBVA México, Mercado Pago, Conekta, Citibanamex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Payments Market Strategic Shifts
Tokenized credential architecture is replacing static card numbers across Mexican payment flows, compressing fraud exposure windows while enabling device-agnostic authentication methods.
Biometric authentication protocols are consolidating transaction security standards across mobile wallet providers. Unbanked consumers in Mexico City metropolitan zones are adopting facial-recognition verification at triple the rate of password-based alternatives. This consolidation is collapsing the traditional trade-off between security friction and user conversion rates.
COFECE interchange fee scrutiny is reshaping merchant acquisition economics across card networks. The antitrust regulator's pricing investigations are compressing issuer margin pools and redirecting investment toward alternative revenue streams. Retail banking segments are responding by accelerating SPEI-based debit product development.
Subscription-based billing models are displacing one-time transaction structures among SaaS and utility providers. Mid-market enterprises in Nuevo León manufacturing corridors are migrating to automated recurring payment rails. This behavioral pivot is most visible in Monterrey's industrial zones where cash flow predictability commands premium pricing.
Mexico Payments Market Segmentation
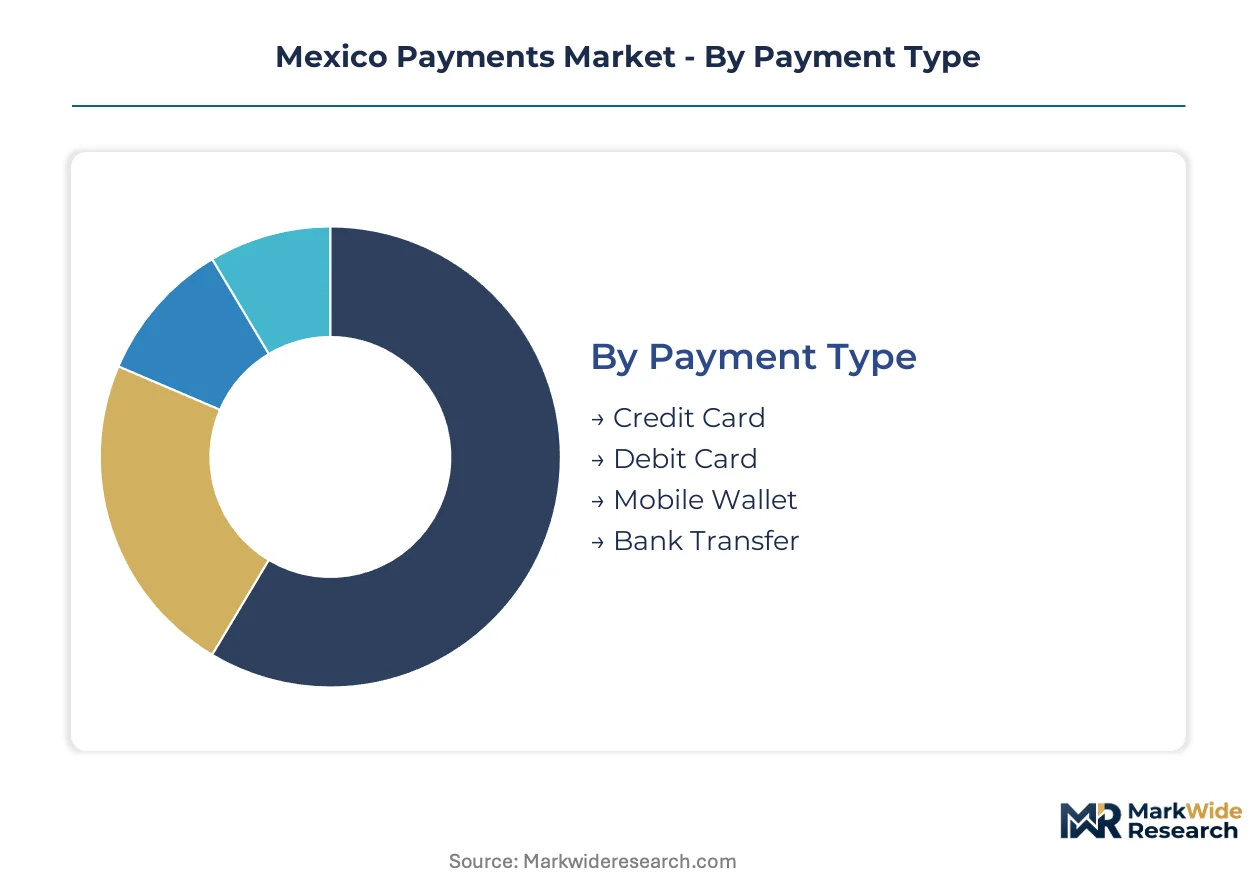
Payment infrastructure in Mexico fragments across four critical dimensions that determine regulatory burden, technology deployment, and merchant acquisition economics. Each segmentation axis reveals distinct compliance pathways and margin structures that shape competitive positioning.
Payment Type:
CNBV licensing requirements vary sharply across instruments, with electronic money institutions facing lighter capital reserves than full bank charter holders while SPEI participation mandates create uniform technical standards for real-time rails.
- Credit Card:Revolving credit instruments with tokenized credential architecture dominate affluent urban corridors. Mexico City and Monterrey retail clusters sustain interchange revenue pools despite COFECE pricing pressure. Issuers leverage co-brand partnerships with airline and retail chains to offset margin compression.
- Mobile Wallet:Stored-value accounts accessible via smartphone applications are penetrating unbanked populations fastest. QR code acceptance networks in Guadalajara and Puebla eliminate terminal hardware barriers for informal merchants. CNBV simplified licensing for e-money issuers accelerates onboarding velocity.
- Debit Card:Direct-linked demand deposit instruments clearing through SPEI real-time rails. Traditional bank networks anchor corporate treasury adoption while fintech challengers push contactless EMV migration.
- Bank Transfer:Account-to-account electronic fund movements leveraging Banco de México settlement infrastructure. Enterprise payroll and supplier payment flows concentrate in Nuevo León manufacturing belts.
Credit Card sits at the top of the volume ranking, with Mobile Wallet climbing the fastest.
End User:
Customer procurement patterns diverge sharply between integrated platform players and fragmented standalone merchants, with API orchestration capabilities determining acquisition cost economics.
- E-Commerce Platforms:Digital marketplace operators requiring embedded checkout and split-payment settlement architectures. Mercado Libre and Amazon México deployments drive demand for automated reconciliation and multi-party escrow services.
- Retailers:Brick-and-mortar merchants spanning convenience stores, supermarkets, and specialty shops. QR interoperability standards enable smartphone-based acceptance without dedicated terminal investment.
- Service Providers:Utility, telecom, and subscription businesses migrating to automated recurring billing rails. Monterrey industrial zone SaaS vendors prioritize cash flow predictability through tokenized credential vaulting.
- Financial Institutions:Banks and credit unions modernizing legacy core systems for real-time API deployment. SPEI integration mandates force mainframe architecture upgrades at traditional deposit-taking institutions.
E-Commerce Platforms command the deepest technology integration budgets, while Service Providers are gaining share fastest through subscription billing conversion.
Transaction Volume:
Scale thresholds determine fraud detection investment intensity and interchange fee tiering structures across merchant categories.
- Very High:Enterprise-grade processors clearing billions of pesos monthly through redundant SPEI connections. Walmart México and OXXO convenience networks demand 99.99% uptime SLAs with sub-second authorization latency.
- High:Mid-market chains and regional retail groups with concentrated geographic footprints. Jalisco and Veracruz supermarket cooperatives negotiate volume-based acquiring fee discounts.
- Medium:Growing independents and franchise operators crossing monthly thresholds for premium service tiers. Quick-service restaurant chains in Querétaro and León optimize for settlement velocity.
- Low:Micro-merchants and sole proprietors with sporadic transaction patterns. Street vendors and taxi operators in Mexico City metropolitan zone adopt QR acceptance with zero fixed monthly fees.
Very High volume segments anchor infrastructure investment decisions, with Low volume tiers expanding most quickly through smartphone-based onboarding.
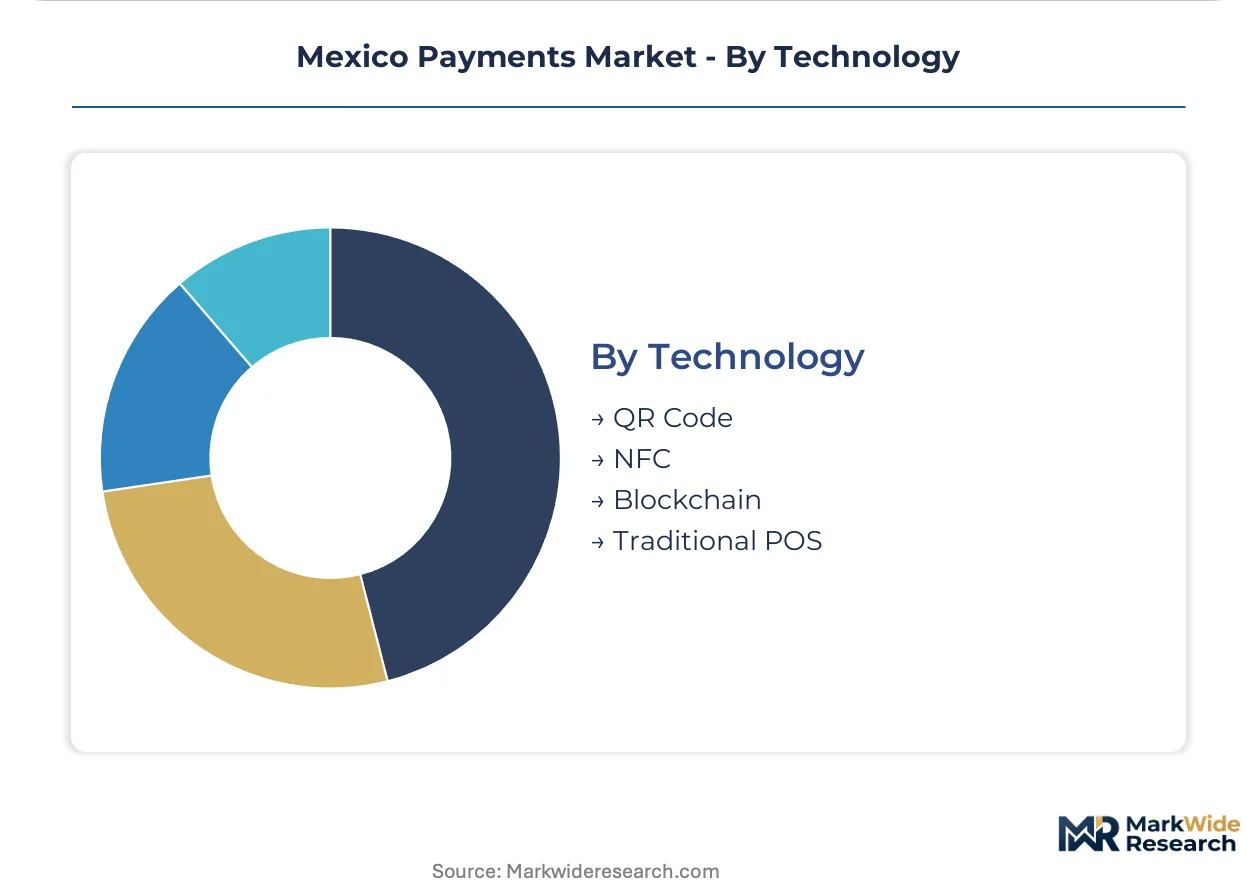
Technology:
Hardware deployment requirements and certification timelines create divergent paths to merchant activation across acceptance modalities.
- QR Code:Static and dynamic two-dimensional barcodes enabling smartphone-to-smartphone fund transfers. Interoperability standards from Banco de México eliminate fragmentation between wallet providers.
- NFC:Contactless proximity communication protocols embedded in cards and mobile devices. Transit authority deployments in Mexico City Metro accelerate consumer habit formation.
- Traditional POS:Dedicated terminal hardware with EMV chip and magnetic stripe reading capability. Incumbent acquirer networks leverage sunk cost advantages in established retail footprints.
- Blockchain:Distributed ledger settlement rails for cross-border remittance and experimental central bank digital currency pilots. Regulatory clarity remains pending at CNBV and Banco de México.
Traditional POS maintains installed base dominance, with QR Code capturing activation momentum fastest among new merchant segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping payment infrastructure deployment across Mexico, as compliance-cost differentials between states accelerate fintech concentration in permissive jurisdictions while legacy banks retreat to fortified regulatory moats.
Mexico City Metro
SPEI real-time settlement density and CNBV fintech sandbox proximity drive challenger bank clustering. Banco de México oversight mandates concentrate payment processor headquarters in the capital. Polanco and Santa Fe financial districts host Mercado Pago and Conekta engineering centers.
Nuevo León
Industrial payroll automation and supplier payment digitization anchor enterprise demand. CNBV simplified e-money licensing accelerates fintech onboarding velocity. Monterrey manufacturing corridors adopt subscription billing rails for SaaS vendor ecosystems.
Jalisco
Guadalajara's e-commerce marketplace density propels QR code merchant acquisition. State-level digital inclusion programs complement federal CNBV open banking mandates. Zapopan technology parks concentrate wallet provider back-office operations.
Bajío Region
Querétaro and León quick-service retail chains optimize for contactless settlement velocity. Regional banking cooperatives leverage SPEI integration for competitive acquiring fee positioning. Automotive supplier payment corridors drive bank transfer volume concentration.
Northern Border States
Cross-border remittance corridor density attracts US correspondent banking partnerships. Banco de México SPEI linkage pilots target diaspora worker fund flows. Tijuana and Ciudad Juárez cash-to-digital conversion programs accelerate unbanked wallet adoption.
Mexico Payments Market Competitive Environment
Mexico City-based financial conglomerates anchor one tier; US-based payment networks hold infrastructure dominance; domestic fintech specialists capture merchant acquisition velocity. The market structures around three archetypes: legacy deposit-taking institutions with SPEI integration mandates, global card networks with tokenized credential standards, and API-native challengers with QR interoperability. Consolidation pressure operates through strategic partnerships between incumbent banks and fintech infrastructure providers, while vertical integration into merchant software stacks emerges as a secondary competitive vector.
Within the legacy banking tier, Banco Santander México and BBVA México exemplify deposit-taking institutions navigating core system modernization imperatives. Among API-native challengers, Mercado Pago occupies a position exemplifying marketplace-integrated financial services, while Conekta represents specialized merchant onboarding infrastructure. These anchors illustrate the competitive tension between branch-network scale and smartphone-first acquisition economics.
| Leading Market Players |
|---|
| Banco Santander México |
| Visa |
| Banco de México |
| PayPal |
| Mastercard |
| BBVA México |
| Mercado Pago |
| Conekta |
| Citibanamex |
| Others |
Value Chain & Pricing Dynamics
SPEI integration costs cascade from Banco de México settlement infrastructure through acquiring fee tiers, compressing margins for legacy batch-processors while API-native challengers capture volume discounts through cloud-native architecture.
Pricing Analysis
Acquirer margin layers stratify across premium, standard, and economy tiers based on settlement velocity guarantees and fraud liability allocation. COFECE interchange fee scrutiny intensifies cost compression at the issuer level, forcing margin migration toward value-added services. Enterprise merchants in Nuevo León manufacturing corridors demonstrate lowest price sensitivity due to cash flow predictability premiums, while micro-merchants in Mexico City informal commerce segments optimize for zero fixed-fee QR acceptance.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan semiconductor foundries supplying EMV chip modules to Mexican terminal manufacturers. Payment hardware assembly draws from China, Mexico, and Brazil, with tokenization software development concentrated in US and Israeli cybersecurity clusters. Tariff exposure on Chinese terminal components threatens merchant acquisition economics. Distribution runs through bank-owned acquiring networks and independent payment service providers with direct ISO relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
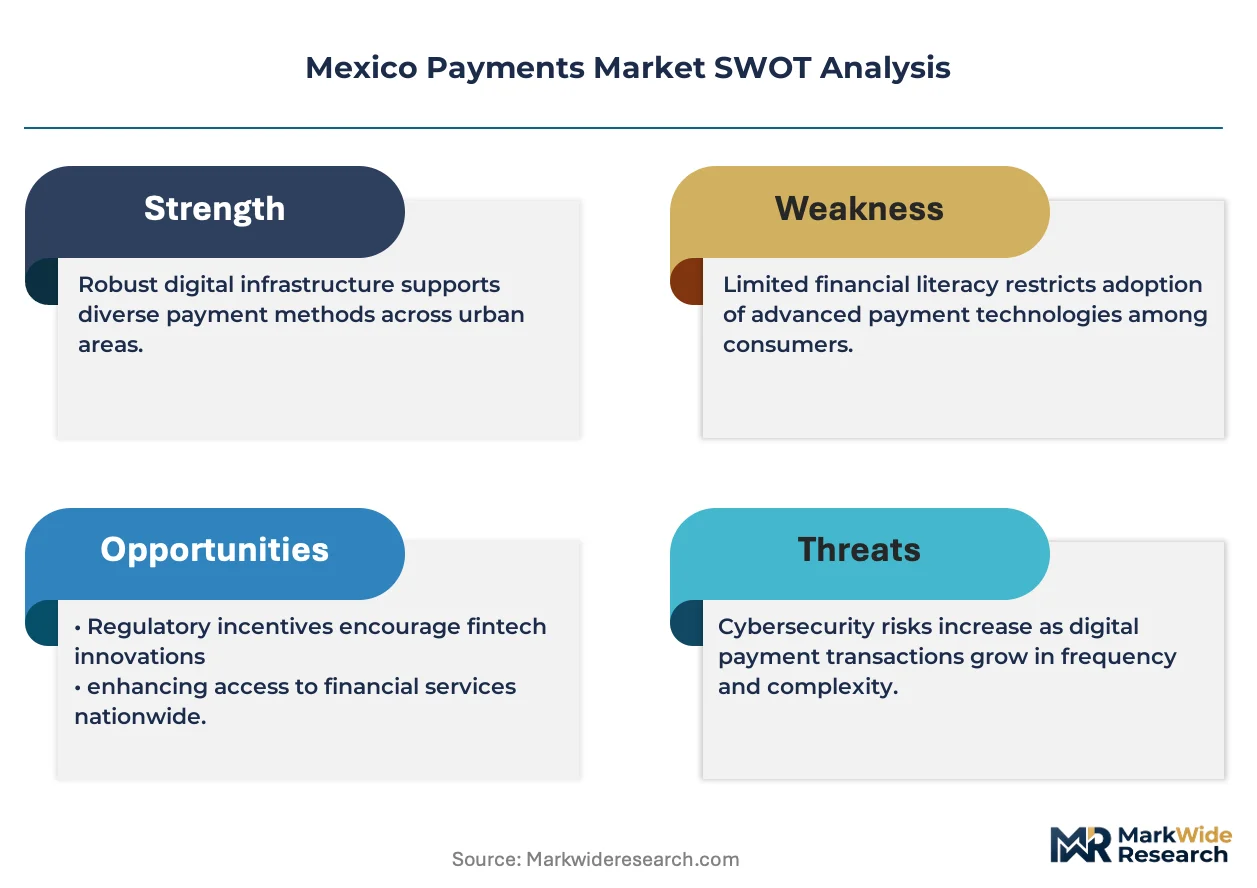
Mexico Payments operates as a regulatory compounder where CNBV open banking mandates create structural demand for API infrastructure investment across the financial sector.
For Market Incumbents: Anticipate SPEI real-time settlement obsolescence of legacy mainframe cores by accelerating cloud migration timelines. BBVA México and Santander México must defend corporate treasury relationships against fintech challengers through embedded finance API orchestration. Vertical integration into merchant software stacks represents the critical lever for retention economics. For New Entrants and Emerging Players: CNBV fintech sandbox licensing in Mexico opens a window for specialized credit-underwriting models targeting unbanked populations in Jalisco and Guanajuato. White-space concentration exists in SME payroll automation across Bajío manufacturing belts. Go-to-market velocity depends on QR interoperability certification with Banco de México standards. For Investors and Strategic Acquirers: Consolidation pressure builds where merchant acquisition costs exceed lifetime value recovery horizons for sub-scale fintechs. Long-term viability favors API-native infrastructure providers with SPEI direct participation. Watch CNBV capital reserve requirement adjustments as the inflection signal for sector repricing.| Strategic Initiative | Industry Significance |
|---|---|
| SPEI Direct Participation | Eliminates intermediary settlement delays for real-time merchant funding. |
| QR Interoperability Certification | Unlocks Banco de México unified acceptance standards across wallet providers. |
| Embedded Finance API Development | Penetrates mid-market enterprise segments through accounting software integration. |
| Biometric Authentication Investment | Collapses CNBV compliance friction for thin-file customer onboarding. |
| Cross-border Remittance Rail Linkage | Captures diaspora worker flows through US correspondent banking partnerships. |
Study Parameters
Direct dialogue with payment network executives, fintech product managers, CNBV regulatory affairs specialists, and merchant acquiring operations heads grounded qualitative findings. Secondary validation drew from Banco de México statistical bulletins, CNBV licensing registries, COFECE antitrust filings, and SPEI transaction volume disclosures. Bottom-up merchant adoption modeling triangulated against top-down payment flow estimates.
Segment-level projections across payment type, end user, transaction volume, and technology dimensions were generated through the analysis window. CAGRs were derived from historical SPEI volume trajectories and mobile wallet penetration curves. Forecast inputs incorporated CNBV regulatory timeline assumptions and e-commerce marketplace growth correlations.
Revisions become necessary when CNBV capital requirement changes, COFECE interchange rulings, or SPEI technical standard updates materialize. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
UK Prepaid Cards Market
Payments
Mobile Payment Market
Payments
Brazil POS Terminal Market
Payments
United Kingdom Payment Gateway Market
Payments
Global Mobile Payment Technology Market
Payments
Transaction Monitoring Market
Payments
Digital Payment in Healthcare Market
Payments
Canada Real Time Payments Market
Payments
Japan Real Time Payment Market
Payments
Germany Mobile Payments Market
Payments
Asia Pacific POS Terminal Market
Payments
Online Payment Gateway Market
Payments
United States POS Terminals Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Online Charging System (OCS) Market
Payments
United Arab Emirates Payment Market