
 Romania POS Terminals Market | 2026-2036
Romania POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Romania POS Terminals Market Analytics
Software-defined terminal features is pivoting vendor revenue models from hardware sales to recurring SaaS streams. ING Bank Romania leverages its merchant banking footprint to bundle POS subscriptions with working capital products. Banca Transilvania anchors its strategy in Transylvania's dense SME retail base, while myPOS competes aggressively on cross-border settlement speed for e-commerce merchants.
A POS terminal is an electronic device that captures payment card data through integrated chip readers, NFC antennas, or magnetic stripe heads, processing transactions via encrypted communication with acquiring banks. These systems serve as the terminal node in retail payment infrastructure, authenticating funds transfer and generating settlement records. Mobile terminals and cloud-based terminals capture the fastest expansion as Romanian food delivery networks and pop-up vendors prioritize untethered checkout, while fixed terminals remain the margin pool in supermarket and hypermarket deployments. EMV and contactless payment technologies dominate new installations as card issuers phase out mag-stripe acceptance liability.
The National Bank of Romania governs payment system licensing and terminal security certification, while BIS standards and EU PSD2 directives shape device interoperability and strong customer authentication protocols. Romanian fiscal law mandates electronic receipt transmission to ANAF, the national tax authority, which forces terminal vendors to integrate certified fiscal modules or risk market exclusion. Stakeholders must weigh whether to build proprietary acquiring rails or partner with existing processors as transaction volume thresholds trigger regulatory reclassification.
Market Dynamics
Romania's POS terminal market is being reshaped by the National Bank of Romania's aggressive push for electronic payment infrastructure, which forces merchants to upgrade legacy hardware or face exclusion from the formal economy. This regulatory pressure compounds with fiscal law mandates requiring direct receipt transmission to ANAF, creating a hardware refresh cycle that vendors must navigate.
Growth Catalysts
- EU PSD2 Strong Authentication:The directive mandates upgraded terminal security protocols, compelling Romanian retailers to replace non-compliant devices with certified chip-and-PIN systems.
- Food Delivery Networks:Bucharest-based aggregators and dark kitchen operators are deploying mobile terminals for untethered curbside payment capture.
- Contactless Infrastructure:NFC antenna integration in new terminals accelerates transaction speed for hospitality venues in Cluj-Napoca's dense urban core.
Market Restraints
- Certified Fiscal Module Costs:ANAF-mandated hardware adds fixed cost layers that compress margins for micro-merchants in rural counties.
- Mag-Stripe Liability Phaseout:Card issuer policies eliminating mag-stripe acceptance liability strand legacy terminal investments for small retailers.
- Transylvania SME Credit Access:Working capital constraints in secondary cities delay terminal refresh cycles beyond regulatory deadlines.
Strategic Opportunities
- Cloud Terminal Convergence:Software-defined architectures merging payment processing with inventory management create upsell potential for hospitality groups.
- Cross-Border E-Commerce Settlement:Romanian online merchants need terminals with multi-currency instant settlement for EU market access.
- Pop-Up Vendor Channel:Seasonal markets and festival circuits in Brașov and Sibiu remain underpenetrated by mobile terminal providers.
Industry Challenges
- EMV Certification Timelines:Terminal vendors face extended approval queues at the National Bank of Romania, delaying product launches.
- Legacy Cash Register Integration:Merchants operating hybrid systems encounter firmware conflicts between fiscal modules and existing accounting software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania POS Terminals Market |
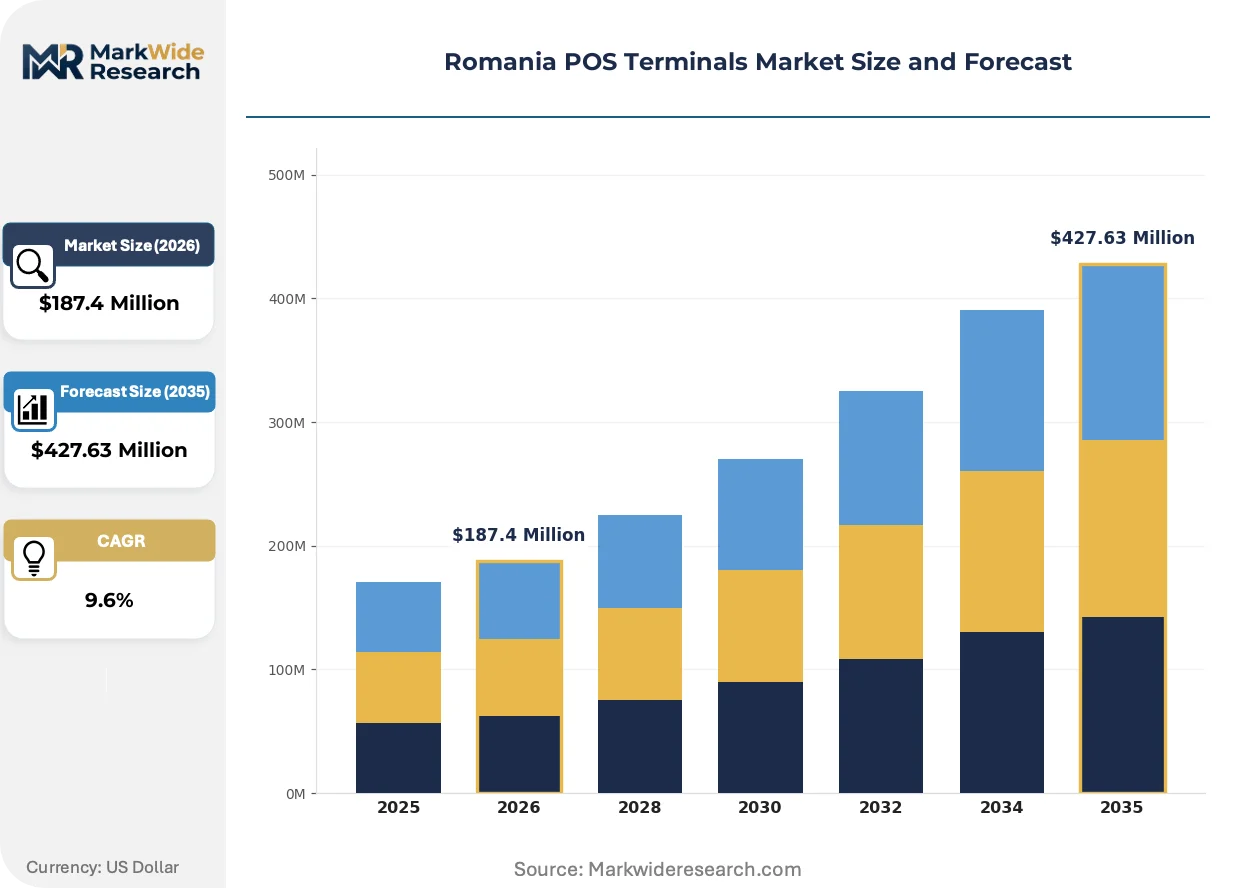
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Terminals, Mobile Terminals, Cloud-Based Terminals, Multilane Terminals Customer Type: Retail Stores, Restaurants, Hospitality, E-commerce Technology: Contactless Payment, EMV, Magnetic Stripe, NFC Integration Level: Standalone, Integrated with ERP, Integrated with CRM, Wireless |
| Companies Covered | ING Bank Romania, OTP Bank, SIBS, myPOS, Mellon Romania, Ingenico, Rapyd, Global Payments Romania, Banca Transilvania, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania POS Terminals Market Evolving Landscape
Software-defined architectures are dissolving the boundary between payment hardware and merchant services, enabling vendors to bundle working capital, analytics, and loyalty programs into subscription offerings. This shift reconfigures how Romanian banks and fintechs compete for merchant relationships.
Cloud-native terminal operating systems are consolidating vendor control over the merchant software stack. These platforms enable remote firmware updates and feature deployment without hardware swaps. Romanian hospitality chains and franchise networks are adopting cloud terminals fastest, compressing the traditional five-year replacement cycle into three-year refresh windows as feature velocity accelerates.
Romanian fiscal law mandating electronic receipt transmission to ANAF is forcing hardware redesigns. Terminal vendors must integrate certified fiscal modules or forfeit market access. This regulatory compression most affects entry-level device manufacturers, who are exiting rather than absorbing compliance engineering costs, leaving the field to vendors with existing ANAF certification relationships.
Merchant acquisition is rotating toward bundled service contracts. Romanian retailers now expect terminals delivered with integrated accounting software, inventory tracking, and tax reporting automation. This expectation is most pronounced in Bucharest and Cluj-Napoca, where multi-location operators demand centralized dashboard control across dispersed terminal fleets.
Romania POS Terminals Market Segmentation
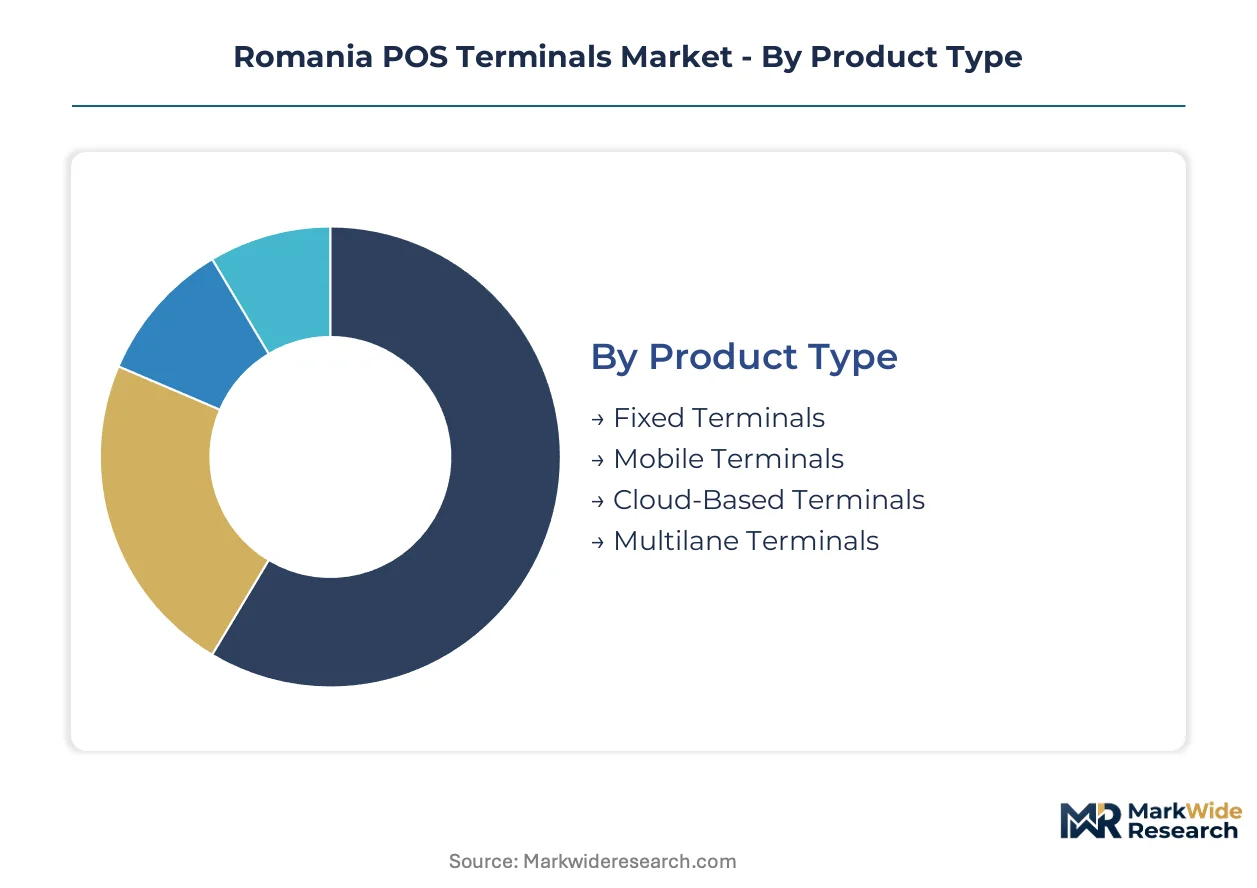
POS terminal segmentation in Romania reflects distinct replacement cycles driven by regulatory mandates and merchant operational requirements. Hardware refresh decisions hinge on ANAF fiscal compliance deadlines, payment network security protocols, and the shift toward software-defined service bundles.
Product Type:
Terminal replacement cycles accelerate where hardware obsolescence collides with National Bank of Romania certification requirements.
- Fixed Terminals:Stationary countertop devices with ethernet connectivity and integrated fiscal modules anchor supermarket and hypermarket checkout lanes. Bucharest-based retail chains prioritize these units for high-volume transaction environments where reliability and ANAF-compliant receipt transmission are non-negotiable.
- Mobile Terminals:Battery-powered units with cellular or Wi-Fi connectivity enable untethered payment capture. Food delivery aggregators and dark kitchen operators across Cluj-Napoca deploy these for curbside transactions, compressing refresh cycles as firmware updates outpace hardware durability.
- Cloud-Based Terminals:Thin-client devices running operating systems hosted on vendor infrastructure, enabling remote feature deployment without hardware swaps.
- Multilane Terminals:High-throughput systems designed for retail environments with multiple simultaneous checkout points and centralized transaction management.
Fixed terminals sit at the top of the volume ranking, with mobile terminals climbing the fastest.
Customer Type:
Merchant scale and transaction complexity dictate integration requirements and terminal refresh urgency across Romanian commercial sectors.
- Retail Stores:Brick-and-mortar merchants ranging from independent shops to national chains require EMV-compliant devices with inventory synchronization. Franchise networks in Transylvania's secondary cities drive clustered procurement decisions as corporate mandates override individual merchant preferences.
- Restaurants:Table-service and quick-service venues demand portable payment devices with tip functionality and split-check capabilities. Bucharest's dense hospitality corridor generates concentrated demand for terminals integrating with kitchen display systems and reservation platforms.
- Hospitality:Hotels and accommodation providers need property management system integration for room charges and incidentals.
- E-commerce:Online merchants require virtual terminal capabilities and multi-currency settlement for cross-border transactions.
Retail stores command the largest installed base, though restaurants show the steepest expansion trajectory as hospitality investment accelerates.
Technology:
Payment network liability shifts force terminal technology upgrades ahead of merchant-planned replacement schedules.
- Contactless Payment:NFC-enabled transaction acceptance with tap-to-pay functionality. Cluj-Napoca's urban hospitality venues prioritize these terminals to reduce queue friction, with transaction speed becoming a competitive differentiator in high-footfall districts.
- EMV:Chip-and-PIN authentication protocols mandated by card network liability rules. The National Bank of Romania's security certification requirements make EMV compliance a gating factor for market access, not merely a feature preference.
- Magnetic Stripe:Legacy swipe-based card reading technology facing phased liability elimination.
- NFC:Near-field communication protocols enabling smartphone wallet and wearable payment acceptance.
EMV technology dominates current installations, while contactless payment gains share fastest as issuer preference shifts toward tap-first transaction routing.
Integration Level:
Terminal architecture decisions increasingly hinge on software ecosystem compatibility rather than hardware specifications alone.
- Standalone:Discrete payment devices operating independently from merchant business systems. Micro-merchants in rural Romanian counties favor these units for lower upfront cost, though ANAF fiscal module requirements narrow the viable supplier base.
- Integrated with ERP:Terminals connected to enterprise resource planning systems for automated accounting reconciliation. Multi-location retail operators in Bucharest demand this integration to centralize tax reporting across dispersed terminal fleets.
- Integrated with CRM:Payment systems linked to customer relationship management platforms for loyalty program enrollment and purchase history tracking.
- Wireless:Connectivity-agnostic terminals operating across cellular, Wi-Fi, and Bluetooth protocols.
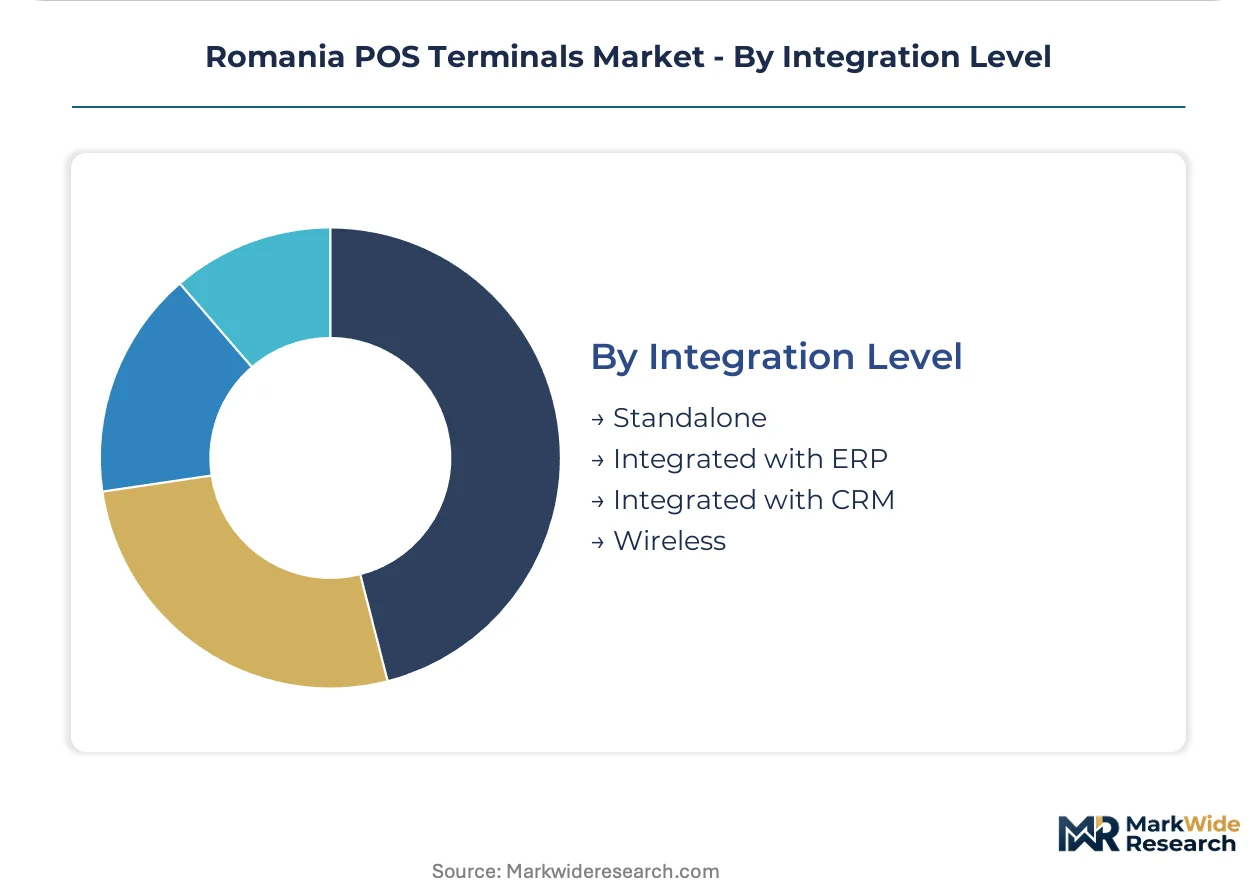
Standalone configurations retain the largest installed base, with ERP-integrated terminals expanding most quickly as merchant sophistication increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Romania outpaces neighboring Bulgaria in terminal density per merchant, yet trails Poland where EU structural funds accelerated contactless infrastructure deployment. The National Bank of Romania's regulatory pressure exceeds that of Hungary's central bank, creating steeper compliance curves for cross-border operators.
Bucharest-Ilfov
Franchise networks and hospitality groups drive terminal refresh cycles in the capital region. ANAF's fiscal module mandates hit hardest here due to merchant concentration and audit intensity. Băneasa and Pipera business districts host dense clusters of cloud-terminal deployments for multi-location retail operators.
Cluj-Napoca
Transylvania's tech hub generates demand for NFC-enabled hospitality terminals. Banca Transilvania anchors its merchant banking strategy in this urban core. The city's university-driven food delivery ecosystem compresses mobile terminal replacement cycles below the national average.
Timișoara
Cross-border trade with Hungary and Serbia creates multi-currency settlement demand. Western Romania's manufacturing base sustains integrated ERP-terminal procurement for industrial supply chains. The city's logistics parks require ruggedized mobile units for freight payment capture.
Brașov-Sibiu Corridor
Seasonal tourism and festival circuits create underpenetrated pop-up vendor opportunities. Rural micro-merchants in surrounding counties face ANAF module cost barriers that delay compliance. Sibiu's heritage retail district drives aesthetic-focused terminal design preferences.
Constanța
Black Sea port operations and maritime tourism generate specialized maritime-terminal requirements. The city's casino and hospitality sector demands high-throughput multilane systems. Summer seasonal spikes strain terminal network capacity, favoring cloud-based elasticity.
Romania POS Terminals Market Competitive Landscape
Top-tier vendors anchor acquiring-bank partnerships, while fintech challengers compete on settlement velocity and software bundling. The market structures around three archetypes: incumbent banks with merchant banking divisions, pure-play fintechs with cross-border capabilities, and hardware-software integrators with ANAF certification relationships. Consolidation pressure intensifies as EMV certification timelines and fiscal module compliance costs squeeze subscale operators. Strategic moves center on SaaS revenue conversion and working capital product bundling.
Within the bank-led tier, ING Bank Romania and Banca Transilvania exemplify the merchant-banking bundling archetype, anchoring terminal subscriptions in broader financial service relationships. Among fintech specialists, myPOS occupies a position defined by cross-border settlement speed for e-commerce merchants. SIBS represents the infrastructure-utility archetype, sitting within the payment processing layer that other vendors depend upon for transaction routing. These three patterns—bank bundling, fintech velocity, and infrastructure anchoring—capture the competitive geometry of the Romanian market.
| Leading Market Players |
|---|
| ING Bank Romania |
| OTP Bank |
| SIBS |
| myPOS |
| Mellon Romania |
| Ingenico |
| Rapyd |
| Global Payments Romania |
| Banca Transilvania |
| Others |
Value Network & Pricing Analysis
Bank-led merchant acquisition networks concentrate pricing power among vertically integrated financial institutions, compressing margins for independent hardware vendors while elevating subscription-based SaaS bundles as the dominant commercial model. This ownership pattern tightens pricing discipline across Bucharest and Cluj-Napoca, where bundled terminal-plus-working-capital offerings reset customer willingness-to-pay thresholds.
Pricing Analysis
Capacity additions in Shenzhen and Taipei are reshaping price floors for entry-level terminal hardware, forcing Romanian distributors to absorb margin compression or exit the micro-merchant segment. Three-tier pricing structure across premium, standard, and economy levels prevails, with ANAF fiscal module certification and EMV security tier serving as the primary differentiation drivers. Pricing pressure stems from fintech challengers offering zero-hardware-cost subscription models. Micro-merchants in rural Transylvania exhibit highest price sensitivity, while multi-location hospitality groups in Bucharest prioritize feature velocity over unit economics.
Supply Chain Analysis
Engineering talent scarcity in Dongguan and Shenzhen assembly corridors is extending component lead times for fiscal module integration, compelling terminal vendors to front-load inventory commitments. Hardware supply concentrates in China, Taiwan, and Vietnam, with NFC antenna arrays and secure chipsets drawing from semiconductor foundries in Hsinchu and Shanghai. Single-source vulnerability around ANAF-certified fiscal module suppliers poses structural risk. Distribution runs through bank-led merchant acquisition channels and direct fintech platforms, bypassing traditional electronics wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Romania's POS terminal market represents a late-cycle quality story where merchant procurement criteria are shifting toward cloud-native architectures and integrated software stacks, rewarding vendors with certified fiscal module relationships and recurring revenue models.
For Market Incumbents: Extend ANAF certification moats by accelerating firmware development cycles and embedding inventory management modules that deepen merchant switching costs. Consolidate position through selective acquisition of cloud-terminal specialists before EMV certification queues lengthen further. Vertical integration into fiscal module engineering reduces regulatory dependency risk. For New Entrants and Emerging Players: Dark kitchen operators and festival circuit vendors in Brașov-Sibiu corridor offer the most penetrable white-space targets, as these segments remain underserved by incumbent bank channels. Target pop-up merchant ecosystems with ruggedized mobile terminals featuring instant settlement and minimal onboarding friction. Partner with food delivery aggregators as embedded distribution channels. For Investors and Strategic Acquirers: Merchant banking divisions with existing SME lending books are the most active acquirer in this space, seeking terminal platforms to anchor working capital cross-sell. Five-to-ten-year viability hinges on SaaS revenue conversion rates and merchant retention metrics. Monitor National Bank of Romania certification queue lengths as early inflection indicator for vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fiscal Module Certification Investment | ANAF compliance relationships determine market access eligibility for terminal vendors. |
| Cloud-Native Platform Migration | Software-defined architectures enable remote feature deployment and subscription revenue conversion. |
| Cross-Border Settlement Capability | Multi-currency instant settlement addresses Romanian e-commerce merchant expansion into EU markets. |
| Merchant Banking Partnership | Terminal distribution through Banca Transilvania and ING Bank Romania accelerates customer acquisition. |
| Mobile Terminal Ruggedization | Battery durability and cellular connectivity meet dark kitchen and logistics park operational requirements. |
Research Methodology
Coverage spans Bucharest-Ilfov, Cluj-Napoca, Timișoara, and Brașov-Sibiu corridor, with primary inputs from each region combined with secondary validation. Interviews with merchant acquisition executives at Romanian banks, fintech product managers, ANAF compliance officers, hospitality procurement directors, and retail franchise operators informed demand-side assumptions. Secondary sources include National Bank of Romania payment system reports, ANAF fiscal certification databases, EU PSD2 implementation guidance, and customs import records for terminal hardware. Bottom-up merchant penetration estimates triangulate against top-down transaction volume projections.
Rate-of-change decomposition separates hardware replacement cycles from software subscription conversion velocity across the projection horizon. Segmentation dimensions modeled include terminal product type, customer vertical, payment technology tier, and integration level complexity. CAGRs derive from regression analysis against electronic payment adoption curves and regulatory deadline clustering. Forecast inputs incorporate EMV certification queue dynamics and ANAF fiscal module compliance timelines.
Revisions become necessary when National Bank of Romania extends security certification timelines, ANAF modifies fiscal transmission protocols, or EU payment directives alter strong authentication requirements. Forecasts reflect assumptions about merchant onboarding rates and hardware refresh elasticity. Material deviation in regulatory implementation schedules or fintech subsidy intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Wearable Payments Market
Payments
Global Digital Wallets Market
Payments
Germany Payments Market
Payments
Global Accounts Payable Automation Market
Payments
UAE POS Terminal Market
Payments
Saudi Arabia Mobile Payments Market
Payments
Payment Security Market
Payments
Global Payment Monitoring Market
Payments
Canada Payments Market
Payments
Finland Payments Market
Payments
United Kingdom Mobile Payments Market
Payments
QR Codes Payment Market
Payments
Smart Home Payments Market
Payments
Finland POS Terminals Market
Payments
Portugal Mobile Payments Market
Payments
Asia Pacific POS Terminal Market