
 Virtual Workspace Solutions Market | 2026-2036
Virtual Workspace Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Workspace Solutions Market Analytics
Healthcare delivery is decoupling from physical infrastructure, pulling virtual workspace demand toward clinical environments with strict data residency requirements. Microsoft Corporation leverages its Azure stack and Teams integration to anchor healthcare deployments with HIPAA-aligned compliance frameworks. VMware, Inc. competes through specialized virtualization layers that sustain workload portability across on-premises and sovereign cloud instances.
Virtual workspace solutions encompass software-defined environments that abstract compute, storage, and application layers from endpoint hardware, typically delivering sub-50ms latency for interactive sessions through protocol optimization and GPU passthrough architectures. Their primary commercial purpose centers on enabling secure, policy-enforced access to enterprise resources from distributed locations without data residing on local devices. Cloud-based deployment is capturing the fastest expansion as enterprises exit capital-intensive data center commitments, while hybrid architectures retain the deepest margin pools where consulting and custom integration services attach. AI-powered solutions within the technology dimension are attracting disproportionate R&D allocation as vendors embed generative assistants directly into workspace orchestration layers.
The EU AI Act and GDPR shape product architecture by mandating algorithmic transparency and data localization, forcing providers to segment inference workloads and audit trails by jurisdiction. The SEC's cybersecurity disclosure rules and HIPAA enforcement by the Office for Civil Rights further tighten liability for vendors serving regulated industries. Stakeholders must weigh sovereign cloud certification costs against the pricing power these credentials confer in procurement cycles for defense, healthcare, and financial services buyers.
Market Dynamics
Hybrid workspace mandates from Germany's Mittelstand sector are pulling vendor roadmaps toward sovereign cloud architectures, compressing deployment timelines while fragmenting procurement across compliance jurisdictions.
Growth Catalysts
- GDPR data localization requirements:Healthcare providers in the EU must maintain patient records within jurisdictional boundaries, forcing infrastructure investment in regional data centers.
- Telemedicine workload expansion:Clinical environments now require GPU-accelerated virtual desktops for diagnostic imaging, pulling specialized virtualization layers into hospital IT stacks.
- Germany's industrial digitization push:Mittelstand manufacturers are consolidating legacy terminal environments into centralized workspace platforms to reduce endpoint management overhead.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in data center graphics silicon creates procurement bottlenecks for GPU passthrough architectures essential to clinical workloads.
- EU AI Act compliance costs:Algorithmic transparency mandates require expensive audit infrastructure for AI-powered workspace orchestration features.
- On-premises data center sunk costs:Enterprises with recent capital-intensive infrastructure investments face write-down friction when migrating to cloud-based deployments.
Strategic Opportunities
- France's healthcare sovereignty initiative:ANSM and CNIL are accelerating certification programs for clinical-grade virtual workspace platforms, creating first-mover advantages for compliant vendors.
- Edge computing convergence with 5G:Low-latency connectivity is enabling sub-20ms virtual desktop experiences for field-based diagnostics in rural clinical settings.
- Subscription-based channel models:Managed service providers are bundling workspace platforms with compliance consulting, capturing recurring revenue from regulated industries.
Industry Challenges
- Sovereign cloud certification timelines:EMA and national health regulators require 18-24 month validation cycles for clinical workspace deployments.
- Legacy EMR integration complexity:Hospital information systems built on 1990s architectures resist API-based connectivity with modern workspace orchestration layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Workspace Solutions Market |
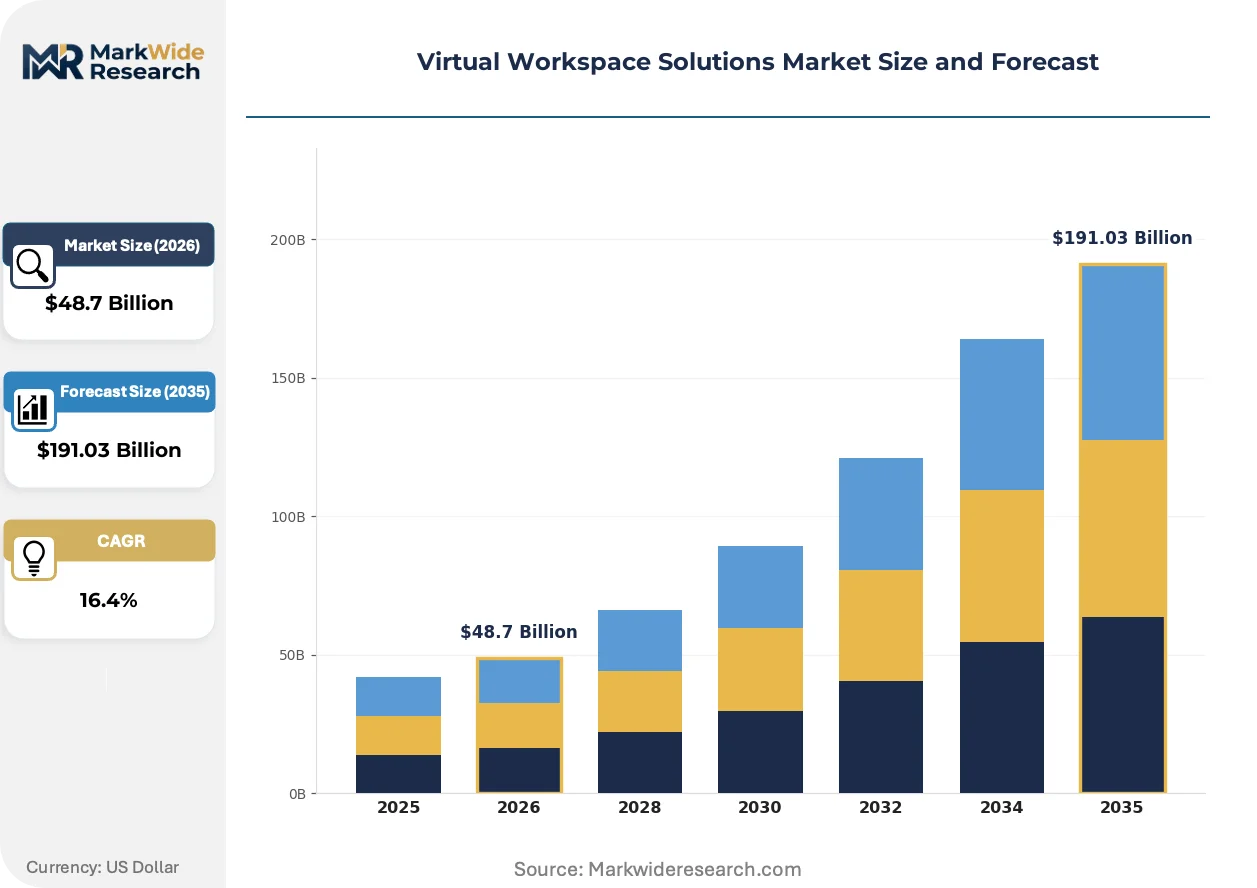
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Remote End User: Small Businesses, Large Enterprises, Educational Institutions, Freelancers Technology: Virtual Reality, Augmented Reality, AI-Powered Solutions, Collaborative Platforms Service Type: Managed Services, Consulting, Support Services, Custom Development |
| Companies Covered | Microsoft Corporation, Amazon Web Services, VMware, Inc., Citrix Systems, Cisco Systems Inc., Dell Inc., Google LLC, Ivanti Software, Atlantis Computing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Workspace Solutions Market Evolving Landscape
Generative AI integration is compressing the boundary between workspace infrastructure and intelligent assistance, while regulatory segmentation forces architectural divergence across compliance zones.
GPU passthrough virtualization is rewriting how clinical workloads access graphics silicon. Radiology departments in German university hospitals are deploying these architectures at scale, replacing physical workstations. This capability is rewriting procurement patterns by eliminating per-seat hardware refresh cycles.
The EU AI Act's risk classification framework is forcing algorithmic audit trails into workspace orchestration layers. Vendors must now document inference logic for AI-powered session optimization. Healthcare deployments across France, Germany, and the Netherlands face the strictest compliance burdens, driving demand for explainable AI modules.
Subscription consumption models are displacing perpetual licensing in enterprise procurement. German automotive suppliers and French pharmaceutical groups now prioritize operational expenditure structures. This shift is most visible in multi-site manufacturing environments where workspace demand fluctuates with production schedules.
Virtual Workspace Solutions Market Segmentation
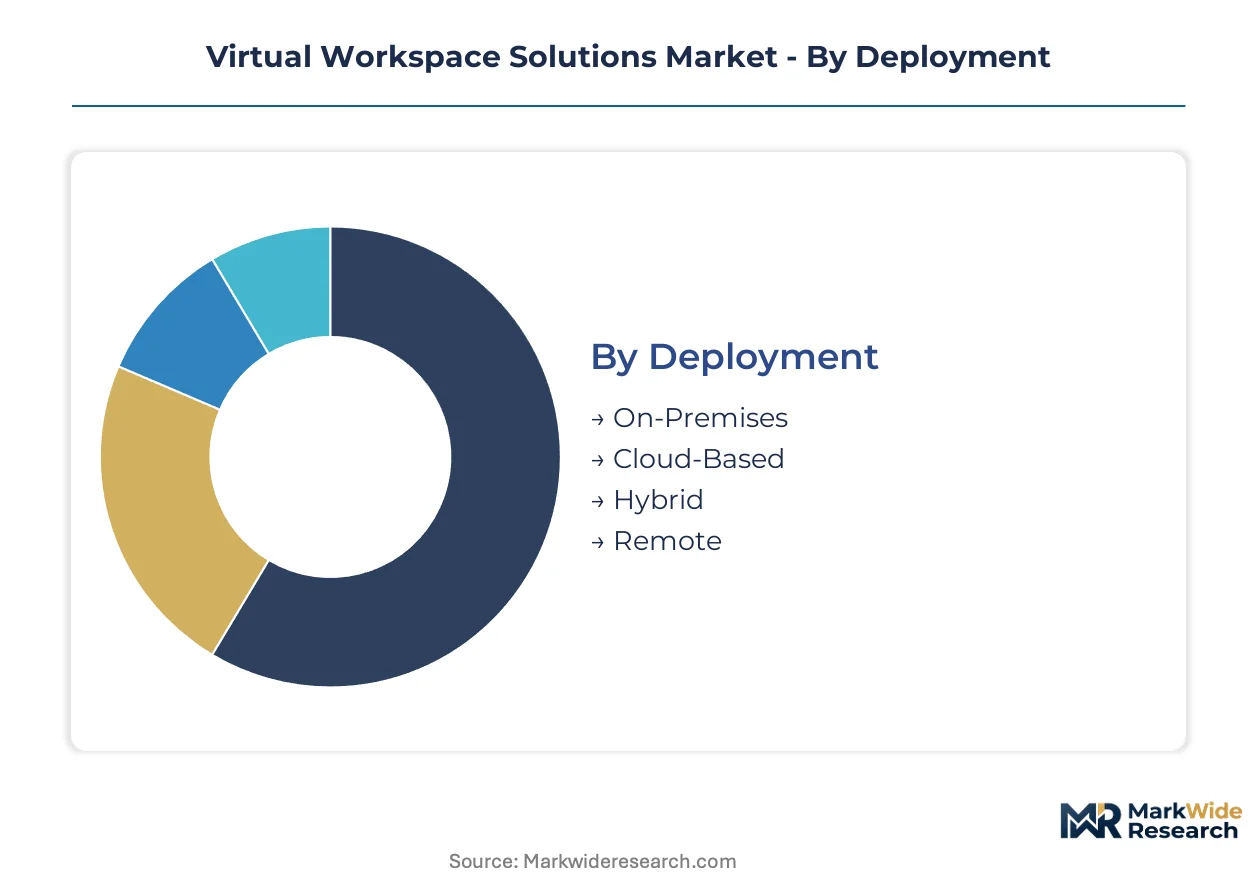
Segmentation in virtual workspace solutions reveals divergent margin structures and compliance requirements across deployment architectures and buyer types. Procurement patterns split sharply between regulated industries demanding sovereign infrastructure and distributed workforces prioritizing latency and accessibility.
Deployment:
Volume concentrates in cloud-based configurations while premium pricing attaches to hybrid sovereignty-certified deployments.
- On-Premises:Full-stack infrastructure ownership with dedicated hardware stacks for data residency enforcement. German healthcare networks and French defense contractors anchor demand here, driven by ANSM and CNIL certification requirements that disqualify shared cloud tenancy.
- Cloud-Based:Multi-tenant subscription delivery with elastic scaling and API-native orchestration. Mittelstand manufacturers across Bavaria and Baden-Württemberg are consolidating legacy terminal farms into these platforms, eliminating endpoint refresh cycles.
- Hybrid:Split workload architecture maintaining sensitive data on-premises while bursting compute to cloud. GDPR Article 44 transfer restrictions push financial services buyers toward this topology.
- Remote:Lightweight client access to centralized desktops with protocol-optimized streaming. Field diagnostic teams in rural clinical settings deploy these for sub-50ms imaging workstation access.
Mature deployment sits with on-premises. Newer deployment is concentrated in cloud-based.
End User:
Customer sophistication determines integration complexity and recurring services attachment.
- Large Enterprises:Multi-site workspace consolidation with EMR integration and custom compliance frameworks. German automotive suppliers and French pharmaceutical groups drive the steepest expansion trajectory through subscription procurement mandates.
- Small Businesses:Standardized SaaS consumption with minimal customization and rapid deployment. Cost sensitivity here limits vendor selection to pre-configured vertical templates.
- Educational Institutions:Semester-scaled licensing with lab-specific GPU access for engineering and medical curricula. Campus IT departments prioritize zero-trust session policies for student device populations.
- Freelancers:Individual subscription tiers with collaborative platform access and basic security postures. Demand clusters in creative and software development verticals.
Integration depth peaks with large enterprises. Deployment velocity concentrates among freelancers.
Technology:
Architecture choices determine latency profiles and capital intensity for graphics workloads.
- AI-Powered Solutions:Generative assistants embedded in workspace orchestration with inference workload segmentation. EU AI Act risk classification mandates algorithmic audit trails, driving explainable AI module procurement in France, Germany, and the Netherlands.
- Collaborative Platforms:Real-time document co-editing and persistent virtual spaces with policy-enforced data residency. Microsoft Teams-anchored deployments dominate healthcare procurement cycles.
- Virtual Reality:Immersive 3D environments with headset-tethered or standalone rendering. Surgical training and industrial design applications sustain niche adoption despite hardware cost barriers.
- Augmented Reality:Overlay graphics on physical environments for field service and remote assistance. 5G edge convergence is enabling sub-20ms experiences for diagnostic support in rural settings.
Production maturity sits with collaborative platforms. R&D allocation concentrates in AI-powered solutions.
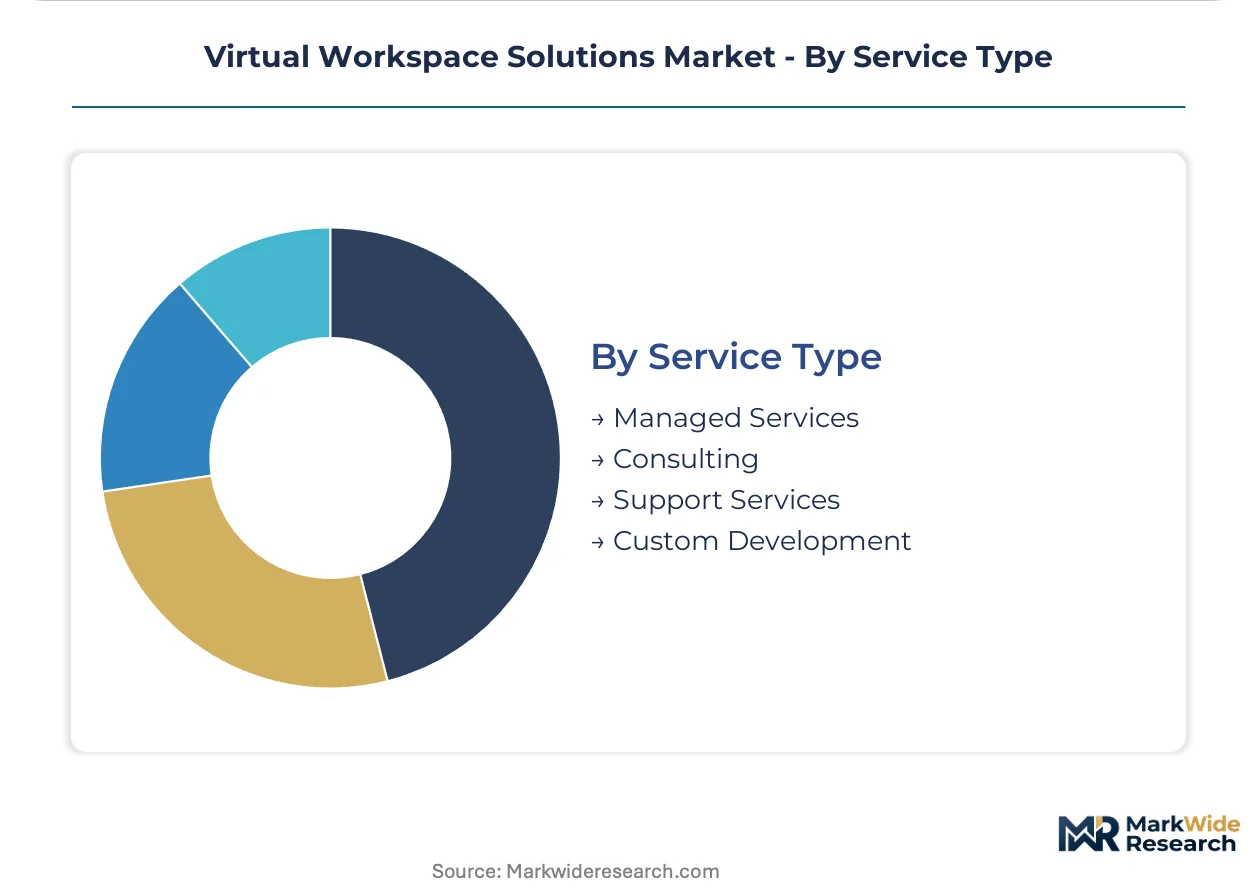
Service Type:
Revenue mix shifts toward recurring managed services as buyers exit capital-intensive ownership models.
- Managed Services:End-to-end workspace operation including patching, scaling, and compliance monitoring. German automotive suppliers now mandate operational expenditure structures with MSP-bundled sovereignty consulting.
- Consulting:Migration planning, compliance gap analysis, and custom integration architecture. EMA and national health regulator validation cycles create 18-24 month engagement pipelines.
- Support Services:Break-fix, tiered helpdesk, and user onboarding with SLAs tied to clinical workflow continuity.
- Custom Development:Legacy EMR API bridges and specialized virtualization layers for diagnostic imaging workloads.
Margin depth sits with managed services. Project volatility concentrates in custom development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virtual workspace infrastructure concentrates in North American cloud hyperscaler regions while procurement demand clusters in European regulated industries. Consumption patterns diverge sharply between sovereign-certified deployments and elastic multi-tenant consumption.
United States
Healthcare networks and defense contractors drive sovereign cloud demand with strict data residency requirements. HIPAA enforcement by the Office for Civil Rights and SEC cybersecurity disclosure rules tighten vendor liability frameworks. The Washington DC-Baltimore corridor anchors federal workspace deployments with FedRAMP-certified infrastructure.
Germany
Mittelstand manufacturers consolidate legacy terminal environments into centralized platforms for endpoint management reduction. GDPR Article 44 transfer restrictions and the EU AI Act algorithmic transparency mandates shape procurement specifications. Bavarian automotive suppliers and Baden-Württemberg industrial clusters lead hybrid workspace adoption with subscription-based operational expenditure models.
France
ANSM and CNIL accelerate certification programs for clinical-grade virtual workspace platforms in hospital networks. The EU AI Act risk classification framework imposes strictest compliance burdens on healthcare deployments. Île-de-France pharmaceutical groups and Auvergne-Rhône-Alpes medical device manufacturers prioritize explainable AI modules in procurement cycles.
United Kingdom
NHS trusts expand virtual desktop infrastructure for telemedicine and remote diagnostic imaging workloads. Post-Brexit data protection frameworks maintain GDPR-equivalent localization requirements for patient records. London financial services firms and Cambridge healthcare technology clusters drive demand for hybrid architectures with jurisdictional workload segmentation.
Netherlands
EMA validation requirements for clinical workspace deployments create extended certification timelines for vendors. Dutch hospital information systems integrate GPU-accelerated virtualization layers for radiology department workstation replacement. The Randstad metropolitan region concentrates healthcare IT procurement with strict sovereign cloud tenancy requirements.
Virtual Workspace Solutions Market Competitive Landscape
Top-tier vendors anchor the cloud-native segment, while specialized virtualization providers occupy the hybrid sovereignty tier. The market structure splits between hyperscaler-integrated platforms and independent orchestration specialists. Three archetypes dominate: cloud-native workspace suites, legacy virtualization incumbents with sovereign certifications, and managed service providers bundling compliance consulting. Competitive moves concentrate on strategic partnerships for regulatory certification acceleration and portfolio diversification into AI-powered session optimization.
Within the cloud-native tier, Microsoft Corporation and Amazon Web Services exemplify hyperscaler-integrated deployment models with healthcare compliance frameworks. VMware, Inc. occupies a position among legacy virtualization specialists competing through workload portability across on-premises and sovereign cloud instances. Citrix Systems represents the independent orchestration archetype with established clinical workload credentials.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| VMware, Inc. |
| Citrix Systems |
| Cisco Systems Inc. |
| Dell Inc. |
| Google LLC |
| Ivanti Software |
| Atlantis Computing |
| Others |
Value Network & Pricing Analysis
Captive sovereign cloud infrastructure anchors both supply positioning and pricing power for vendors serving EU healthcare and defense buyers. German Mittelstand manufacturers and French hospital networks demand jurisdictional data residency, forcing providers to build or lease region-locked capacity that inflates fixed costs and supports premium subscription tiers.
Pricing Analysis
Short lead times for GDPR-certified deployments command substantial premiums over standard cloud instances. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification depth, with ANSM-validated clinical deployments sitting at the apex. Cost compression in mid-market SaaS tiers is intensifying because hyperscaler competition erodes per-seat margins. Small businesses exhibit highest price sensitivity, while German automotive suppliers prioritize operational expenditure predictability over unit cost minimization.
Supply Chain Analysis
France's healthcare sovereignty initiative and Germany's IT security certification requirements are reshaping sourcing patterns toward domestic data center operators. GPU silicon concentrates in Taiwan and South Korea, while sovereign cloud infrastructure builds cluster in Germany, France, and the Netherlands. Supply chain risk centers on NVIDIA's data center graphics dominance creating single-source vulnerability for clinical virtualization workloads. Distribution runs through hyperscaler marketplaces and managed service provider channels with compliance consulting bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
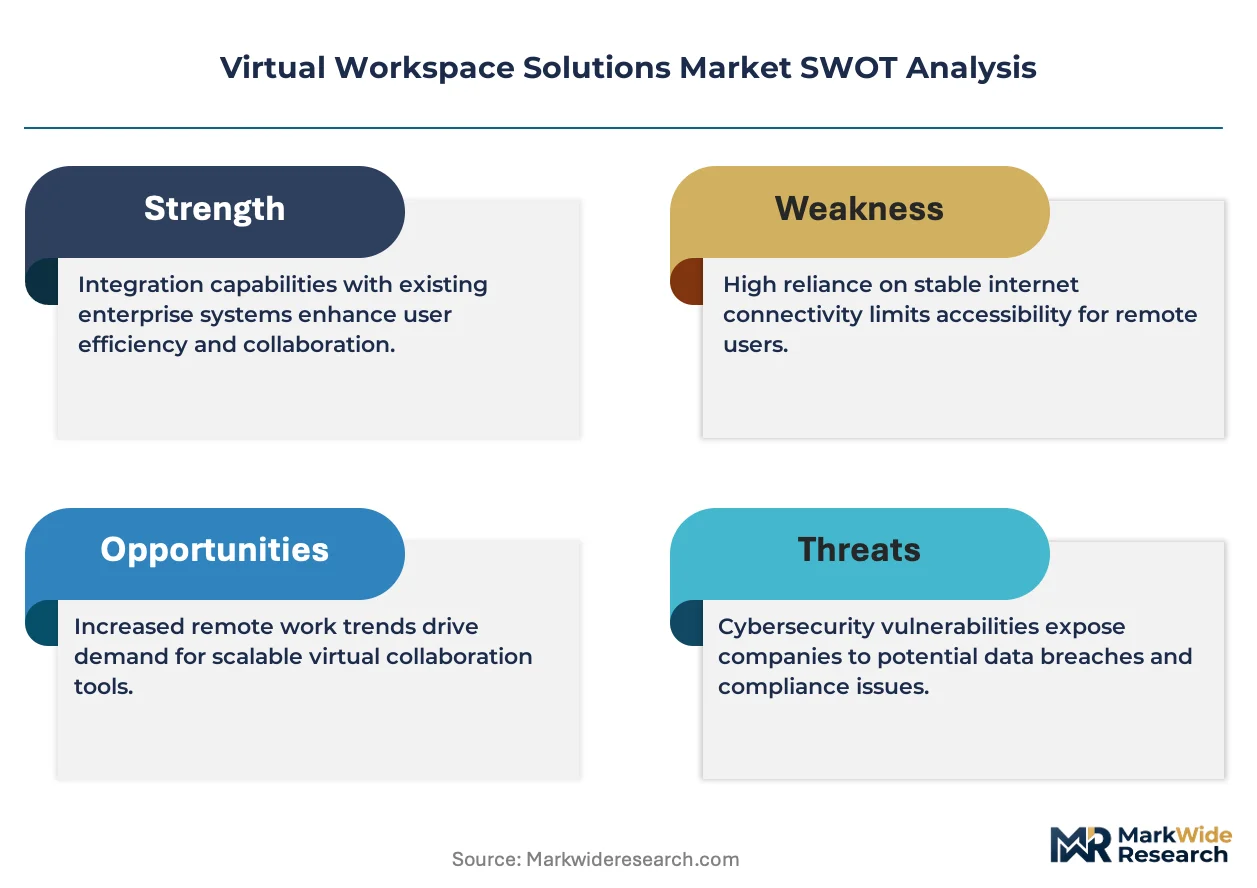
EU AI Act compliance costs and sovereign certification timelines are forcing consolidation among sub-scale virtualization vendors. Market incumbents with existing EMA and national health regulator validations will absorb distressed competitors unable to sustain 18-24 month audit cycles.
For Market Incumbents: Deepen vertical integration into GPU-accelerated virtualization layers to escape NVIDIA supply bottlenecks for clinical imaging workloads. Expand sovereign cloud capacity in Bavaria and Île-de-France to capture Mittelstand and pharmaceutical procurement cycles. Lock in channel control through exclusive managed service provider partnerships bundling compliance consulting.
For New Entrants and Emerging Players: Edge-native workspace orchestration with 5G-optimized protocol stacks offers a technology-first wedge into rural clinical diagnostics underserved by centralized cloud architectures. Target French university hospital networks awaiting ANSM certification slots with lightweight remote desktop solutions requiring minimal validation overhead. Pursue white-label OEM arrangements with German industrial automation vendors seeking embedded workspace capabilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler tuck-in acquisitions seeking sovereign cloud credentials and healthcare compliance expertise. Long-term viability favors vendors with established EMA validation pipelines and recurring managed services revenue exceeding perpetual license exposure. Watch for EU AI Act enforcement actions against non-compliant workspace orchestration features as an inflection signal accelerating distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EMA validation unlocks German and French hospital procurement cycles with 18-24 month competitive moats. |
| GPU Virtualization Layer Development | Specialized passthrough architectures eliminate per-seat workstation hardware for radiology departments. |
| Managed Service Provider Partnership | Compliance consulting bundles convert capital expenditure buyers to recurring operational expenditure structures. |
| Edge Computing Convergence | 5G-optimized protocols enable sub-20ms virtual desktop experiences for field-based clinical diagnostics. |
| Explainable AI Module Integration | Algorithmic audit trails satisfy EU AI Act risk classification mandates for healthcare deployments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital IT directors, biomedical engineers, GPO contracts managers, and sovereign cloud architects combined with secondary validation from EMA submission databases, ANSM certification registries, and hyperscaler capex disclosures. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Data-stream reconciliation across deployment architecture, end-user scale, and technology layer dimensions produced consistent trajectory outputs over the projection horizon. Segmentation modeling captured cloud-based, hybrid, and on-premises configurations alongside large enterprise, small business, and educational institution buyer archetypes. CAGRs derived from elasticity-adjusted adoption curves incorporating GDPR enforcement intensity and EU AI Act implementation pacing.
Several conditions sit outside the modeled scope, including speculative regulatory delays, geopolitical disruption to GPU supply chains, and unanticipated hyperscaler pricing warfare. Forecasts reflect documented assumptions about sovereign certification timeline stability and Mittelstand digitization budget continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
United Kingdom ICT Market
Digital Solutions
Digital Library Software Market
Digital Solutions
IT Asset Management Market
Digital Solutions
Product Life Cycle Management (PLM) Market
Digital Solutions
Supplier Contract Management Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Digital Fitness Apps Market
Digital Solutions
Messaging Platform Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
Thin Client Market