
 Virtual Reality (VR) Market | 2026-2036
Virtual Reality (VR) Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality (VR) Market Analytics
The EU Green Deal is decoupling hardware manufacturing from carbon-intensive supply chains, pressuring VR headset makers to redesign sourcing and assembly footprints. Meta leverages its captive silicon and display pipeline to control cost structures across standalone devices. Sony Group Corporation anchors premium console VR through exclusive content licensing and optical engineering depth. HTC Corporation specializes in enterprise-grade tethered systems for medical and industrial simulation buyers.
Virtual Reality denotes computer-generated immersive environments rendered through stereoscopic displays with sub-20ms motion-to-photon latency, tracking user position via inside-out cameras or external base stations to create persistent spatial presence for training, entertainment, or therapeutic intervention. Headsets capture the dominant revenue share as optical stack costs concentrate value upstream, while standalone VR is displacing PC-tethered configurations in education and field training where deployment flexibility outweighs raw compute. Services margin pools are deepening around custom enterprise content creation and ongoing fleet management for healthcare and defense clients.
FCC equipment authorization rules govern radio frequency emissions from wireless VR headsets in the United States, while the EU AI Act imposes conformity assessment burdens on biometric inference algorithms embedded in social VR platforms. The report identifies regulatory fragmentation across electromagnetic safety, data privacy, and AI governance as the primary compliance vector shaping market access timelines. Stakeholders must monitor divergence between FDA digital health pathways for therapeutic VR and EMA notified body expectations as reimbursement frameworks crystallize.
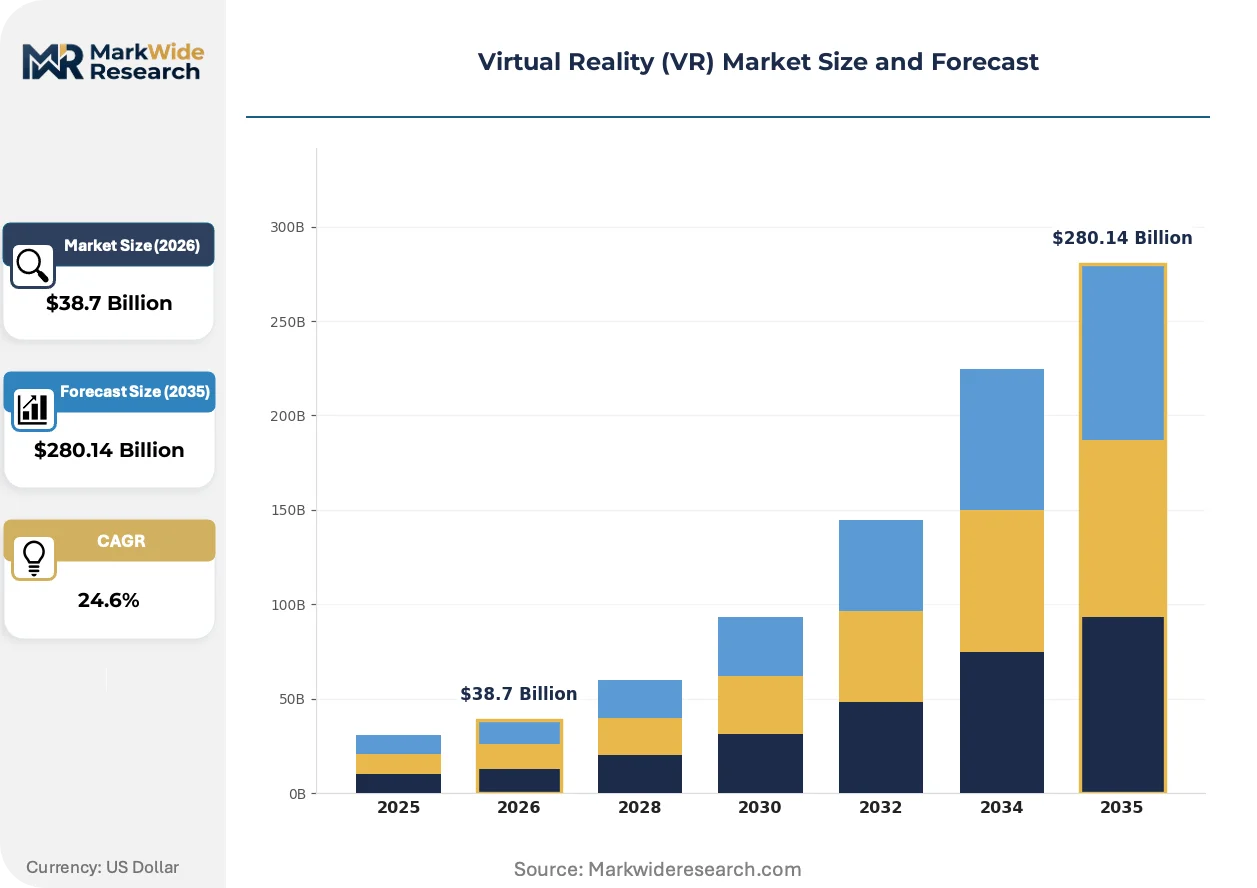
Market Dynamics
The VR market is compressing around standalone headset architectures as optical stack integration and captive silicon production rewrite cost structures for mass deployment.
Growth Catalysts
- FDA digital health pathways:Therapeutic VR applications for pain management and anxiety disorders are securing reimbursement codes, accelerating hospital procurement cycles for behavioral health departments.
- Defense simulation contracts:The United States Department of Defense is scaling synthetic training environments for pilot and vehicle crew certification, creating sustained demand for high-fidelity immersive systems.
- Inside-out tracking:Camera-based spatial positioning is eliminating external base station requirements, reducing installation friction for enterprise training deployments in logistics and manufacturing facilities.
Market Restraints
- Display panel supply concentration:High-resolution AMOLED and micro-OLED production concentrates in South Korea and Taiwan, creating input cost volatility for headset assemblers during demand surges.
- EU AI Act conformity assessments:Biometric inference algorithms in social VR platforms face mandatory third-party auditing, extending time-to-market for emotion-tracking features by 12-18 months.
- Motion-to-photon latency floors:Sub-20 millisecond rendering thresholds require dedicated compute architectures that resist cost reduction, limiting price accessibility for education and consumer segments.
Strategic Opportunities
- India's PLI scheme for electronics:Manufacturing incentives are attracting component assembly and testing operations, creating regional supply hubs to serve Middle East and Southeast Asian demand.
- Haptic feedback convergence:Integration of force-feedback gloves and full-body suits with visual immersion is opening surgical rehearsal and industrial maintenance training applications previously served by physical simulators.
- Cloud-rendered streaming:Edge computing infrastructure is enabling thin-client VR headsets that offload rendering to remote servers, reducing hardware BOM costs for K-12 education deployments.
Industry Challenges
- Spatial computing talent scarcity:Shortages of engineers with simultaneous expertise in computer vision, perceptual psychology, and real-time graphics are inflating R&D payrolls and slowing feature development cycles.
- Legacy system integration:Enterprise buyers require API compatibility with existing LMS, ERP, and patient record platforms, forcing vendors to maintain expensive middleware layers and certification documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality (VR) Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software, Accessories, Services End User: Gaming, Education, Healthcare, Training Technology: Mobile VR, PC VR, Console VR, Standalone VR Application: Entertainment, Simulation, Therapy, Design |
| Companies Covered | Meta, Sony Group Corporation, Apple Inc., Microsoft Corporation, HTC Corporation, Samsung Electronics Co., Ltd., ByteDance, Unity Technologies, DPVR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality (VR) Market Evolving Landscape
Pancake lens optics and local dimming micro-LEDs are redefining visual fidelity benchmarks while regulatory frameworks for biometric data reshape platform architecture requirements.
Standalone VR headsets with integrated Snapdragon XR processors are overtaking PC-tethered configurations in enterprise training budgets. Logistics operators and field service organizations are adopting wireless deployments for facility-scale instruction without cable management infrastructure. This shift is compressing the addressable market for high-end GPU vendors previously supplying rendering workstations.
The EU AI Act's risk classification system for biometric inference is forcing social VR platforms to reengineer emotion detection and gaze tracking pipelines. Developers must implement algorithmic transparency documentation and human oversight protocols before CE marking approval. Social platforms with avatar-based interaction are most affected, with several delaying European launches to restructure data processing architectures.
Subscription-based content licensing is displacing perpetual purchase models in healthcare and defense training programs. Hospital systems and military procurement offices are consolidating vendor relationships around multi-year service agreements with guaranteed content refresh cycles. This pattern is most visible in the United States, where enterprise buyers prioritize predictable operational expenditures over capital equipment ownership.
Virtual Reality (VR) Market Segmentation
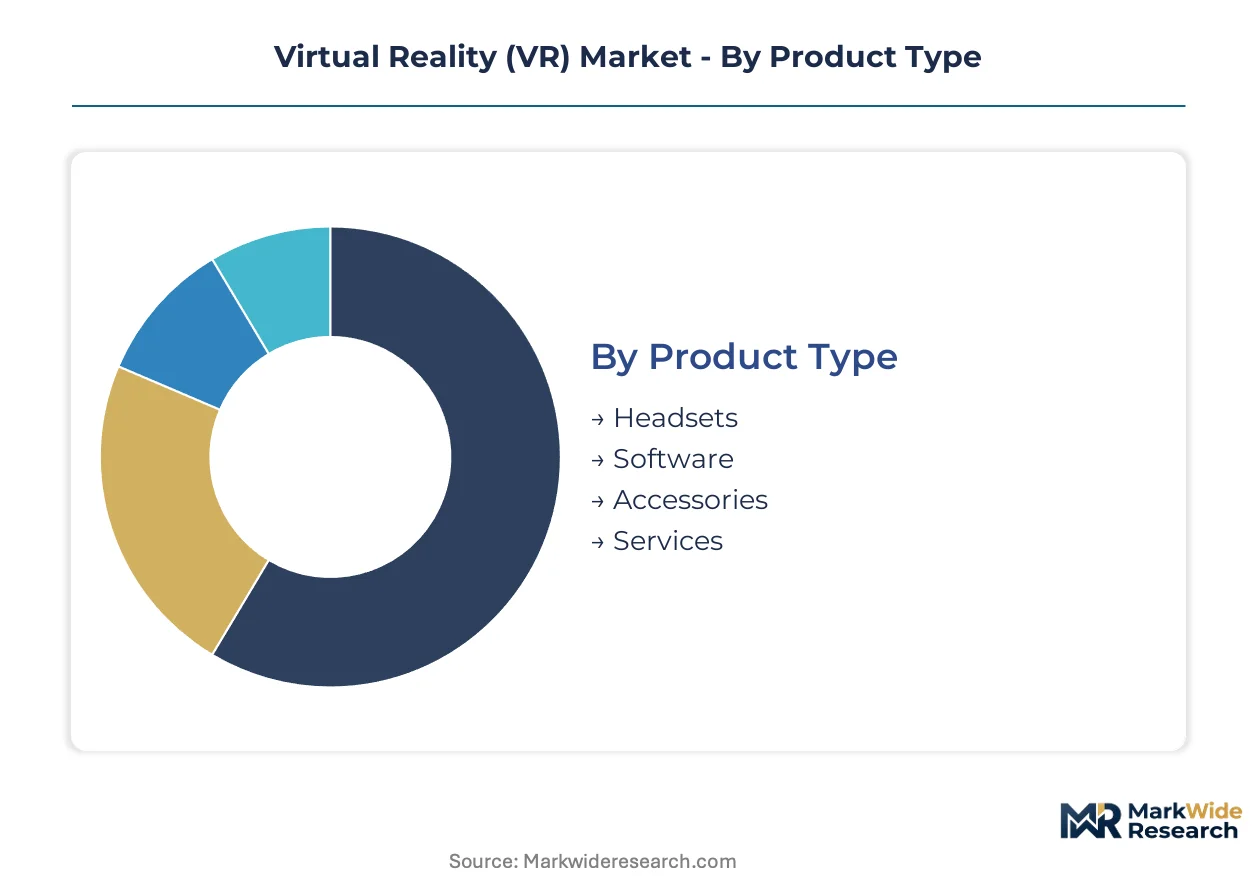
Segmentation in the VR market reveals how capital allocation, deployment constraints, and regulatory exposure concentrate value differently across hardware stacks, content formats, and buyer verticals. Understanding these divisions clarifies where procurement budgets flow and which technology trajectories face scaling friction.
Product Type:
Headset manufacturing demands the heaviest upfront capital, with optical stack integration and captive silicon fabrication requiring multi-billion-dollar fabrication commitments before volume shipment.
- Headsets:Stereoscopic display assemblies with sub-20ms motion-to-photon latency concentrate value upstream in AMOLED and micro-OLED supply chains. Hospital systems in the United States are accelerating procurement for surgical training and pain management applications as FDA digital health pathways mature.
- Services:Custom enterprise content creation and ongoing fleet management for healthcare and defense clients generate recurring revenue pools with deeper margins than hardware resale. Subscription-based licensing is displacing perpetual purchase models in military procurement offices prioritizing predictable operational expenditures.
- Software:Platform operating systems and development SDKs anchor ecosystem control.
- Accessories:Haptic gloves, force-feedback controllers, and full-body tracking suits extend immersion fidelity.
Headsets absorb the bulk of installed capacity; Services is expanding most quickly.
End User:
Buyer sophistication and procurement cycle length vary sharply across these verticals, with defense and healthcare requiring extended certification timelines that consumer segments bypass entirely.
- Healthcare:Therapeutic VR for anxiety disorders and surgical rehearsal demands FDA 510(k) clearance or EMA notified body assessment, extending time-to-deployment by 12-24 months. Reimbursement code availability in the United States is accelerating hospital procurement for behavioral health departments.
- Training:Enterprise and defense buyers require API compatibility with existing LMS and ERP platforms, forcing vendors to maintain expensive middleware certification layers. The United States Department of Defense is scaling synthetic training environments for pilot certification, creating sustained demand for high-fidelity immersive systems.
- Gaming:Consumer entertainment drives volume shipment but compresses price points.
- Education:K-12 and university deployments prioritize wireless standalone configurations for facility-scale instruction without cable management infrastructure.
Training commands the largest procurement budgets; Healthcare is climbing the fastest as reimbursement frameworks crystallize.
Technology:
Architectural trade-offs between rendering location, tracking methodology, and mobility determine deployment feasibility across enterprise and consumer contexts.
- Standalone VR:Integrated Snapdragon XR processors with inside-out camera tracking eliminate external base station requirements, reducing installation friction for logistics and manufacturing facility deployments. This architecture is displacing PC-tethered configurations in education and field training where deployment flexibility outweighs raw compute.
- PC VR:External GPU rendering delivers highest visual fidelity for simulation applications requiring photorealistic environments. Defense pilot training programs in the United States continue specifying tethered configurations for certification-grade fidelity thresholds.
- Mobile VR:Smartphone-dependent architectures leverage existing device penetration but sacrifice spatial tracking precision.
- Console VR:Premium optical engineering tied to exclusive content licensing anchors living-room entertainment positioning.
Standalone VR has captured majority shipment share; PC VR retains premium simulation contracts.
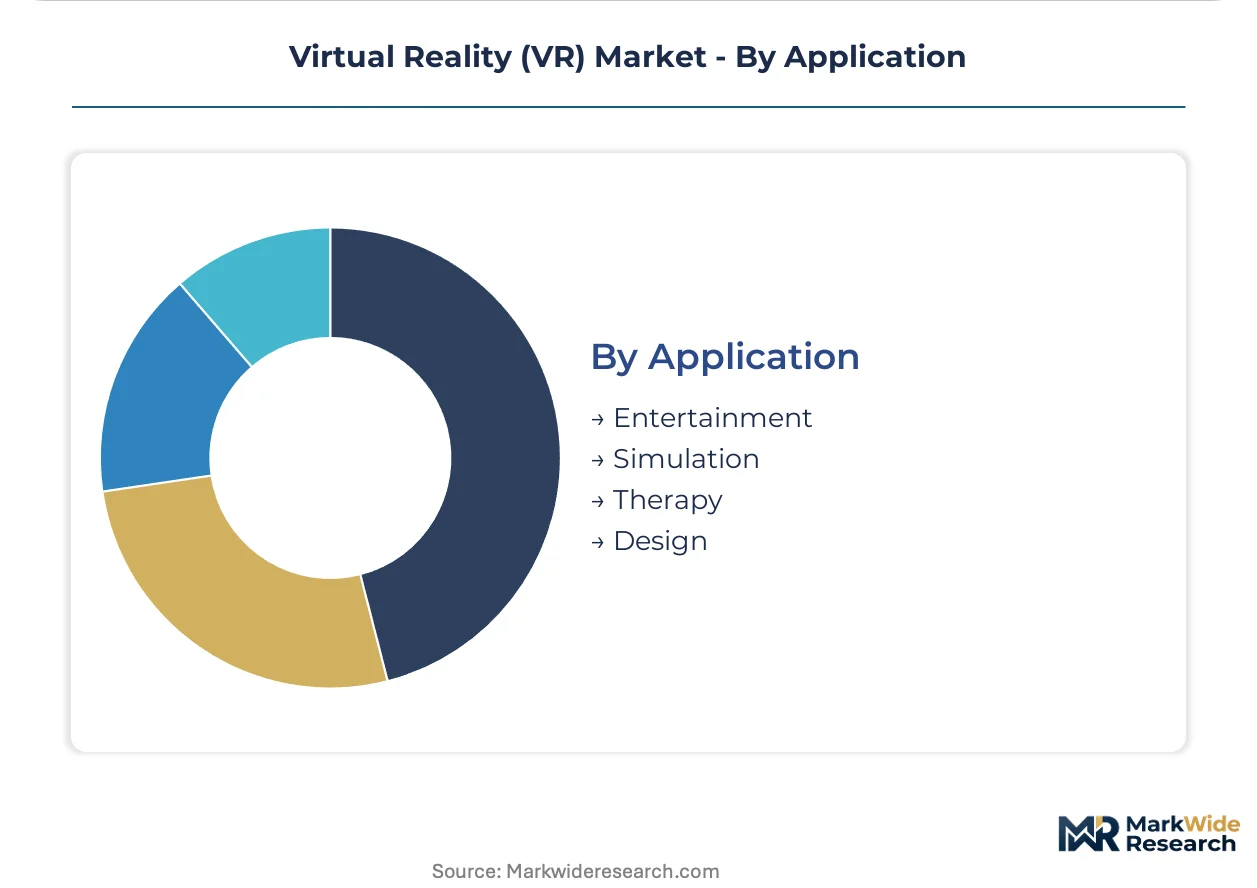
Application:
Functional use cases impose divergent latency, fidelity, and regulatory requirements that reshape hardware specification and content development priorities.
- Simulation:Military flight crew certification and industrial maintenance training demand sub-20ms motion-to-photon latency with force-feedback haptic integration. Cloud-rendered streaming via edge computing infrastructure is enabling thin-client deployments that reduce hardware BOM costs for scalable training programs.
- Therapy:Pain management and exposure therapy applications face EU AI Act conformity assessment burdens for biometric inference algorithms embedded in gaze tracking and emotion detection. Several social VR platforms have delayed European launches to restructure data processing architectures for algorithmic transparency documentation.
- Entertainment:Gaming and cinematic content prioritize visual immersion over physiological precision.
- Design:Architectural visualization and automotive prototyping require collaborative multi-user spatial environments.
Simulation dominates defense and industrial procurement; Therapy is gaining share fastest as reimbursement pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the global VR ecosystem through Meta's Reality Labs and a dense concentration of venture-backed spatial computing startups. The Bay Area's talent pipelines feed engineering teams across the industry, while defense contracts flow through nearby federal procurement channels.
United States
The Department of Defense scales synthetic training environments for pilot certification, creating sustained procurement demand for high-fidelity immersive systems. FDA digital health pathways for therapeutic VR accelerate hospital adoption in behavioral health departments. Austin and Seattle clusters specialize in enterprise training content and cloud-rendered streaming infrastructure for education deployments.
China
Domestic headset manufacturers leverage MIIT industrial policy support and GB standards compliance to serve education and industrial simulation buyers. The dual carbon goals pressure component suppliers to decarbonize fabrication processes. Shenzhen's electronics corridor concentrates optical stack assembly and Snapdragon XR integration for cost-optimized standalone devices.
Germany
Automotive manufacturers deploy VR for design visualization and assembly line training, with BMW and Volkswagen operating captive simulation facilities. The EU AI Act imposes conformity assessment burdens on biometric inference algorithms, extending time-to-market for emotion-tracking features. Munich and Stuttgart clusters anchor industrial VR engineering and precision optics development.
South Korea
Samsung Electronics and LG Display concentrate high-resolution AMOLED and micro-OLED production, creating input cost leverage for headset assemblers worldwide. MFDS regulates therapeutic VR devices for pain management applications in clinical settings. Seoul's Digital Media City hosts content studios specializing in K-12 education and corporate training simulations.
India
The PLI scheme for electronics manufacturing attracts component assembly and testing operations from multinational headset vendors. Healthcare providers pilot VR therapy for anxiety disorders in metropolitan hospital systems awaiting reimbursement framework clarity. Bengaluru and Hyderabad clusters develop custom enterprise content for logistics and field service training applications.
Virtual Reality (VR) Market Competitive Landscape
The competitive structure tilts toward integrated platform operators with captive silicon and content ecosystems. Three tiers have crystallized: full-stack hardware-software integrators controlling optical and semiconductor supply chains; premium console VR specialists leveraging exclusive content licensing; and enterprise-grade tethered system providers serving medical and defense simulation buyers. Dominant competitive moves include backward integration into display panel sourcing and multi-year service agreement consolidation around subscription-based content licensing.
Among full-stack platform operators, Meta and Apple exemplify the integrated architecture approach through in-house semiconductor design and optical engineering depth. Sony Group Corporation occupies a distinctive position in premium living-room entertainment through console-tethered configurations and exclusive intellectual property licensing. These three entities represent divergent strategic bets on standalone versus tethered form factors and consumer versus enterprise addressable markets.
| Leading Market Players |
|---|
| Meta |
| Sony Group Corporation |
| Apple Inc. |
| Microsoft Corporation |
| HTC Corporation |
| Samsung Electronics Co., Ltd. |
| ByteDance |
| Unity Technologies |
| DPVR |
| Others |
Value Network & Pricing Analysis
Platform operators with captive silicon fabrication and optical engineering pipelines command upstream pricing leverage through in-house control over display stack costs and Snapdragon XR processor sourcing. This ownership pattern compresses hardware margins for pure-play assemblers while enabling integrated vendors to absorb AMOLED panel volatility through volume commitments to South Korean suppliers.
Pricing Analysis
Outcome-based pricing for therapeutic VR deployments anchors hospital procurement decisions to FDA-cleared pain management efficacy rather than hardware specifications. Three-tier pricing structure across premium simulation-grade, standard enterprise, and economy education tiers separates defense pilot certification systems from K-12 wireless deployments. Cost compression in the standalone headset tier intensifies as Meta's captive silicon production forces competitor BOM reductions. Education buyers exhibit highest price sensitivity due to thin public-sector budgets, while defense simulation offices prioritize fidelity thresholds over unit economics.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing is reshaping sourcing footprints by attracting component assembly and testing operations away from China-dominant configurations. High-resolution AMOLED and micro-OLED production draws from South Korea and Taiwan, while Snapdragon XR processor integration concentrates in Shenzhen and Bengaluru corridors. Single-source vulnerability in micro-OLED etching equipment creates bottleneck exposure during demand surges. Distribution runs through direct enterprise sales teams for healthcare and defense contracts, with education and consumer segments flowing through retail channel partners and regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
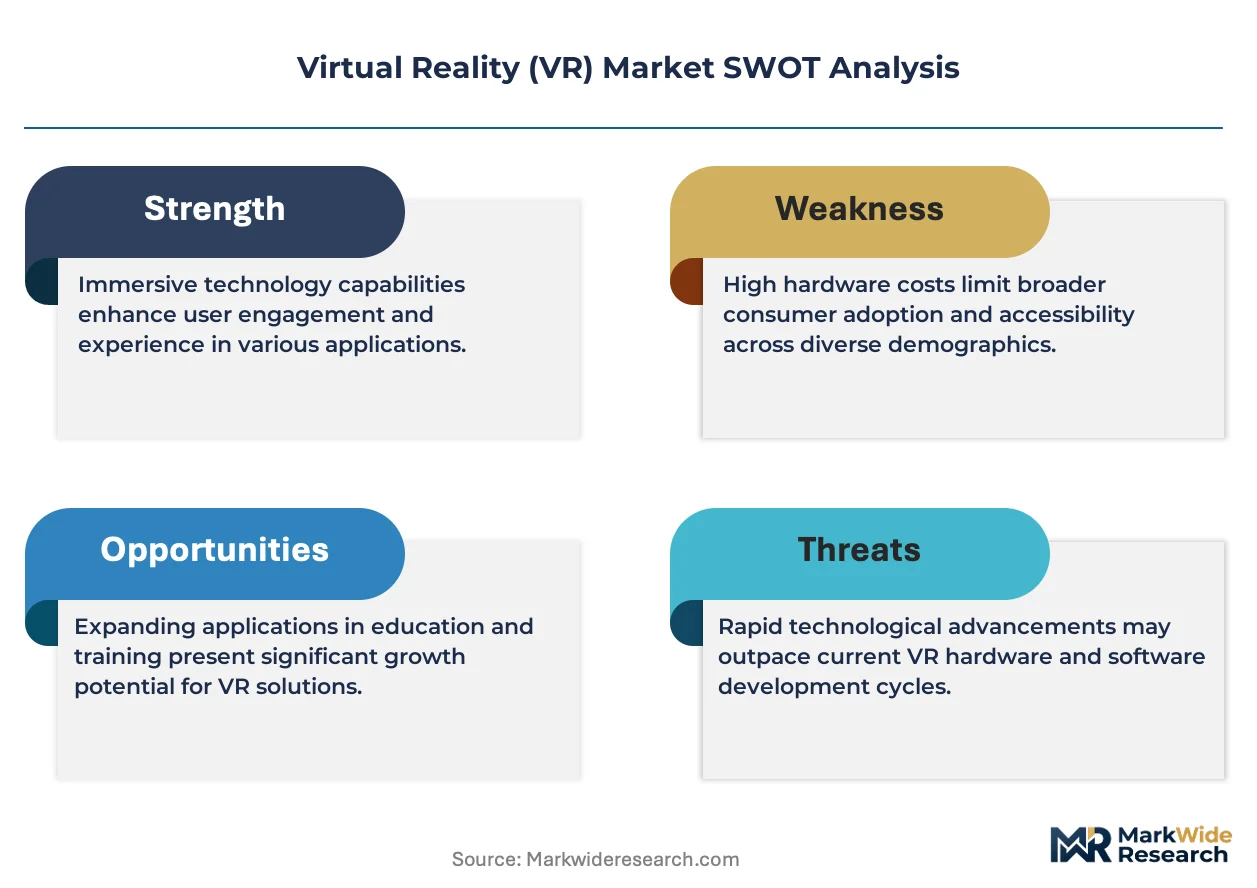
The VR market is consolidating around a vertical-integration race where optical stack ownership and captive semiconductor design determine margin survival. Players are pursuing backward integration into display panel sourcing to escape foundry pricing cycles.
For Market Incumbents: To counter cloud-rendered streaming architectures threatening hardware attach rates, Meta and Sony should deepen exclusive content licensing for therapeutic and defense applications while expanding captive micro-OLED foundry partnerships in South Korea. Certification investment in FDA 510(k) pathways for surgical rehearsal creates switching costs against thin-client competitors.
For New Entrants and Emerging Players: Haptic feedback convergence with force-feedback gloves offers a technology-first wedge into industrial maintenance training previously served by physical simulators. India's PLI-attracted manufacturing clusters present the most penetrable geography for cost-optimized standalone headsets serving Middle East education demand. A channel partnership with logistics operators seeking facility-scale wireless deployment accelerates reference customer acquisition.
For Investors and Strategic Acquirers: Distressed-cycle entries favor enterprise-grade tethered system specialists with EMA notified body relationships and hospital GPO contracts in Germany. Long-term viability across the projection horizon rests on reimbursement framework maturation in the United States behavioral health sector. The signal to monitor is FDA digital health pathway expansion into anxiety disorder exposure therapy codes.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicon Development | In-house Snapdragon XR-class processor design insulates Meta from Qualcomm foundry pricing and enables custom latency optimization for healthcare applications. |
| Micro-OLED Backward Integration | Direct sourcing relationships with Samsung Display and LG Display secure AMOLED allocation priority during supply-constrained demand surges for standalone headsets. |
| FDA 510(k) Certification Investment | Therapeutic VR clearance for pain management creates reimbursement code eligibility that accelerates hospital procurement cycles against uncertified competitors. |
| Cloud-Rendered Streaming Partnership | Edge computing alliances with hyperscalers enable thin-client education deployments that reduce hardware BOM costs for K-12 district budgets. |
| EU AI Act Compliance Architecture | Algorithmic transparency documentation and human oversight protocols for biometric inference secure CE marking approval for social VR platform launches in Germany. |
Research Methodology
Multi-period observation of Snapdragon XR processor shipment volumes, FDA 510(k) clearance timelines, and defense simulation contract awards anchored the trend analysis, supplemented by interviews with hospital biomedical engineers, defense procurement officers, and enterprise training directors. Secondary validation drew from FCC equipment authorization filings, EMA notified body guidance documents, and hyperscaler edge infrastructure capex disclosures. Bottom-up headset shipment aggregation and top-down enterprise training budget analysis were triangulated against reimbursement code adoption rates.
Input-output matrices modeled segment interactions across standalone versus PC-tethered technology architectures, healthcare versus training versus gaming end-user verticals, and United States versus China versus Germany regional clusters throughout the forecast period. CAGRs were derived from regression analysis of historical Snapdragon XR integration cycles and projected FDA digital health pathway maturation. Forecast inputs included AMOLED fab capacity expansion schedules and EU AI Act conformity assessment duration estimates.
Several conditions sit outside the modeled scope, including unannounced semiconductor export restrictions, abrupt reimbursement code withdrawals by CMS, and breakthrough haptic technologies displacing visual-centric immersion paradigms. Forecasts reflect documented assumptions around defense budget continuity and optical stack yield improvements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Japan Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Amusement Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market