
 Glasses Free 3D Tvs Market | 2026-2036
Glasses Free 3D Tvs Market Size, Share, and Industry Trends Forecast 2026-2036
Glasses Free 3D Tvs Market Foresight
Display panel foundries in Taiwan and South Korea are hardening capacity allocations toward autostereoscopic substrates. Samsung Electronics leverages vertical integration across semiconductor and display divisions to control lenticular lens sourcing. LG Electronics sustains R&D intensity in parallax barrier architectures through captive research centers in Gumi. Sony differentiates through cinematic color calibration pipelines optimized for glasses-free depth rendering.
Glasses Free 3D TVs employ lenticular lens arrays or parallax barrier layers to direct discrete images toward each eye without wearable optics, achieving depth perception through angular multiplexing at refresh rates exceeding 120 Hz for flicker-free viewing. The primary commercial purpose centers on immersive home entertainment, medical visualization, and public digital signage where user comfort and hygiene dictate against head-mounted or shutter-based systems. Lenticular lens displays currently lead installed base due to manufacturing scalability and brightness retention advantages over parallax barrier alternatives. Medical imaging represents the fastest-growing application segment as radiology departments adopt autostereoscopic monitors for preoperative planning and volumetric diagnostics. Holographic displays occupy premium niche positioning with concentrated margin pools in specialized simulation and design visualization workflows.
FCC emissions standards govern wireless connectivity modules integrated into smart TV platforms across the United States, while CE marking under the EU's Ecodesign Directive mandates standby power thresholds for displays sold in European member states. South Korea's Radio Research Agency certifies electromagnetic compatibility for domestic consumer electronics exports, creating layered compliance obligations for multi-region manufacturers. Stakeholders must monitor evolving energy efficiency benchmarks and regional content accessibility mandates that will reshape product configuration requirements and market access pathways.
Market Dynamics
Foundry capacity allocation toward autostereoscopic substrates is reshaping competitive positioning in glasses-free 3D displays, with Taiwan and South Korea hardening dedicated production lines while medical imaging procurement accelerates in Germany and Japan.
Growth Catalysts
- MIIT-Aligned Subsidies:South Korea's Ministry of Trade, Industry and Energy channels display material subsidies toward lenticular lens manufacturing, lowering input costs for domestic panel producers.
- Surgical Planning Adoption:Radiology departments in Germany and Japan are expanding autostereoscopic monitor procurement for preoperative volumetric visualization, creating sustained institutional demand.
- Guangdong Manufacturing Corridor:Electronics assembly clusters in Guangdong province concentrate downstream integration capacity, enabling rapid prototyping-to-production cycles for glasses-free 3D TV modules.
Market Restraints
- Lenticular Lens Supply Concentration:Precision lens array fabrication depends on a limited supplier base concentrated in East Asian optical component foundries, creating single-source vulnerability.
- CE Marking Compliance Costs:EU Ecodesign Directive standby power thresholds impose redesign burdens for displays entering European member states, extending certification timelines.
- Parallax Barrier Brightness Penalty:Light-attenuating barrier layers sacrifice luminance efficiency compared to lenticular alternatives, limiting adoption in high-ambient-light commercial signage.
Strategic Opportunities
- India Medical Imaging Gap:Underpenetrated radiology infrastructure in tier-2 and tier-3 Indian cities creates whitespace for cost-optimized autostereoscopic diagnostic monitors.
- Holographic-Premium Convergence:Integration of holographic light-field engines with glasses-free depth rendering is expanding into specialized surgical simulation and automotive design visualization workflows.
- Public Digital Signage Mandates:Transit authority hygiene protocols in post-pandemic urban planning are favoring touchless, glasses-free 3D displays over head-mounted alternatives in station advertising networks.
Industry Challenges
- Optical Engineer Talent Scarcity:Specialized expertise in angular multiplexing and lenticular lens design remains concentrated in legacy camera and microscope industries, constraining R&D team scaling.
- FCC-CE Dual Certification Burden:Smart TV platforms with wireless connectivity modules require sequential electromagnetic compatibility validation for US and EU markets, compressing launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glasses Free 3D Tvs Market |
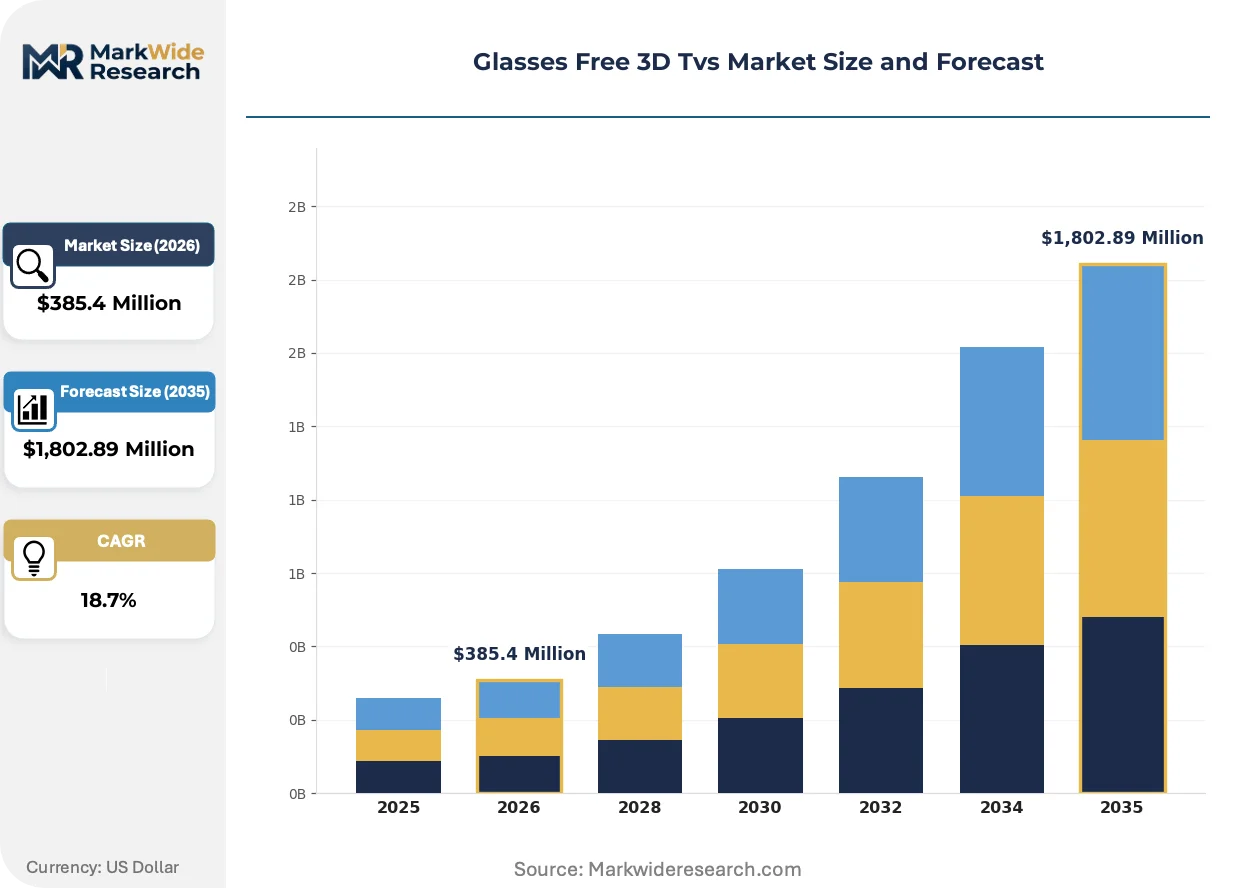
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Display Technology: Lenticular Lens, Parallax Barrier, Integral Imaging, Holographic Displays Screen Size: 24 Inches, 32 Inches, 43 Inches, 55 Inches, 65 Inches Application: Home Entertainment, Education & Training, Medical Imaging, Gaming Consoles, Public Information Distribution Channel: Online Retailers, Specialty Electronics Stores, Department Stores, Direct Manufacturer Sales |
| Companies Covered | Samsung Electronics, LG Electronics, Sony, Panasonic, Toshiba, Sharp, Philips, TCL, Hisense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glasses Free 3D Tvs Market Shifts & Advancements
Active matrix backlight modulation and real-time eye-tracking fusion are compressing the performance gap between glasses-free 3D and traditional stereoscopic systems across entertainment and professional visualization segments.
Real-time pupil-tracking arrays integrated with dynamic lenticular lens adjustment are expanding into high-end home theater installations. Home cinema integrators in California and Florida are specifying these systems for dedicated media rooms. The technology is expanding into residential markets previously blocked by narrow viewing-cone limitations.
The EU AI Act's risk classification framework for biometric inference systems is imposing documentation requirements on eye-tracking modules embedded in smart displays. Manufacturers must now maintain algorithmic transparency logs for gaze-estimation components. Medical imaging OEMs serving European hospitals are responding by segregating eye-tracking firmware into detachable modules subject to separate conformity assessment.
Direct procurement relationships between Guangdong electronics assemblers and Taiwan substrate foundries are displacing traditional component distributor channels for high-volume glasses-free 3D TV orders. Volume buyers in the digital signage vertical now negotiate annual supply agreements spanning lens arrays, driver ICs, and backlight units. This pattern is most visible in procurement by Korean and Chinese out-of-home advertising network operators seeking margin compression through channel consolidation.
Glasses Free 3D Tvs Market Segmentation
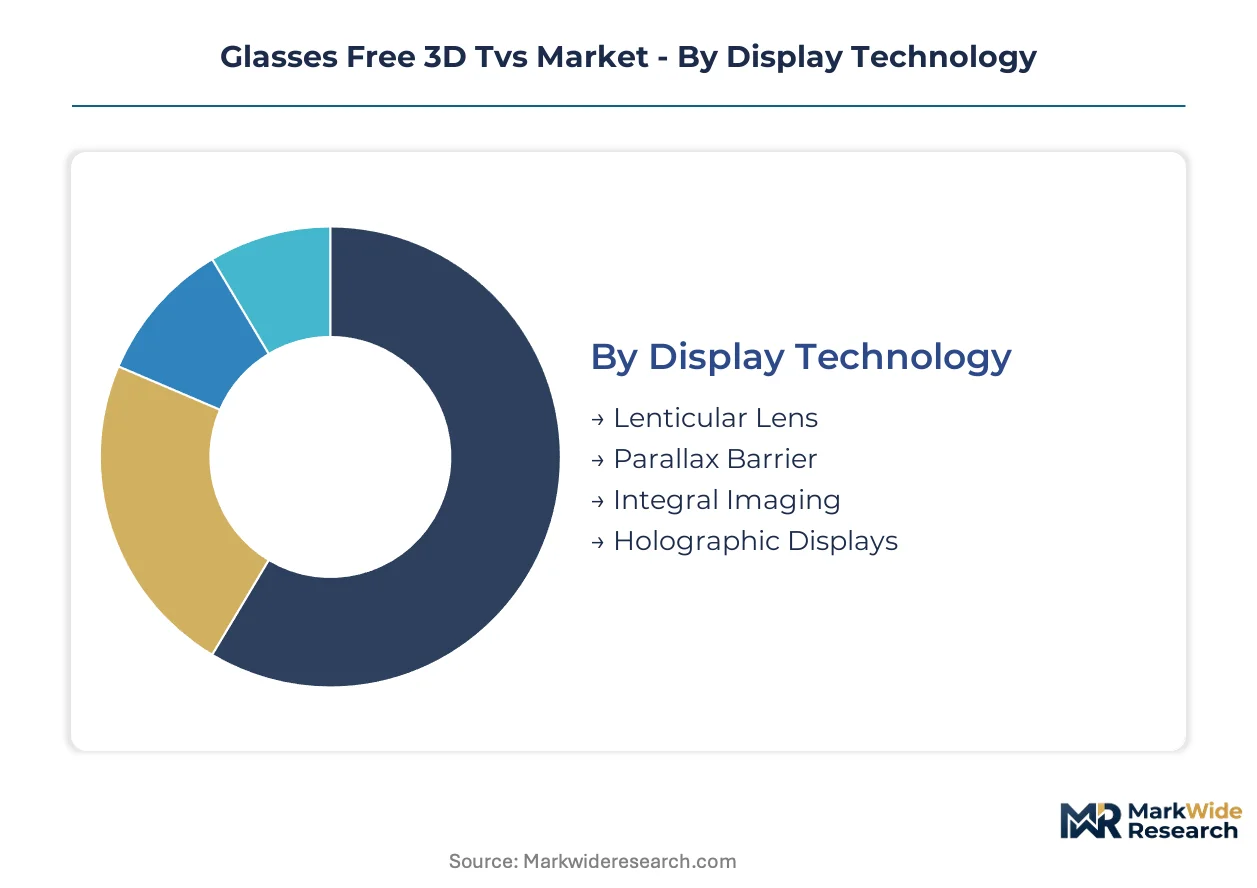
Segmentation in glasses-free 3D TVs reveals how display architecture, installation environment, and procurement channel each impose distinct performance requirements and margin structures. Manufacturers configure product lines around these boundaries to optimize factory utilization and regional go-to-market economics.
Display Technology:
Upgrade cycles in this category accelerate when brightness efficiency and viewing-angle tolerance improve meaningfully, pushing institutional buyers toward newer architectures.
- Lenticular Lens:Cylindrical lens arrays mounted on LCD or OLED substrates steer discrete images to each eye through angular multiplexing. Manufacturing scalability at Taiwan and South Korean foundries has concentrated procurement for digital signage networks in Guangdong province and Seoul metropolitan area.
- Parallax Barrier:Precision light-blocking apertures create viewing zones without additional optical layers, sacrificing luminance for thinner form factors. German and Japanese medical imaging departments favor these configurations for surgical planning workstations where space constraints dominate.
- Integral Imaging:Micro-lens arrays capture and reproduce light fields through multiple perspective images, enabling continuous parallax without eye-tracking.
- Holographic Displays:Interference-pattern reconstruction creates volumetric images viewable without glasses, occupying premium niches in automotive design studios and surgical simulation centers.
Lenticular Lens sits at the top of the volume ranking, with Holographic Displays climbing the fastest.
Screen Size:
Cost tier positioning determines factory allocation, with larger substrates commanding dedicated production lines and specialized handling equipment.
- 55 Inches:Dominant form factor for residential home theater installations, balancing immersion with living-room spatial constraints. California and Florida integrators specify these for dedicated media rooms with eye-tracking fusion systems.
- 65 Inches:Premium residential and commercial installations requiring maximum field-of-view for group viewing. Korean out-of-home advertising operators deploy these in transit station networks under post-pandemic hygiene mandates.
- 24 Inches:Compact diagnostic monitors for radiology workstations.
- 32 Inches:Secondary displays for educational and training environments.
- 43 Inches:Mid-size commercial signage and gaming console integration.
55 Inches generates the highest shipment volumes, while 65 Inches expands most quickly into commercial replacement cycles.
Application:
Volume concentration varies sharply by end-use maturity, with established segments defending share against emerging verticals redefining performance specifications.
- Medical Imaging:Autostereoscopic monitors enable volumetric visualization of CT and MRI datasets without radiologist fatigue from head-mounted systems. German university hospitals and Japanese diagnostic centers are expanding procurement for preoperative planning, creating the steepest expansion trajectory among all applications.
- Home Entertainment:Residential installations with real-time eye-tracking and dynamic lens adjustment are penetrating California and Florida markets previously blocked by narrow viewing cones.
- Education & Training:Institutional procurement for anatomy and engineering visualization labs.
- Gaming Consoles:Peripheral displays for immersive gameplay without wearable optics.
- Public Information:Transit authority advertising networks favoring touchless glasses-free formats.
Home Entertainment maintains volume leadership, with Medical Imaging gaining share fastest on institutional procurement acceleration.
Distribution Channel:
Supply concentration in East Asian manufacturing clusters is compressing channel layers, with volume buyers negotiating direct relationships.
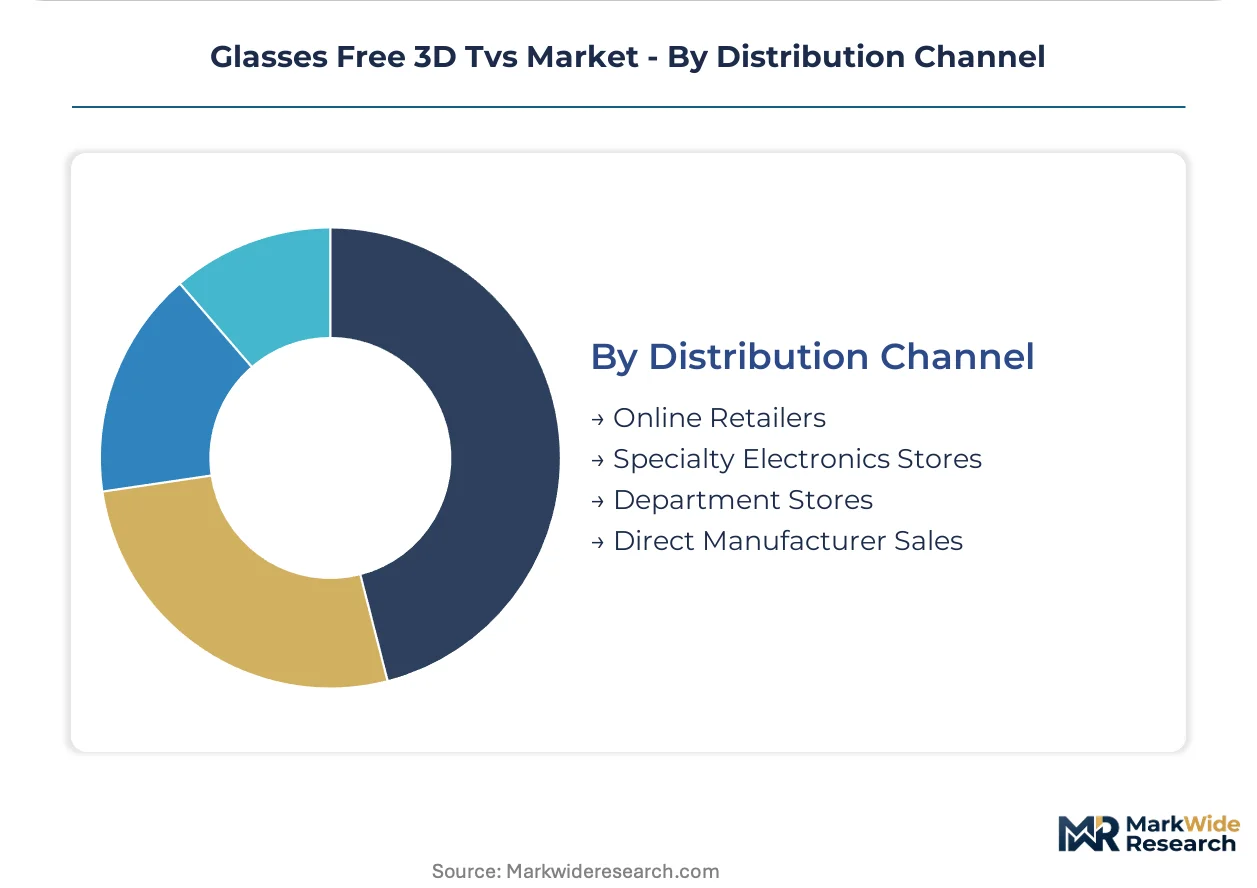
- Direct Manufacturer Sales:Annual supply agreements spanning lens arrays, driver ICs, and backlight units now dominate procurement by Korean and Chinese digital signage operators seeking margin compression through channel consolidation.
- Online Retailers:E-commerce platforms capture residential replacement demand in North American and European markets with standardized logistics and return handling.
- Specialty Electronics Stores:Home cinema integrators in California and Florida source through these channels for white-glove installation services.
- Department Stores:Mass-market retail presence for entry-tier consumer models.
Direct Manufacturer Sales commands the highest volume flow, with Online Retailers climbing fastest on residential demand digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions where display material subsidies offset compliance costs, while procurement clusters form around medical imaging infrastructure and electronics manufacturing corridors.
South Korea
Seoul Capital Area producers dominate lenticular lens substrate fabrication, drawing on Ministry of Trade, Industry and Energy subsidies aligned with MIIT standards. The Radio Research Agency certifies electromagnetic compatibility for consumer electronics exports, creating dual compliance pathways for multi-region manufacturers. Gumi hosts captive R&D centers advancing parallax barrier architectures.
Japan
METI procurement programs accelerate autostereoscopic monitor adoption in university hospitals for preoperative volumetric visualization. The Pharmaceuticals and Medical Devices Agency oversees diagnostic display quality standards, institutionalizing clinical validation requirements. Tokyo and Osaka diagnostic centers anchor institutional demand for radiology workstation configurations.
Germany
CE marking under the EU Ecodesign Directive mandates standby power thresholds, extending certification timelines for displays entering European markets. The Federal Motor Transport Authority does not regulate this sector, but university hospital procurement in Bavaria and North Rhine-Westphalia drives medical imaging demand. Berlin-Brandenburg clusters concentrate surgical planning software integration.
China
Guangdong province's electronics manufacturing corridor concentrates downstream integration capacity for rapid prototyping-to-production cycles. MIIT display material subsidies lower input costs for domestic panel producers. Shenzhen and Dongguan assembly clusters displace traditional component distributor channels through direct procurement relationships with Taiwan substrate foundries.
United States
FCC emissions standards govern wireless connectivity modules integrated into smart TV platforms, while California and Florida home cinema integrators specify eye-tracking fusion systems for dedicated media rooms. The FDA does not regulate consumer displays, but medical imaging OEMs serving European hospitals maintain algorithmic transparency logs for gaze-estimation components under EU AI Act documentation requirements.
Glasses Free 3D Tvs Market Competitive Landscape
South Korean producers anchor one tier; Japanese and Taiwanese specialists hold differentiated positions in optical component and substrate fabrication. The market exhibits moderate consolidation around vertically integrated electronics conglomerates with captive display divisions. Three archetypes dominate: conglomerate-scale systems integrators controlling lenticular lens sourcing, regional specialists in parallax barrier architectures, and optical component foundries supplying precision lens arrays. Capacity expansion and backward integration into substrate production represent the dominant competitive moves.
Within the conglomerate-scale tier, Samsung Electronics Co., Ltd. and LG Electronics Inc. exemplify vertically integrated structures spanning semiconductor and display divisions. Sony Corporation occupies a distinct position emphasizing cinematic color calibration pipelines. These three anchors represent divergent strategic postures: captive supply chain control, sustained R&D intensity in barrier architectures, and premium-tier differentiation through imaging heritage.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony |
| Panasonic |
| Toshiba |
| Sharp |
| Philips |
| TCL |
| Hisense |
| Others |
Supply & Pricing Matrix
Lenticular lens substrate pricing indices from Taiwan and South Korean foundries cascade through Guangdong assembly clusters into three distinct buyer tiers, compressing channel margins for digital signage operators while preserving premium capture for medical imaging OEMs serving German and Japanese hospitals.
Pricing Analysis
Distributor markups of 12-18 percent on optical component bundles are collapsing under direct procurement relationships between Guangdong electronics assemblers and Taiwan substrate foundries. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic monitors from commercial signage units and entry-level residential displays. Pricing pressure stems from MIIT-aligned subsidy programs lowering input costs for domestic Chinese panel producers. Digital signage operators in Seoul and Guangzhou exhibit highest price sensitivity, while German university hospitals accept premium positioning for CE-marked surgical planning workstations.
Supply Chain Analysis
CE marking and FCC emissions certification create dual gating costs that extend launch windows for multi-region manufacturers serving both European and North American markets. Precision lens array fabrication concentrates in Taiwan, South Korea, and Japan, drawing from specialized optical glass substrates, driver ICs, and active matrix backlight modules. Single-source vulnerability in cylindrical lens master tooling creates supply chain risk. Distribution runs through direct annual supply agreements for volume buyers, displacing traditional component distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in glasses-free 3D displays rests on MIIT subsidy capture and premium-tier migration toward eye-tracking fusion systems in California and Florida residential markets.
For Market Incumbents: Acquire captive lenticular lens fabrication capacity to defend against parallax barrier substitutes encroaching from LG's Gumi R&D centers. Secure Radio Research Agency pre-certification for electromagnetic compatibility to compress dual-market launch timelines. Backward integration into Taiwan substrate sourcing insulates against Guangdong assembler margin compression. For New Entrants and Emerging Players: Capture whitespace in tier-2 and tier-3 Indian cities where underpenetrated radiology infrastructure lacks autostereoscopic diagnostic monitors. Target cost-optimized 24-inch parallax barrier configurations for hospital procurement committees. Partner with Guangdong electronics assemblers for rapid prototyping-to-production cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with optical component foundries possessing precision lens array expertise concentrated in legacy camera and microscope industries. Long-term viability favors specialists with captive R&D in angular multiplexing and real-time pupil-tracking arrays. Watch for EU AI Act enforcement triggering detachable eye-tracking module architectures as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lens Array Fabrication | Samsung Electronics controls lenticular lens sourcing through captive semiconductor-display division coordination. |
| CE Marking Pre-Certification Investment | EU Ecodesign Directive standby power thresholds impose redesign burdens extending European market access timelines. |
| Medical Imaging OEM Partnership | German university hospitals in Bavaria anchor procurement for preoperative volumetric visualization workstations. |
| Eye-Tracking Fusion Product Launch | California and Florida home cinema integrators specify dynamic lens adjustment systems for dedicated media rooms. |
| Direct Procurement Channel Establishment | Korean and Chinese digital signage operators negotiate annual supply agreements spanning lens arrays and driver ICs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with display panel foundry executives, optical component procurement managers, radiology department heads in German and Japanese hospitals, home cinema integrators in California and Florida, and digital signage network operators in Seoul and Guangzhou with secondary validation against SEC filings from Samsung Electronics and LG Electronics, MIIT subsidy disclosure records, EU Ecodesign Directive implementation reports, and FCC equipment authorization databases. Bottom-up shipment aggregation and top-down market sizing triangulated volume estimates.
Historical reference periods anchored the projection horizon to observed foundry capacity allocation shifts and medical imaging procurement acceleration patterns across the modeling period. Segmentation dimensions modeled include display technology architecture, screen size tier, application vertical, and distribution channel structure. CAGRs derived from installed base replacement cycles and emerging segment penetration curves incorporated lenticular lens manufacturing yield improvements and parallax barrier brightness efficiency gains as industry-specific inputs.
Subsidy program expiration, regulatory reclassification of eye-tracking modules under EU AI Act risk frameworks, and foundry capacity reallocation toward non-autostereoscopic substrates are the dominant revision risks to forecast assumptions. A model refresh is warranted upon material change in MIIT-aligned display material subsidy continuity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
Global 3D Virtual Platform Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
Global 3D Rendering Service Market
3D Technology
3D Printing CAD Software Market
3D Technology
3D Photogrammetry Software Market
3D Technology
3D Rendering Software Market
3D Technology
3D Machine Vision Market
3D Technology
3D CAD Market
3D Technology
3D Technology Market
3D Technology
Europe 3D 4D Technology Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
North America 3D 4D Technology Market
3D Technology
3D Simulation Software Market
3D Technology
Global 3D 4D Technology Market
3D Technology
Global Mobile 3D Sensing Market