
 VR HMD Shipment Market | 2026-2036
VR HMD Shipment Market Size, Share, and Industry Trends Forecast 2026-2036
VR HMD Shipment Market Analytics
The capital-intensity divergence between self-sufficient ecosystem builders and component-dependent assemblers is unwinding competitive stability across the VR HMD landscape. Meta Platforms leverages its vertically integrated hardware-software stack to control content monetization and reduce per-unit silicon dependency. Sony Group Corporation anchors its position through display supply chain partnerships inherited from television and camera sensor operations. Valve Corporation specializes in precision tracking subsystems that sustain premium pricing in PC-tethered segments.
A VR HMD (virtual reality head-mounted display) is a wearable display system incorporating dual micro-displays, Fresnel or pancake optics, and inertial measurement units to render stereoscopic 3D environments with sub-20ms motion-to-photon latency for real-time immersion. The device serves commercial purposes spanning interactive entertainment, workforce simulation, and clinical intervention protocols. Standalone headsets now dominate volume shipments as Qualcomm Snapdragon XR platforms eliminate external compute dependencies. Tethered systems retain margin concentration in enterprise simulation and defense training where 4K OLED fidelity and expanded field-of-view specifications justify premium procurement. Smartphone-based configurations have contracted to emerging-market entry segments as affordable standalone alternatives displace cardboard-derived architectures.
FCC equipment authorization governs radio frequency emissions for VR HMDs sold in the United States, while CE marking under EU MDR and RoHS directives constrains material composition and biocompatibility claims for therapeutic applications in Europe. Japan's METI has issued guidance on display safety standards for extended-duration immersion, influencing manufacturer backlight modulation strategies. Stakeholders must monitor how divergent electromagnetic exposure thresholds between FDA clinical device pathways and consumer electronics frameworks reshape product architecture decisions for dual-use healthcare-entertainment headsets.
Market Dynamics
The migration from Fresnel to pancake optical architectures is compressing headset form factors while demanding precision manufacturing capabilities that concentrate supply among specialized Asian optics houses. This single technical transition is redistributing margin pools across the VR HMD value chain and forcing tier-2 assemblers into dependency relationships with component suppliers.
Growth Catalysts
- Surgical Simulation Demand:Healthcare systems in Germany and the United States are procuring tethered VR HMDs for resident training programs, with procurement volumes tied to hospital accreditation standards.
- EU AI Act Conformity Pathways:The MDR's tightened biocompatibility requirements for therapeutic devices are creating certified-product premiums that reward early regulatory investment.
- Qualcomm Snapdragon XR Dominance:The platform's integration of spatial computing silicon is eliminating external compute dependencies and enabling standalone volume expansion across enterprise deployment hubs.
Market Restraints
- Display Supply Concentration:Micro-OLED fabrication capacity concentrates in South Korean and Japanese foundries, creating allocation risk for premium headset tiers.
- Silicon Cost Volatility:Advanced node wafers for XR-specific SoCs face pricing pressure from competing automotive and smartphone demand.
- Motion Sickness Physiology:Sub-20ms motion-to-photon latency requirements impose hard technical barriers on entry-level chipset selections.
Strategic Opportunities
- India Clinical Validation Centers:The country's emerging network of medical device testing facilities offers lower-cost CE marking precursor studies for European market entry.
- Defense Training Procurement:NATO member states are soliciting 4K OLED tethered systems for simulation environments with expanded field-of-view specifications.
- Spatial Computing Convergence:Integration of passthrough mixed reality capabilities is opening industrial maintenance applications previously served by tablet-based AR.
Industry Challenges
- Optomechanical Talent Scarcity:Precision pancake lens assembly requires skills concentrated in camera module and semiconductor lithography industries.
- Dual-Use Certification Complexity:Headsets targeting both FDA clinical device pathways and consumer electronics frameworks face divergent electromagnetic exposure testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR HMD Shipment Market |
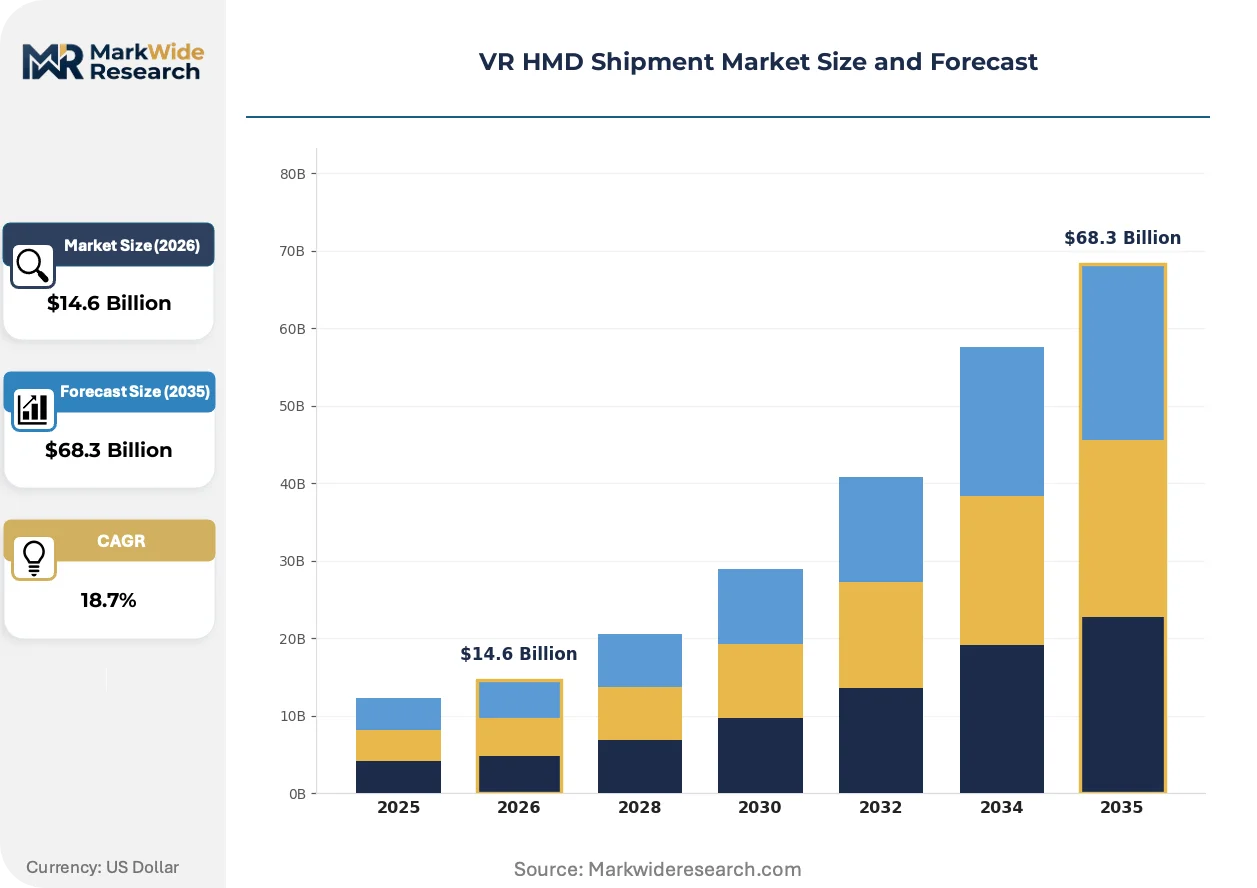
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $68.3 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Tethered, Smartphone-Based, PC-Based Technology: OLED, LCD, 4K, FOV End User: Gaming, Education, Training, Healthcare Application: Entertainment, Simulation, Therapy, Design |
| Companies Covered | Meta Platforms, Sony Group Corporation, HTC Corporation, Pico Interactive, Valve Corporation, Apple, Samsung Electronics, Microsoft Corporation, RayNeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR HMD Shipment Market Evolving Landscape
Pancake optical stacks are compressing headset thickness while demanding tighter manufacturing tolerances. This optical transition is redistributing competitive advantage toward suppliers with precision lens molding capabilities and away from legacy Fresnel-focused assemblers.
Silicon carbide (SiC) wafer substrates are displacing traditional glass-based waveguide materials in high-end enterprise headsets. Defense contractors and surgical simulation centers are adopting SiC-based devices for their thermal stability during extended immersion sessions. This material shift is compressing the addressable market for conventional glass optics suppliers.
The EU AI Act's risk classification framework for biometric identification systems is forcing manufacturers to segregate healthcare and entertainment firmware tracks. Devices marketed for therapeutic applications face enhanced conformity assessment under MDR Article 10. German notified bodies are processing these dual-track submissions with 14-18 month timelines.
Hospital procurement departments are consolidating VR HMD purchasing through group purchasing organizations rather than individual department acquisition. This concentration is displacing direct-to-clinic sales channels in the United States and compressing vendor margins through volume-based contracting. The Veterans Health Administration's centralized procurement office exemplifies this pattern.
VR HMD Shipment Market Segmentation
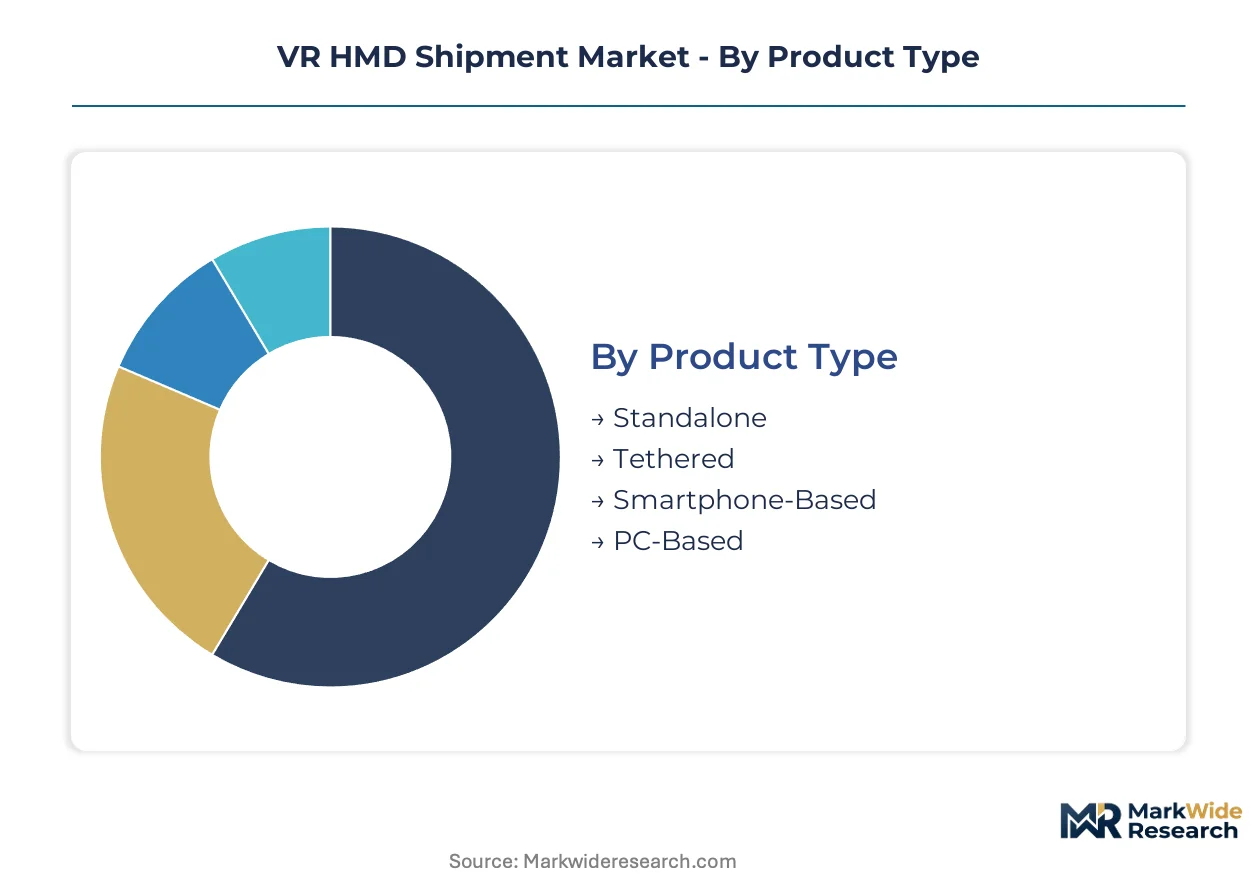
Segmentation in VR HMD shipments reveals how regulatory pathways, optical specifications, and end-use certification requirements reshape procurement patterns across healthcare, defense, and consumer channels. Each dimension carries distinct compliance burdens and margin structures that determine vendor viability.
Product Type:
FDA 510(k) clearance timelines and CE MDR conformity assessments diverge sharply across tethered versus standalone architectures, with battery-powered systems facing additional electromagnetic exposure testing.
- Standalone:Qualcomm Snapdragon XR platforms integrate compute, display driver, and tracking silicon into single-SoC designs. Hospital systems in Germany and the United States are procuring these for ward-based patient therapy where installation flexibility outweighs fidelity demands. CE MDR Article 10 compliance for therapeutic claims adds 14-18 month certification cycles.
- Tethered:External GPU dependency enables 4K OLED fidelity and sub-20ms motion-to-photon latency through dedicated DisplayPort bandwidth. NATO defense training centers and US Veterans Health Administration simulation facilities specify these for expanded field-of-view surgical rehearsal environments.
- Smartphone-Based:Cardboard-derived architectures now concentrate in Indian and Southeast Asian education ministries with constrained capital budgets.
- PC-Based:Valve precision tracking subsystems sustain premium pricing in enterprise simulation where SteamVR software integration reduces deployment friction.
Standalone handles the majority of throughput; tethered is climbing the fastest on share as healthcare accreditation standards tighten.
Technology:
Material composition determines thermal stability during extended immersion, with silicon carbide substrates displacing glass waveguides in defense and surgical simulation procurement.
- OLED:Micro-OLED fabrication from South Korean and Japanese foundries delivers per-eye 4K resolution with pixel-dense RGB stripe patterns. US FDA clinical device pathways and EU MDR biocompatibility claims both specify OLED for diagnostic-grade visualization tasks.
- LCD:Fast-switching IPS derivatives with mini-LED backlight zones reduce cost per unit for volume education deployments. Chinese procurement of LCD-based headsets for vocational training centers is expanding most quickly.
- 4K:Resolution threshold now mandatory for NATO simulation tenders and German hospital group purchasing organization specifications.
- FOV:Field-of-view expansion beyond 110 degrees requires pancake optical stacks with precision lens molding capabilities concentrated in Asian optics houses.
OLED dominates revenue concentration; LCD is expanding most quickly in unit terms.
End User:
Procurement authority concentration through group purchasing organizations and defense central purchasing offices is compressing direct-to-department sales channels.
- Gaming:Consumer entertainment volume concentrates in Meta Platforms' vertically integrated hardware-software stack with content monetization control.
- Education:Indian clinical validation centers and lower-cost CE marking precursor studies are enabling European market entry for budget-tier hardware vendors.
- Training:NATO member state defense procurement specifies 4K OLED tethered systems with SiC thermal stability for extended simulation sessions.
- Healthcare:German notified bodies processing dual-track healthcare-entertainment firmware submissions under EU AI Act risk classification frameworks.
Healthcare commands premium pricing; training is gaining share fastest on defense procurement acceleration.
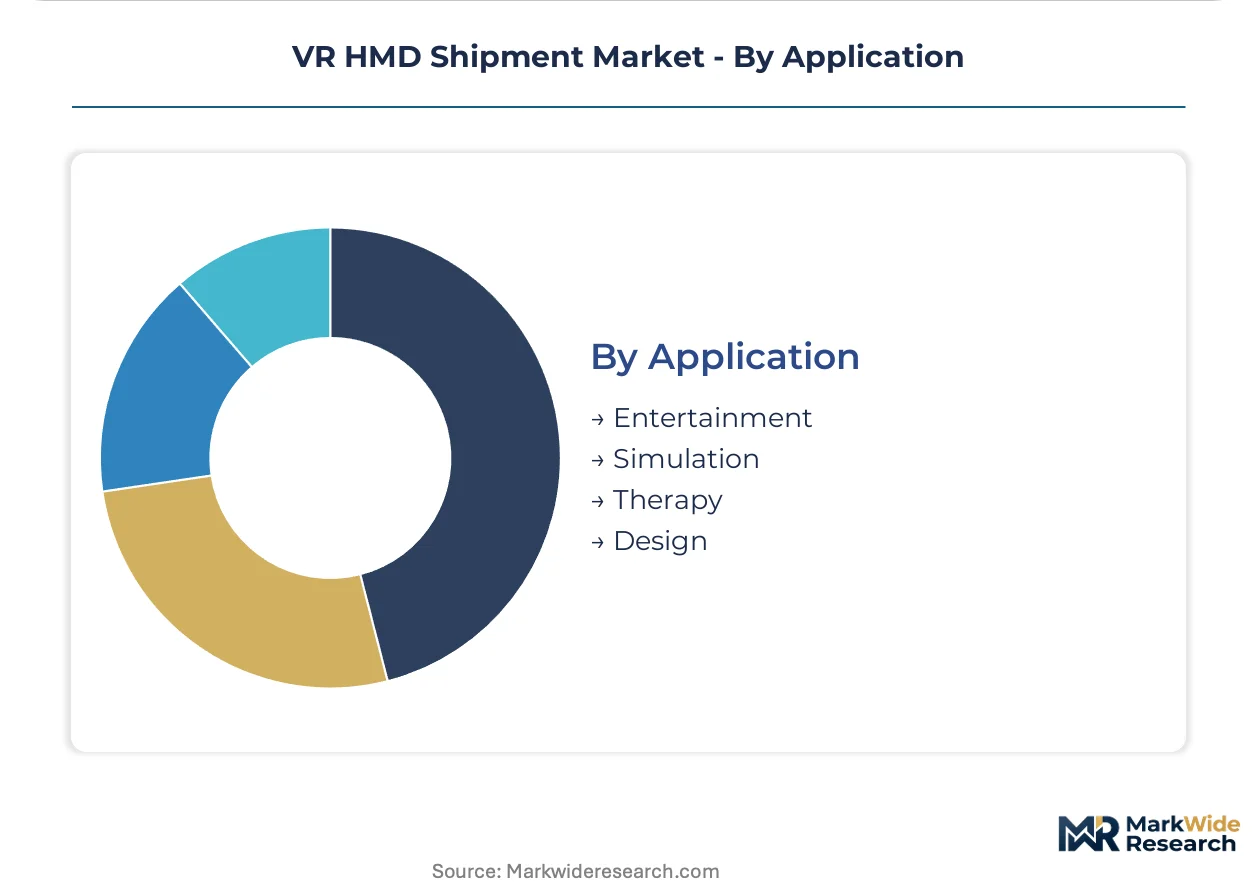
Application:
Passthrough mixed reality convergence is opening industrial maintenance segments previously served by tablet-based AR, reshaping competitive positioning across enterprise deployment hubs.
- Entertainment:Meta content monetization through Horizon Worlds and third-party studio revenue share agreements.
- Simulation:US Veterans Health Administration centralized procurement office and German hospital accreditation standards driving tethered system specification.
- Therapy:EU AI Act biometric identification risk classification forcing firmware track segregation for therapeutic versus entertainment marketing claims.
- Design:Autodesk and Dassault Systèmes integration with SteamVR and OpenXR runtime standards.
Simulation handles throughput concentration; therapy is expanding most quickly on regulatory-certified product premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement elasticity varies sharply by geography, with German hospital systems absorbing certified-device premiums while Indian education ministries prioritize cost-minimized LCD configurations. This demand bifurcation shapes regional vendor strategies and certification investment timelines.
United States
The Veterans Health Administration operates centralized procurement for tethered surgical simulation systems, with hospital accreditation standards mandating 4K OLED fidelity for resident training programs. FCC equipment authorization governs radio frequency emissions for standalone therapy devices deployed in ward-based patient care. Boston and San Francisco host clinical validation centers processing FDA 510(k) submissions for dual-use healthcare-entertainment headsets.
Germany
German hospital group purchasing organizations specify CE MDR Article 10 compliance for therapeutic VR claims, creating 14-18 month certification cycles that reward early regulatory investment. The EU AI Act's biometric identification risk classification forces firmware track segregation for devices marketed across healthcare and entertainment segments. Munich and Stuttgart anchor precision optics manufacturing clusters supplying pancake lens assemblies to tier-1 headset vendors.
China
Vocational training centers in Guangdong and Jiangsu provinces drive LCD-based headset volume procurement for workforce simulation curricula. MIIT display safety standards influence backlight modulation strategies for extended-duration immersion applications. Shenzhen's enterprise deployment hubs concentrate standalone headset assembly for domestic education and industrial maintenance segments.
India
Indian clinical validation centers offer lower-cost CE marking precursor studies, enabling European market entry for budget-tier hardware vendors facing German notified body bottlenecks. BIS certification requirements for electronic imports shape component sourcing strategies for domestic assemblers. Bangalore and Hyderabad host medical device testing facilities processing biocompatibility claims for therapeutic headset applications.
Japan
METI guidance on display safety standards for extended-duration immersion drives manufacturer investment in thermal management architectures. Micro-OLED fabrication capacity concentrates in Japanese and South Korean foundries, creating allocation priority for defense and surgical simulation procurement. Tokyo and Osaka anchor precision electronics clusters supplying inertial measurement units and tracking subsystems to premium headset tiers.
VR HMD Shipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical control over silicon and content distribution separating margin capture from assembly-dependent competitors. The market structure concentrates around three strategic archetypes: ecosystem builders commanding hardware-software integration, display supply chain specialists leveraging inherited manufacturing partnerships, and precision tracking vendors sustaining premium positioning in tethered segments. Competitive moves center on regulatory certification pre-positioning for healthcare procurement and optical technology transitions compressing headset form factors.
Among ecosystem-integrated players, Meta Platforms exemplifies the vertically controlled archetype through its captive hardware-software stack and content monetization infrastructure. Sony Group Corporation occupies a position anchored by display supply chain partnerships inherited from adjacent consumer electronics operations. Valve Corporation sits within the precision specialist tier, with SteamVR runtime integration reducing deployment friction in enterprise simulation environments.
| Leading Market Players |
|---|
| Meta Platforms |
| Sony Group Corporation |
| HTC Corporation |
| Pico Interactive |
| Valve Corporation |
| Apple |
| Samsung Electronics |
| Microsoft Corporation |
| RayNeo |
| Others |
Value Network & Pricing Analysis
Pancake optical stacks replacing Fresnel lenses simultaneously concentrates manufacturing in Asian precision optics houses and compresses margin capture for legacy assemblers unable to source molded lens components. This substitution dynamic redistributes pricing power toward specialized suppliers while forcing tier-2 headset vendors into dependency relationships that erode their procurement leverage.
Pricing Analysis
After-sales service contracts and extended warranty tiers now drive lifetime value more than hardware margins, with hospital systems and defense procurement offices negotiating multi-year maintenance bundles alongside initial device acquisition. Three-tier pricing structure across premium tethered systems, standard standalone configurations, and economy LCD-based education headsets reflects certification grade and optical fidelity differentiation. Pricing pressure stems from Qualcomm Snapdragon XR platform commoditization eliminating compute subsystem premiums. Education ministries in India and Southeast Asia exhibit highest price sensitivity, while German hospital group purchasing organizations absorb certified-device premiums for MDR-compliant therapeutic claims.
Supply Chain Analysis
Strategic stockpiling of micro-OLED display panels characterizes procurement behavior among premium headset vendors, contrasting with just-in-time component flows for LCD-based volume education shipments. Manufacturing concentrates in China for final assembly, South Korea and Japan for micro-OLED fabrication, and Germany for precision pancake lens molding. Silicon carbide wafer substrates and inertial measurement units represent critical input dependencies. Single-source vulnerability in South Korean and Japanese foundry capacity creates allocation risk for 4K OLED tiers. Distribution runs through enterprise deployment hubs in Shenzhen, direct-to-clinic sales channels for US healthcare, and centralized defense procurement offices for NATO simulation tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VR HMD market sits in an early-cycle expansion phase, with surgical simulation accreditation standards and EU AI Act conformity pathways accelerating healthcare procurement beyond consumer entertainment saturation levels.
For Market Incumbents: Compound regulatory certification advantages by securing dual-track FDA 510(k) and CE MDR submissions before notified body bottlenecks intensify, while deepening backward integration into precision optics manufacturing to reduce dependency on Asian lens molding houses threatened by optomechanical talent scarcity. For New Entrants and Emerging Players: Lead with India's lower-cost clinical validation centers as a CE marking precursor pathway, targeting budget-tier standalone headsets for European market entry through German hospital procurement specifications that reward early MDR investment with certified-product premiums. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertically integrated ecosystem builders with captive content monetization infrastructure over component-dependent assemblers; prioritize targets with established Snapdragon XR platform engineering teams and healthcare firmware segregation capabilities. Watch for FDA clinical device pathway clearance volumes as the inflection signal separating sustainable healthcare positioning from consumer entertainment margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE MDR Article 10 Certification Investment | Creates 14-18 month regulatory moats that reward early notified body engagement in Germany. |
| Pancake Optical Stack Integration | Compresses headset form factors while concentrating supply relationships with Asian precision lens molders. |
| Hospital Group Purchasing Organization Partnership | Secures volume-based contracting access displacing direct-to-clinic sales channels in US healthcare. |
| Silicon Carbide Waveguide Adoption | Enables thermal stability premiums in NATO defense training and surgical simulation procurement. |
| Spatial Computing Platform Convergence | Opens industrial maintenance applications previously served by tablet-based AR through passthrough mixed reality. |
Research Methodology
The analysis maps standalone, tethered, smartphone-based, and PC-based headset architectures, each validated through procurement managers at hospital systems, biomedical engineers at clinical validation centers, defense simulation officers at NATO training facilities, and optics manufacturing specialists at precision lens houses. Primary interview insights combined with secondary validation against FCC equipment authorization databases, EU MDR notified body submission records, and MIIT display safety standard filings. Bottom-up shipment estimates by product tier triangulated against top-down healthcare procurement budget allocations across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, display technology, end-user vertical, and application use case dimensions. CAGRs derived from healthcare procurement elasticity coefficients, defense budget appropriation trajectories, and education ministry capital expenditure patterns. Industry-specific inputs included Qualcomm Snapdragon XR platform adoption curves, micro-OLED foundry capacity expansion schedules, and German notified body processing timelines.
Forecasts assume regulatory continuity in FDA clinical device pathways, EU AI Act risk classification frameworks, and CE MDR conformity assessments; material policy shifts in electromagnetic exposure thresholds or biometric identification requirements would require re-modeling. Revision becomes warranted when hospital accreditation standards mandate display specifications exceeding current micro-OLED fabrication yields or when defense procurement tenders specify thermal stability metrics beyond silicon carbide substrate availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Japan Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market