
 Consumer Metaverse Market | 2026-2036
Consumer Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Metaverse Market Outlook
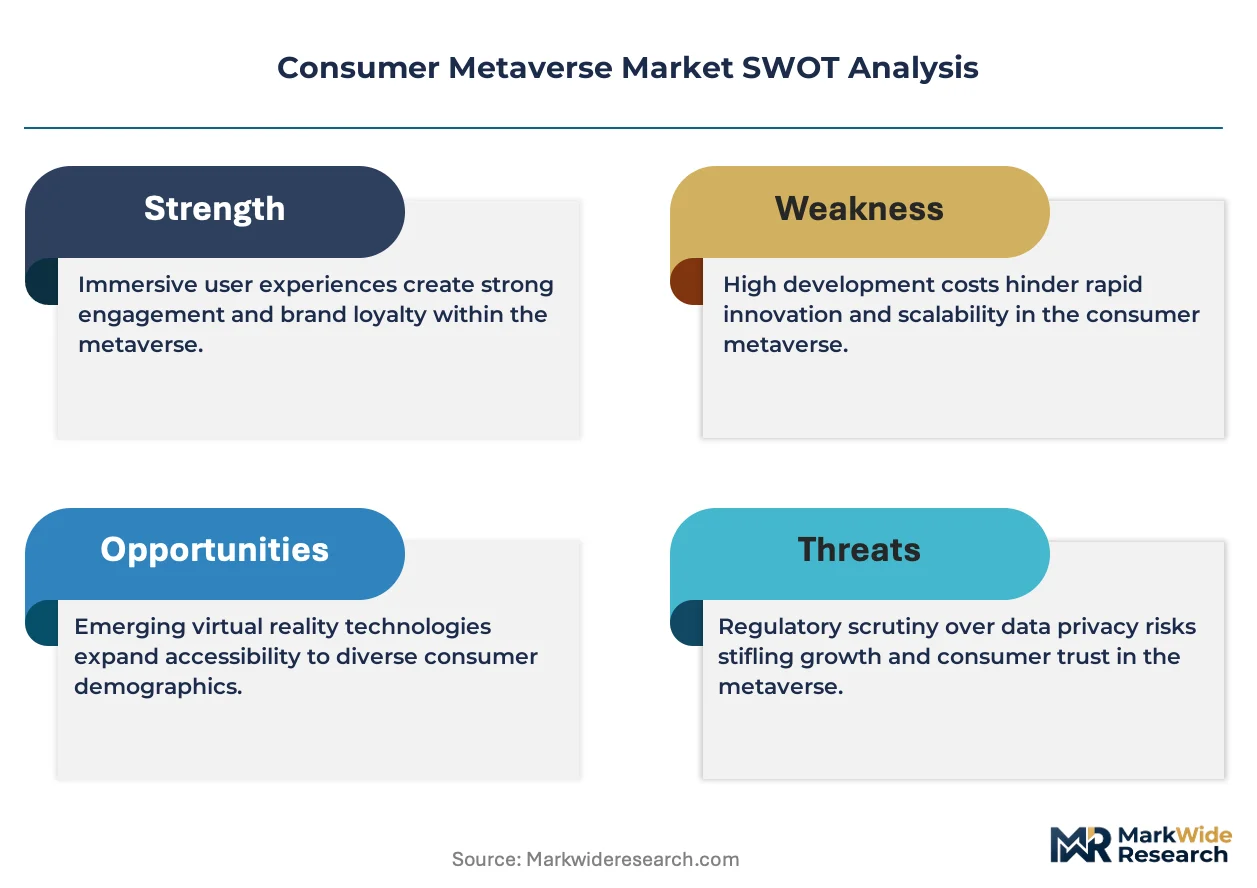
Buyer fragmentation across younger demographics and casual creators is realigning platform monetization strategies toward micro-transaction economies. Meta Platforms leverages its social graph infrastructure to retain immersive engagement hours. Roblox Corporation anchors its position through creator revenue-sharing mechanisms that sustain user-generated content volume. Epic Games differentiates via Unreal Engine fidelity standards that attract premium brand activations.
The consumer metaverse denotes persistent, shared virtual environments where users interact through avatars across real-time rendered spaces, typically requiring sub-20ms latency for presence retention and spatial audio synchronization for social immersion. Gaming Experiences currently dominate application revenue through battle-pass and cosmetic economies, while Virtual Shopping represents the fastest-expanding segment as luxury houses deploy photogrammetric showrooms. Blockchain technology underpins digital scarcity claims for collectible assets, though AI-Driven Avatars command growing infrastructure investment for natural-language interaction layers.
FCC broadband mapping mandates and EU GDPR data-localization requirements shape platform hosting architectures, while the EU AI Act imposes transparency obligations on avatar-generation algorithms. Stakeholders must monitor how interoperability standards between walled-garden ecosystems evolve, as cross-platform identity portability becomes the decisive factor for developer allegiance and user retention economics.
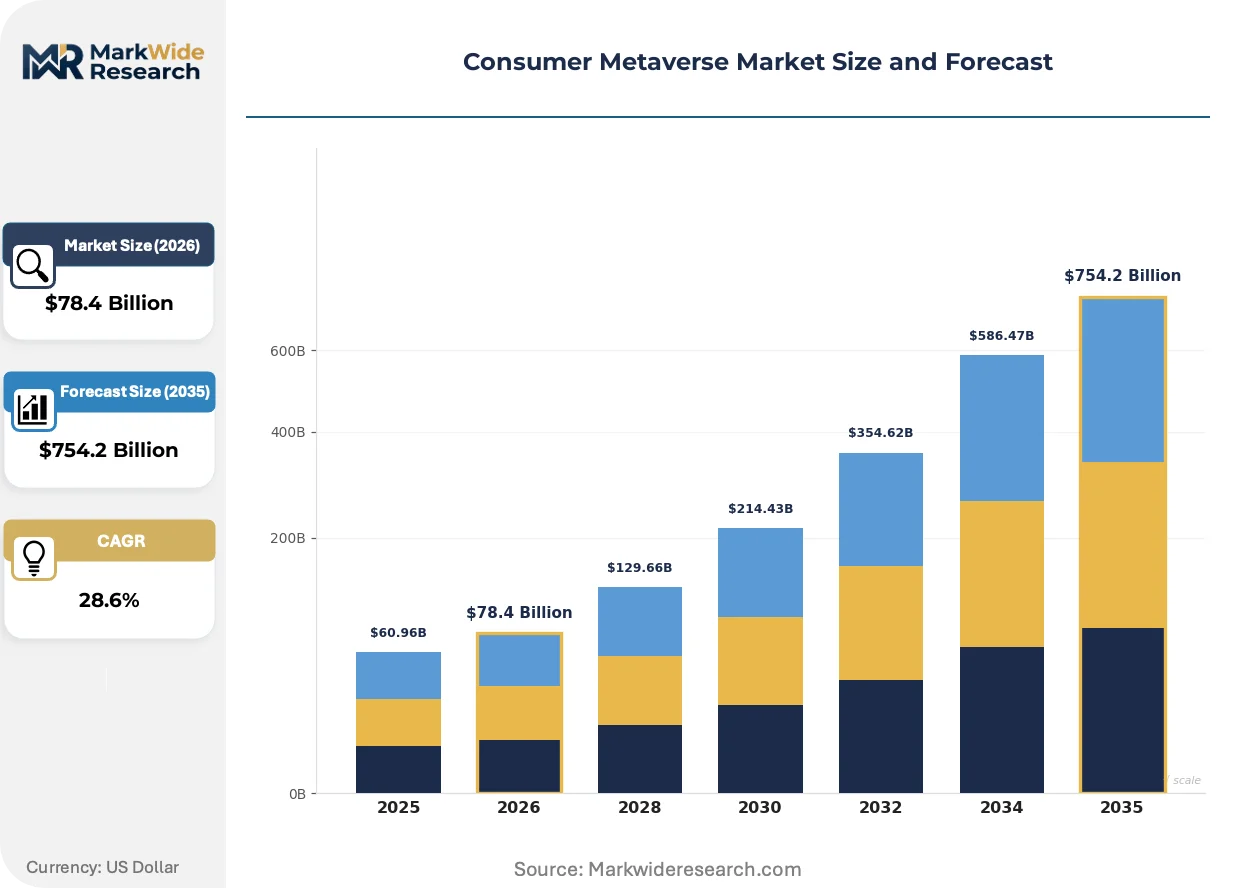
Market Dynamics
Latency compression below 20 milliseconds and photogrammetric rendering fidelity are restructuring competitive advantage around infrastructure density rather than content volume alone.
Growth Catalysts
- EU AI Act transparency mandates:Avatar-generation algorithm disclosures are accelerating trust architecture investments across European deployments.
- Photogrammetric showroom adoption:Luxury retail houses are deploying spatial commerce infrastructure that drives hardware upgrade cycles.
- FCC broadband mapping:Federal infrastructure classification is directing fiber deployment capital toward edge computing nodes essential for real-time rendering.
Market Restraints
- GPU supply concentration:Taiwan-based foundry capacity constraints create input volatility for headset and server manufacturers.
- GDPR data-localization:European hosting requirements fragment infrastructure economics and duplicate capital expenditure across jurisdictions.
- Substitution from flat-screen streaming:High-fidelity 2D gaming platforms capture discretionary entertainment hours at lower hardware cost.
Strategic Opportunities
- India PLI scheme for electronics:Domestic manufacturing incentives reduce import dependency for headset assembly and component sourcing.
- AI-driven natural-language avatars:Convergence of large language models with spatial audio enables persistent conversational agents in virtual environments.
- Creator revenue-sharing channels:User-generated content marketplaces represent underpenetrated monetization infrastructure outside gaming-centric platforms.
Industry Challenges
- Spatial audio engineering talent:Acoustic simulation expertise scarcity constrains development timelines for immersive social features.
- Interoperability standardization delays:Walled-garden identity systems fragment user asset portability and developer allegiance economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Metaverse Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $754.2 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Social Interaction, Virtual Shopping, Gaming Experiences, Collaborative Workspaces Technology: Augmented Reality, Virtual Reality, Blockchain, AI-Driven Avatars Content Type: User-Generated Content, Educational Materials, Promotional Experiences, Digital Art End User: Individuals, Brands, Educators, Artists |
| Companies Covered | Meta Platforms, Roblox Corporation, Epic Games, Microsoft, Apple, Unity Technologies, NVIDIA, Animoca Brands, Niantic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Metaverse Market Strategic Shifts
Generative systems and regulatory transparency requirements are compressing content production cycles while fragmenting platform control over user identity and asset ownership.
AI-driven avatar generation is automating the creation of personalized 3D representations from 2D inputs, reducing production costs for individual users and small creators. Casual content producers are adopting these tools at accelerating velocity, collapsing the distinction between consumer and creator economies. This automation is compressing the premium that professional design services previously commanded for custom avatar assets.
The EU AI Act imposes explicit disclosure obligations on synthetic media generation, forcing platform operators to watermark AI-created avatar content and document training data provenance. European deployments must now embed provenance tracking into rendering pipelines, increasing compliance engineering headcount. Avatar-heavy social applications face the steepest adaptation costs as they retrofit existing content libraries for auditability.
Battle-pass monetization models are displacing upfront software purchases across immersive gaming experiences, binding user retention to seasonal content cadence rather than discrete product releases. Platform operators are unbundling cosmetic economies from core gameplay access, capturing recurring revenue from engaged cohorts. This shift is most visible in United States and South Korean markets where mobile payment infrastructure supports micro-transaction velocity.
Consumer Metaverse Market Segmentation
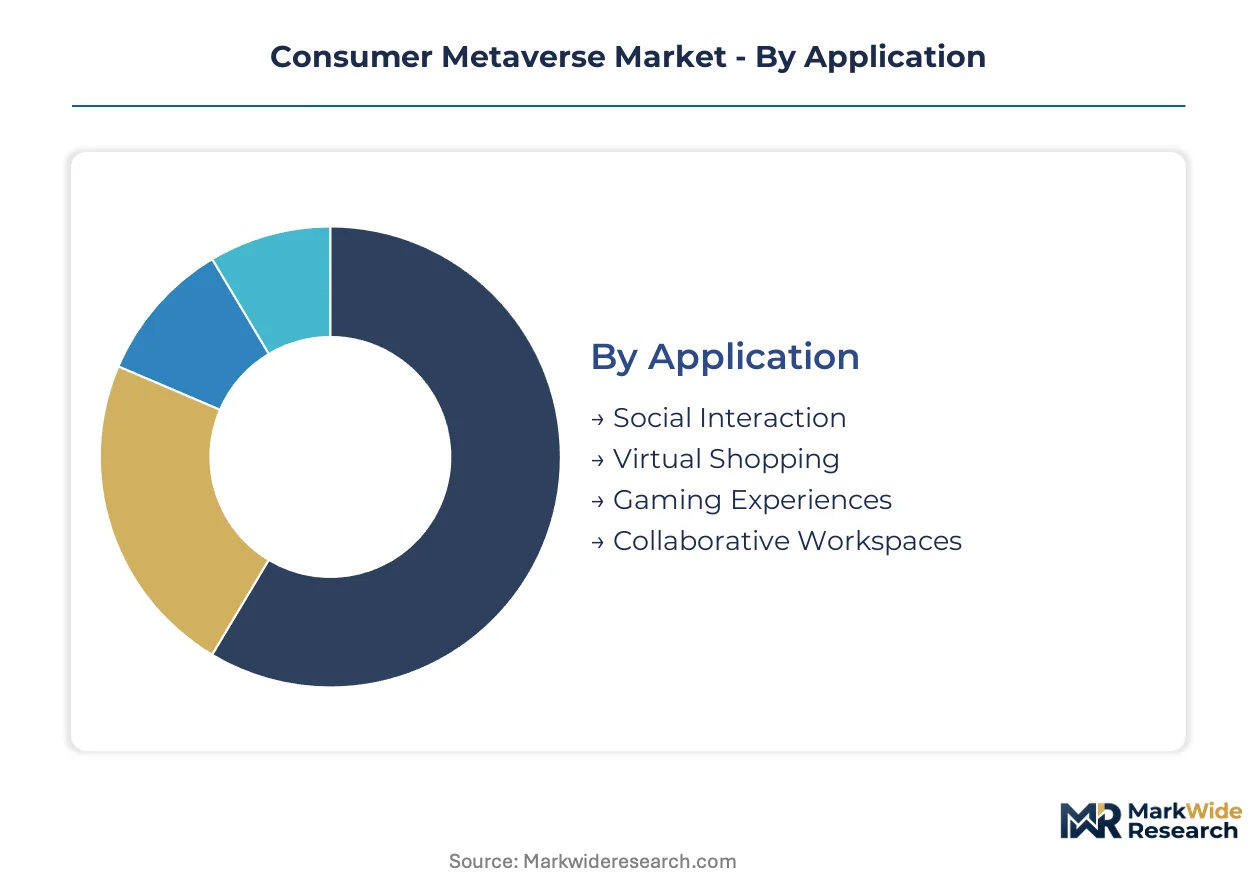
Consumer metaverse segmentation reveals divergent capital requirements across technology stacks and application layers. Infrastructure-heavy segments demand sustained investment in edge computing and rendering pipelines, while content-centric categories prioritize creator tooling over fixed assets.
Application:
Gaming Experiences and Virtual Shopping impose the heaviest upfront infrastructure burdens, requiring sub-20ms latency architecture and photogrammetric rendering systems that strain capital deployment timelines.
- Gaming Experiences:Persistent virtual worlds with real-time avatar interaction and spatial audio synchronization. Demand clusters in the United States and South Korea where battle-pass monetization and mobile payment velocity sustain recurring revenue models.
- Virtual Shopping:Photogrammetric showrooms enabling spatial commerce for luxury retail houses. European luxury brands are driving hardware upgrade cycles through fidelity requirements that exceed current consumer headset specifications.
- Social Interaction:Avatar-based communication platforms leveraging existing social graphs.
- Collaborative Workspaces:Shared virtual environments for distributed team presence.
Gaming Experiences absorbs the bulk of installed capacity; Virtual Shopping is expanding most quickly.
Technology:
Virtual Reality and AI-Driven Avatars command the steepest R&D expenditure trajectories, blending hardware miniaturization with generative model training costs that reshape competitive economics.
- Virtual Reality:Headset-dependent immersion requiring custom optics, tracking systems, and thermal management. Taiwan-based foundry capacity constraints create input volatility for original equipment manufacturers.
- AI-Driven Avatars:Large language model integration with spatial audio for natural-language interaction layers. EU AI Act transparency mandates force watermarking infrastructure and training data provenance documentation.
- Augmented Reality:Optical see-through displays overlaying digital content on physical environments.
- Blockchain:Distributed ledger infrastructure for digital scarcity claims and asset ownership verification.
Virtual Reality captures dominant capital deployment; AI-Driven Avatars is climbing the fastest as compliance engineering and generative capabilities converge.
Content Type:
User-Generated Content and Digital Art exhibit opposing margin structures, with creator economies scaling through revenue-sharing mechanisms while scarce digital assets command premium valuations.
- User-Generated Content:Creator-produced virtual assets and experiences distributed through platform marketplaces. Roblox Corporation's revenue-sharing mechanisms sustain volume outside gaming-centric platforms.
- Digital Art:Blockchain-verified scarce assets including collectibles and generative works. Speculative trading activity concentrates in United States and South Korean exchange venues.
- Educational Materials:Structured learning content delivered through immersive spatial environments.
- Promotional Experiences:Brand-commissioned activations leveraging Unreal Engine fidelity standards.
User-Generated Content dominates platform hours; Digital Art is gaining share fastest among monetization infrastructure investments.
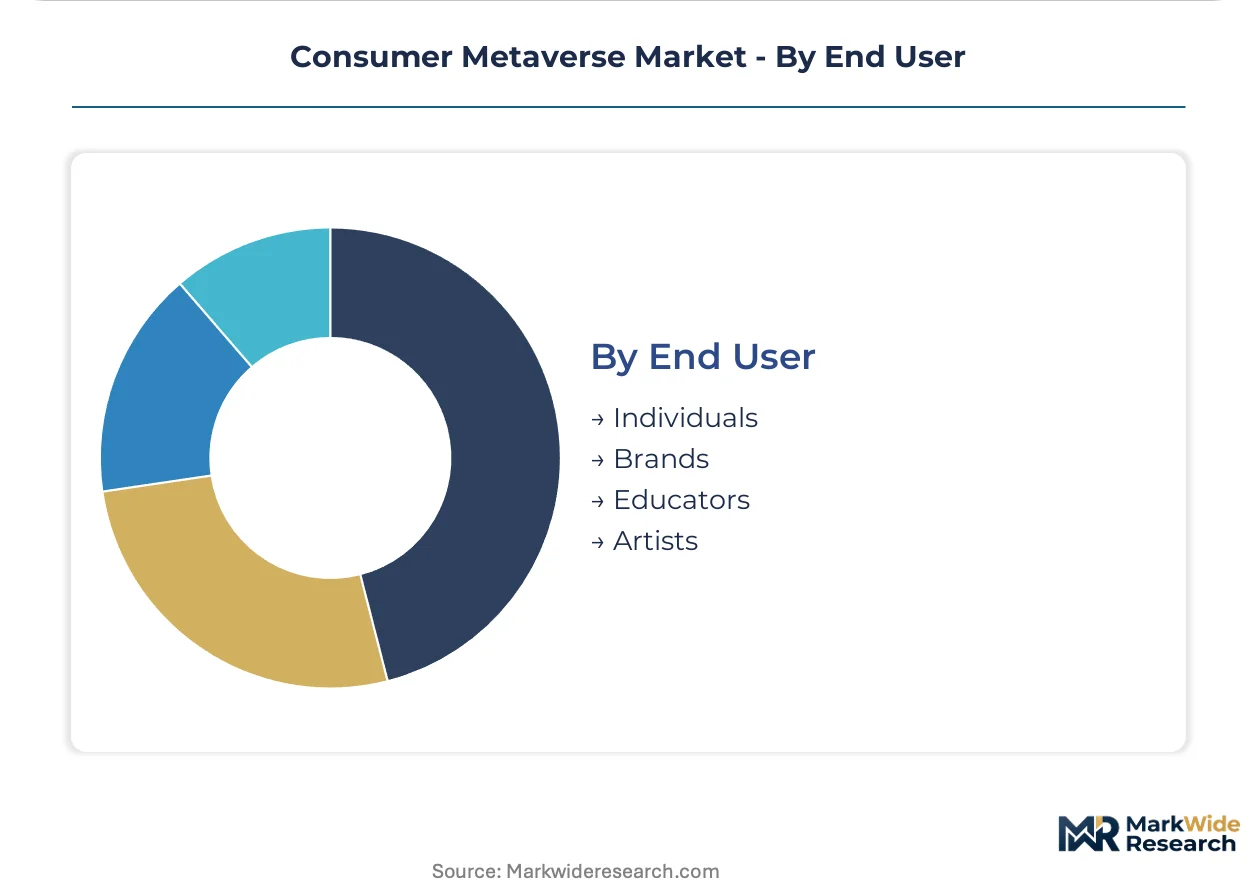
End User:
Individuals and Brands present contrasting acquisition economics, with consumer segments prioritizing hardware accessibility and enterprise deployments demanding custom integration services.
- Individuals:Avatar-based consumers spending on virtual goods and immersive experiences. Younger demographics and casual creators are realigning platform monetization toward micro-transaction economies.
- Brands:Luxury houses and consumer goods companies deploying photogrammetric showrooms and promotional activations. Premium brand activations cluster where Unreal Engine fidelity standards attract marketing expenditure.
- Educators:Institutions deploying structured learning content in persistent virtual environments.
- Artists:Creators producing blockchain-verified digital art and generative works.
Individuals account for the majority of transaction volume; Brands is expanding most quickly as spatial commerce infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households generate the highest per-capita spending on virtual goods and immersive hardware, concentrating platform monetization experiments and creator economy infrastructure in North American markets.
United States
FCC broadband mapping mandates direct fiber deployment capital toward edge computing nodes essential for sub-20ms latency rendering. Meta Platforms anchors hardware-software ecosystem development through its social graph infrastructure, while Apple drives headset specification upgrades through its Silicon Valley design centers.
South Korea
Mobile payment velocity sustains battle-pass monetization models across gaming platforms with exceptional transaction frequency. MFDS regulates extended reality medical applications that spill over into consumer avatar health monitoring features. Seoul Capital Area hosts the densest concentration of spatial audio engineering talent outside North America.
Germany
Automotive industrial applications for digital twin technology create spillover demand for photogrammetric rendering expertise. GDPR data-localization requirements fragment hosting economics and duplicate capital expenditure across European jurisdictions. Bavaria's Munich cluster anchors Unreal Engine fidelity deployments for premium brand activations.
United Kingdom
Financial services experimentation with persistent virtual environments drives enterprise-to-consumer technology transfer. The Information Commissioner's Office enforces GDPR-derived avatar data processing standards that shape platform architecture. London's creative sector concentrates promotional experience production for luxury retail houses.
India
Younger demographic penetration and casual creator adoption realign platform strategies toward micro-transaction economies at lower price points. The PLI scheme for electronics manufacturing reduces import dependency for headset assembly and component sourcing. Karnataka's Bangalore cluster hosts the fastest-growing volume of user-generated content marketplace development outside established gaming platforms.
Consumer Metaverse Market Competitive Environment
United States producers anchor one tier through social graph infrastructure and hardware-software integration; Asian specialists hold concentrated positions in component manufacturing and mobile-first platform economics. The market structure consolidates around three to five ecosystem orchestrators with substantial captive user bases. Strategic archetypes include social graph leverage platforms, creator revenue-sharing engines, and rendering fidelity standard-setters. Competitive moves concentrate on interoperability coalition-building and exclusive content licensing arrangements.
Within the social graph leverage tier, Meta Platforms exemplifies infrastructure-heavy ecosystem control. Roblox Corporation occupies a position defined by creator revenue-sharing mechanisms that sustain user-generated content volume. Epic Games anchors the rendering fidelity vector through engine standard-setting that attracts premium brand marketing expenditure. These three entities collectively represent the dominant competitive archetypes shaping platform allegiance economics.
| Leading Market Players |
|---|
| Meta Platforms |
| Roblox Corporation |
| Epic Games |
| Microsoft |
| Apple |
| Unity Technologies |
| NVIDIA |
| Animoca Brands |
| Niantic |
| Others |
Value Chain & Pricing Dynamics
Luxury retail photogrammetric fidelity requirements are forcing headset manufacturers toward custom optics and thermal management solutions that compress margins across component tiers. Taiwan-based foundry capacity constraints for GPU and SoC production amplify input cost volatility, pushing original equipment manufacturers toward long-term foundry allocation contracts that lock in pricing floors.
Pricing Analysis
Volume concentration in battle-pass gaming economies splits margin capture between platform operators and creator revenue-sharing pools, while premium hardware tiers extract surplus from luxury brand marketing budgets. Price differentiation rests on rendering fidelity certification and spatial audio latency benchmarks rather than raw compute specifications. Cost compression in mid-tier headsets is intensifying because mobile-first platforms in South Korea and India are normalizing lower hardware entry points. Individual consumers exhibit acute price sensitivity, whereas luxury houses deploying photogrammetric showrooms prioritize fidelity over unit economics.
Supply Chain Analysis
Regional distribution centers for headset assembly concentrate in Vietnam, Mexico, and India following PLI scheme incentives that reduce import dependency for final assembly. Component sourcing draws from Taiwan for advanced semiconductors, South Korea for display panels, and China for structural materials and battery cells. Single-source vulnerability around Taiwan-based foundry capacity creates supply chain risk that platform operators mitigate through dual-sourcing qualification programs. Distribution runs through direct-to-consumer channels for hardware and platform-integrated marketplaces for virtual goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consumer metaverse sits at a technology-transition inflection where AI-driven avatar generation displaces manual 3D asset production workflows. Stakeholders must calibrate capital deployment around generative infrastructure rather than legacy content pipeline investments.
For Market Incumbents: Extend social graph infrastructure into persistent conversational agent layers that bind user retention through natural-language avatar interaction. Incumbent platforms face substitution risk from generative tools that collapse the premium on professional design services. Vertical integration into edge computing nodes secures latency architecture for photogrammetric rendering demands. For New Entrants and Emerging Players: Launch via creator revenue-sharing marketplaces that bypass gaming-centric platform saturation in the United States and South Korea. The most penetrable white space sits in India's micro-transaction economy, where younger demographics and casual creator adoption outpace infrastructure investment. A direct-to-creator tooling angle bypasses incumbent platform control over distribution. For Investors and Strategic Acquirers: The window for entry favors specialist avatar-generation engine developers with EU AI Act compliance infrastructure already embedded. Long-term viability hinges on interoperability coalition participation rather than walled-garden user capture. The decisive signal to watch is cross-platform identity standard adoption velocity among developer communities.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Coalition Formation | Cross-platform avatar portability secures developer allegiance and sustains user retention economics across Meta Platforms and Roblox Corporation ecosystems. |
| EU AI Act Compliance Infrastructure | Watermarking and provenance documentation capabilities unlock European deployment access for avatar-heavy social applications. |
| Edge Computing Node Expansion | FCC broadband-mapped fiber deployment capital enables sub-20ms latency rendering for photogrammetric showroom fidelity requirements. |
| Creator Revenue-Share Mechanism | Roblox Corporation's model demonstrates volume sustainability outside gaming-centric platforms through user-generated content marketplace economics. |
| Spatial Audio Engineering Acquisition | Talent scarcity in acoustic simulation constrains immersive social feature timelines, making specialist firms attractive consolidation targets. |
Study Parameters
Independent corroboration across platform operator disclosures, semiconductor foundry production reports, and regulatory filing databases underwrites the qualitative findings. Primary interviews with metaverse platform executives, spatial audio engineering leads, luxury brand digital officers, and edge computing infrastructure planners combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory transparency repositories. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume estimates.
Comparable-period anchoring to installed base penetration rates and hardware shipment trajectories structured the forecast window across the projection horizon. Segmentation dimensions modeled include application layer, technology stack, content type, and end-user archetype alongside regional regulatory cluster differentiation. CAGRs derived from cohort retention analysis and monetization velocity curves incorporated battle-pass transaction frequency and virtual goods spending patterns as industry-specific inputs.
GPU supply concentration, EU AI Act implementation delays, and substitution acceleration from flat-screen streaming platforms are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumption sets regarding interoperability standard adoption and foundry capacity expansion timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality (XR) Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market