
 North America Augmented Reality Market | 2026-2036
North America Augmented Reality Market Size, Share, and Industry Trends Forecast 2026-2036
North America Augmented Reality Market Analytics
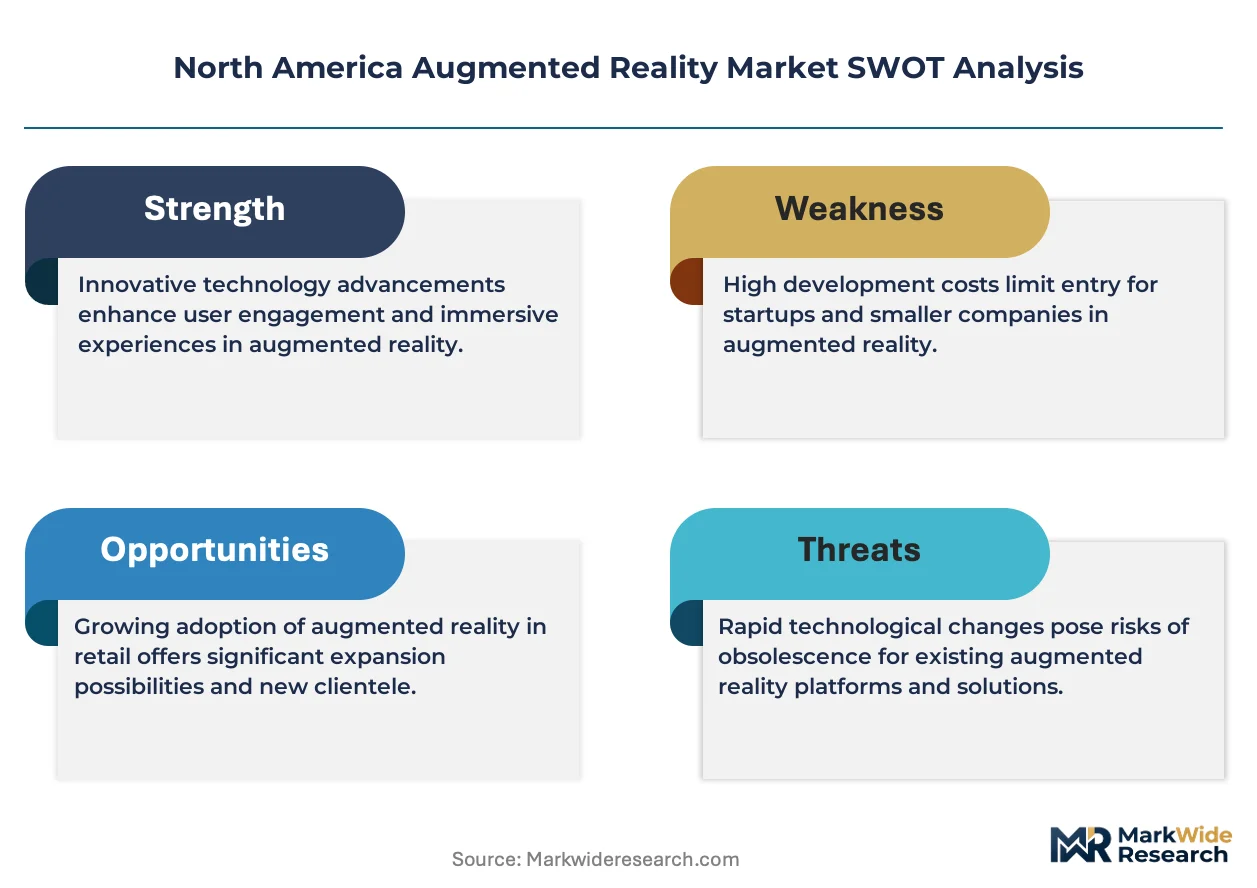
Enterprise-grade spatial computing is collapsing the cost barrier between pilot AR programs and full-scale operational deployment. Microsoft Corporation leverages its Azure cloud backbone to anchor industrial metaverse applications across automotive and aerospace supply chains. Meta Platforms, Inc. competes through vertical integration of its Quest hardware stack with Horizon Workrooms collaboration software. Magic Leap, Inc. specializes in medical-grade optics, sustaining premium positioning among surgeons and radiologists who require sub-millimeter registration accuracy.
Augmented Reality in North America overlays computer-generated imagery, spatial audio, and haptic feedback onto the physical environment through see-through displays with field-of-view parameters typically ranging from 40 to 110 degrees. The technology serves industrial maintenance, surgical navigation, and immersive commerce by registering virtual objects to real-world coordinate systems via simultaneous localization and mapping algorithms. Headsets command the highest hardware margins while smartphones retain the largest installed base for consumer-facing applications. Markerless tracking is displacing marker-based systems in enterprise settings where physical fiducial placement proves impractical. Gaming applications mature fastest in revenue terms though healthcare providers represent the most defensible long-term customer segment due to reimbursement pathways and clinical validation requirements.
FCC Part 15 rules govern unlicensed radio emissions from AR wearables, while FDA 510(k) clearance requirements constrain medical visualization software marketed for diagnostic or surgical use. OSHA standards for workplace eye protection intersect with ANSI Z87.1 certification for industrial smart glasses deployed in manufacturing environments. Stakeholders must monitor how NHTSA distracted-driving guidelines evolve as automakers integrate AR head-up displays into vehicle platforms, since regulatory ambiguity around driver attention partitioning could accelerate or constrain automotive adoption independently of technical readiness.
Market Dynamics
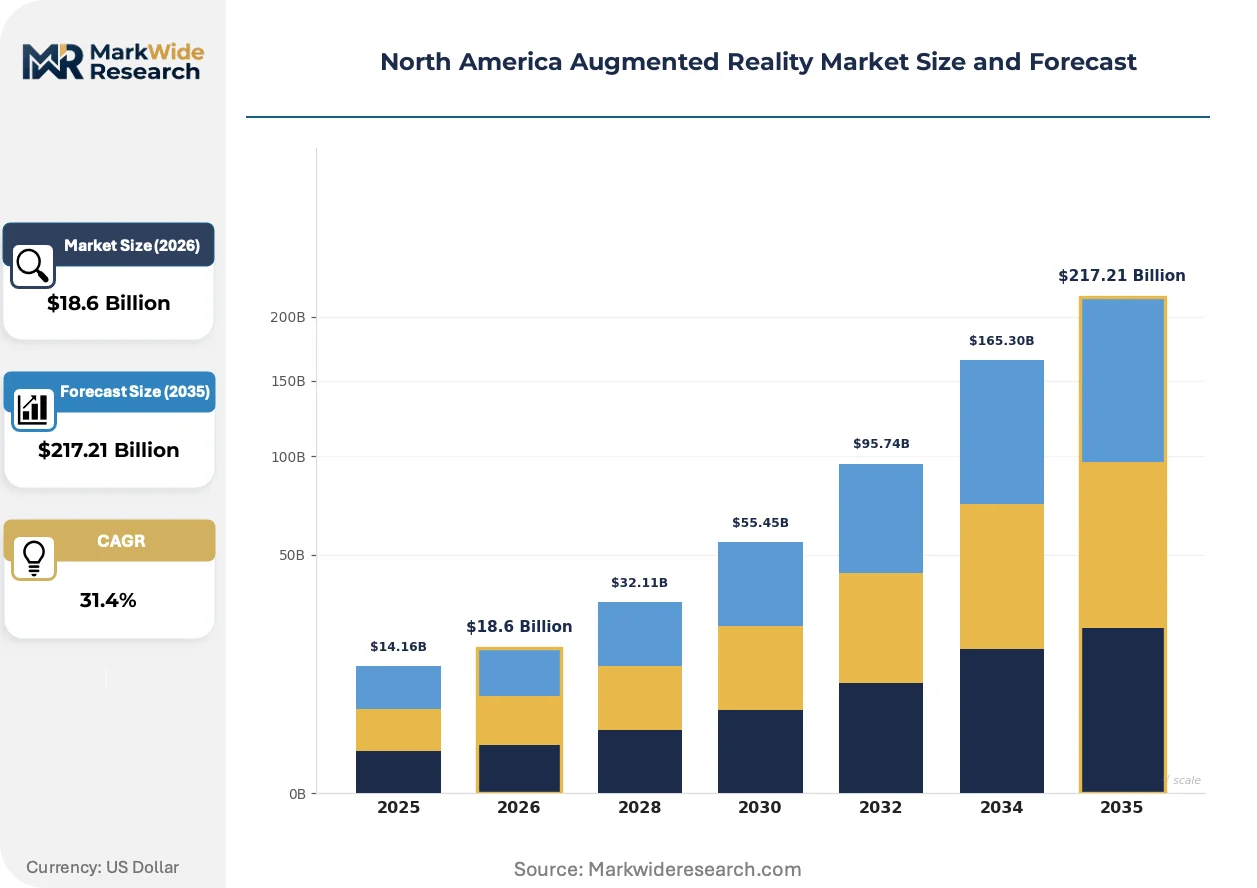
Enterprise spatial computing is compressing deployment timelines from pilot to production as FCC mmWave allocations and FDA surgical guidance create dual regulatory tailwinds for industrial and medical AR applications across the United States and Canada.
Growth Catalysts
- FCC Part 15 unlicensed spectrum:New mmWave band allocations enable low-latency wireless AR streaming in factory floors and logistics hubs without licensed infrastructure costs.
- FDA 510(k) surgical visualization pathway:Streamlined clearance for AR-enabled navigation systems accelerates hospital procurement cycles among radiologists and orthopedic surgeons.
- California-Texas-Ontario demand cluster:Technology corridor concentration creates dense beta-testing environments that compress product iteration cycles.
Market Restraints
- Waveguide display supply concentration:Precision optical component manufacturing concentrates among specialized Asian suppliers, creating input bottlenecks for North American headset assemblers.
- OSHA-ANSI Z87.1 dual certification costs:Industrial smart glasses require simultaneous workplace safety and eye protection compliance, extending time-to-market by 8-14 months.
- Smartphone AR substitution:Markerless tracking on iOS and Android devices satisfies basic enterprise visualization needs at fraction of dedicated hardware cost.
Strategic Opportunities
- Underpenetrated Canadian healthcare:Ontario's surgical innovation cluster lacks scaled AR deployment compared to US hospital networks, creating first-mover whitespace.
- NHTSA automotive HUD mandate trajectory:Evolving distracted-driving guidelines will likely embed AR displays as standard safety equipment, opening OEM integration contracts.
- 5G-Edge convergence:Low-latency rendering offload to Azure and AWS edge nodes enables lighter headset designs without sacrificing visual fidelity.
Industry Challenges
- Spatial computing talent scarcity:Simultaneous localization and mapping engineers command premium compensation, constraining development velocity for mid-tier vendors.
- Legacy manufacturing system integration:AR maintenance overlays require real-time PLC and SCADA data feeds that expose cybersecurity vulnerabilities in brownfield facilities.
- Cross-jurisdictional certification fragmentation:Health Canada PMRA and FDA maintain divergent clinical evidence standards for surgical AR, forcing dual-track validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Augmented Reality Market |
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $217.21 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Healthcare, Education, Retail, Gaming Technology: Marker-Based, Markerless, Projection-Based, Superimposition-Based Device Type: Smartphones, Tablets, Headsets, Smart Glasses End User: Consumers, Enterprises, Government, Healthcare Providers |
| Companies Covered | Microsoft Corporation, Meta Platforms, Inc., Google LLC, Apple Inc., Magic Leap, Inc., Unity Technologies, Snap Inc., Niantic, Inc., Qualcomm Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Augmented Reality Market Evolving Landscape
Optical waveguide architectures and cloud-edge rendering topologies are actively redrawing competitive boundaries between premium enterprise headsets and smartphone-dependent AR experiences.
Waveguide combiner technology is bifurcating the hardware tier. Surface-relief gratings deliver 50-degree fields-of-view for industrial maintenance crews at sub-$1,500 price points. Volume holographic optics command $3,000-plus price tags among surgeons demanding 110-degree immersion. The technology split is compressing mid-market vendor margins as buyers polarize toward adequate visualization or clinical-grade precision.
FDA 510(k) premarket notification requirements are tightening evidentiary standards for AR surgical navigation. The agency now demands prospective clinical studies demonstrating non-inferiority to conventional imaging for specific procedures. Orthopedic spine applications face the steepest compliance burden, while radiological visualization maintains grandfathered predicate pathways.
Enterprise procurement is consolidating around outcome-based service contracts. Automotive manufacturers now contract for uptime-guaranteed AR maintenance systems rather than capital hardware purchases. Tier-1 suppliers bundle headset fleets with predictive analytics subscriptions, shifting revenue recognition from unit sales to recurring service fees. This pattern concentrates in Michigan and Ohio assembly plant networks.
North America Augmented Reality Market Segmentation
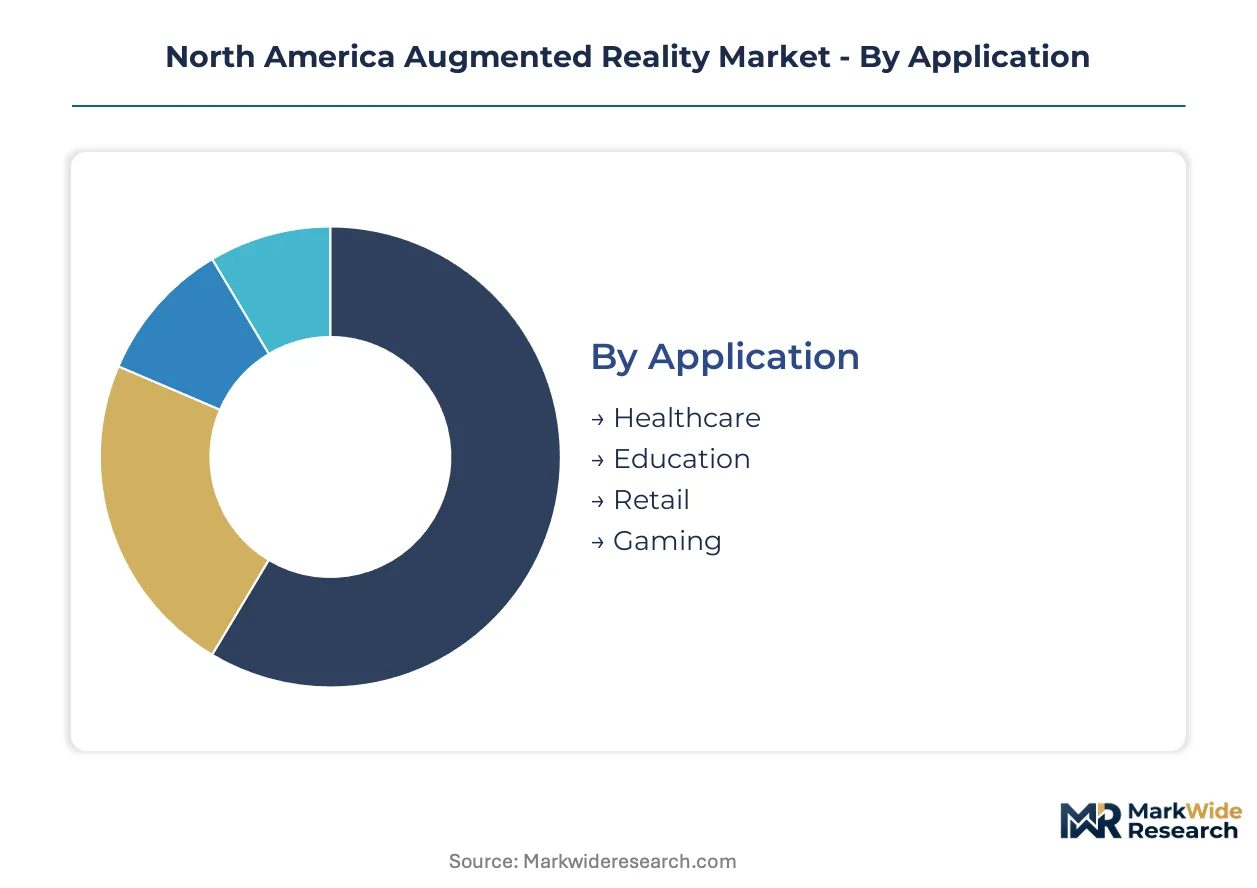
AR deployment patterns diverge sharply across North America based on regulatory intensity and reimbursement pathways. FDA clearance timelines and FCC spectrum rules create tiered adoption curves that segment vendors must navigate with distinct commercial strategies.
Application:
FDA 510(k) pathways and HIPAA compliance requirements fragment commercial viability across verticals, with medical applications facing steeper validation burdens than consumer-facing deployments.
- Healthcare:Surgical navigation and radiological visualization systems require FDA 510(k) premarket notification with prospective clinical studies demonstrating non-inferiority to conventional imaging. Orthopedic spine applications face the steepest compliance burden in California and Texas hospital networks.
- Education:K-12 and higher education deployments concentrate in Ontario's innovation corridor and California's technology districts, driven by NSF and Canadian federal research grants rather than regulatory clearance.
- Retail:Virtual try-on and spatial commerce applications bypass FDA oversight entirely, scaling through direct-to-consumer app store distribution with lower capital barriers.
- Gaming:Entertainment AR matures fastest in revenue terms through smartphone-based distribution, though premium headset experiences retain higher per-user monetization in urban Canadian and US markets.
Healthcare handles the majority of high-margin enterprise throughput; Gaming is the fastest mover on volume share.
Technology:
Cost tier differentiation separates enterprise-grade spatial computing from consumer accessibility, with hardware BOM variance exceeding 400% between premium and entry-level tracking architectures.
- Marker-Based:Fiducial-dependent registration systems dominate legacy industrial maintenance workflows in Michigan and Ohio automotive plants where controlled environments permit physical marker placement.
- Markerless:SLAM-based simultaneous localization and mapping algorithms command premium engineering talent costs, displacing marker systems in brownfield logistics hubs across Texas and Ontario where physical infrastructure modification proves impractical.
- Projection-Based:Spatial light projection systems serve niche manufacturing quality assurance applications with high ambient light tolerance requirements.
- Superimposition-Based:Object recognition overlays concentrate in retail and automotive HUD prototyping where real-time environmental parsing replaces geometric fiducial dependency.
Markerless systems absorb the majority of new capital deployment; Projection-Based retains defensive positioning in specialized industrial niches.
Device Type:
Margin structure inverts between installed base scale and per-unit profitability, with smartphones capturing volume while headsets defend hardware margins through optical component differentiation.
- Smartphones:iOS and Android ARKit/ARCore deployments retain the largest installed base for consumer and basic enterprise visualization, though per-session engagement metrics trail dedicated hardware significantly.
- Tablets:Larger form factors serve field service technicians in Texas energy corridors and California utility networks where screen real estate outweighs hands-free requirements.
- Headsets:Premium waveguide optics command $3,000-plus price points among surgeons demanding 110-degree immersion, with volume holographic architectures sustaining Magic Leap and Microsoft medical-grade positioning.
- Smart Glasses:Industrial deployments require simultaneous OSHA workplace safety and ANSI Z87.1 eye protection certification, extending time-to-market by 8-14 months for manufacturing floor applications.
Smartphones handle the majority of consumer throughput; Headsets are expanding most quickly in enterprise medical procurement.
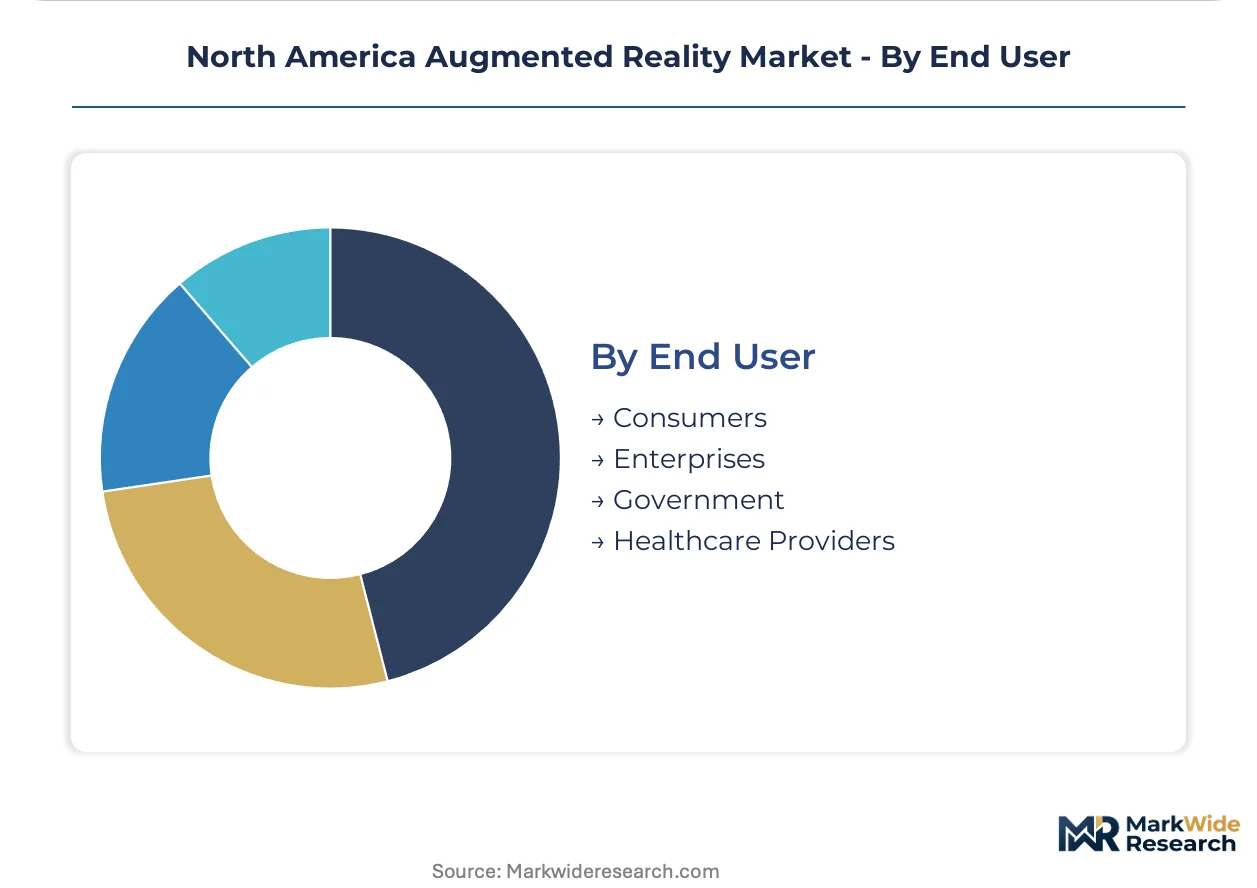
End User:
Customer procurement patterns split between outcome-based service contracts in automotive and capital hardware purchases in government verticals, reshaping vendor revenue recognition models.
- Consumers:Direct app store distribution and gaming hardware purchases dominate volume, with Quest and smartphone AR satisfying price-sensitive entertainment demand.
- Enterprises:Michigan and Ohio automotive manufacturers now contract for uptime-guaranteed AR maintenance systems rather than capital hardware purchases, shifting vendor revenue to recurring service fees.
- Government:Defense and municipal procurement cycles favor established contractors with FedRAMP and CMMC compliance, creating barriers for emerging spatial computing vendors.
- Healthcare Providers:Hospital networks in California, Texas, and Ontario concentrate purchasing power through group purchasing organizations, consolidating vendor selection around FDA-cleared platforms with established reimbursement pathways.
Enterprises drive the majority of new contract value; Healthcare Providers are climbing the fastest on procurement sophistication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in AR software licensing and optical component design, while importing precision waveguide substrates from specialized Asian foundries. Canada and Mexico concentrate on hardware assembly and cross-border logistics integration for enterprise headset deployment.
United States
FCC Part 15 unlicensed mmWave allocations enable factory-floor AR streaming without licensed infrastructure costs. FDA 510(k) pathways for surgical visualization systems accelerate hospital procurement among California and Texas medical networks. The San Francisco Bay Area and Austin technology corridors host dense beta-testing environments that compress product iteration cycles for industrial metaverse applications.
Canada
Health Canada PMRA maintains divergent clinical evidence standards from FDA, forcing dual-track validation studies for surgical AR vendors. Ontario's healthcare innovation cluster lacks scaled deployment compared to US hospital networks, creating first-mover whitespace for medical-grade headset vendors. Toronto and Waterloo anchor enterprise pilot programs in manufacturing and logistics sectors.
Mexico
Maquiladora assembly plants in Baja California and Chihuahua integrate AR maintenance overlays for automotive supply chain quality assurance. Mexican federal technology incentives support hardware manufacturing investments near the US border. Mexico City hosts growing software development talent pools serving Spanish-language enterprise AR applications.
North America Augmented Reality Market Competitive Landscape
Concentration sits with cloud-integrated platform providers and specialized medical optics fabricators. The vendor base stratifies across three tiers: hyperscale cloud anchors with hardware-software stacks, premium medical-grade specialists, and component suppliers licensing silicon and tracking algorithms. Strategic moves center on outcome-based service contract structuring and edge rendering partnerships with telecommunications carriers.
Within the cloud-integrated tier, Microsoft Corporation and Meta Platforms, Inc. exemplify divergent positioning—one anchoring industrial metaverse applications through Azure backbone integration, the other pursuing vertical control of consumer and enterprise hardware-software stacks. Magic Leap, Inc. occupies the medical-grade specialist position, sustaining premium pricing among surgical applications requiring sub-millimeter registration accuracy.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Meta Platforms, Inc. |
| Google LLC |
| Apple Inc. |
| Magic Leap, Inc. |
| Unity Technologies |
| Snap Inc. |
| Niantic, Inc. |
| Qualcomm Incorporated |
| Others |
Value Network & Pricing Analysis
FDA 510(k) certification tiers and OSHA-ANSI Z87.1 dual compliance requirements gate both supplier qualification and price stratification across medical and industrial AR headset segments. These regulatory thresholds create non-linear cost jumps that separate qualified vendors from price-competitive aspirants.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with volume holographic optics commanding $3,000-plus price points among surgeons while surface-relief gratings serve factory floors below $1,500. Price differentiation rests on certification grade and optical field-of-view performance. Margins are tightening due to smartphone AR substitution for basic enterprise visualization. Healthcare providers demonstrate lowest price sensitivity given reimbursement pathways, while logistics operators in Texas and Ontario exhibit highest sensitivity to per-unit hardware costs.
Supply Chain Analysis
Strategic stockpiling of precision waveguide substrates dominates procurement strategy among North American headset assemblers facing extended lead times from specialized Asian foundries. Component manufacturing concentrates in Taiwan, South Korea, and Japan for optical combiners and microdisplays. Raw material dependencies include rare-earth phosphors, high-index glass substrates, and semiconductor-grade silicon photonics. Single-source vulnerability concentrates in volume holographic optics fabrication. Distribution runs through Tier-1 automotive suppliers bundling headset fleets with predictive analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise spatial computing is entering a cyclical recovery phase as FCC mmWave allocations and FDA surgical guidance create dual regulatory tailwinds that compress deployment timelines from pilot to production.
For Market Incumbents: Shield market position through backward integration into optical waveguide fabrication and captive supply of precision components from Asian foundries. Accelerate certification investment for Health Canada PMRA dual-track validation to preempt emerging entrants in Ontario's healthcare cluster. Prioritize channel control through outcome-based service contracts that shift automotive OEM procurement toward recurring revenue models. For New Entrants and Emerging Players: Differentiate on Canadian healthcare whitespace where scaled AR deployment lags US hospital networks. Target Ontario's surgical innovation cluster with medical-grade optics offerings that bypass established vendor relationships in California and Texas. Pursue direct-to-hospital sales bypassing group purchasing organization consolidation through specialized clinical training partnerships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade headset manufacturing as FDA evidentiary standards tighten for orthopedic spine applications. Long-term viability favors acquisition targets with established 510(k) predicate pathways and reimbursement relationships. Watch for inflection when NHTSA distracted-driving guidelines crystallize into automotive HUD mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Rendering Partnership | Azure and AWS node integration enables lighter headset designs without sacrificing visual fidelity. |
| Dual Certification Investment | Simultaneous FDA 510(k) and Health Canada PMRA clearance opens underpenetrated Canadian surgical markets. |
| Optical Component Backward Integration | Captive waveguide supply reduces dependency on concentrated Asian foundry capacity. |
| Outcome-Based Service Contracting | Uptime-guaranteed AR maintenance systems shift Michigan and Ohio automotive procurement to recurring fees. |
| SLAM Engineering Talent Acquisition | Scarce simultaneous localization and mapping expertise commands premium compensation and constrains development velocity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, FCC spectrum allocation filings, and hospital procurement records. Primary interviews engaged AR hardware engineering directors, healthcare GPO contracts managers, automotive Tier-1 supplier procurement leads, and industrial safety compliance officers. Secondary sources encompassed SEC 10-K filings from cloud platform providers, Health Canada PMRA device licensing data, and customs trade records for optical component imports. Bottom-up unit shipment estimates triangulate against top-down enterprise IT spending allocations across the analysis window.
Segmentation dimensions modeled include application vertical, technology architecture, device type, and end-user procurement pattern across the projection horizon. CAGRs derive from regression analysis against enterprise software spending growth and healthcare capital equipment replacement cycles. Industry-specific forecast inputs incorporate FCC mmWave deployment timelines and FDA surgical navigation clearance velocity.
The analysis sits within stated boundaries; outcomes outside sustained regulatory clarity for automotive HUD applications would require recalibration. Forecasts reflect assumptions around reimbursement pathway stability for surgical AR and continued hyperscaler edge infrastructure investment. Revision becomes warranted when Health Canada-FDA regulatory divergence crosses thresholds that fragment North American certification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market