
 Canada Metaverse Market | 2026-2036
Canada Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Metaverse Market Insights
CRTC broadband infrastructure mandates are expanding the cost-of-entry calculus for domestic metaverse operators seeking low-latency distribution. Visualhawk Solutions Inc. leverages its Toronto-based development footprint to anchor enterprise VR deployments across Ontario's manufacturing sector. MetaVRse Inc. competes through web-native 3D commerce tools that reduce hardware dependency for mid-market retailers. Autodesk sustains its position via deep integration between Revit workflows and immersive visualization pipelines for architecture and engineering clients.
The Canada metaverse comprises persistent, interconnected virtual environments rendered through real-time 3D engines, spatial computing interfaces, and distributed ledger authentication protocols, serving industrial simulation, remote collaboration, and digital commerce functions. VR technology dominates current enterprise training budgets, while blockchain-based asset verification represents the fastest-growing infrastructure layer as Canadian financial institutions pilot tokenized settlement mechanisms. Gaming applications command the largest installed base of consumer headsets, though healthcare applications—particularly surgical planning and therapeutic interventions—now attract the deepest margin pools from institutional procurement cycles.
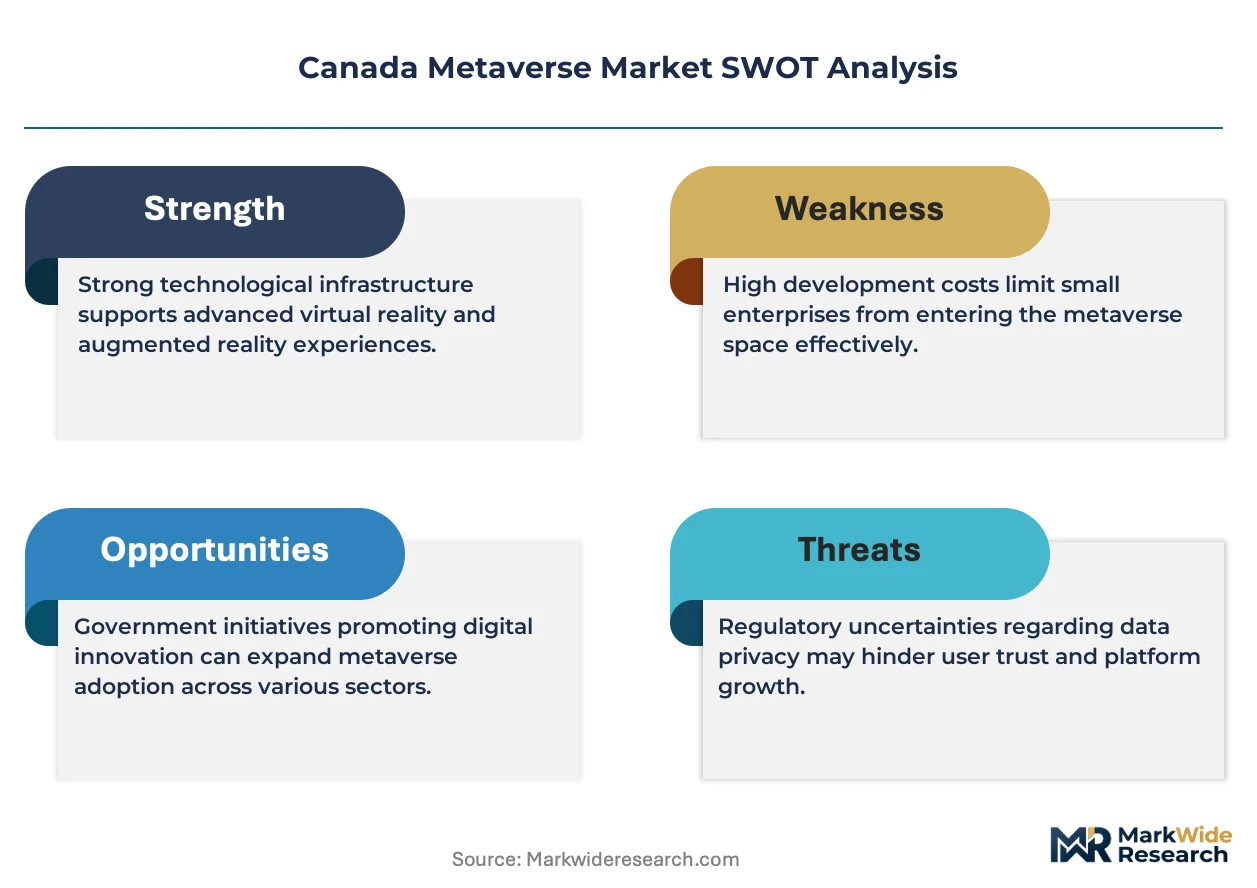
Health Canada regulates medical device classifications for VR therapeutic systems, while the CRTC governs network neutrality provisions affecting cloud-rendered streaming quality, and the Office of the Privacy Commissioner enforces PIPEDA compliance for biometric data harvested through facial tracking interfaces. These overlapping frameworks compel platform architects to embed privacy-by-design architectures and clinical validation pathways from initial product conception. Stakeholders must monitor forthcoming federal artificial intelligence legislation for provisions that could reclassify generative content moderation obligations across immersive social environments.
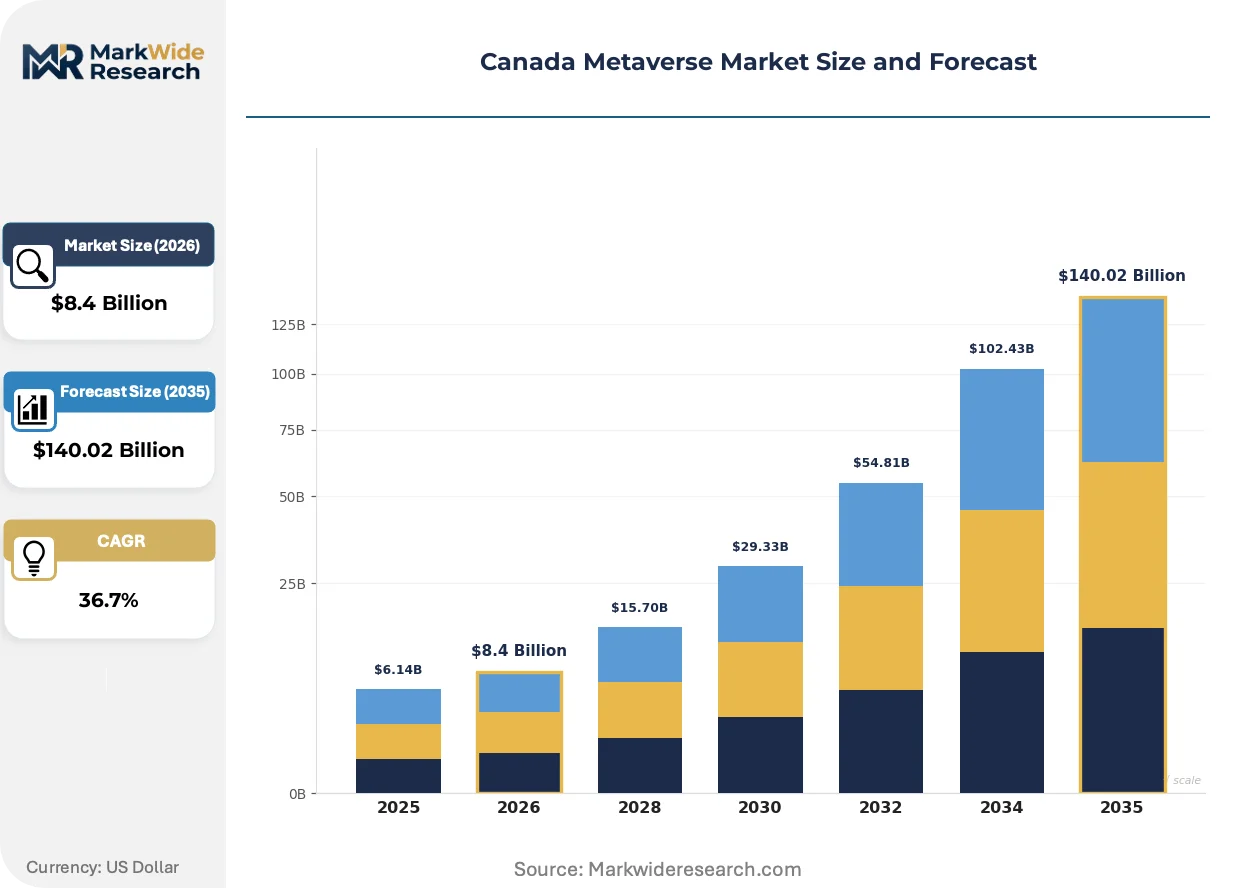
Market Dynamics
Health Canada's evolving digital health frameworks are compressing validation timelines for therapeutic VR systems while CRTC broadband mandates reshape infrastructure investment priorities for domestic operators.
Growth Catalysts
- CRTC Broadband Mandates:Low-latency network requirements are accelerating edge computing deployments for real-time 3D rendering across Ontario and Quebec.
- Healthcare Procurement Cycles:Institutional buyers in surgical planning and therapeutic interventions are expanding VR training budgets with dedicated capital allocation.
- Federal Innovation Tax Incentives:Toronto's technology corridor and Montreal's gaming cluster are capturing R&D credits that reduce effective development costs for immersive platforms.
Market Restraints
- Hardware Cost Volatility:GPU and spatial computing component pricing fluctuates with semiconductor supply chain constraints affecting headset manufacturing economics.
- Biometric Data Compliance:PIPEDA enforcement by the Office of the Privacy Commissioner imposes architectural costs for facial tracking and haptic feedback data collection.
- Clinical Validation Burden:Medical device classification requirements under Health Canada extend product development cycles for therapeutic applications.
Strategic Opportunities
- Web-Native 3D Commerce:Browser-based immersive tools reduce hardware dependency for mid-market retailers in Vancouver and Calgary metropolitan areas.
- Industrial Simulation Convergence:Integration between Revit workflows and real-time engines creates vertical penetration paths in architecture and engineering procurement.
- Provincial Education Mandates:Distributed learning infrastructure investments in British Columbia and Alberta are opening institutional VR procurement channels.
Industry Challenges
- Spatial Computing Talent Scarcity:Developer pools with Unreal Engine and Unity expertise concentrate in Toronto and Montreal, creating recruitment bottlenecks for Prairie-region operators.
- Legacy System Integration:Enterprise IT architectures require custom API development to connect immersive platforms with existing ERP and CRM systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Metaverse Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $140.02 Billion |
| CAGR (2026 – 2036) | 36.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AR, VR, Blockchain, 3D Modeling Application: Gaming, Education, Healthcare, Retail End User: Enterprises, Consumers, Developers, Content Creators Content Type: Virtual Goods, Events, Services, Experiences |
| Companies Covered | Visualhawk Solutions Inc., Zesty Market, MetaVRse Inc., Terraunity, Shift Reality, Synervoz Communications Inc., Livshows, Autodesk, ibentos INC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Metaverse Market Trends and Innovations
Real-time 3D engines are migrating toward cloud-native architectures that decouple rendering from end-user hardware capabilities. This shift is compressing total cost of ownership for enterprise deployments.
Web-native spatial computing is absorbing mid-market demand that previously required dedicated VR headsets. Browser-based 3D commerce tools from Canadian developers are capturing retail sector pilots in Vancouver and Calgary. This absorption is fragmenting hardware vendor concentration and redistributing margin pools toward software-layer providers.
Health Canada's medical device classification pathways for VR therapeutic systems are tightening clinical evidence requirements. Surgical planning applications now require prospective validation studies that extend regulatory timelines. Ontario-based healthcare technology developers are responding by embedding clinical advisory boards into product design phases.
Enterprise procurement of immersive training platforms is consolidating around subscription-based service models. Capital expenditure avoidance is displacing perpetual license purchases in manufacturing and logistics verticals. This pattern is most visible in Quebec's aerospace supply chain, where tier-one suppliers are mandating SaaS delivery for workforce simulation tools.
Canada Metaverse Market Segmentation
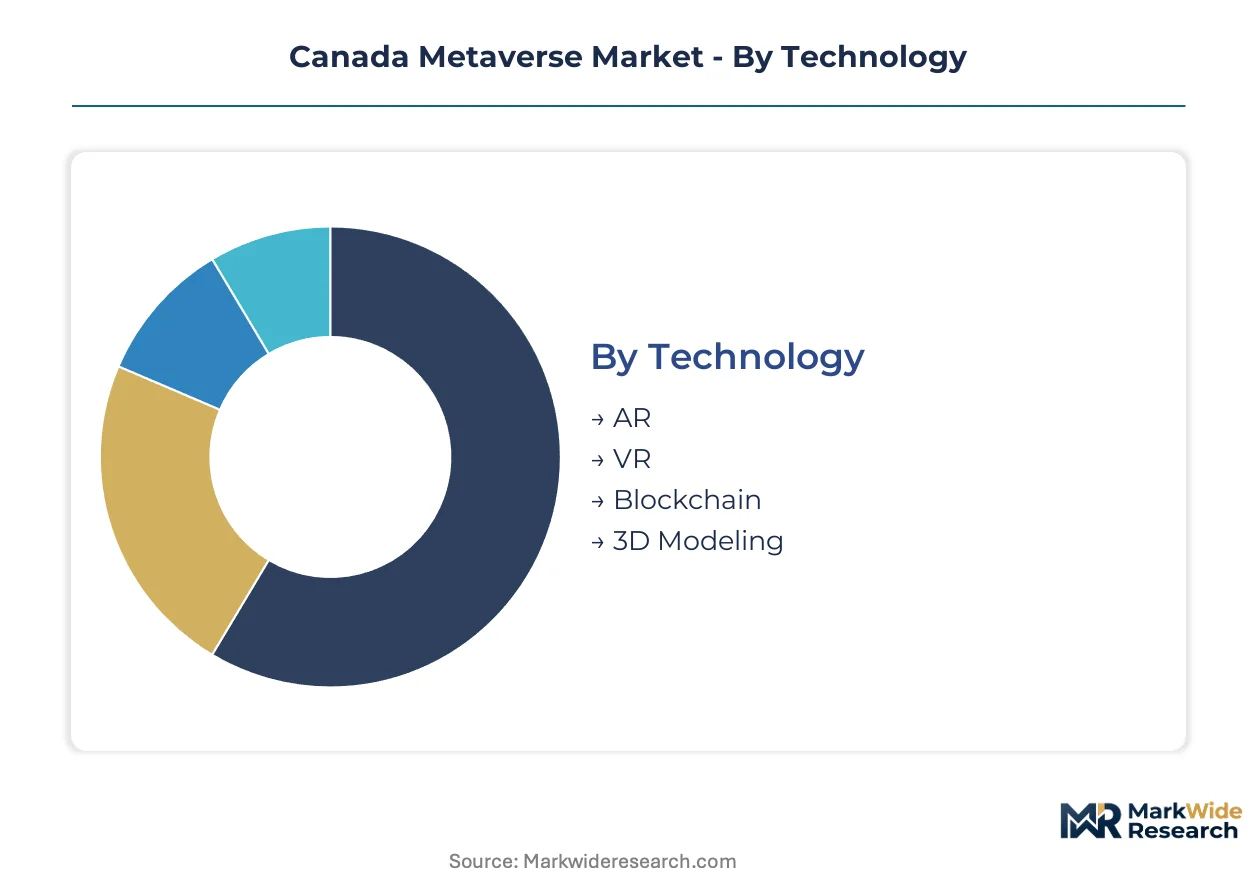
Technology selection dictates infrastructure investment requirements for Canadian operators navigating CRTC latency mandates and Health Canada validation pathways. Application priorities vary sharply between Toronto's enterprise corridor and Montreal's consumer-facing development studios.
Technology:
VR and AR specifications determine hardware dependency, rendering architecture, and edge computing requirements for domestic deployments.
- VR:Headset-based immersive environments with six-degrees-of-freedom tracking dominate Ontario manufacturing training budgets. Demand concentrates in Toronto's aerospace supply chain where tier-one suppliers mandate SaaS delivery for workforce simulation.
- AR:Overlay spatial computing reduces hardware costs through smartphone and tablet compatibility. Quebec's industrial maintenance sector drives procurement as legacy system integration requirements favor incremental deployment over full VR replacement.
- Blockchain:Distributed ledger protocols enable asset verification and tokenized settlement mechanisms for financial institutions piloting digital commerce.
- 3D Modeling:Real-time engine workflows from Revit integration support architecture and engineering visualization pipelines.
Mature deployment sits with VR. Newer deployment is concentrated in AR.
Application:
End-use function determines regulatory exposure, margin structure, and procurement cycle length for platform developers.
- Gaming:Consumer headset installed base remains the largest volume category. Montreal's development cluster captures federal innovation tax incentives while browser-based tools fragment hardware vendor concentration.
- Healthcare:Surgical planning and therapeutic interventions attract the deepest margin pools. Health Canada's medical device classification requirements compress validation timelines while extending product development cycles.
- Education:Distributed learning infrastructure investments in British Columbia and Alberta open institutional procurement channels for immersive training platforms.
- Retail:Web-native 3D commerce tools reduce hardware dependency for mid-market retailers in Vancouver and Calgary metropolitan areas.
Procurement maturity clusters in gaming. Steepest expansion trajectory appears in healthcare.
End User:
Customer type shapes pricing architecture, implementation complexity, and support service requirements.
- Enterprises:Subscription-based service models displace perpetual licenses in manufacturing and logistics verticals. Capital expenditure avoidance dominates procurement criteria.
- Consumers:Gaming applications drive headset volume through direct-to-retail channels.
- Developers:Spatial computing talent scarcity in Unreal Engine and Unity expertise creates recruitment bottlenecks for Prairie-region operators.
- Content Creators:Generative content moderation obligations under forthcoming federal artificial intelligence legislation reshape platform design requirements.
Revenue concentration favors enterprises. Developer segment shows tightest supply constraints.
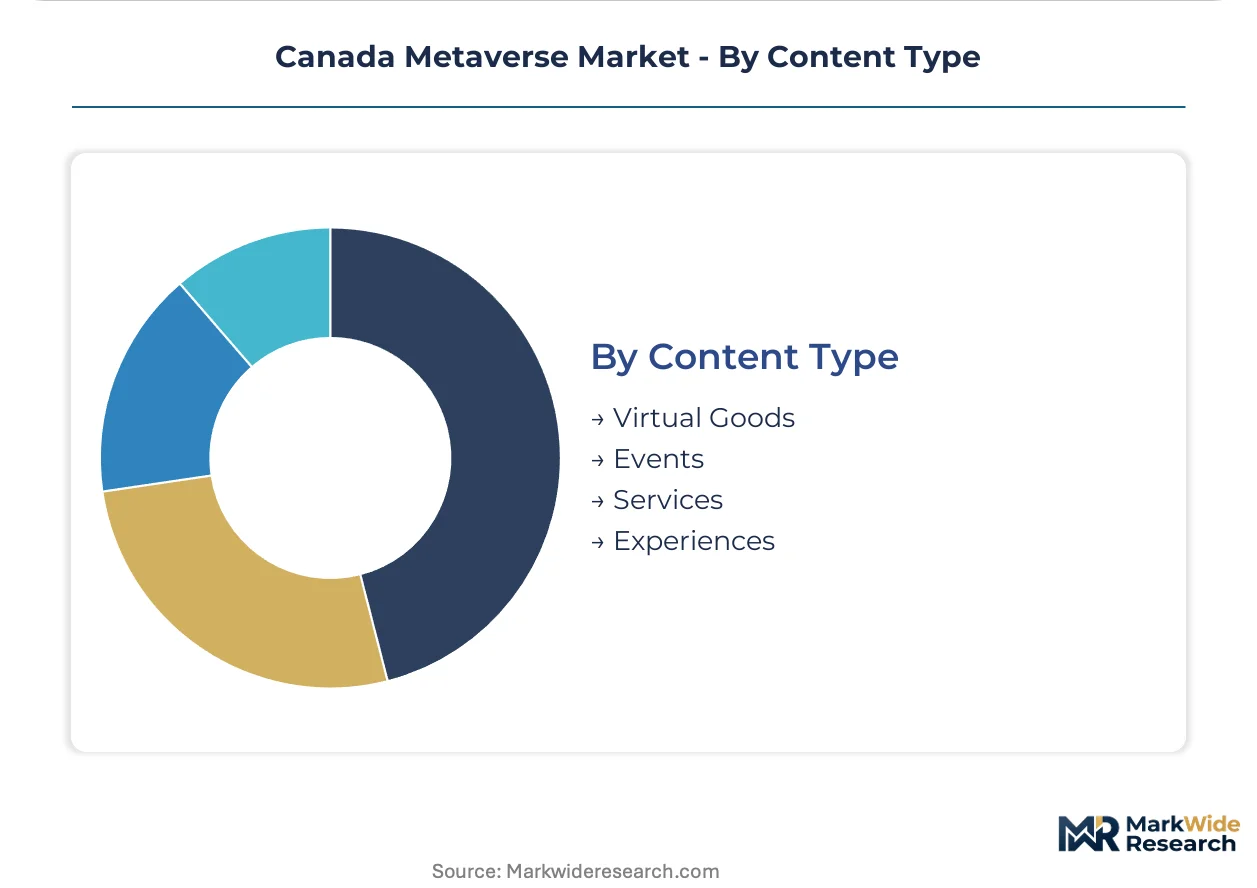
Content Type:
Monetization format determines platform architecture, authentication protocols, and recurring revenue potential.
- Virtual Goods:Tokenized asset verification through blockchain infrastructure enables secondary market functionality for digital commerce.
- Events:Temporary immersive gatherings require scalable cloud-native rendering architectures.
- Services:Enterprise training and therapeutic interventions command subscription pricing with clinical validation requirements.
- Experiences:Consumer-facing entertainment content competes on hardware accessibility and distribution reach.
Virtual goods capture established monetization. Services segment gains share fastest through institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Scientific Research and Experimental Development tax incentive anchors developer concentration in Ontario and Quebec, compressing effective R&D costs for immersive platform builders while federal broadband mandates reshape infrastructure deployment priorities.
Ontario
Toronto's technology corridor concentrates enterprise VR deployment for manufacturing training, with tier-one aerospace suppliers mandating SaaS delivery for workforce simulation tools. Health Canada's evolving digital health frameworks compress validation timelines for therapeutic systems developed in the Waterloo-Kitchener cluster. The province's edge computing investments align with CRTC low-latency mandates, enabling real-time 3D rendering for industrial clients.
Quebec
Montreal's gaming cluster captures federal innovation tax incentives while browser-based 3D tools fragment hardware vendor concentration in consumer-facing development. The CRTC's network neutrality provisions govern cloud-rendered streaming quality for French-language immersive content distribution. Industrial maintenance procurement in Quebec City favors AR overlay solutions that reduce legacy system integration burdens.
British Columbia
Distributed learning infrastructure investments in Vancouver open institutional VR procurement channels for educational technology developers. The Office of the Privacy Commissioner enforces PIPEDA compliance for biometric data harvested through facial tracking interfaces deployed in provincial healthcare pilots. Web-native 3D commerce tools from Vancouver-based developers capture retail sector pilots.
Alberta
Energy sector training budgets in Calgary drive immersive simulation procurement for hazardous environment workforce preparation. Provincial education mandates expand institutional adoption of VR platforms across Edmonton metropolitan area technical colleges. The CRTC broadband infrastructure calculus affects edge computing deployment economics for remote oil sands training facilities.
Atlantic Canada
Halifax-based maritime simulation centers deploy immersive training for offshore energy and naval applications. Federal Atlantic Canada Opportunities Agency programs supplement SR&ED incentives for regional immersive technology startups. The concentration of ocean technology research creates specialized demand for underwater environment visualization pipelines.
Canada Metaverse Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology layers, with the vendor base organizing into three distinct tiers. Autodesk occupies the diversified tier through deep workflow integration with existing enterprise software stacks. Pure-play immersive specialists concentrate in Toronto and Montreal, capturing federal R&D incentives while web-native tool builders fragment hardware dependency. Competitive moves cluster around strategic partnerships with systems integrators and geographic expansion into Prairie-region enterprise accounts.
Among Canada-based developers, Visualhawk Solutions Inc. and MetaVRse Inc. anchor the domestic pure-play tier, with Visualhawk representing enterprise VR deployment specialists and MetaVRse exemplifying web-native 3D commerce tool builders. Autodesk occupies a position as the diversified workflow incumbent, leveraging Revit integration to sustain architecture and engineering relationships. Zesty Market sits within the emerging digital commerce infrastructure layer.
| Leading Market Players |
|---|
| Visualhawk Solutions Inc. |
| Zesty Market |
| MetaVRse Inc. |
| Terraunity |
| Shift Reality |
| Synervoz Communications Inc. |
| Livshows |
| Autodesk |
| ibentos INC |
| Others |
Pricing and Supply Chain Analysis
GPU spot pricing indices from Taiwan and South Korea cascade through headset assembly tiers, compressing margins for economy-grade hardware while premium enterprise VR systems maintain pricing power through Health Canada certification requirements and extended validation timelines.
Pricing Analysis
Short lead-time premiums of 15-25% apply to enterprise VR deployments requiring Health Canada medical device clearance, while spot inventory discounts emerge for consumer gaming headsets facing inventory overhang. Three-tier pricing structure across premium certified-therapeutic, standard enterprise-training, and economy consumer-gaming levels reflects validation burden differentiation. Pricing pressure stems from semiconductor supply volatility affecting GPU and spatial computing component costs. Mid-market retailers in Vancouver and Calgary metropolitan areas exhibit highest price sensitivity, driving demand for web-native 3D commerce tools that reduce hardware dependency.
Supply Chain Analysis
Spatial computing engineering talent scarcity in Toronto and Montreal concentrates headset design and software development, while Taiwan, China, and South Korea dominate GPU, display panel, and sensor component manufacturing. Raw material and component dependencies center on advanced semiconductors, lithium-ion battery cells, and precision optical assemblies. Single-source vulnerability runs through Taiwan-based foundry capacity for high-performance GPUs. Distribution runs through direct OEM channels for enterprise deployments and consumer electronics retail networks for gaming hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada metaverse market sits in a technology-transition phase where cloud-native rendering architectures displace hardware-dependent VR systems, with web-native spatial computing absorbing mid-market demand previously requiring dedicated headsets.
For Market Incumbents: Anticipate margin compression from browser-based 3D tools fragmenting hardware vendor concentration by embedding clinical advisory boards into product design phases for Health Canada validation pathways. Prioritize Revit workflow integration depth to defend architecture and engineering relationships against emerging web-native competitors. Capacity addition in Ontario's edge computing infrastructure aligns with CRTC low-latency mandates for real-time enterprise rendering.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in therapeutic VR systems creates white-space opportunity for mid-market surgical planning tools with streamlined validation timelines. Prairie-region enterprise accounts in Calgary's energy sector and Edmonton's technical colleges represent underpenetrated geographies with institutional procurement budgets. Go-to-market angle should emphasize SaaS delivery models that displace perpetual licenses in manufacturing training verticals.
For Investors and Strategic Acquirers: Distressed-cycle entries favor web-native 3D commerce specialists with established retail sector pilots in Vancouver and Calgary metropolitan areas during hardware inventory correction phases. Long-term viability hinges on platform architecture flexibility across cloud-native and edge-deployed rendering modes. Signal to watch is Health Canada medical device classification pathway expansion into mental health therapeutic applications as inflection indicator for margin pool deepening.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Revit workflow embedding captures architecture and engineering procurement cycles in Ontario. |
| Strategic Partnership | Clinical advisory board integration compresses Health Canada validation timelines for therapeutic systems. |
| Geographic Expansion | Prairie-region enterprise accounts in Calgary energy sector open institutional training budgets. |
| Product Launch | Web-native 3D commerce tools reduce hardware dependency for Vancouver mid-market retailers. |
| Acquisition of Specialist Firm | Spatial computing talent pools in Montreal gaming cluster address developer scarcity bottlenecks. |
Research Methodology
Document review covered CRTC regulatory filings, Health Canada medical device classification databases, and federal innovation tax incentive program disclosures, complemented by interviews with immersive platform CTOs, hospital biomedical engineering directors, enterprise IT procurement officers, and spatial computing integration specialists. Secondary validation drew from hyperscaler capex disclosures, provincial education infrastructure investment reports, and aerospace supply chain procurement records. Bottom-up deployment sizing across Toronto, Montreal, Vancouver, and Calgary metropolitan areas was triangulated against top-down market aggregation.
Cross-referencing historical adoption curves from healthcare VR deployments with panel input from Quebec aerospace training coordinators and British Columbia distributed learning administrators shaped the analytical framework. Segmentation dimensions modeled include technology layer, application function, end-user archetype, and provincial regulatory cluster. CAGRs were derived through trend extrapolation moderated by infrastructure investment timing and clinical validation pathway evolution. Industry-specific forecast inputs encompassed CRTC broadband mandate implementation schedules and SR&ED tax credit utilization patterns.
Inputs from Health Canada regulatory databases and CRTC infrastructure filings were available through the study window; gaps in real-time headset shipment data and provincial education procurement cycle timing introduce uncertainty bands around near-term adoption trajectories. Forecasts reflect documented assumptions regarding edge computing deployment economics and therapeutic VR reimbursement pathway development. Material deviation in CRTC latency mandate enforcement or Health Canada classification pathway expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Germany Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Amusement Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market