
 Anime Movies and TV Shows Market | 2026-2036
Anime Movies and TV Shows Market Size, Share, and Industry Trends Forecast 2026-2036
Anime Movies and TV Shows Market Analytics
Japanese animation studios is decoupling from traditional broadcast dependency as streaming infrastructure matures. Toei Animation Co., Ltd. leverages its decades-long franchise stewardship to sustain theatrical relevance alongside digital windows. Production I.G, Inc. competes through technology leadership in hybrid CGI-cel animation pipelines. Crunchyroll anchors North American audience capture through exclusive licensing and direct-to-consumer subscription mechanics.
Anime movies and TV shows constitute serialized or feature-length animated content produced primarily through cel-style or digital 2D/3D hybrid techniques, with frame rates typically ranging from 8 to 24 fps depending on budget tier and scene complexity. The form serves commercial purposes spanning entertainment consumption, merchandise tie-ins, and transmedia intellectual property exploitation. Streaming platforms represent the fastest-growing distribution channel as theatrical windows compress and TV broadcast audiences fragment. Feature films retain premium margin pools through limited theatrical runs and collector-edition physical media. The action genre dominates volume production, while fantasy content commands disproportionate licensing revenue in international markets.
Japan's Ministry of Economy, Trade and Industry (METI) promotes anime export through content industry subsidies and co-production treaties. The US Federal Communications Commission (FCC) and Children's Online Privacy Protection Act (COPPA) compliance requirements shape streaming platform content categorization and data handling practices for under-18 audiences. Stakeholders must monitor how platform content moderation policies and regional age-rating divergences affect catalog availability and subscriber churn across jurisdictions.
Market Dynamics
Streaming platform dominance is fragmenting traditional broadcast windows and compressing theatrical-to-digital release cycles across production ecosystems. This structural shift forces studios to rebuild revenue models around subscription mechanics rather than box office or syndication.
Growth Catalysts
- Content Export Subsidies:Japan's METI funds international co-production treaties and localization grants that lower market entry costs for overseas distributors.
- Hybrid CGI-Cel Pipelines:Real-time rendering engines are slashing per-episode production timelines from months to weeks for mid-budget series.
- Teen and Young Adult Viewership Concentration:North American subscriber bases between ages 13-29 drive platform commissioning decisions and exclusive licensing premiums.
Market Restraints
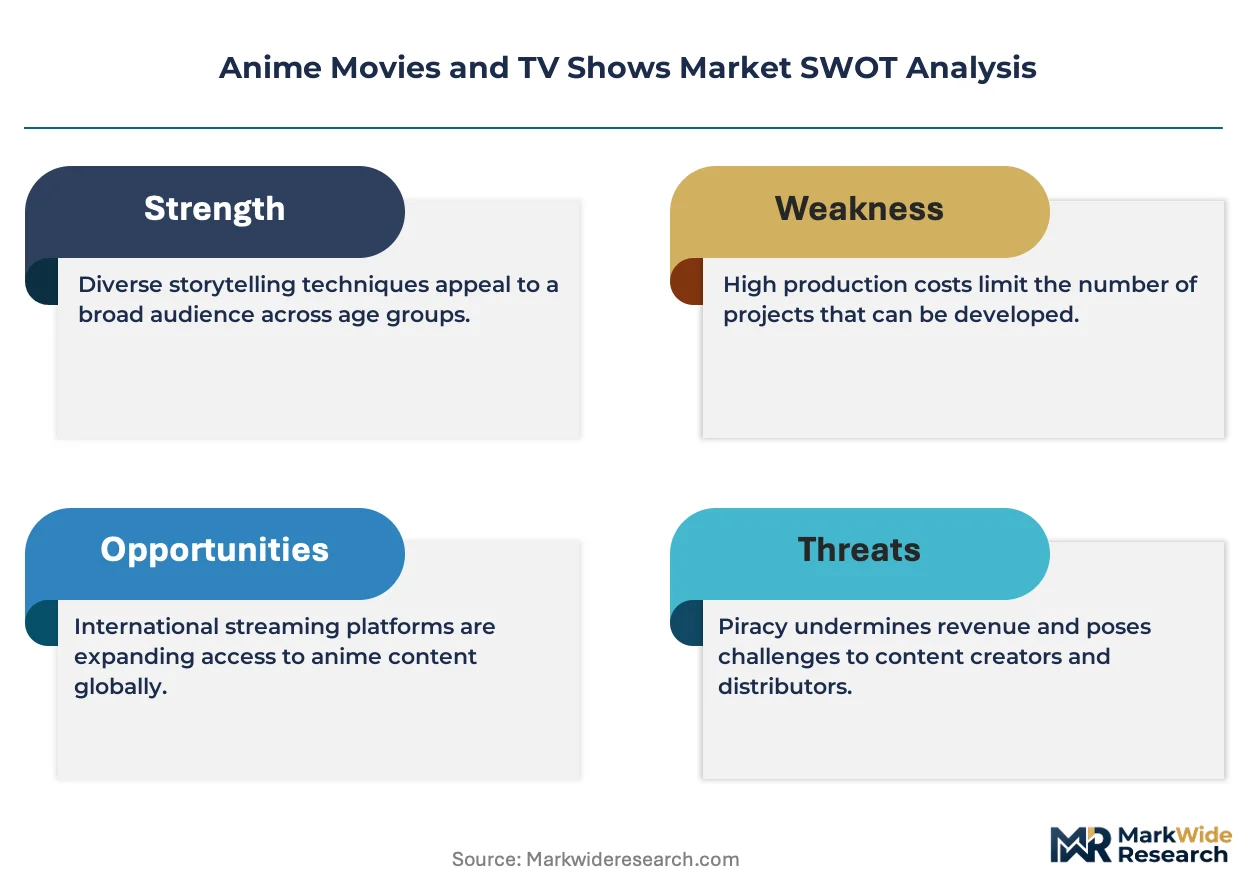
- Animator Labor Supply Bottlenecks:Japan's in-between animation workforce faces attrition as wages lag adjacent creative industries.
- Single-Region Production Concentration:Over 70% of cel-style animation labor pools cluster in Tokyo-Osaka corridors, creating geographic vulnerability.
- US COPPA Compliance Friction:Age verification and data handling requirements for under-13 audiences restrict catalog availability and increase platform legal costs.
Strategic Opportunities
- South Korean Cultural Ministry Incentives:Tax credits for animation co-productions attract Japanese studios seeking cost arbitrage on labor-intensive sequences.
- AI-Assisted In-Betweening:Machine learning tools trained on studio style guides promise 40% frame interpolation cost reductions for high-volume series.
- Collector Physical Media:Limited steelbook and vinyl soundtrack releases capture superfan willingness to pay premium multiples above digital subscriptions.
Industry Challenges
- Key Animator Succession Crisis:Master animators aging out of the workforce lack sufficient apprenticeship pipelines to transfer timing and spacing expertise.
- Cross-Border Licensing Complexity:Territorial rights fragmentation across 200+ jurisdictions creates windowing conflicts between streaming and theatrical exhibitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anime Movies and TV Shows Market |
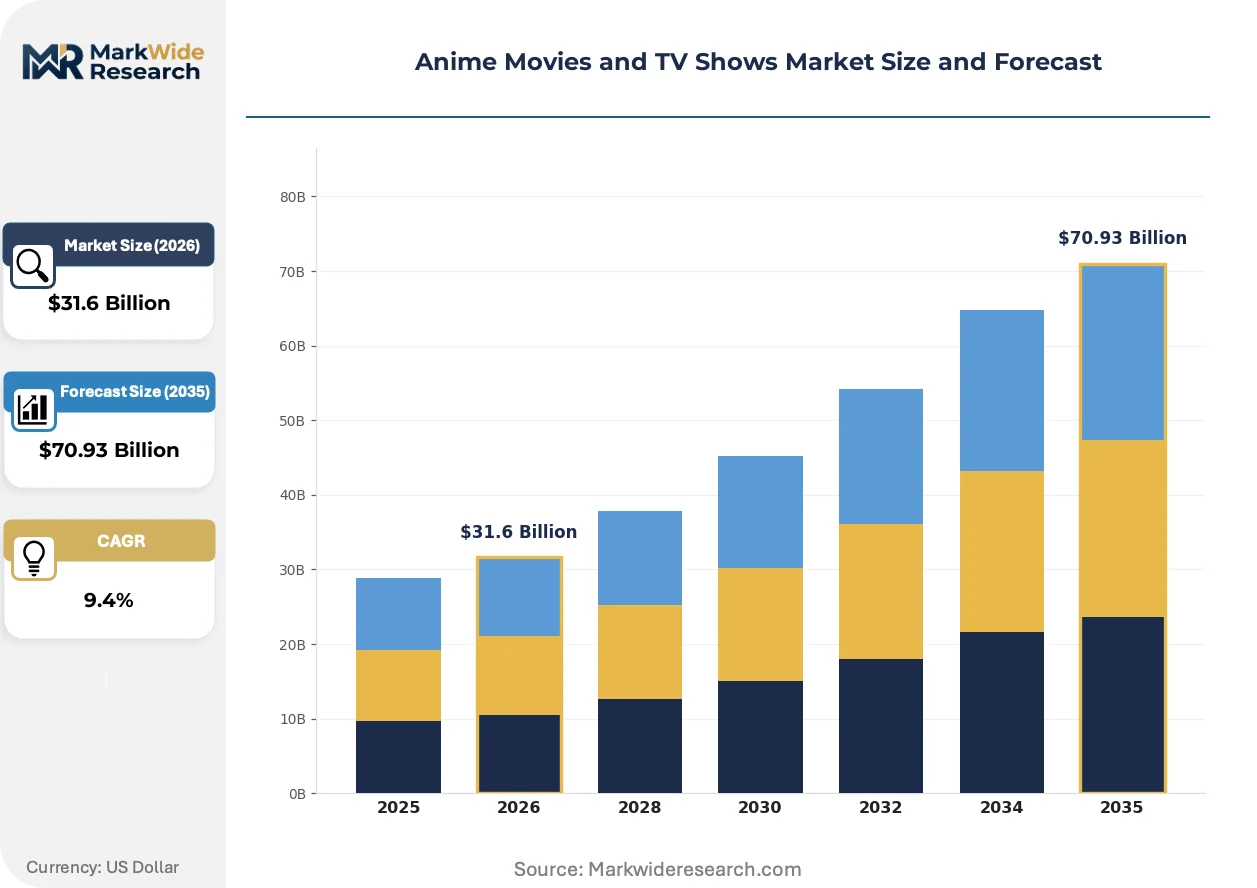
| Market Size in 2026 | $31.6 Billion |
| Market Size in 2035 | $70.93 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Feature Films, Series, OVAs, Specials Distribution Channel: Theatrical, Streaming Platforms, TV Broadcast, DVDs Genre: Action, Romance, Fantasy, Horror Target Audience: Children, Teens, Adults, Family |
| Companies Covered | Pierrot Co., Ltd., Production I.G, Inc., Studio Ghibli, Inc., Toei Animation Co., Ltd., Bones Inc., Kyoto Animation Co., Ltd., MADHOUSE, Inc., Crunchyroll, Netflix, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anime Movies and TV Shows Market Evolving Landscape
Production technology and distribution mechanics are converging to collapse traditional release hierarchies. Studios now compete on speed-to-platform rather than theatrical exclusivity.
Unreal Engine and Unity real-time pipelines are integrating into cel-shaded animation workflows, enabling dynamic camera moves previously reserved for 3D productions. Mid-tier studios in Seoul and Bangkok adopt these tools to bypass traditional render farm bottlenecks. The technology is integrating pre-visualization and final output stages, compressing post-production schedules by half for action-heavy sequences.
South Korea's cultural ministry tax credit schemes now cover 30% of labor costs for animation co-productions with foreign partners. This industrial consequence attracts Japanese studios seeking cost relief on in-betweening and background art. The policy most affects fantasy and science fiction genres with high frame counts, prompting producers to relocate labor-intensive episodes to Busan production houses.
Subscription fatigue among 18-34 demographics is shortening content discovery windows and elevating algorithmic recommendation importance over traditional marketing. Streaming platforms respond by unbundling season drops into weekly episode releases to sustain engagement metrics. This pattern is most visible in North American markets where churn rates exceed 8% quarterly for pure anime services without broader entertainment catalogs.
Anime Movies and TV Shows Market Segmentation
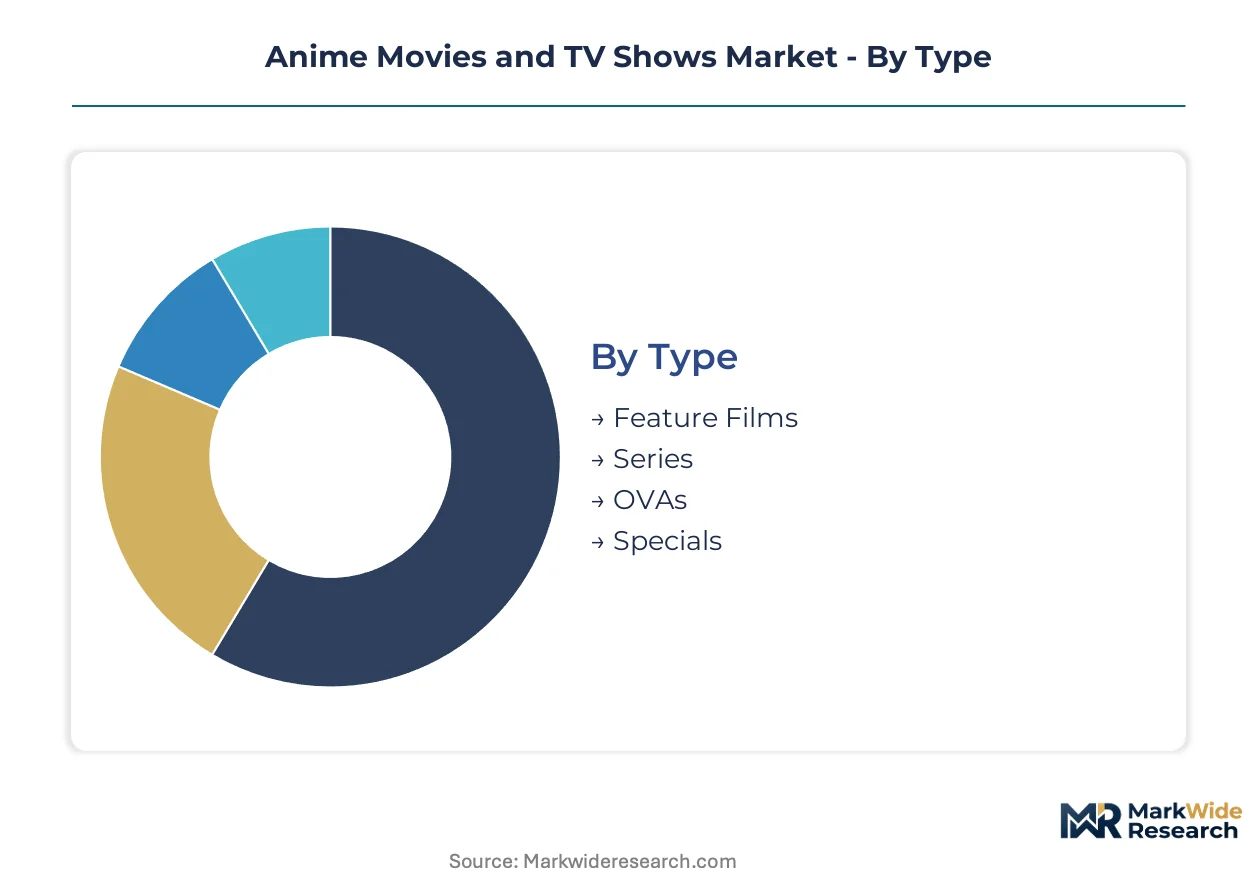
Content format and distribution mechanics determine revenue architecture across the anime value chain. Studios calibrate production budgets and windowing strategies against segment-specific audience behaviors and platform economics.
Type:
Feature Films require theatrical classification from Japan's Film Classification and Rating Organization and carry the heaviest compliance burden for international festival exhibition. Series and shorter formats face lighter regulatory loads but heavier platform content moderation scrutiny.
- Feature Films:Theatrical releases typically run 90-120 minutes with cel or hybrid CGI production budgets concentrated in the upper quartile. Demand clusters in Japan's domestic box office and North American limited theatrical windows, where collector-oriented marketing sustains premium ticket pricing.
- Series:Serialized content spans 12-26 episodes per cour with standardized episode lengths of 23-24 minutes. Teen and young adult subscribers on streaming platforms drive commissioning volume, though production schedules strain animator labor pools.
- OVAs:Direct-to-video releases historically served as franchise extensions with higher per-minute budgets than broadcast series. Niche collector demand in Japan and limited streaming catalog placement define current distribution.
- Specials:Single-episode or short-form content including recap episodes, side stories, and promotional tie-ins. Bundled with physical media or deployed as platform retention tools during production gaps.
Leading the category by volume: Series. Growing fastest: Feature Films.
Distribution Channel:
Channel selection determines margin capture and territorial reach. Theatrical and physical media retain premium pricing power while streaming scales audience access.
- Theatrical:Limited theatrical runs in Japan, South Korea, and select North American markets generate event-driven revenue spikes. Windowing compression pressures exhibitors as streaming platforms negotiate shorter exclusivity periods.
- Streaming Platforms:Subscription video-on-demand services command the largest audience share among 13-29 demographics. Japan's METI export subsidies reduce localization costs for platform catalog expansion.
- TV Broadcast:Traditional linear channels retain relevance for family-oriented content and franchise premieres in Japan. Ad-supported models face audience fragmentation to on-demand alternatives.
- DVDs:Physical media persists for collector editions with premium packaging and exclusive bonus content. Steelbook releases and limited vinyl soundtracks target superfan willingness to pay multiples above digital access.
Dominating revenue contribution: Streaming Platforms. Expanding most quickly: Theatrical (driven by international expansion).
Genre:
Genre classification shapes production cost structures and licensing premiums. Action and fantasy content carry higher frame counts and background art demands.
- Action:High frame-rate sequences and complex choreography dominate volume production. South Korean co-production tax credits attract labor-intensive episodes to Busan production houses.
- Fantasy:World-building requirements and magic-effect animation command disproportionate international licensing revenue. European and North American distributors pay premiums for completed fantasy series.
- Romance:Lower per-episode production costs with emphasis on character acting and dialogue timing. Sustained catalog value on streaming platforms through rewatch-driven engagement metrics.
- Horror:Mature content ratings restrict platform availability in markets with strict age verification requirements. Niche but loyal subscriber segments drive selective commissioning.
Commanding production volume: Action. Gaining share fastest: Fantasy.
Target Audience:
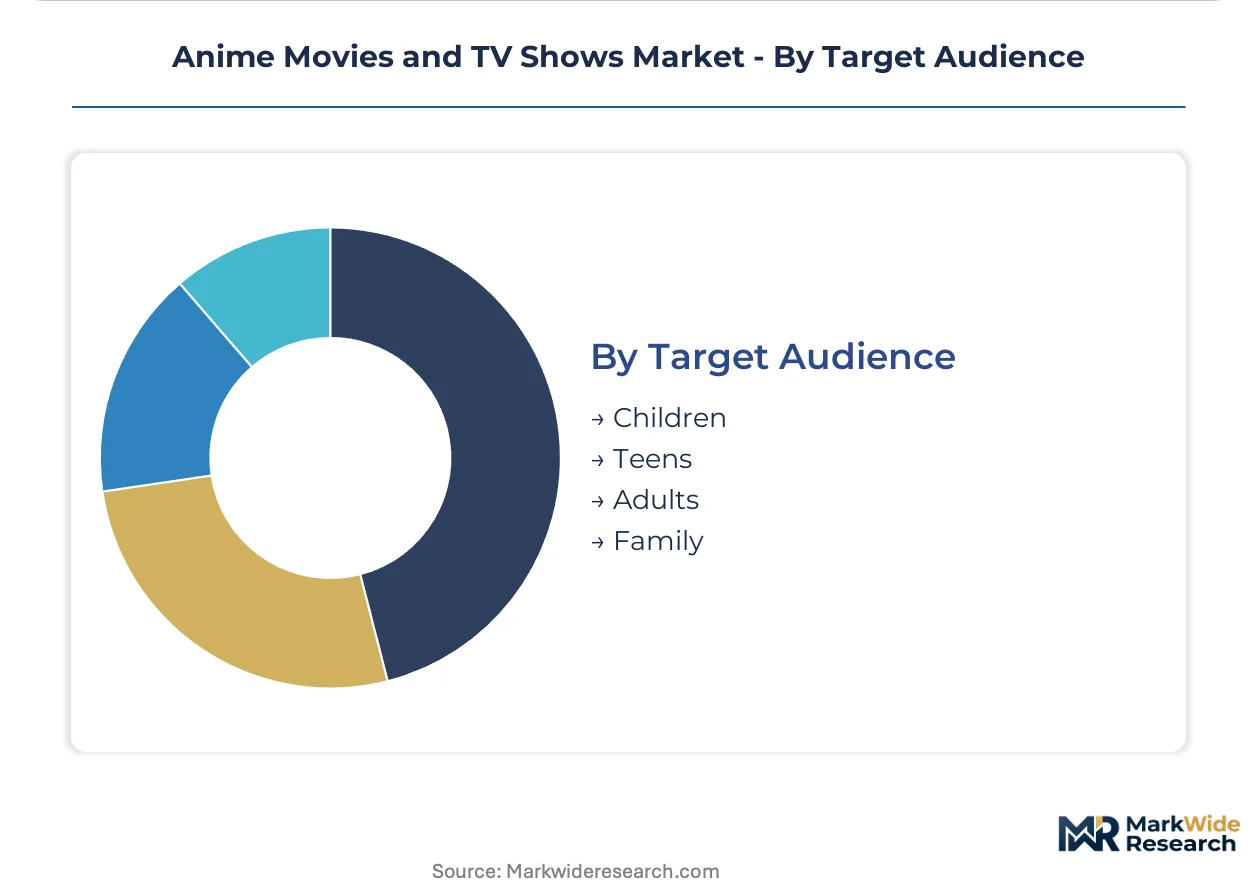
Age demographic determines content rating, platform placement, and regulatory exposure. COPPA compliance requirements in the US reshape data handling for under-13 content.
- Teens:The core subscriber base for streaming platforms drives commissioning decisions and exclusive licensing competition. Content ratings cluster in TV-14 equivalents with action and romance genre concentration.
- Adults:Mature-rated content including psychological drama and horror targets evening viewing windows and higher subscription tiers. Less regulatory friction than youth-directed content.
- Children:Strictest compliance burden under US COPPA and equivalent frameworks. Merchandise tie-in potential offsets content moderation costs and limited platform catalog slots.
- Family:Cross-generational appeal with broadcast-friendly ratings sustains longer syndication windows. Theatrical releases in this category capture holiday-season box office concentration.
Anchoring platform subscriber acquisition: Teens. Climbing the fastest: Adults.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's animator labor pools and Seoul's tax credit schemes anchor production geography across the anime value chain. Distribution infrastructure concentrates in Los Angeles and New York for North American subscriber capture. Regulatory frameworks in each jurisdiction reshape content windowing and platform compliance burdens.
Japan
Domestic theatrical releases and streaming platform licensing drive revenue concentration in the Tokyo-Osaka corridor. METI content export subsidies reduce localization costs for international distributors. Suginami Ward's animation studio cluster houses Toei Animation and Production I.G pipeline operations.
United States
Teen and young adult subscribers on streaming platforms command exclusive licensing premiums from Japanese studios. FCC content categorization and COPPA age verification requirements restrict catalog availability for under-13 audiences. Los Angeles-based distribution offices negotiate territorial rights for North American theatrical windows.
South Korea
Cultural ministry tax credits covering labor costs attract Japanese co-production partnerships for frame-intensive sequences. Busan production houses execute in-betweening contracts for fantasy and science fiction genres. Seoul's real-time rendering adoption accelerates hybrid CGI-cel pipeline integration.
France
European festival exhibition and collector physical media sustain premium pricing for theatrical features. ANSM content rating alignment with Japanese standards reduces regulatory friction for catalog imports. Paris-based distributors license fantasy genre content at disproportionate premiums.
China
Platform content moderation policies and territorial rights fragmentation limit streaming catalog depth versus other Asian markets. NMPA import quotas and review timelines compress theatrical window opportunities. Guangdong production houses experiment with real-time engine adoption for cost arbitrage.
Anime Movies and TV Shows Market Competitive Landscape
Global majors compete with regional champions across streaming platform licensing and theatrical distribution channels. The market structure fragments across legacy animation studios, technology-forward mid-tiers, and platform-integrated distributors. Three archetypes dominate: franchise stewards with decades-long IP catalogs, hybrid pipeline specialists leveraging real-time engines, and streaming-native platforms with exclusive commissioning power. Competitive moves center on exclusive licensing auctions and co-production treaty exploitation for labor cost relief.
Within the franchise steward tier, Toei Animation Co., Ltd. and Studio Ghibli, Inc. occupy positions defined by theatrical relevance and collector media premiums. Production I.G, Inc. exemplifies the technology-forward archetype through hybrid CGI-cel pipeline leadership. Crunchyroll anchors the platform-integrated distributor category with North American subscriber capture mechanics.
| Leading Market Players |
|---|
| Pierrot Co., Ltd. |
| Production I.G, Inc. |
| Studio Ghibli, Inc. |
| Toei Animation Co., Ltd. |
| Bones Inc. |
| Kyoto Animation Co., Ltd. |
| MADHOUSE, Inc. |
| Crunchyroll |
| Netflix, Inc. |
| Others |
Value Network & Pricing Analysis
Tokyo-Osaka animator labor pools concentrate cel-style production expertise, and wage differentials between master key animators and in-between staff create pricing-tier spreads across theatrical, streaming, and collector physical media segments. South Korean tax credits and Southeast Asian production houses widen these spreads further as studios arbitrage frame-intensive sequences across borders.
Pricing Analysis
Collector physical media bundles exclusive steelbook packaging and vinyl soundtracks with purchase, while streaming subscriptions unbundle theatrical windows entirely. Three-tier pricing structure across premium collector editions, standard digital access, and economy ad-supported tiers separates superfans from casual viewers from price-sensitive youth segments. Cost compression in mid-budget series production is intensifying because real-time rendering engines shorten post-production timelines. Platform subscribers aged 13-29 exhibit highest price sensitivity, whereas collector edition buyers show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Tokyo-Suginami Ward studio clusters that house over 70% of cel-style animation labor pools. Production draws from Japanese key animator expertise, South Korean in-betweening houses, and Thai background art studios. Supply chain risk centers on animator workforce attrition as wages lag adjacent creative industries. Distribution runs through streaming platform direct-to-consumer mechanics, theatrical limited windows, and physical media specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from streaming platform commissioning concentration is forcing smaller studios into co-production partnerships or acquisition by franchise stewards with exclusive licensing leverage.
For Market Incumbents: Extend franchise IP lifecycles through transmedia exploitation across gaming, merchandise, and music verticals. Lock exclusive platform licensing windows before competitors capture North American subscriber bases. Backward integration into real-time rendering technology reduces dependency on external CGI pipeline vendors.
For New Entrants and Emerging Players: AI-assisted in-betweening tools offer a technology-first wedge into high-volume series production where labor costs dominate budgets. Target South Korean co-production tax credits for fantasy and science fiction genres with frame-intensive requirements. Pursue direct platform commissioning relationships rather than theatrical distribution dependencies.
For Investors and Strategic Acquirers: The window for entry favors mid-tier studios with hybrid CGI-cel pipeline capabilities and established platform relationships. Long-term viability rests on technology adoption speed and exclusive IP ownership rather than pure production volume. Monitor streaming platform churn rates as the inflection indicator for commissioning budget shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid CGI-Cel Pipeline Investment | Production I.G's Unreal Engine integration compresses action-sequence post-production schedules by half. |
| Exclusive Platform Licensing Agreement | Crunchyroll's North American subscriber capture mechanics command premium minimum guarantees from Japanese studios. |
| South Korean Co-Production Partnership | Busan production houses execute 30% labor-cost savings on frame-intensive fantasy episodes through cultural ministry tax credits. |
| AI-Assisted In-Betweening Deployment | Machine learning tools trained on studio style guides promise substantial frame interpolation cost reductions for high-volume series. |
| Collector Physical Media Extension | Steelbook and vinyl soundtrack releases capture superfan willingness to pay multiples above digital subscription access. |
Research Methodology
Independent corroboration across studio production executives, streaming platform content acquisition leads, and theatrical distribution officers underwrites the qualitative findings. Primary interviews with Japanese animation studio heads, South Korean co-production coordinators, and North American platform licensing managers combined with secondary validation. Sources include Japan's METI content export reports, FCC content categorization filings, and streaming platform subscriber disclosure data. Bottom-up production volume estimates and top-down licensing revenue aggregates triangulate market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include content format, distribution channel, genre classification, and target audience demographic. CAGRs derive from production pipeline capacity expansion, platform subscriber growth trajectories, and territorial licensing fee trends. Industry-specific inputs incorporate animator labor pool attrition rates and real-time rendering adoption curves.
Several conditions sit outside the modeled scope, including NMPA import quota changes in China and unforeseen platform content moderation policy shifts. Forecasts reflect documented assumptions about streaming window compression and theatrical exclusivity period stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Film and Cinema
Cinema Camera Market
Film and Cinema
Japan Animation, VFX and Post Production Market
Film and Cinema
Global Advanced Cinema Projector Market
Film and Cinema
Brazil Animation, VFX and Post Production Market
Film and Cinema
Film Dubbing Market
Film and Cinema
Movies and Entertainment Market
Film and Cinema
Digital Cinema Projectors Market
Film and Cinema
Cinema Lenses Market
Film and Cinema
Camera Jib Market
Film and Cinema
Latin America Animation, VFX and Post Production Market
Film and Cinema
North America 3D Cinema Screen Market
Film and Cinema
Movie Tickets Market
Film and Cinema
Drive-In Movie Theater Market
Film and Cinema
Tripod Dolly Market
Film and Cinema
North America Animation, VFX and Post Production Market
Film and Cinema
United Kingdom Animation, VFX and Post Production Market