
 Television Services Market | 2026-2036
Television Services Market Size, Share, and Industry Trends Forecast 2026-2036
Television Services Market Intelligence
Streaming-sports bundling is realigning how households construct their entertainment spend. Comcast Corporation leverages its hybrid cable-broadband infrastructure to anchor subscription retention. The Walt Disney Company sustains pricing power through exclusive live sports rights. Warner Bros. Discovery competes by consolidating disparate streaming libraries under a single interface.
Television services encompass the production, aggregation, and distribution of video content through terrestrial broadcast, satellite transmission, cable infrastructure, and internet protocol networks, typically delivered via set-top boxes, smart TVs, or mobile applications requiring sustained bandwidth above 5 Mbps for high-definition streams. The primary commercial purpose centers on monetizing viewer attention through subscription fees, advertising impressions, or transactional purchases. Streaming services now capture the fastest expansion within service type segmentation, while live sports commands premium advertising rates within content type segmentation. Cable maintains residual dominance in rural distribution channels where fiber deployment remains uneconomical.
The FCC enforces must-carry rules and retransmission consent frameworks that govern how broadcast signals enter pay-TV packages across the United States. Ofcom in the United Kingdom imposes public service broadcasting quotas and prominence requirements for linear channels on electronic program guides. India's TRAI mandates tariff transparency and a la carte channel selection to prevent bundling abuse. Stakeholders must monitor how spectrum reallocation and streaming exclusivity reshape content access economics without assuming regulatory permanence.
Market Dynamics
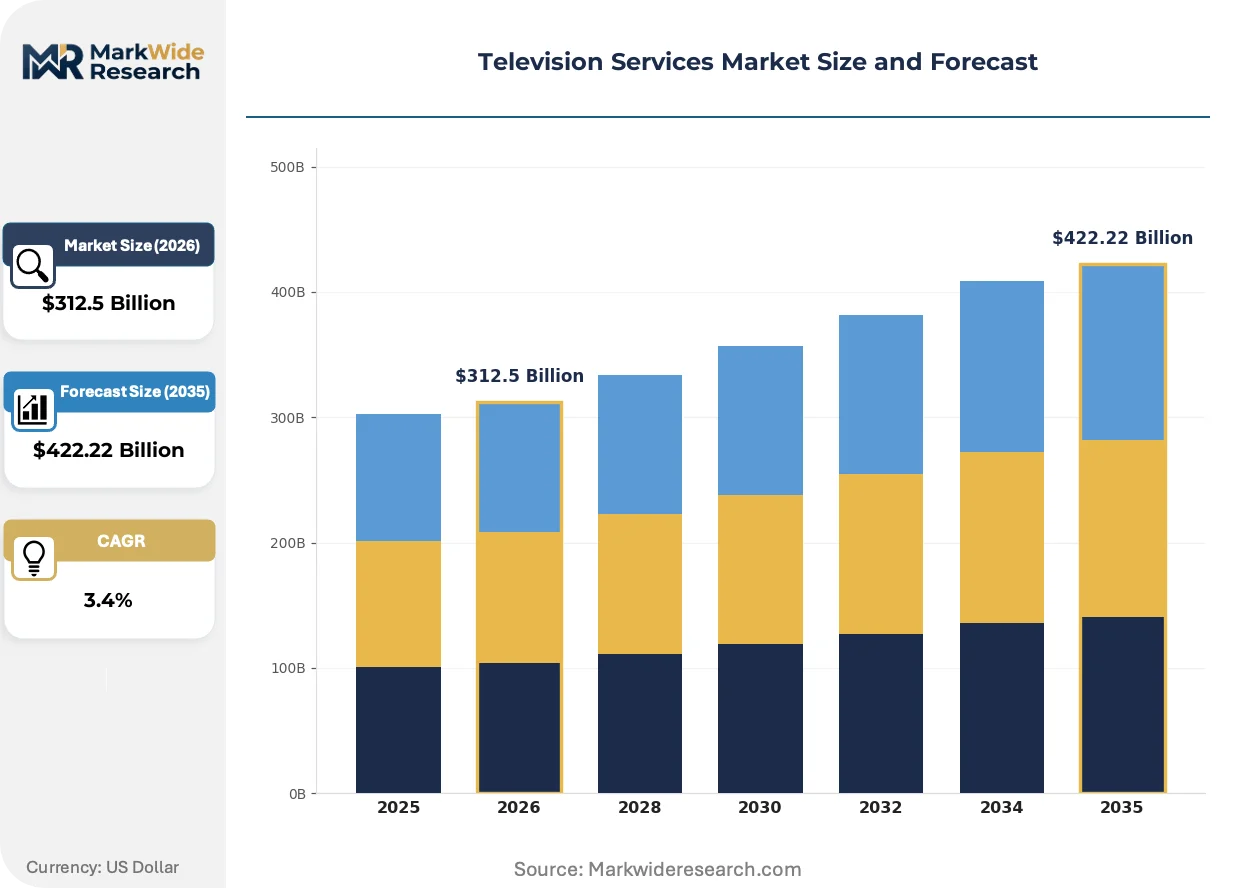
The Television Services Market is reconfiguring around broadband infrastructure economics as fiber-to-the-home deployment and 5G fixed wireless access compete to replace legacy coaxial distribution, compressing subscriber acquisition costs while elevating content licensing expenditures.
Growth Catalysts
- Net Neutrality Frameworks:The FCC's open-internet rules and similar EU regulations prevent gatekeeping by last-mile providers, enabling independent streaming platforms to reach households without preferential access fees.
- Live Sports Exclusivity:Premium broadcasting rights for major leagues concentrate viewer attention during appointment-viewing windows, sustaining advertising rate premiums that subsidize platform expansion.
- India:TRAI's tariff transparency mandates and a la carte channel regulations dismantle opaque bundling practices, accelerating household migration from cable to addressable streaming alternatives.
Market Restraints
- Content Licensing Cost Inflation:Exclusive sports and entertainment rights auctions drive input cost volatility, compressing platform margins without commensurate subscriber pricing power.
- Rural Infrastructure Gaps:Fiber deployment economics fail in low-density geographies, leaving satellite and legacy cable as the sole distribution options with inferior bandwidth economics.
- Retransmission Consent Friction:FCC-mandated negotiation frameworks between broadcasters and distributors create recurring carriage disputes that disrupt service continuity.
Strategic Opportunities
- Advertising-Supported Tiers:Hybrid monetization models combining subscription and impression-based revenue are penetrating price-sensitive household segments previously excluded from paid streaming.
- Cloud Gaming Convergence:Low-latency streaming infrastructure built for video is integrating interactive entertainment delivery, expanding addressable spend per household.
- Ofcom Prominence Requirements:UK regulatory mandates for public service broadcaster visibility on electronic program guides preserve linear channel relevance within hybrid streaming interfaces.
Industry Challenges
- Subscriber Churn Management:Low switching costs across over-the-top platforms force continuous content investment to maintain engagement metrics and reduce acquisition spend inefficiency.
- Legacy Set-Top Box Integration:Cable operators face technical debt from hybrid QAM-IP delivery systems that complicate feature parity with pure streaming competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Television Services Market |
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $422.22 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cable, Satellite, Streaming, IPTV Content Type: Live Sports, Movies, News, Series Viewer Demographics: Adults, Families, Kids, Seniors Distribution Channel: Online, Retail, Direct Sales, Resellers |
| Companies Covered | Comcast Corporation, Warner Bros. Discovery, The Walt Disney Company, Paramount Global, British Broadcasting Corporation, Fox Corporation, Canal+ Group, AT&T Inc., Vivendi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Television Services Market Strategic Shifts & Innovations
Artificial intelligence is compressing content discovery timelines and personalizing advertising insertion, while regulatory pressure on data localization and cross-border content licensing is fragmenting previously global distribution architectures.
Server-side ad insertion technology is integrating with programmatic buying platforms to replace traditional broadcast spot schedules with individually targeted impressions. Mid-tier streaming services are adopting this infrastructure to capture CTV advertising budgets migrating from linear television. The technology is integrating measurement capabilities that satisfy advertiser demands for verified viewability, compressing the attribution gap between digital and broadcast media.
The EU's Digital Services Act imposes algorithmic transparency obligations on large streaming platforms operating across member states. Content recommendation systems must now disclose ranking parameters, altering how platforms optimize for engagement. French and German regulators are prioritizing enforcement against opacity in youth-targeted content curation, forcing operational adjustments in parental control interfaces.
Households are constructing entertainment stacks through sequential free-trial exploitation rather than committing to annual subscriptions. This behavior compresses platform lifetime value calculations and elevates retention marketing expenditure. The pattern is most visible in United States metropolitan markets where broadband penetration enables frictionless service switching without hardware installation barriers.
Television Services Market Segmentation
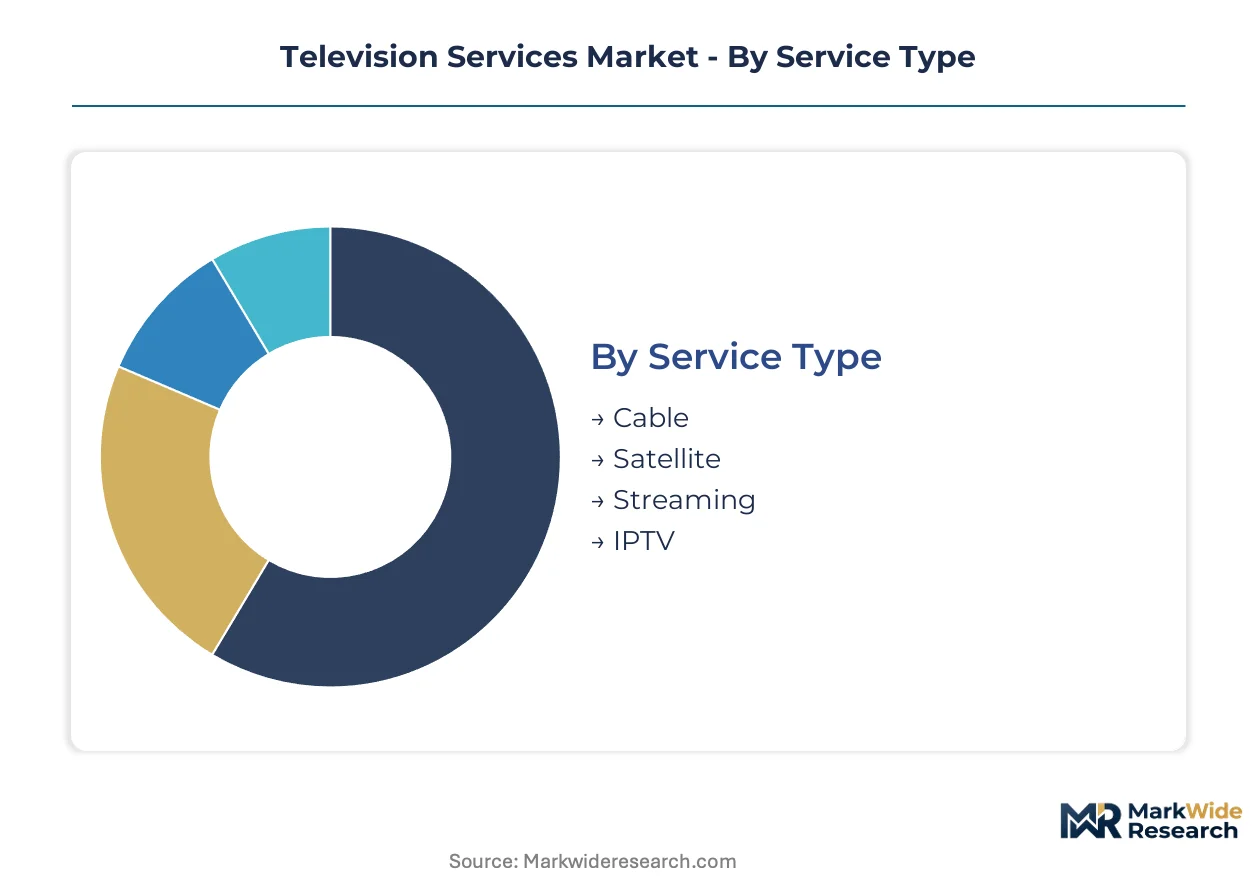
Television services fragment across delivery infrastructure, content economics, and household composition, with each dimension commanding distinct pricing power and retention mechanics. Understanding these divisions reveals where platform investment concentrates and which subscriber cohorts drive lifetime value.
Service Type:
Households upgrade from legacy distribution as broadband penetration crosses thresholds that enable reliable high-definition streaming, compressing cable replacement cycles and accelerating satellite attrition.
- Streaming:Internet protocol delivery requires sustained bandwidth above 5 Mbps for HD quality and 25 Mbps for 4K, with adaptive bitrate technology smoothing congestion periods. Demand concentrates in United States metropolitan markets where fiber-to-the-home deployment eliminates buffering friction, though rural 5G fixed wireless access is extending addressable geography.
- Cable:Hybrid fiber-coaxial infrastructure sustains residual dominance where fiber economics fail, particularly in low-density United States exurbs and secondary European markets. QAM-IP delivery systems create technical debt that complicates feature parity with pure streaming competitors, elevating subscriber churn risk among broadband-native households.
- Satellite:Geostationary and low-earth-orbit constellations serve rural distribution gaps where terrestrial infrastructure remains uneconomical, with inferior latency economics limiting interactive service expansion.
- IPTV:Managed IP networks over telecom operator infrastructure bundle television with broadband and voice services, prevalent in European markets with dominant incumbent carriers.
Streaming sits at the top of the volume ranking, with IPTV climbing the fastest as telecom operators consolidate triple-play bundles.
Content Type:
Content economics stratify by production cost intensity and advertising rate premiums, with live appointment viewing sustaining pricing power against on-demand commoditization.
- Live Sports:Exclusive league rights auctions concentrate viewer attention during fixed windows, commanding CPM multiples above entertainment programming. NFL, Premier League, and IPL broadcasting agreements drive platform subscriber acquisition in the United States, United Kingdom, and India respectively.
- Series:Serialized fiction production spreads costs across episode counts and multiple seasons, with binge-release models compressing engagement windows and elevating retention marketing expenditure. Netflix and Amazon Prime Video original productions dominate United States streaming libraries.
- Movies:Theatrical window compression and day-and-date streaming releases are restructuring talent compensation and production financing, with premium video-on-demand transactions supplementing subscription revenue.
- News:Linear channel bundles and dedicated streaming apps serve election cycles and breaking event spikes, with advertising rates fluctuating around political calendars in the United States and European markets.
Live Sports captures the steepest expansion trajectory in advertising yield, with Series gaining share fastest in total viewing hours.
Viewer Demographics:
Household composition determines bundle complexity and price sensitivity, with multi-generational homes requiring content diversity that elevates tiered subscription uptake.
- Families:Parental control requirements and multi-profile interfaces drive platform selection, with Disney+ and Netflix family plan pricing calibrated to household rather than individual subscription economics.
- Adults:Solo and couple households without children exhibit lower churn tolerance and higher willingness to stack multiple niche services, particularly for prestige drama and documentary content.
- Seniors:Linear viewing habits and interface complexity barriers sustain cable retention in this cohort, though simplified streaming applications are penetrating price-sensitive segments.
- Kids:Dedicated content libraries and COPPA-compliant advertising restrictions create regulatory compliance costs that favor platforms with established children's programming infrastructure.
Families dominate subscriber count, with Adults expanding most quickly in average revenue per user.
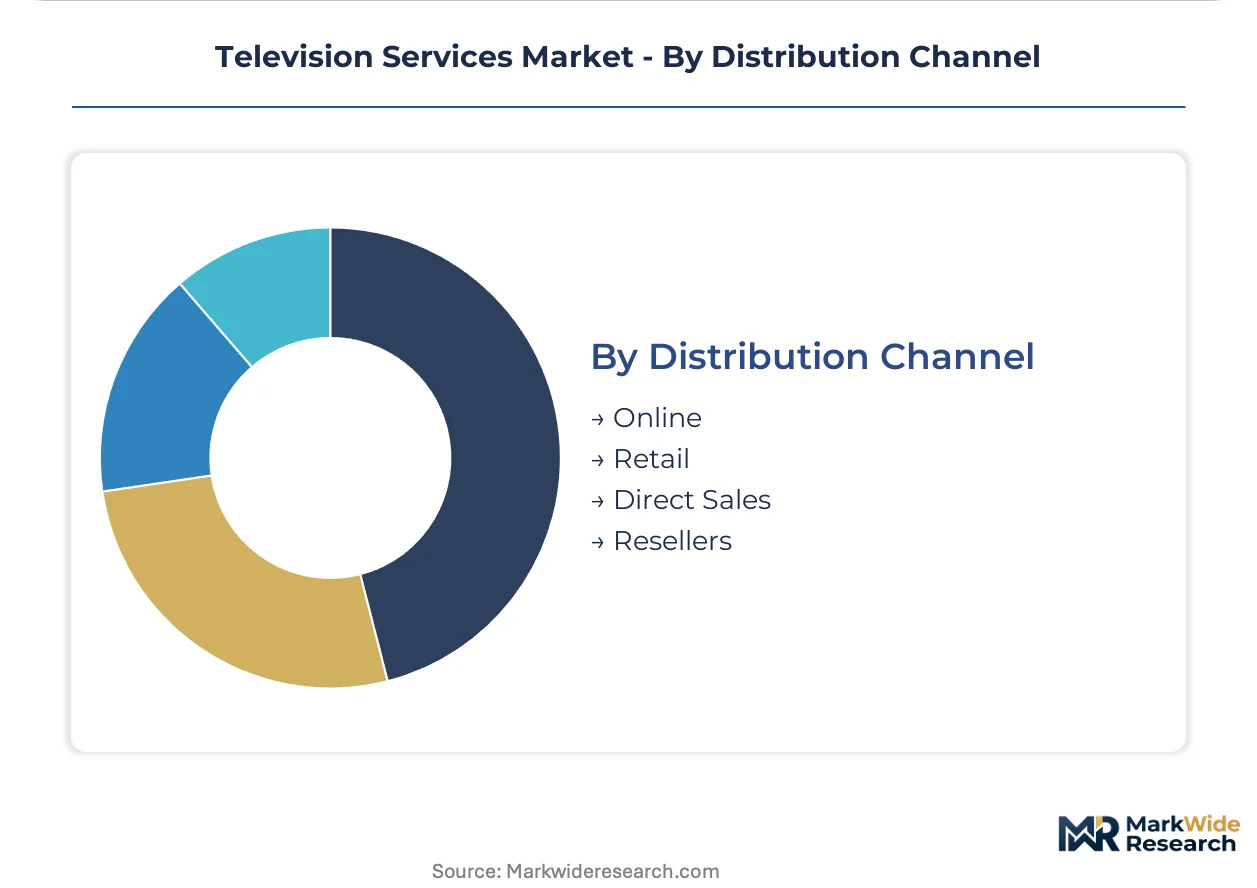
Distribution Channel:
Channel economics reflect customer acquisition cost variation and hardware subsidy structures, with direct relationships enabling data collection that powers personalization algorithms.
- Online:Self-service subscription through platform websites and mobile applications eliminates retail margin extraction, with free trial conversion rates varying by payment method and promotional intensity.
- Direct Sales:Telesales and field representatives target cable-to-streaming migrators with bundled broadband offers, prevalent in United States markets where Comcast and Charter maintain hybrid infrastructure.
- Retail:Big-box electronics and mobile carrier stores distribute streaming hardware and prepaid subscription cards, with commission structures influencing staff recommendation behavior.
- Resellers:Aggregator platforms and telecom bundles package multiple services under unified billing, reducing individual platform brand visibility while lowering subscriber acquisition costs.
Online channels lead transaction volume, with Resellers gaining share fastest through telecom convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Television services originated in terrestrial broadcast networks across the United States and United Kingdom before scaling through satellite and cable infrastructure. Broadband deployment patterns now determine regional competitive dynamics as streaming displaces legacy distribution.
United States
Cord-cutting households drive over-the-top platform expansion as fiber-to-the-home penetration exceeds thresholds for reliable 4K streaming. The FCC enforces must-carry rules and retransmission consent frameworks governing broadcast signal carriage. Los Angeles and New York anchor content production clusters where studio facilities feed exclusive streaming libraries.
United Kingdom
Public service broadcasting quotas sustain linear channel relevance within hybrid streaming interfaces. Ofcom mandates prominence requirements for public service broadcasters on electronic program guides. London concentrates commissioning power for premium drama production that exports to global streaming catalogs.
Germany
Telecom operator triple-play bundles preserve IPTV dominance through broadband-television convergence. German regulators prioritize enforcement against opacity in youth-targeted content curation under EU Digital Services Act implementation. Munich and Cologne host broadcast technology development clusters advancing server-side ad insertion infrastructure.
India
Household migration from cable to addressable streaming accelerates as TRAI tariff transparency mandates dismantle opaque bundling practices. The regulator's a la carte channel regulations prevent bundling abuse in pay-TV packages. Mumbai and Bangalore concentrate streaming platform headquarters and original content production facilities.
South Korea
5G fixed wireless access extends high-bandwidth streaming into dense metropolitan apartment complexes. The country's national broadcasting regulator imposes content quota requirements for domestic production in streaming catalogs. Seoul anchors the Seoul Capital Area where platform competition drives rapid subscription tier innovation.
Television Services Market Key Industry Players
Premium-margin players sit above commodity-margin players across content exclusivity and infrastructure control dimensions. The market structures around three tiers: integrated media conglomerates with sports rights portfolios, pure-play streaming platforms with global distribution, and telecom-cable hybrids with last-mile broadband ownership. Strategic archetypes include content licensors seeking maximum rights valuation, platform aggregators minimizing subscriber acquisition costs, and infrastructure owners extracting carriage fees. Dominant competitive moves involve exclusive sports rights auctions and advertising-supported tier introduction.
Among integrated media conglomerates, Comcast Corporation and Warner Bros. Discovery occupy positions spanning content production through distribution infrastructure. The Walt Disney Company exemplifies the premium-tier archetype through exclusive live sports rights concentration. These three entities represent distinct strategic postures: infrastructure-anchored retention, library consolidation under unified interfaces, and pricing power through appointment-viewing exclusivity.
| Leading Market Players |
|---|
| Comcast Corporation |
| Warner Bros. Discovery |
| The Walt Disney Company |
| Paramount Global |
| British Broadcasting Corporation |
| Fox Corporation |
| Canal+ Group |
| AT&T Inc. |
| Vivendi |
| Others |
Cost & Logistics Intelligence
Content licensing expenditures flow from exclusive sports rights auctions through to subscriber pricing tiers, with escalating input costs compressing platform margins before reaching household bills. This cost transmission shapes how streaming services structure advertising-supported tiers against premium ad-free alternatives.
Pricing Analysis
Hybrid subscription-advertising monetization stratifies across premium, standard, and economy tiers, with live sports exclusivity commanding the highest subscriber willingness-to-pay. Price differentiation hinges on content exclusivity depth and concurrent stream allowances, while cost compression in the standard tier intensifies due to content licensing inflation. Households in metropolitan United States markets exhibit lowest price sensitivity for sports-inclusive bundles, whereas rural satellite-dependent households show highest sensitivity to base-rate increases.
Supply Chain Analysis
Single-source vulnerability sits with Amazon Web Services, Microsoft Azure, and Google Cloud Platform for streaming infrastructure hosting, concentrating platform operational dependency on three hyperscalers. Raw material dependencies encompass fiber-optic cable, semiconductor components for set-top boxes, and satellite launch capacity. Supply chain risk centers on regulatory restriction as data localization mandates fragment previously global content delivery architectures. Distribution runs through direct-to-consumer applications, telecom bundles, and retail hardware partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in television services rests on advertising-supported tier penetration and cloud infrastructure cost optimization, with premium sports rights sustaining pricing power against commoditized entertainment libraries.
For Market Incumbents: Anchor subscriber retention through exclusive live sports rights concentration and hybrid cable-broadband infrastructure bundling. The Walt Disney Company and Comcast Corporation demonstrate how infrastructure-anchored retention and appointment-viewing exclusivity defend against pure-play streaming churn. Invest in server-side ad insertion infrastructure to capture CTV advertising budgets migrating from linear television. For New Entrants and Emerging Players: Direct-to-consumer mobile applications offer the lowest customer acquisition cost route for price-sensitive household penetration. White-space targets include advertising-supported tiers in India under TRAI tariff transparency mandates and rural United States markets underserved by fiber deployment. Pursue telecom bundle partnerships to reduce individual brand visibility trade-offs against subscriber acquisition cost efficiency. For Investors and Strategic Acquirers: Consolidation pressure builds where content libraries overlap and subscriber acquisition costs exceed lifetime value thresholds. Long-term viability favors platforms with exclusive sports rights or owned broadband infrastructure rather than content-licensing-dependent models. Monitor FCC retransmission consent friction and EU Digital Services Act enforcement as inflection indicators for platform margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Sports Rights Acquisition | NFL, Premier League, and IPL broadcasting agreements concentrate viewer attention during fixed appointment windows. |
| Advertising-Supported Tier Launch | Hybrid monetization penetrates price-sensitive households previously excluded from paid streaming subscriptions. |
| Cloud Infrastructure Partnership | Hyperscaler alliances reduce operational dependency while enabling low-latency streaming for interactive services. |
| Telecom Bundle Integration | Triple-play packaging lowers subscriber acquisition costs through unified billing and hardware subsidy structures. |
| Server-Side Ad Insertion Deployment | Programmatic buying integration captures CTV advertising budgets with verified viewability measurement capabilities. |
Research Approach
Coverage spans the United States, United Kingdom, Germany, India, and South Korea, with primary inputs from each market informing demand modeling. The analysis combines interviews with streaming platform executives, broadcast technology directors, telecom bundle strategists, and content licensing specialists alongside secondary validation through FCC filings, Ofcom reports, TRAI tariff orders, and SEC 10-K disclosures. Bottom-up subscriber forecasts triangulate against top-down broadband penetration projections.
Granularity-level modeling disaggregates the analysis window by service type, content economics, and household composition dimensions. CAGRs derive from fitted growth curves calibrated to historical cord-cutting velocity and streaming substitution patterns. Industry-specific inputs encompass exclusive sports rights auction outcomes, fiber-to-the-home deployment schedules, and 5G fixed wireless access coverage expansion.
The model assumes a particular technology adoption path; alternative pathways for cloud gaming convergence or low-earth-orbit satellite distribution would alter the outlook. Forecasts reflect assumptions around regulatory permanence, content licensing cost trajectories, and broadband infrastructure investment continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Pay TV Services Market
Television
Television Broadcasting Services Market
Television
HDTV Market
Television
Cloud Television (TV) Market
Television
Broadcasting and Cable TV Market
Television
Traditional TV and Home Video Market
Television
Pay TV Market
Television
Television and Set Top Box Market
Television
Cloud TV Market
Television
Pay TV Operator Market
Television
Global Digital Terrestrial Television Market
Television
Curved Television Market
Television
Print Newspapers and Magazines Market
Television
Global Broadcast Equipment Market
Television
Digital TV Market
Television
Television Advertising Market