
 Asrs and Ruos Market | 2026-2036
Asrs and Ruos Market Size, Share, and Industry Trends Forecast 2026-2036
Asrs and Ruos Market Analysis
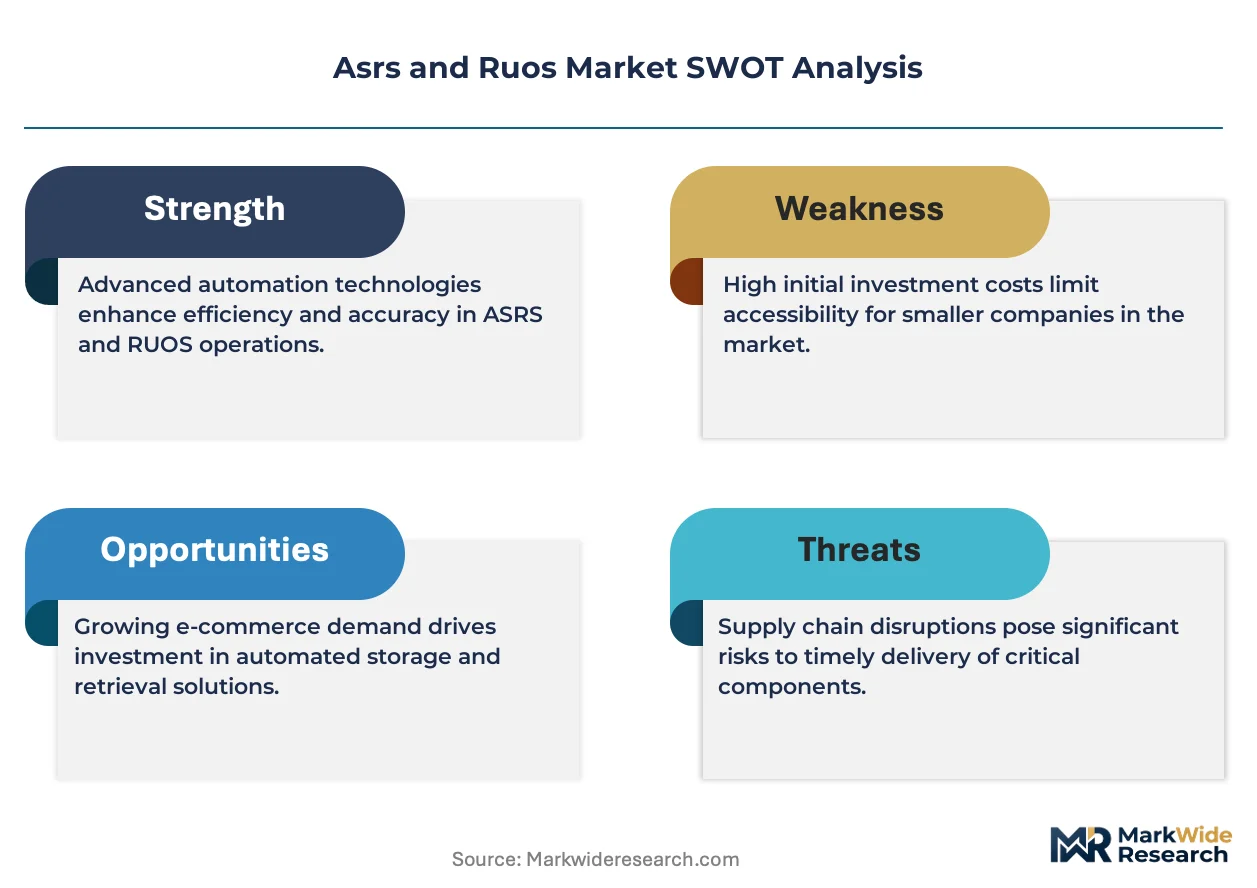
Project finance tied to robotics-as-a-service contracts is narrowing the capital barrier for mid-size warehouse operators seeking automated storage and retrieval systems without upfront equipment ownership. Daifuku Co., Ltd. leverages its vertical integration across conveyor and crane manufacturing to control cost structures in high-bay installations. SSI SCHAEFER anchors its competitive position through dense R&D spending on energy-efficient shuttle technologies. TGW Logistics Group specializes in modular system architectures that allow phased deployment across frozen and ambient temperature zones.
Automated storage and retrieval systems (AS/RS) and robotic unit operations systems (RUOS) encompass crane-based storage racks, shuttle vehicles, robotic picking arms, and associated warehouse control software engineered to move inventory vertically and horizontally with minimal human intervention, typically achieving throughput rates exceeding 200 dual cycles per hour in high-density configurations. These systems serve the core industrial purpose of compressing warehouse footprints while accelerating order cycle times in environments where labor availability constrains operational scaling. Mobile robots within the product type dimension are capturing disproportionate investment as fulfillment networks prioritize flexible aisle navigation over fixed infrastructure. The end user split reveals manufacturing as the most mature revenue pool, while healthcare distribution is emerging as the fastest-growing application due to cold-chain compliance requirements and serialized track-and-trace mandates. Artificial Intelligence and IoT integrations across the technology dimension are concentrating margin pools in predictive maintenance and real-time inventory visibility layers rather than hardware alone.
FDA traceability rules for pharmaceutical distribution and OSHA warehouse safety directives in the United States are accelerating replacement of manual material handling with validated automated systems that generate auditable movement logs. The EU Machinery Directive and CE marking requirements under EMA-aligned good distribution practice standards are shaping product design specifications for European pharmaceutical and food-grade installations. Stakeholders must monitor how evolving energy efficiency standards and battery chemistry regulations for mobile robots affect total cost of ownership calculations across multi-site deployment strategies.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing warehouse design cycles, forcing operators to choose between fixed high-bay crane infrastructure and mobile robot fleets that reconfigure aisle layouts dynamically.
Growth Catalysts
- OSHA warehouse safety mandates:United States operators facing injury exposure liability are accelerating automation procurement to eliminate manual pallet handling in elevated rack zones.
- Pharmaceutical cold-chain serialization:FDA track-and-trace rules for drug distribution require auditable automated movement logs that manual systems cannot generate.
- Shuttle vehicle density gains:Multi-deep storage configurations in German automotive parts distribution are demonstrating throughput rates that justify crane replacement in greenfield sites.
Market Restraints
- Lithium battery supply concentration:Mobile robot fleets depend on cell chemistry sourced from concentrated Asian refining capacity, exposing total cost of ownership to raw material volatility.
- High-bay structural engineering costs:Seismic zone requirements in Japan and California inflate foundation and rack anchoring expenditures beyond mid-size operator budgets.
- EU Machinery Directive compliance friction:CE marking validation for safety-rated collaborative robot arms extends deployment timelines by 8-14 months in European pharmaceutical installations.
Strategic Opportunities
- Robotics-as-a-service penetration:Mid-size third-party logistics operators in the United States are accessing automated storage through opex-based contracts that eliminate upfront capital barriers.
- AI-driven predictive maintenance layering:Convergence of IoT sensor networks with machine learning algorithms is creating recurring revenue streams for system integrators beyond hardware installation.
- Healthcare distribution automation:Hospital pharmacy consolidation in Germany and France is generating demand for validated automated dispensing systems with full batch traceability.
Industry Challenges
- Controls engineering talent scarcity:Warehouse management system integration with programmable logic controllers requires specialists whose availability constrains deployment velocity across North American projects.
- Legacy WMS interoperability:Decades-old enterprise resource planning architectures in manufacturing verticals resist real-time data exchange with modern shuttle control software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asrs and Ruos Market |
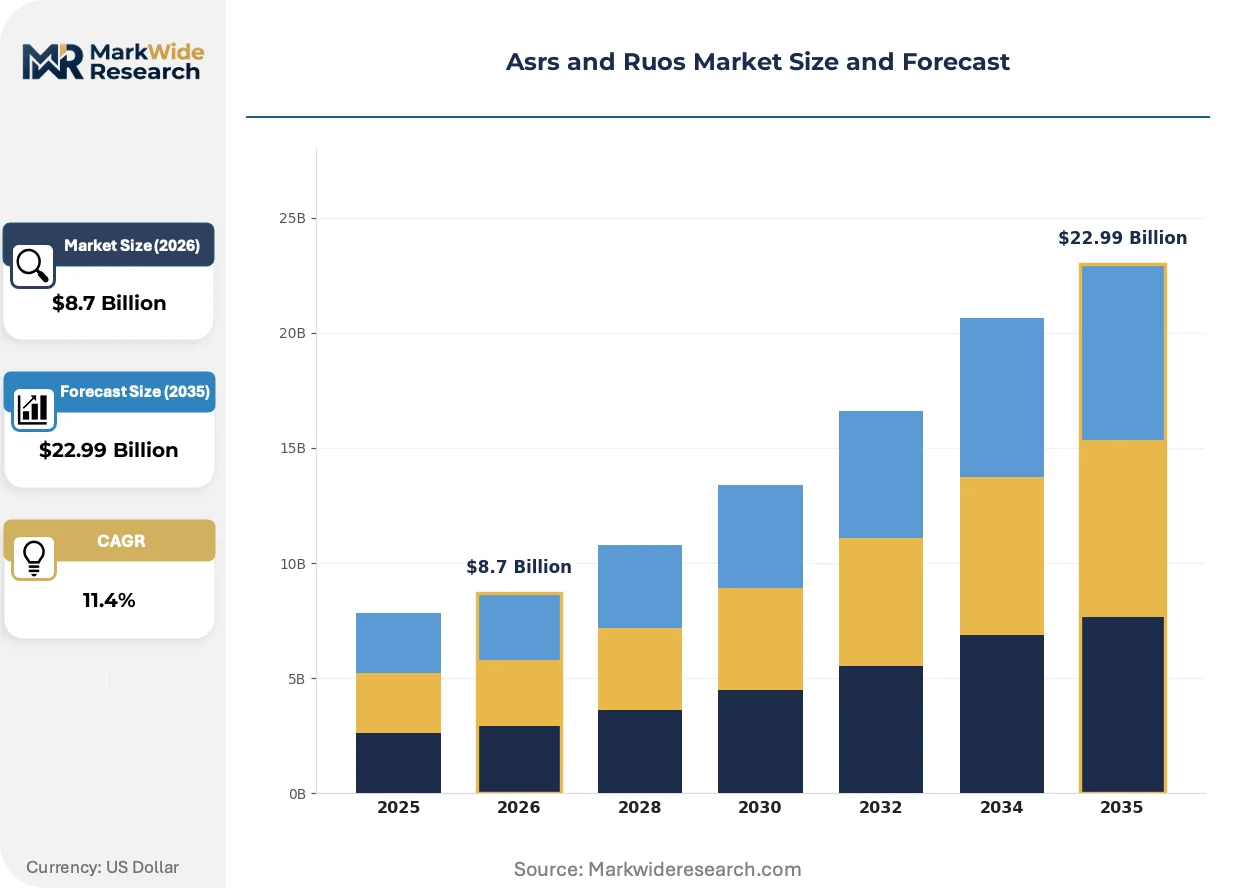
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Storage, Retrieval Systems, Mobile Robots, Sortation Systems End User: Retail, E-commerce, Manufacturing, Healthcare Technology: Artificial Intelligence, Machine Learning, IoT, Robotics Application: Inventory Management, Order Fulfillment, Distribution Centers, Warehousing |
| Companies Covered | Daifuku Co., Ltd., SSI SCHAEFER, TGW Logistics Group, Murata Machinery, Ltd., Kardex Group, KION Group AG, Knapp AG, KUKA AG, Mecalux, S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asrs and Ruos Market Emerging Trajectories
Autonomous mobile robots are displacing fixed conveyor backbones in fulfillment architectures, enabling operators to reconfigure flow paths without structural demolition. This shift is compressing facility modification costs while extending system functional lifespans.
Shuttle-based storage technology is hybridizing crane density with robot flexibility. These systems combine vertical lift modules with autonomous cart movement, allowing pharmaceutical distributors in Switzerland and Germany to achieve dual-cycle rates exceeding 200 moves hourly while retaining aisle reconfiguration capability. The hybrid architecture is enabling brownfield warehouse retrofits that fixed crane systems could not accommodate.
EMA-aligned good distribution practice standards under the EU Machinery Directive are mandating validated software documentation for automated pharmaceutical handling. Installers must now submit functional safety assessments and electromagnetic compatibility certifications before operational commissioning. Cold-chain operators in the Netherlands and Belgium are responding by pre-qualifying integrators with existing CE-marked control system portfolios.
Third-party logistics buyers are unbundling after-sales service contracts from initial system procurement. Large e-commerce operators in the United States now separately negotiate predictive maintenance subscriptions and spare parts logistics, treating automation vendors as ongoing service partners rather than one-time equipment suppliers. This behavioral shift is most visible among multi-site retail fulfillment networks seeking standardized uptime guarantees across distributed footprints.
Asrs and Ruos Market Segmentation
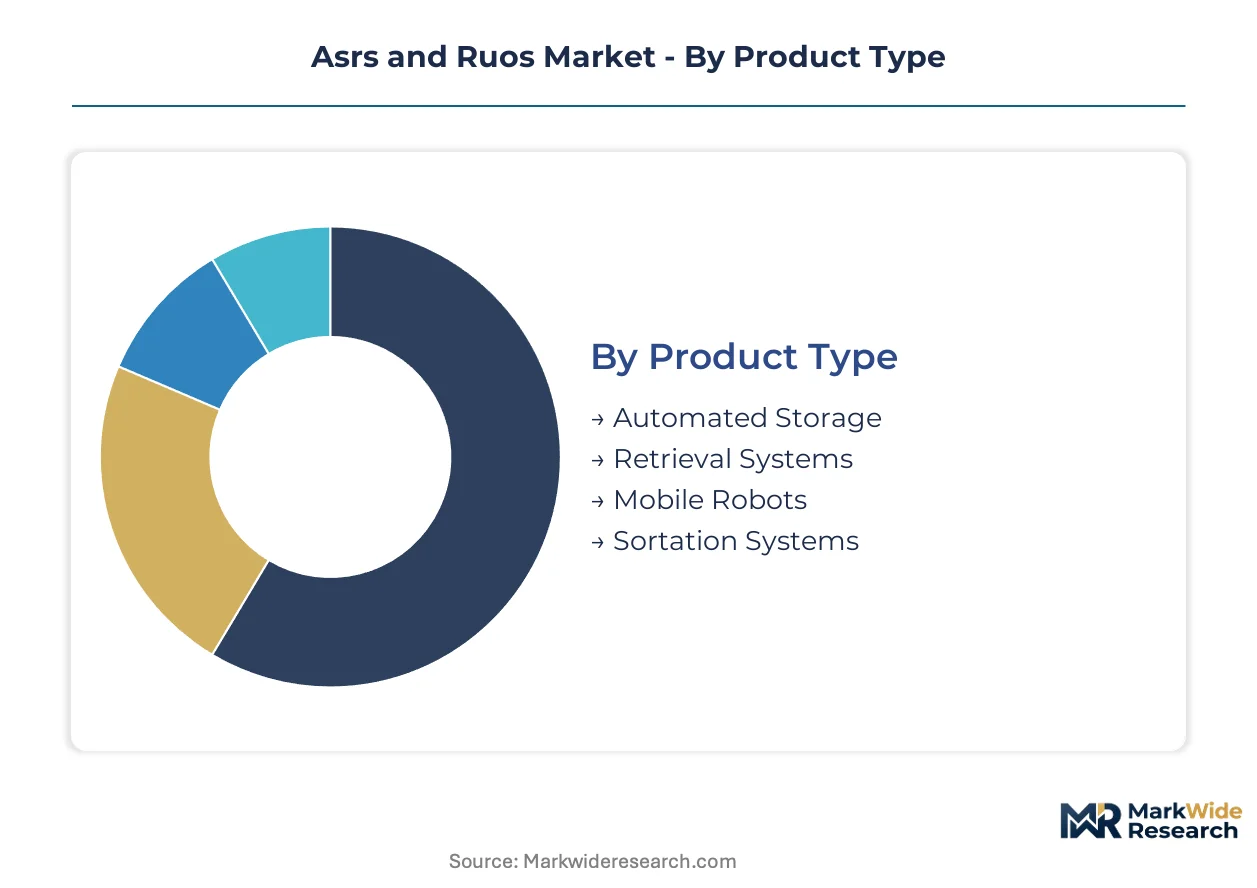
Segmentation in the Asrs and Ruos Market reveals how cycle-time requirements differ sharply across deployment contexts. Pharmaceutical cold-chain operations demand validated systems with 99.99% uptime guarantees, while e-commerce fulfillment prioritizes reconfigurable throughput over certification depth.
Product Type:
Cycle-time compression varies dramatically by mechanical architecture—fixed crane systems deliver sustained dual-cycle rates above 200 hourly in stable demand environments, while mobile robot fleets sacrifice peak throughput for aisle reconfiguration agility during seasonal spikes.
- Automated Storage:Vertical lift modules and high-bay rack structures engineered for dense cubic utilization in seismic-rated configurations. German automotive parts distributors in Stuttgart and Wolfsburg deploy these systems to achieve floor-space compression ratios exceeding 5:1 against conventional warehousing.
- Retrieval Systems:Crane-based extractors and shuttle vehicles operating on fixed rail infrastructure with programmable acceleration curves. Cold-chain operators in the Netherlands face extended commissioning timelines due to EMA-aligned validation requirements for pharmaceutical movement logs.
- Mobile Robots:Autonomous cart fleets with lithium traction batteries enabling dynamic aisle navigation without structural anchoring.
- Sortation Systems:Cross-belt and tilt-tray conveyors handling parcel singulation at e-commerce hub velocities.
Automated Storage dominates installed base. Mobile Robots is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive validated deployments from volume-driven operational efficiency plays—healthcare and pharmaceutical networks absorb premium pricing for compliance documentation, while retail operators prioritize unit economics per pick.
- Retail:Department store and big-box chains requiring seasonal surge capacity with modular system expansion clauses. United States operators in California and Texas are unbundling maintenance contracts from initial procurement to preserve cash flow flexibility.
- E-commerce:Direct-to-consumer fulfillment networks with same-day delivery SLAs driving shuttle density investments. Amazon and Shopify-enabled third-party logistics providers in Pennsylvania and Ohio are displacing fixed conveyor backbones with autonomous mobile robot fleets.
- Manufacturing:Just-in-time component feeding for assembly lines with tolerance for longer integration timelines.
- Healthcare:Hospital pharmacy and medical device distribution requiring FDA 21 CFR Part 11 compliant audit trails.
Manufacturing dominates installed base. Healthcare is expanding most quickly.
Technology:
Margin pools concentrate in software layers that extract predictive value from hardware sensor streams, with AI-driven maintenance subscriptions capturing recurring revenue beyond one-time system sales.
- Artificial Intelligence:Machine vision algorithms for damage detection and pick-point calibration in variable lighting conditions. Swiss pharmaceutical distributors in Basel leverage these systems to reduce mis-pick rates below 0.01% in validated cold-chain environments.
- Machine Learning:Demand forecasting models optimizing shuttle allocation across multi-deep storage configurations. French hospital pharmacy consolidations in Lyon and Marseille deploy these tools to predict inventory velocity patterns for automated dispensing cabinets.
- IoT:Sensor networks generating real-time rack occupancy and equipment health telemetry.
- Robotics:Collaborative arm systems for piece-picking in heterogeneous SKU environments.
Robotics dominates installed base. Artificial Intelligence is gaining share fastest.
Application:
Geographic clustering reflects regulatory intensity—pharmaceutical distribution mandates auditable movement logs, while general warehousing prioritizes throughput per square meter without validation overhead.
- Inventory Management:Real-time location tracking with RFID and vision-based cycle counting for perpetual inventory accuracy. Belgian cold-chain operators in Antwerp combine these capabilities with EMA good distribution practice documentation for vaccine distribution networks.
- Order Fulfillment:Pick-to-light and goods-to-person workstations compressing order cycle times below 15 minutes. Japanese e-commerce operators in Osaka face seismic engineering premiums that inflate high-bay foundation costs beyond mid-size operator budgets.
- Distribution Centers:Cross-dock and flow-through facilities handling mixed-case deconsolidation.
- Warehousing:Long-term storage with retrieval optimization for slow-moving inventory categories.
Warehousing dominates installed base. Order Fulfillment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA warehouse safety mandates and FDA pharmaceutical traceability rules are accelerating automated storage procurement across concentrated industrial clusters. Capital deployment patterns reflect regulatory intensity rather than pure throughput economics.
United States
E-commerce fulfillment networks in Pennsylvania and Ohio are displacing fixed conveyor systems with autonomous mobile robot fleets to meet same-day delivery SLAs. OSHA injury exposure liability rules are eliminating manual pallet handling in elevated rack zones. Third-party logistics operators in Texas and California are unbundling maintenance contracts from initial procurement to preserve cash flow flexibility.
Germany
Automotive parts distributors in Stuttgart and Wolfsburg deploy high-bay rack structures achieving floor-space compression ratios exceeding 5:1 against conventional warehousing. The EU Machinery Directive and CE marking requirements under EMA-aligned good distribution practice standards shape product design specifications. Hospital pharmacy consolidation in Berlin and Munich generates demand for validated automated dispensing systems with full batch traceability.
Japan
Seismic zone requirements inflate foundation and rack anchoring expenditures beyond mid-size operator budgets in Osaka and Nagoya industrial corridors. METI industrial automation incentives support retrofit investments in brownfield manufacturing facilities. E-commerce operators in the Kanto region face structural engineering premiums that constrain high-bay adoption relative to mobile robot alternatives.
Switzerland
Pharmaceutical distributors in Basel leverage machine vision algorithms to reduce mis-pick rates below 0.01% in validated cold-chain environments. Swissmedic and EMA-aligned documentation requirements mandate pre-qualified integrators with existing CE-marked control system portfolios. Dense vertical storage configurations serve pharmaceutical and precision manufacturing clusters around Zurich and Geneva.
Netherlands
Cold-chain operators in Antwerp combine RFID-based inventory tracking with EMA good distribution practice documentation for vaccine distribution networks. Extended commissioning timelines result from validation requirements for pharmaceutical movement logs. Belgian and Dutch logistics hubs are pre-qualifying system integrators to accelerate deployment timelines under EU regulatory frameworks.
Asrs and Ruos Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates margin pools in software and service layers rather than hardware alone. The competitive terrain separates vertically integrated system integrators from modular component suppliers and robotics-as-a-service operators. Two strategic archetypes dominate: full-stack warehouse automation providers and specialized shuttle or mobile robot technology developers. Competitive moves center on predictive maintenance subscription models and unbundled after-sales service contracts that transform equipment vendors into ongoing operational partners.
Within the integrated-system tier, Daifuku Co., Ltd. and SSI SCHAEFER exemplify contrasting approaches to cost control and technology positioning. Daifuku represents the vertically integrated archetype with captive manufacturing of conveyors and crane infrastructure. SSI SCHAEFER occupies a position emphasizing energy-efficient shuttle technologies through sustained R&D concentration. TGW Logistics Group anchors the modular-specialist segment with system architectures permitting phased deployment across temperature zones.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| SSI SCHAEFER |
| TGW Logistics Group |
| Murata Machinery, Ltd. |
| Kardex Group |
| KION Group AG |
| Knapp AG |
| KUKA AG |
| Mecalux, S.A. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese lithium refining capacity is pressuring mobile robot OEMs to absorb cell cost volatility through extended supplier financing, while German high-bay crane manufacturers leverage captive steel fabrication to defend margin structures against raw material spikes.
Pricing Analysis
Certification level (FDA-grade, CE-marked, non-validated) creates the primary spread between system tiers, with pharmaceutical cold-chain installations commanding three to five times the unit economics of general warehousing deployments. Three-tier pricing structure across premium validated, standard industrial, and economy retrofit levels reflects documentation depth and uptime guarantee differentiation. Pricing pressure stems from robotics-as-a-service contract proliferation, which compresses upfront hardware margins in favor of recurring service streams. Mid-size third-party logistics operators in the United States exhibit highest price sensitivity, while healthcare networks in Switzerland and Germany absorb premium tiers for traceability compliance.
Supply Chain Analysis
Extended payment terms from German automotive distributors and supply-chain finance facilities anchored in Netherlands logistics hubs are restructuring working capital flows across crane and shuttle component tiers. Lithium cell production concentrates in China, South Korea, and Japan, while precision rack fabrication draws from German and Austrian steel processing. Mobile robot fleets hinge on rare earth magnet supply from concentrated Asian refining capacity. Single-source vulnerability in semiconductor motor controllers creates exposure to foundry allocation disruptions. Distribution runs through system integrator channels that bundle installation, validation, and aftermarket service into project contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates sticky customer relationships—FDA and EMA validation requirements generate switching costs that protect incumbent positions across multi-site healthcare deployments.
For Market Incumbents: Harden predictive maintenance subscription attach rates to lock in recurring revenue streams and dilute pure-hardware margin pressure from emerging robotics-as-a-service entrants. Deepen backward integration into shuttle battery pack assembly to mitigate lithium supply concentration risk. Fortify CE-marked control system portfolios to accelerate European pharmaceutical commissioning timelines against modular-specialist competitors. For New Entrants and Emerging Players: Build out AI-driven inventory visibility software layers that unbundle from hardware procurement, targeting mid-size United States e-commerce operators seeking opex-based automation access. White-space concentration sits in brownfield warehouse retrofit applications where hybrid shuttle-crane architectures displace fixed infrastructure without structural demolition. Lead with phased deployment capabilities across ambient and frozen temperature zones to penetrate food-grade distribution networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among system integrators with predictive maintenance platforms and multi-site service contracts, positioning these archetypes for premium valuation multiples. Long-term viability favors vendors with validated pharmaceutical track records and software subscription traction over pure hardware manufacturers. Monitor lithium supply contract renegotiation patterns as inflection signal for mobile robot fleet expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics-as-a-Service Platform Launch | Enables mid-size operators to access automation without capital ownership barriers. |
| Predictive Maintenance Subscription Buildout | Creates recurring revenue streams beyond one-time hardware installation for integrators. |
| CE-Marked Control System Pre-Qualification | Accelerates European pharmaceutical deployment timelines under EMA validation requirements. |
| Hybrid Shuttle-Crane Architecture Development | Captures brownfield retrofit demand that fixed high-bay systems cannot accommodate. |
| AI-Driven Inventory Visibility Layer Investment | Concentrates margin pools in software rather than commoditized hardware components. |
Methodological Framework
Cross-validation between executive interviews at Daifuku, SSI SCHAEFER, and TGW Logistics Group and secondary analysis of SEC filings, EU Machinery Directive implementation records, and OSHA enforcement databases anchors the qualitative findings. Primary fieldwork encompassed warehouse operations directors, pharmaceutical distribution compliance officers, robotics procurement leads at third-party logistics providers, and aftermarket service heads. Bottom-up shipment data from crane, shuttle, and mobile robot manufacturers triangulates against top-down capital expenditure tracking across e-commerce, automotive, and healthcare verticals.
Calibration against historical adoption curves in German automotive parts distribution and United States pharmaceutical cold-chain networks informs the projection framework across the analysis window. Segmentation dimensions span product type (automated storage, retrieval systems, mobile robots, sortation), end user (retail, e-commerce, manufacturing, healthcare), technology layer (AI, machine learning, IoT, robotics), and application context (inventory management, order fulfillment, distribution, warehousing). CAGR derivation incorporates equipment replacement cycles, regulatory mandate effective dates, and lithium battery cost trajectory assumptions.
Sensitivities concentrate around OSHA enforcement intensity shifts, EMA validation timeline extensions, and lithium supply contract renegotiation patterns. Forecasts reflect documented assumptions regarding robotics-as-a-service penetration rates and hybrid architecture adoption curves. Macroeconomic contraction, regulatory deviation, or battery chemistry disruption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Harvesting Robot Market
Robotics and Automation
Commercial Robots Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Rotary Gripper Module Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Global Soldering Robot Market
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Smart Lawn Robot Market
Robotics and Automation
Robot Fleet Management Software Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market