
 Europe AUV and ROV Market | 2026-2036
Europe AUV and ROV Market Size, Share, and Industry Trends Forecast 2026-2036
Europe AUV and ROV Market Foresight
The buyer base for underwater robotics across Europe is broadening as national navies, offshore wind developers, and marine research institutes fragment procurement across specialized platforms rather than consolidating with single vendors. Kongsberg leverages its Norwegian heritage to dominate autonomous navigation systems for defense and energy clients. Saab AB competes through sustained R&D intensity in military-grade underwater communication. Exail Technologies anchors its position in acoustic sensor integration for seabed mapping applications.
Autonomous underwater vehicles, remotely operated vehicles, hybrid systems, and their support vessels constitute a class of uncrewed marine platforms engineered for depths exceeding 3,000 meters, utilizing pressure-resistant hull composites, tethered or battery-electric power architectures, and real-time acoustic data links to execute inspection, surveying, and intervention tasks in environments hostile to human divers. ROV platforms occupy the largest installed base across European offshore oil and gas fields, where mature tethered architectures satisfy routine maintenance cycles with predictable operational expenditure. AUV segments are recording the fastest expansion in offshore wind, where autonomous navigation eliminates surface vessel dependency and reduces charter costs for array cable surveys.
EMA's medical device oversight extends to subsea imaging equipment deployed in pharmaceutical cold-chain monitoring, while REACH compliance governs the composite resins and coatings used in pressure vessel manufacturing across European supply chains. The EU AI Act introduces conformity requirements for autonomous decision-making algorithms in uncrewed underwater systems, affecting product development timelines for navigation software providers. Stakeholders must monitor how classification societies adapt certification frameworks for resident underwater vehicles operating without continuous surface supervision.
Market Dynamics
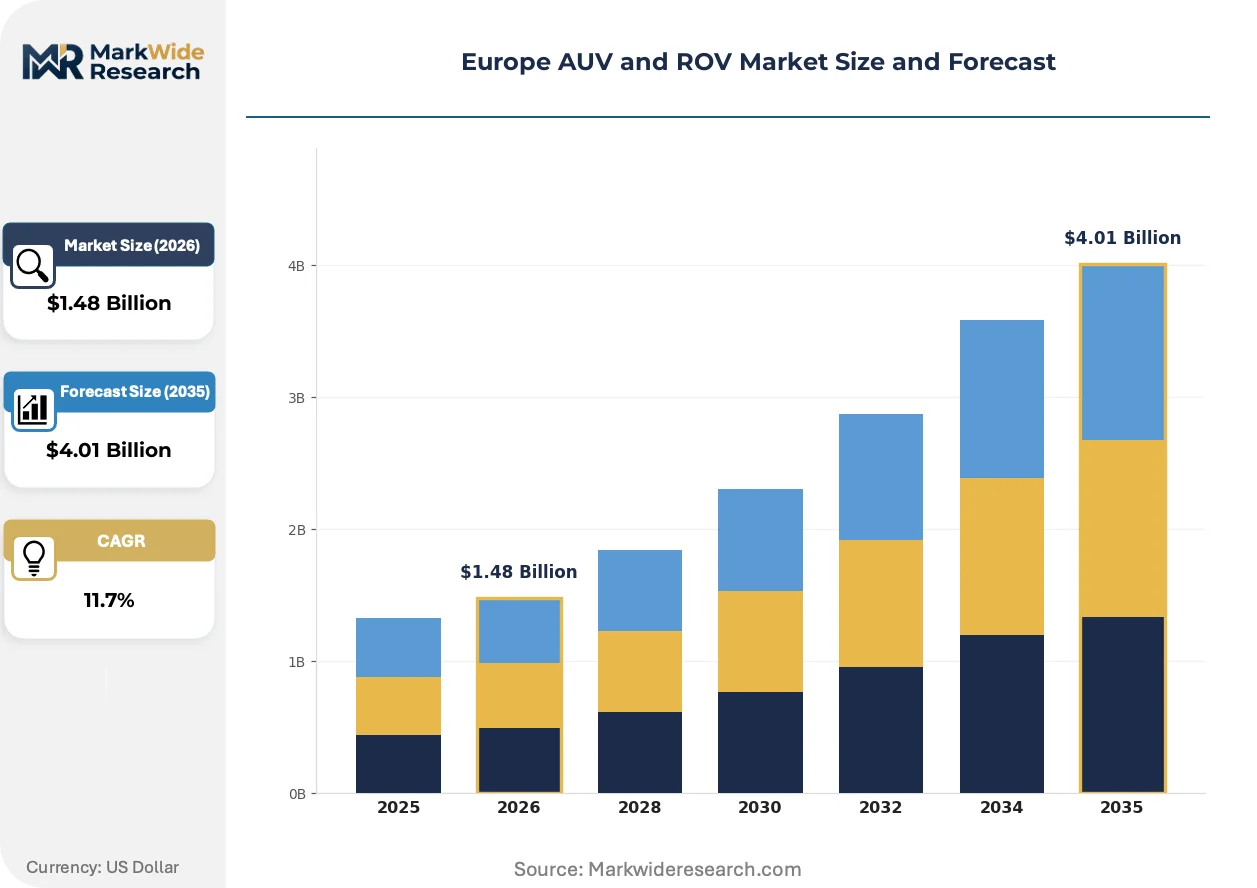
The offshore wind buildout across the North Sea is compressing survey timelines and forcing operators to abandon vessel-tethered ROV architectures in favor of autonomous platforms that eliminate surface dependency and weather downtime.
Growth Catalysts
- EU Green Deal decarbonization mandates:Offshore wind developers in the North Sea face binding emission reduction targets that favor battery-electric AUVs over diesel-powered surface support fleets for array cable installation verification.
- Resident monitoring architectures:Subsea docking stations enable continuous field presence without vessel recall, reducing operational expenditure for infrastructure integrity management in Norwegian deepwater fields.
- F-Gas Regulation phase-down:Restrictions on hydrofluorocarbon propellants accelerate conversion to all-electric hydraulic alternatives in work-class ROV systems deployed across European offshore energy zones.
Market Restraints
- Composite pressure hull supply concentration:Carbon fiber filament winding capacity for 6,000-meter-rated vessels concentrates among specialized German and Italian Tier-2 suppliers, creating single-source vulnerability for AUV manufacturers.
- Acoustic modem interoperability gaps:Proprietary seabed communication protocols from dominant navigation vendors lock end-users into captive sensor ecosystems, raising switching costs for mixed-fleet operators.
- Lithium-thionyl chloride battery chemistry limitations:Energy density constraints restrict mission endurance for deepwater survey AUVs, forcing frequent recovery cycles that offset autonomy benefits in extended-range applications.
Strategic Opportunities
- Polish and Baltic offshore wind pipeline:Emerging lease rounds in the Baltic Sea create first-mover positioning for AUV service providers establishing resident survey capacity ahead of array construction.
- EU AI Act algorithmic conformity pathways:Early certification of autonomous decision-making software for collision avoidance and seabed navigation creates regulatory moats for compliant platform vendors.
- Hybrid ROV-AUV convergence:Tether-free intervention systems combining autonomous transit with remote manipulation unlock inspection-repair workflows in floating offshore wind substructures where diver access is prohibited.
Industry Challenges
- Subsea robotics engineering talent scarcity:Cross-disciplinary expertise spanning hydrodynamics, acoustic signal processing, and marine corrosion science concentrates among aging workforces in Norway and Scotland, constraining platform development velocity.
- Resident vehicle classification gaps:Classification societies lack standardized frameworks for certifying unsupervised subsea systems, delaying insurance coverage and operator acceptance of continuous-deployment architectures.
- Seabed sensor fusion complexity:Integrating multibeam sonar, sub-bottom profiler, and magnetic anomaly detection outputs into unified geophysical models demands specialized data science capabilities absent from traditional survey contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe AUV and ROV Market |
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $4.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AUV, ROV, Hybrid Systems, Support Vessels End User: Military, Oil & Gas, Marine Research, Environmental Monitoring Technology: Autonomous Navigation, Imaging Systems, Acoustic Sensors, Communication Tools Application: Inspection, Surveying, Data Collection, Maintenance |
| Companies Covered | Exail Technologies, RTsys, Kongsberg, L3Harris Technologies, Teledyne Marine, Saab AB, Saipem S.p.A, General Dynamics Mission Systems, BAE Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe AUV and ROV Market Shifts & Advancements
Autonomous navigation architectures are compressing the traditional vessel-ROV survey model, while regulatory pressure on subsea emissions and algorithmic accountability rewrites procurement criteria across European offshore sectors.
Artificial intelligence-based path planning is overtaking pre-programmed waypoint missions in commercial AUV deployments. Offshore wind developers in the North Sea are adopting real-time seabed adaptation for cable route optimization. This capability is overtaking static survey designs that cannot respond to unexpected geohazards without surface intervention.
The EU AI Act imposes conformity assessment requirements on autonomous decision-making algorithms in uncrewed underwater systems. Navigation software providers must now document risk management systems and data governance protocols before CE marking. Deepwater oil and gas operators in Norwegian waters face the steepest compliance timelines given the complexity of resident vehicle supervision architectures.
Charter contracting for survey vessels is fragmenting into discrete mission-based engagements rather than multi-year fixtures. Offshore wind developers now source AUV services through specialized unmanned marine contractors rather than integrated oilfield service majors. This pattern concentrates in the UK and Denmark where project finance structures favor operational expenditure over capital ownership.
Europe AUV and ROV Market Segmentation
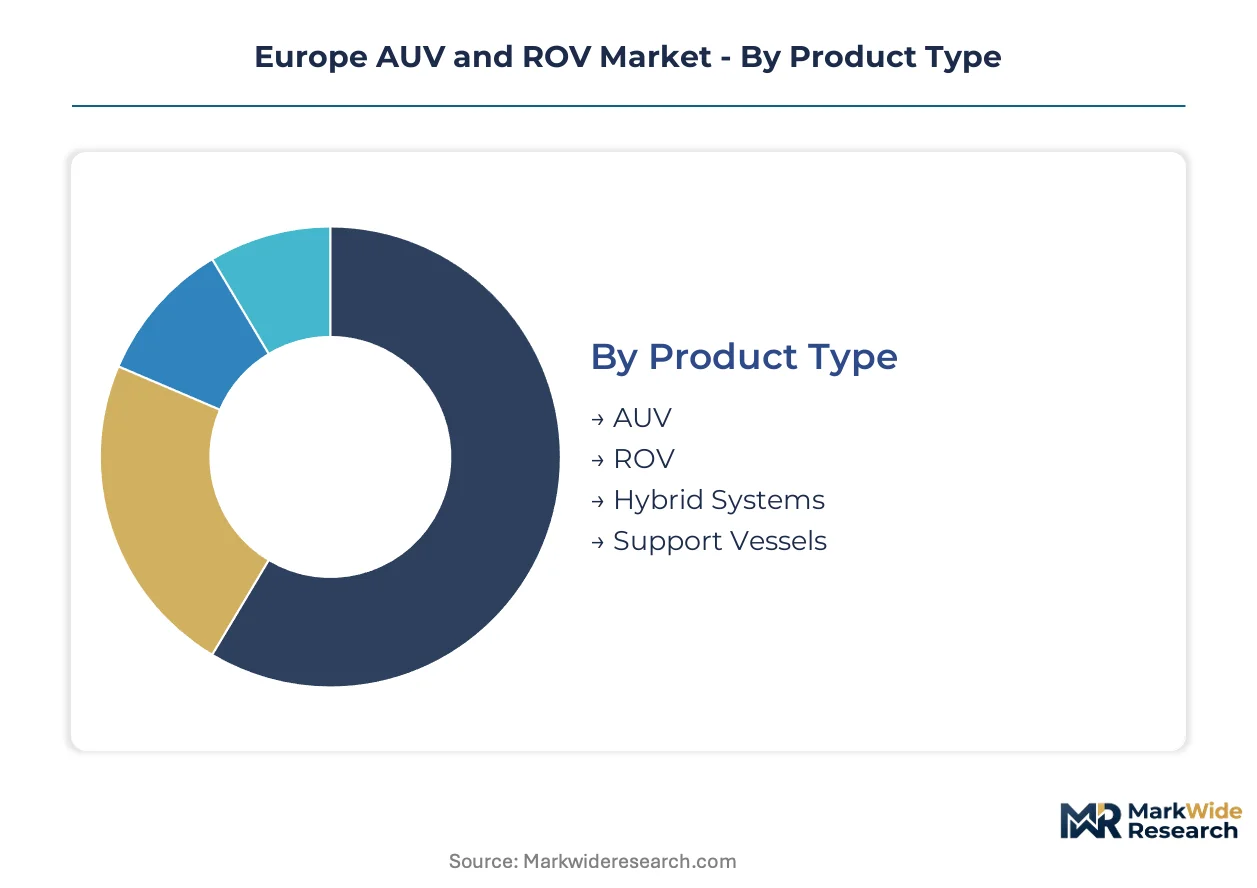
Platform specialization across European waters demands granular segmentation. Procurement patterns diverge sharply between defense integrators seeking resident military systems and offshore wind developers optimizing survey economics through service-based AUV contracts.
Product Type:
Upgrade cycles for uncrewed marine platforms accelerate as battery energy density improves and acoustic modem bandwidth expands. Operators retiring 1990s-era ROV architectures face capital allocation decisions between tethered replacement and autonomous migration.
- AUV:Battery-electric hulls with autonomous navigation eliminate surface vessel dependency for seabed survey missions. North Sea offshore wind developers favor these platforms for array cable route verification, cutting charter expenditure and weather exposure compared to ROV-tethered operations.
- ROV:Tethered architectures with real-time pilot control dominate intervention-heavy workflows in Norwegian deepwater oil and gas fields. Mature hydraulic manipulator ecosystems and predictable operational expenditure sustain installed base retention despite autonomy competition.
- Hybrid Systems:Tether-free transit with remote manipulation capability bridges inspection and light intervention in floating offshore wind substructures.
- Support Vessels:Uncrewed surface platforms and reduced-crew designs extend AUV endurance through at-sea battery swap and data offload.
ROV platforms sit at the top of the volume ranking, with AUV climbing the fastest.
End User:
Customer procurement maturity varies dramatically across sectors. Defense buyers specify multi-decade service life and acoustic stealth, while commercial operators prioritize mission economics and rapid technology refresh.
- Oil & Gas:Norwegian deepwater operators including Equinor and Aker BP drive resident system adoption for continuous field monitoring. Subsea docking stations reduce vessel recall frequency, compressing operational expenditure for infrastructure integrity management.
- Marine Research:Institutes deploy long-endurance AUVs for repeatable seabed mapping campaigns requiring precision navigation without surface tracking.
- Military:Naval forces specify mine countermeasures and seabed warfare platforms with low-acoustic-signature propulsion and encrypted communication links.
- Environmental Monitoring:Regulatory compliance drives deployment for subsea noise monitoring and cold-chain verification in pharmaceutical logistics.
Oil and Gas commands the largest procurement budget, with Environmental Monitoring expanding most quickly.
Technology:
Technology stack decisions lock in vendor ecosystems for operational life. Acoustic modem protocol choices create switching costs that persist across platform generations.
- Autonomous Navigation:AI-based path planning with real-time seabed adaptation overtakes pre-programmed waypoint missions. EU AI Act conformity requirements for collision avoidance algorithms impose documentation burdens on software providers seeking CE marking.
- Acoustic Sensors:Multibeam sonar and sub-bottom profiler integration demands specialized data science capabilities for unified geophysical model construction.
- Imaging Systems:Subsea cameras and laser scanners support visual inspection workflows in turbid North Sea conditions.
- Communication Tools:Seabed-to-surface acoustic modem links and satellite relay architectures enable command telemetry in beyond-visual-range operations.
Autonomous Navigation leads technology investment, with Acoustic Sensors gaining share fastest.
Application:
Application scope determines platform specification intensity. Inspection and maintenance workflows demand manipulator dexterity, while survey missions prioritize navigation precision and sensor payload capacity.
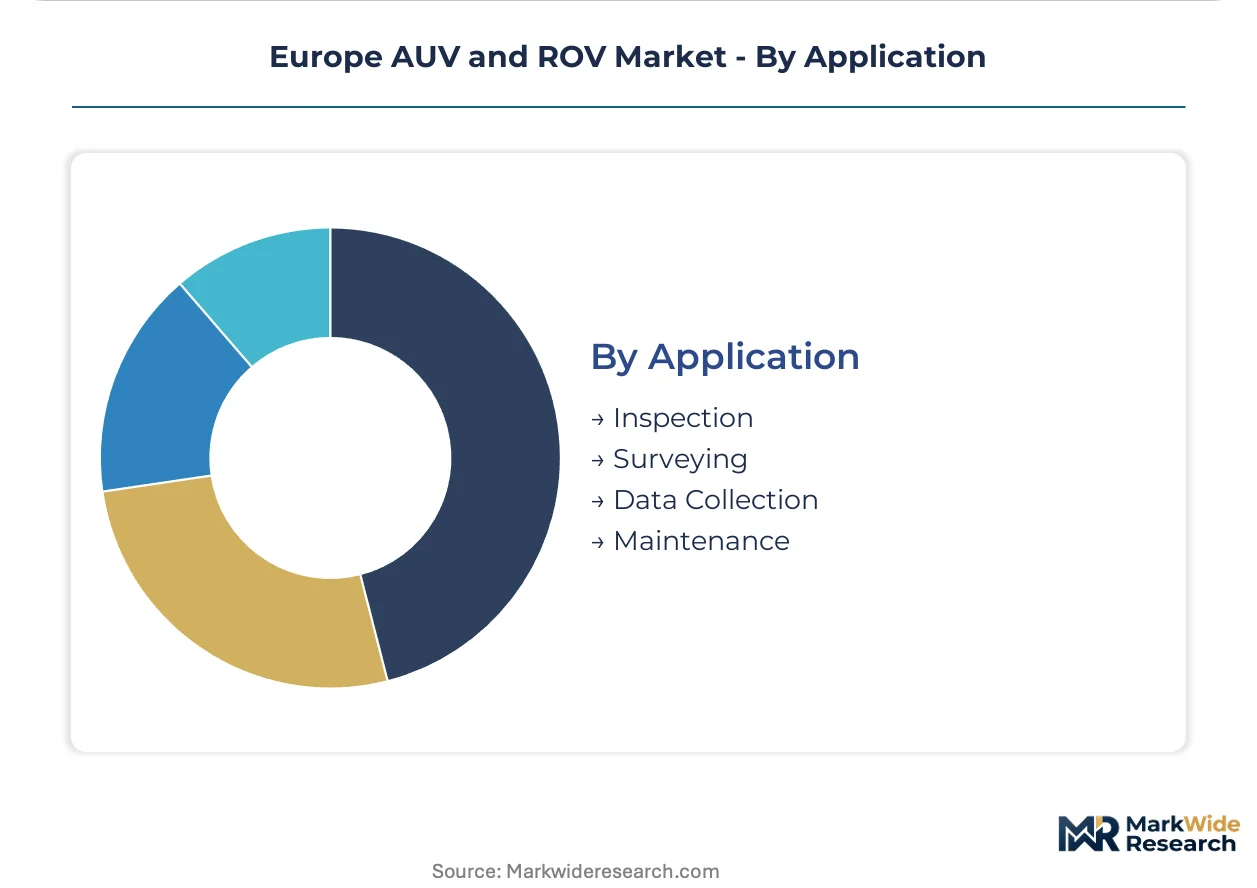
- Surveying:Geophysical and geotechnical seabed characterization for offshore wind foundation design requires integrated multibeam, magnetometer, and sub-bottom profiler payloads. Baltic Sea lease rounds in Polish waters create first-mover positioning for resident survey capacity.
- Inspection:Visual and ultrasonic examination of subsea infrastructure, pipelines, and cables sustains ROV demand in mature North Sea oil and gas assets.
- Data Collection:Oceanographic sensor deployment and seabed sample retrieval support climate research and resource assessment missions.
- Maintenance:Light intervention including valve operation and anode replacement pushes toward hybrid ROV-AUV architectures with remote manipulation.
Surveying dominates mission hours, with Maintenance showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway deploys resident ROV systems for continuous North Sea field monitoring while Poland accelerates Baltic offshore wind leasing that demands autonomous survey capacity.
Norway
Equinor and Aker BP drive resident system procurement for subsea infrastructure integrity management. The F-Gas Regulation accelerates conversion to all-electric hydraulic alternatives in work-class ROV architectures. Stavanger anchors a concentration of subsea robotics engineering talent spanning hydrodynamics and acoustic signal processing disciplines.
United Kingdom
Offshore wind developers in the North Sea favor AUV services through specialized unmanned marine contractors rather than integrated oilfield service majors. The EU AI Act imposes conformity assessment requirements on autonomous navigation algorithms affecting software providers seeking CE marking. Aberdeen sustains ROV demand for visual inspection of mature subsea pipelines and cables.
Germany
Carbon fiber filament winding capacity for 6,000-meter-rated pressure hulls concentrates among specialized Tier-2 suppliers serving AUV manufacturers. REACH compliance governs composite resins and coatings used in pressure vessel manufacturing across European supply chains. Hamburg hosts engineering clusters focused on battery-electric propulsion system integration.
Poland
Emerging Baltic Sea lease rounds create first-mover positioning for AUV service providers establishing resident survey capacity ahead of array construction. The EU Green Deal decarbonization mandates favor battery-electric platforms over diesel-powered surface support fleets for cable installation verification. Gdańsk and Szczecin port clusters attract autonomous platform operators positioning for construction-phase survey contracts.
France
Naval forces specify mine countermeasures and seabed warfare platforms with low-acoustic-signature propulsion systems. EMA medical device oversight extends to subsea imaging equipment deployed in pharmaceutical cold-chain monitoring applications. Toulon and Brest harbor defense-focused underwater robotics development clusters serving military procurement specifications.
Europe AUV and ROV Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across European uncrewed marine platform supply. The vendor base stratifies between defense integrators with multi-decade service life specifications and commercial operators prioritizing mission economics. Three archetypes dominate: Norwegian heritage navigation houses, French acoustic sensor integrators, and Anglo-American defense conglomerates with underwater warfare divisions. Competitive moves concentrate on strategic partnerships for resident system architectures and technology licensing for AI-based path planning algorithms.
Among Norwegian-origin platform specialists, Kongsberg and Exail Technologies exemplify heritage-driven positioning in autonomous navigation and acoustic sensor integration respectively. Saab AB anchors the defense-specialist tier with sustained engineering intensity in military-grade underwater communication. These three entities represent distinct competitive vectors: Kongsberg leverages geographic proximity to North Sea offshore energy operators, Exail Technologies concentrates seabed mapping sensor fusion capabilities, and Saab AB occupies the naval procurement channel with encrypted communication link specifications.
| Leading Market Players |
|---|
| Exail Technologies |
| RTsys |
| Kongsberg |
| L3Harris Technologies |
| Teledyne Marine |
| Saab AB |
| Saipem S.p.A |
| General Dynamics Mission Systems |
| BAE Systems |
| Others |
Supply & Pricing Matrix
All-electric hydraulic conversion under the EU F-Gas Regulation is simultaneously elevating production costs for work-class ROV manufacturers and concentrating procurement leverage among German and Italian carbon fiber specialists capable of certifying 6,000-meter-rated pressure hulls. Battery-electric propulsion system integration adds cost premiums that platform vendors must recover through service-based contracting models with North Sea offshore wind developers.
Pricing Analysis
Capacity additions in Germany and Italy are reshaping price floors for high-performance composite pressure hulls while Norwegian engineering clusters maintain premium positioning in autonomous navigation software. Three-tier pricing structure across premium certified-grade, standard commercial-grade, and economy survey-grade platforms dominates procurement. Price differentiation hinges on CE marking tier for autonomous algorithms and volume scale of vessel charter commitments. Cost compression in standard-grade AUV services is intensifying because Polish and Baltic offshore wind developers are consolidating survey contracts with unmanned marine contractors. Environmental monitoring buyers exhibit highest price sensitivity due to grant-dependent funding cycles, while Norwegian oil and gas operators show lowest sensitivity given operational expenditure prioritization over capital ownership.
Supply Chain Analysis
CE marking and EU AI Act algorithmic conformity requirements gate entry for navigation software providers seeking access to European defense and energy procurement channels. Geographic supply concentration centers on Germany and Italy for carbon fiber filament winding capacity, Norway for hydrodynamics engineering talent, and France for acoustic sensor integration. Raw material dependencies encompass lithium-thionyl chloride battery cells, pressure-resistant composite resins governed by REACH compliance, and specialized acoustic modem chipsets. Single-source vulnerability in Tier-2 carbon fiber suppliers creates structural risk for AUV manufacturers dependent on deepwater-rated hull architectures. Distribution runs through specialized unmanned marine contractors rather than integrated oilfield service majors for offshore wind survey missions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in autonomous navigation software tiers where EU AI Act conformity creates regulatory moats, and in resident system architectures that eliminate surface vessel dependency for Norwegian deepwater operators. Battery energy density improvements and acoustic modem bandwidth expansion are compressing platform lifecycle costs while enabling premium service-based pricing.
For Market Incumbents: Extend resident ROV-AUV docking station networks across Norwegian and UK North Sea fields to lock in continuous field monitoring contracts before classification society frameworks mature. Acquire specialized German or Italian carbon fiber filament winding capacity to secure pressure hull supply against single-source vulnerability. Invest in EU AI Act documentation protocols for collision avoidance algorithms to maintain CE marking access as compliance timelines tighten for deepwater oil and gas operators.
For New Entrants and Emerging Players: Baltic Sea offshore wind developers represent the most penetrable buyer archetype as Polish lease rounds accelerate ahead of resident survey capacity establishment. Target environmental monitoring institutes with long-endurance AUV offerings for repeatable seabed mapping campaigns requiring precision navigation without surface tracking. Pursue technology licensing partnerships with established acoustic sensor integrators rather than building proprietary seabed communication protocols from inception.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap unmanned marine contractors with established Polish or Baltic port positioning ahead of construction-phase survey contract awards. Long-term viability favors platform vendors with demonstrated EU AI Act conformity pathways and resident system deployment experience in Norwegian waters. Watch classification society publication of standardized unsupervised subsea system certification frameworks as the critical inflection indicator for insurance coverage and operator acceptance of continuous-deployment architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Resident System Architecture Deployment | Subsea docking stations in Norwegian waters eliminate surface vessel recall frequency for Equinor and Aker BP. |
| EU AI Act Algorithmic Conformity Investment | CE marking pathways for collision avoidance software create regulatory moats against non-compliant navigation vendors. |
| Carbon Fiber Capacity Backward Integration | In-house pressure hull production mitigates single-source vulnerability from German and Italian Tier-2 suppliers. |
| Baltic Offshore Wind Service Positioning | Gdańsk and Szczecin port clusters capture first-mover advantage ahead of Polish array construction timelines. |
| Hybrid ROV-AUV Platform Development | Tether-free transit with remote manipulation unlocks inspection-repair workflows in floating offshore wind substructures. |
Research Methodology
Coverage spans Norway, the United Kingdom, Germany, Poland, and France, with primary inputs from each national market. Primary interviews engaged subsea robotics engineering directors at platform manufacturers, procurement leads at Norwegian offshore energy operators, autonomous navigation software architects, classification society technical committees, and Baltic offshore wind project developers. Secondary validation drew from EU Green Deal implementation documents, ECHA REACH compliance filings, EU AI Act conformity assessment guidelines, and offshore wind lease round announcements. Bottom-up platform deployment counts triangulate against top-down energy sector capital expenditure forecasts.
Granularity-level modeling distinguishes autonomous navigation, acoustic sensor, imaging system, and communication tool technology tiers across AUV, ROV, hybrid system, and support vessel product categories. Segmentation dimensions encompass oil and gas, marine research, military, and environmental monitoring end users, with application scope spanning surveying, inspection, data collection, and maintenance missions. CAGRs derive from installed base replacement cycles, battery energy density improvement curves, and offshore wind capacity addition pipelines. Forecast inputs incorporate F-Gas Regulation phase-down timelines and EU AI Act compliance cost assumptions for algorithmic risk management documentation.
Inputs from classification societies and national offshore energy regulators were available through the study window; gaps in standardized resident vehicle certification frameworks introduce uncertainty bands around continuous-deployment adoption timelines. Forecasts reflect assumptions regarding acoustic modem bandwidth expansion and lithium-thionyl chloride battery chemistry evolution. Regulatory restriction severity on hydrofluorocarbon propellants and algorithmic accountability requirements represent primary revision risks. A model refresh is warranted upon material change in classification society publication of unsupervised subsea system insurance coverage standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Humanoids Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Europe Agricultural Robot Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
North America Underwater Robotics Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Nanorobots in Healthcare Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Europe Warehouse Robotics Market