
 Sweeper Robot Market | 2026-2036
Sweeper Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Sweeper Robot Market Insights
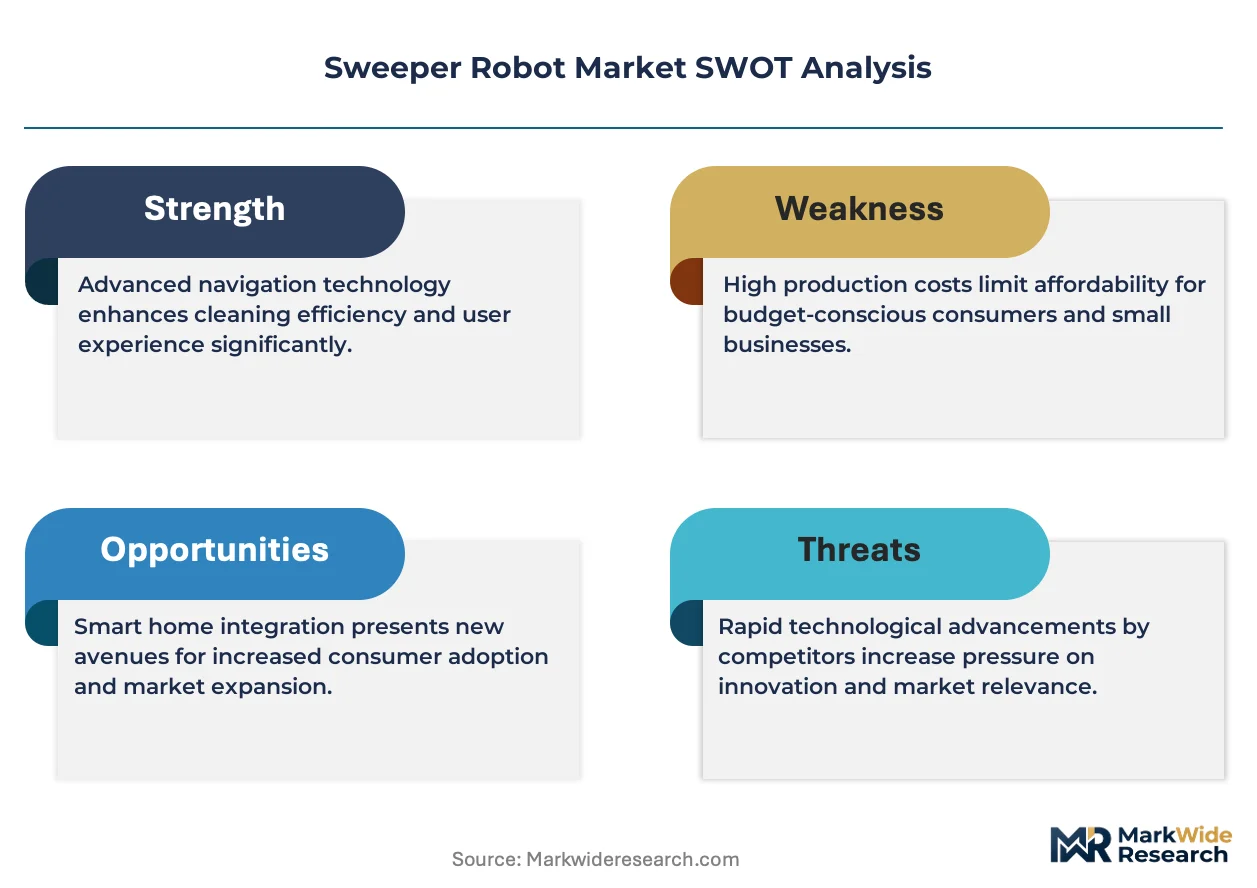
ISO 18646-1 certification for mobile service robots is reorganizing competitive entry in the sweeper robot sector, forcing manufacturers to prove safety and reliability before commercial deployment. iRobot Corporation leverages its decades of navigation R&D to sustain brand credibility in residential channels. Ecovacs Robotics anchors its position through backward integration into motor and sensor production, cutting component lead times. Roborock competes aggressively on LiDAR mapping precision, winning specification battles in Asian commercial tenders.
A sweeper robot is an autonomous or semi-autonomous mobile machine equipped with brushes, suction systems, and debris collection bins, typically operating on battery power with runtimes between 90 and 240 minutes depending on floor coverage area and soil load. Its primary purpose is to replace manual labor in repetitive floor-cleaning tasks across warehouses, retail floors, airports, and residential dwellings. Automatic units dominate volume shipments as price points drop below human-equivalent labor costs in most OECD markets. Commercial end users represent the fastest-expanding demand pool, driven by overnight cleaning contracts and 24/7 facility operations. Online distribution channels are capturing share from retail, particularly for replacement parts and consumables where buyers already know specifications.
The EU AI Act and CE marking requirements under the Machinery Directive are tightening conformity assessment burdens for autonomous navigation systems, effectively raising R&D barriers for new entrants. The US FAA and OSHA have begun coordinating on indoor autonomous vehicle safety protocols, creating a dual-track compliance environment for vendors selling across Atlantic markets. Buyers must weigh total cost of ownership against labor substitution timelines, as firmware update commitments and spare parts availability increasingly determine vendor selection.
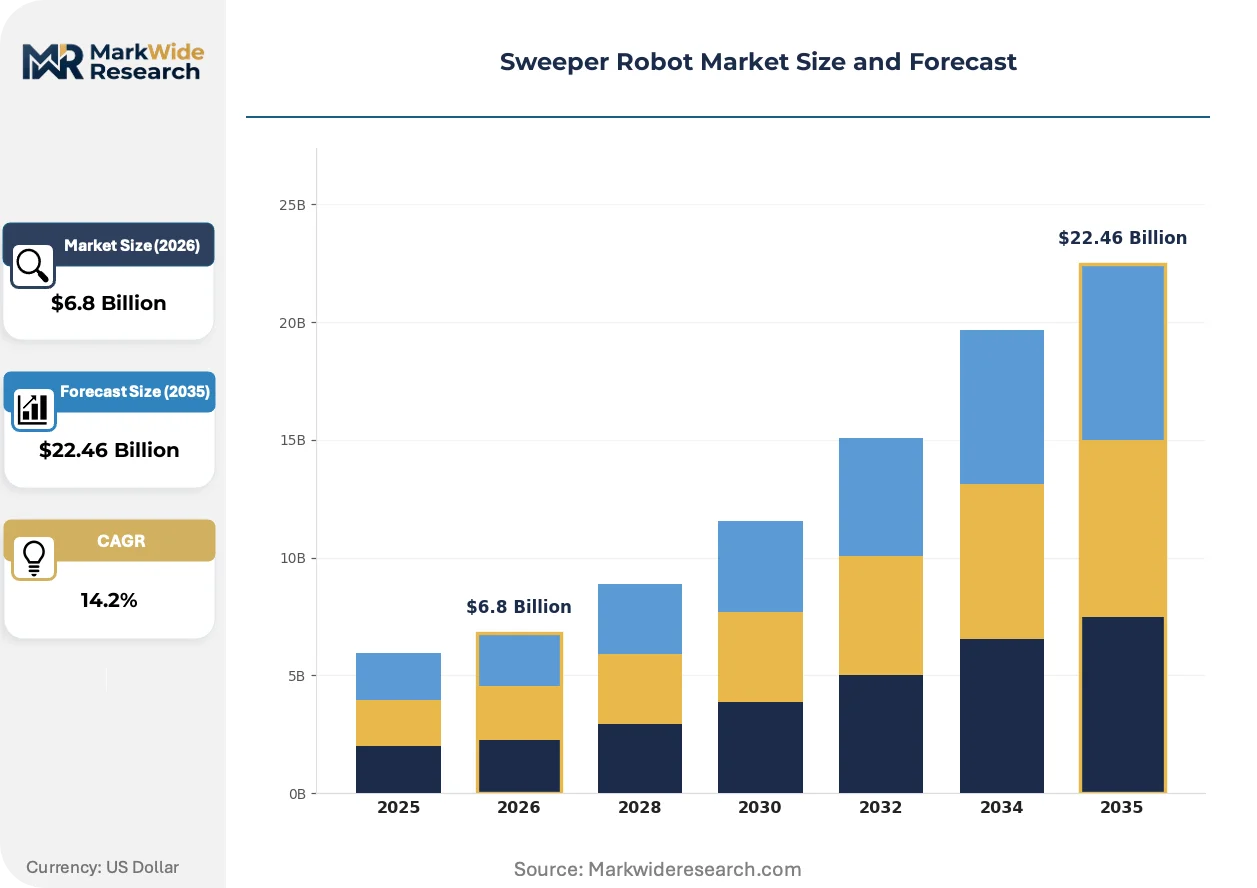
Market Dynamics
Warehouse operators are scaling autonomous floor-cleaning fleets to compress labor substitution timelines, while the EU AI Act's safety requirements for autonomous machines in commercial settings are reorganizing competitive entry barriers across OECD markets.
Growth Catalysts
- ISO 18646-1 certification:This mobile service robot standard forces manufacturers to prove safety and reliability before commercial deployment, filtering out undercapitalized entrants and elevating buyer confidence in fleet purchases.
- Overnight cleaning contracts:24/7 facility operations in logistics hubs and airports generate demand for autonomous units that operate during non-peak hours without human supervision.
- German industrial automation adoption:European manufacturers in this country are deploying sweeper robots deepest among EU markets, creating reference installations that accelerate cross-border purchasing decisions.
Market Restraints
- LiDAR sensor supply concentration:Precision mapping components for navigation systems face bottlenecks from Asian optical component suppliers, creating lead time volatility for manufacturers competing on mapping accuracy.
- CE marking conformity assessment:The Machinery Directive's tightened burdens for autonomous navigation systems extend R&D cycles and raise capital requirements for new product introductions.
- Manual cleaning labor pools:Low-wage janitorial work in emerging markets remains cost-competitive against robot ownership, slowing penetration outside OECD wage structures.
Strategic Opportunities
- Online distribution for consumables:Replacement parts and brushes are migrating to direct channels where buyers already know specifications, capturing margin from traditional retail intermediaries.
- US FAA-OSHA coordination:Emerging indoor autonomous vehicle safety protocols create first-mover advantages for vendors that pre-certify against dual-track compliance requirements spanning Atlantic markets.
- Residential firmware subscriptions:Post-sale software update commitments represent recurring revenue streams as navigation algorithms improve obstacle recognition and coverage efficiency.
Industry Challenges
- Multi-sensor fusion engineering:Integrating LiDAR, visual SLAM, and tactile feedback demands scarce robotics software talent, extending development timelines for navigation reliability.
- Legacy facility integration:Existing warehouse management systems lack standardized APIs for autonomous machine coordination, requiring custom middleware development for fleet deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweeper Robot Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Hybrid End User: Residential, Commercial, Industrial, Public Space Technology: LiDAR, Infrared, Mapping, Navigation Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | iRobot Corporation, Ecovacs Robotics Co., Ltd, Samsung Electronics Co., Ltd., Xiaomi, Roborock, LG Electronics, SharkNinja, Neato Robotics, Haier Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweeper Robot Market Trends and Innovations
Navigation and powertrain technologies are converging to extend runtime autonomy, while regulatory frameworks are hardening around safety certification and buyer procurement patterns are compressing vendor selection cycles around total cost of ownership metrics.
LiDAR-based simultaneous localization and mapping is supplanting camera-only navigation in commercial tender specifications. Airport operators and third-party logistics providers in Germany and the Netherlands are mandating sub-centimeter positional accuracy for overnight cleaning routes. This precision requirement is compressing competitive differentiation around sensor fusion capabilities and excluding pure-visual alternatives from premium commercial segments.
The EU AI Act's risk classification system for autonomous machines is extending conformity documentation burdens. Machinery deployed in public-access commercial settings now faces mandatory third-party assessment of navigation failure modes and emergency stop reliability. Vendors targeting European retail and healthcare facilities are restructuring product development cycles to embed compliance checkpoints eighteen months ahead of market entry.
Facility managers are consolidating vendor relationships around firmware update longevity and spare parts availability rather than upfront hardware pricing. Third-party logistics operators in the US are unbundling after-sales service contracts from equipment purchases, selecting separate maintenance providers for multi-brand fleets. This unbundling is visible most acutely in California and Texas distribution hubs where robot density exceeds ten units per facility.
Sweeper Robot Market Segmentation
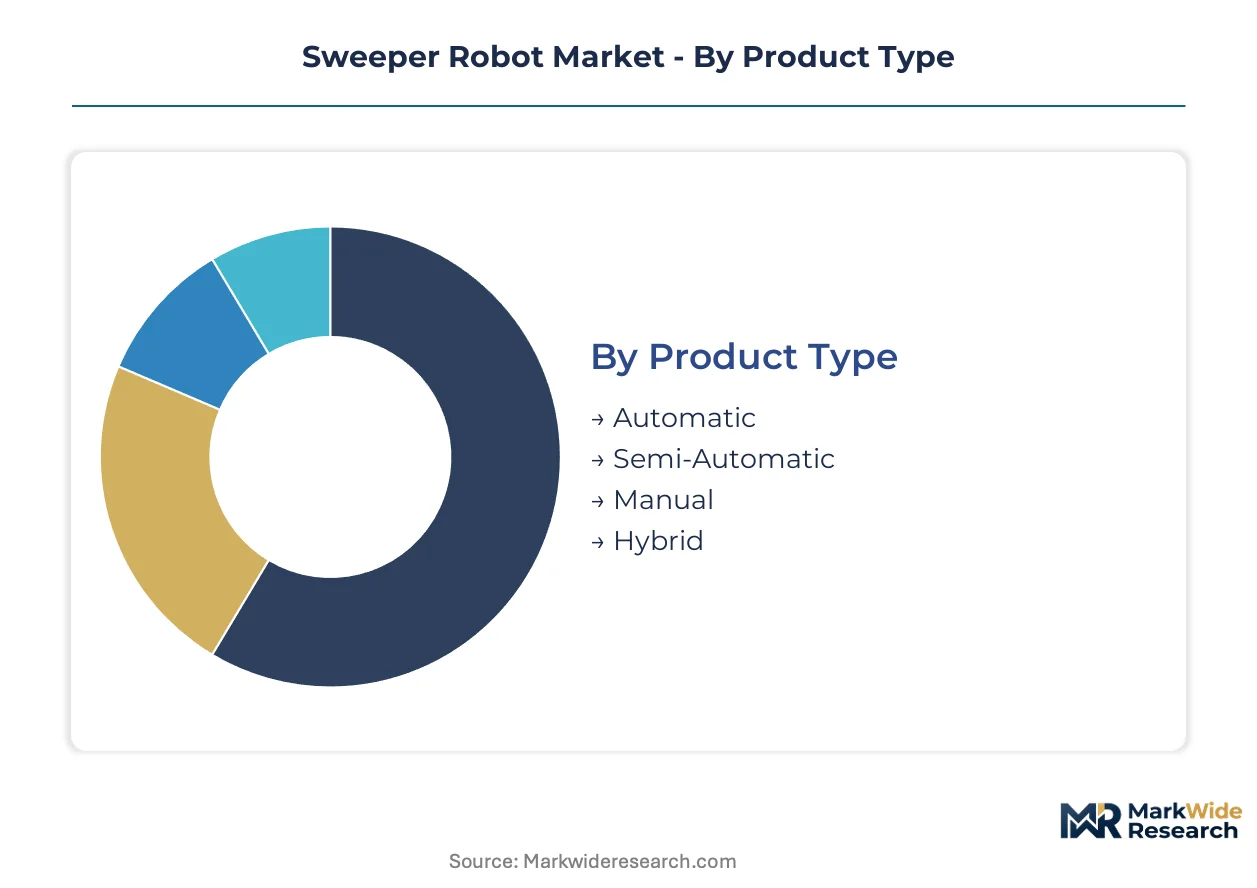
Sweeper robot procurement decisions split sharply across regulatory environments and operational intensity levels. Buyers in EU commercial settings face mandatory CE marking and EU AI Act compliance that filters available product categories, while warehouse operators prioritize runtime specifications over purchase price.
Product Type:
EU AI Act risk classification tiers separate autonomous machines by human proximity and failure consequence severity, pushing commercial buyers toward certified automatic units while semi-automatic alternatives retain footholds in price-sensitive residential channels.
- Automatic:Fully autonomous units with embedded navigation systems, collision avoidance, and self-docking capabilities operate 90-240 minutes per charge. Demand concentrates in German logistics hubs and Dutch airport facilities where overnight cleaning contracts require unsupervised operation and ISO 18646-1 certification satisfies procurement mandates.
- Semi-Automatic:Human-supervised machines with automated brush and suction systems but manual guidance requirements. Adoption favors emerging market commercial settings where labor costs remain below autonomous-equivalent ownership thresholds and CE marking burdens deter full-automation investment.
- Manual:Operator-pushed units with powered brush heads and debris collection. Residential buyers in suburban US markets select these for garage and workshop cleaning where battery runtime concerns outweigh convenience premiums.
- Hybrid:Convertible units switching between autonomous and manual modes. Japanese manufacturing facilities deploy these for mixed-environment cleaning where production floor autonomy meets loading dock manual control.
Established volume favors Automatic; emerging adoption favors Hybrid.
End User:
Cost tier differentiation separates premium-specification commercial deployments from residential price sensitivity, with industrial buyers absorbing firmware subscription costs that residential channels resist.
- Commercial:Third-party logistics operators, retail chains, and healthcare facilities requiring 24/7 cleaning coverage. US distribution hubs in California and Texas exceed ten units per facility, unbundling maintenance contracts from hardware purchases.
- Industrial:Manufacturing plants and warehouse complexes with standardized floor surfaces and defined obstacle environments. German automotive suppliers anchor European demand with fleet-scale deployments validating cross-border purchasing decisions.
- Residential:Single-family homes and multi-unit dwellings where purchase decisions weigh upfront price against labor substitution value. Online distribution captures replacement part and consumable sales as specification familiarity reduces retail intermediary reliance.
- Public Space:Airports, municipal buildings, and transit terminals with public access liability exposure. EU AI Act third-party assessment requirements extend procurement cycles for navigation failure mode documentation.
Commercial segments climb the fastest; Residential maintains absolute volume leadership.
Technology:
Application-specific precision requirements concentrate sensor selection, with sub-centimeter accuracy mandates in German airport tenders excluding camera-only alternatives while infrared suffices for obstacle-avoidance in residential settings.
- LiDAR:Laser-based simultaneous localization and mapping delivering positional accuracy below one centimeter. Asian commercial tender specifications in Singapore and South Korea mandate this precision for overnight cleaning route reliability.
- Infrared:Proximity detection for obstacle avoidance and cliff sensing. Residential units integrate these as supplementary sensors where mapping precision requirements remain relaxed.
- Mapping:Visual SLAM and topological route planning systems. European retail deployments favor these where facility reconfiguration frequency demands rapid map updates without technician intervention.
- Navigation:Integrated sensor fusion combining multiple input modalities. Multi-sensor engineering scarcity extends development timelines for vendors targeting commercial reliability thresholds.
LiDAR commands premium commercial specification; Mapping gains share in adaptive environments.
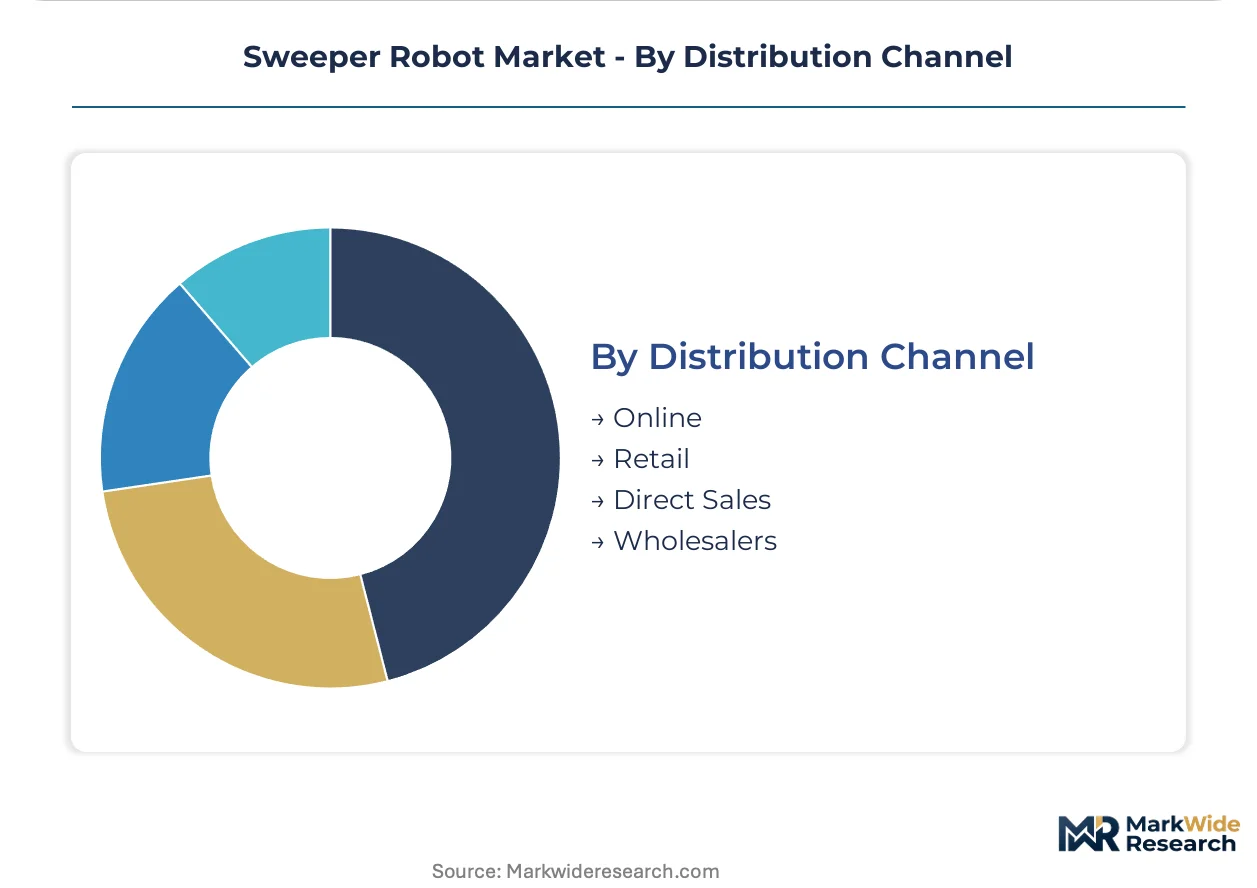
Distribution Channel:
Customer type and purchase sophistication determine channel selection, with enterprise procurement teams leveraging direct sales for fleet negotiations while residential buyers migrate online for specification-known consumables.
- Online:Direct-to-consumer and B2B platforms for replacement brushes, filters, and firmware subscriptions. US buyers in established robot-adoption markets bypass retail for consumable replenishment.
- Retail:Big-box electronics and home improvement stores for first-time residential purchases. Physical demonstration requirements sustain this channel where navigation capability skepticism persists.
- Direct Sales:Vendor field teams negotiating fleet contracts with multi-facility operators. California third-party logistics providers utilize this channel for service-unbundled procurement.
- Wholesalers:Janitorial supply distributors serving regional commercial cleaning contractors. German facility management intermediaries aggregate demand across smaller operators lacking direct vendor relationships.
Direct Sales deepens in enterprise accounts; Online expands fastest in aftermarket capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers in Germany anchor commercial procurement volumes, while warehouse operators in the United States and logistics hubs across Asia scale autonomous fleets to compress labor substitution timelines.
Germany
Automotive suppliers and third-party logistics operators drive fleet-scale deployments of ISO 18646-1 certified units. The EU AI Act's risk classification system mandates third-party assessment of navigation failure modes for public-access commercial settings. Industrial automation adoption runs deepest in Baden-Württemberg and Bavaria, where reference installations accelerate cross-border purchasing decisions.
United States
Distribution hubs in California and Texas exceed ten sweeper robot units per facility, unbundling maintenance contracts from hardware purchases. FAA-OSHA coordination on indoor autonomous vehicle safety protocols creates dual-track compliance requirements for Atlantic-crossing vendors. Third-party logistics operators in the Southwest and Southeast prioritize runtime specifications over upfront hardware pricing.
China
Domestic manufacturers leverage backward integration into motor and sensor production to cut component lead times. GB standards and SAMR oversight shape conformity assessment for autonomous navigation systems. Pearl River Delta electronics clusters and Yangtze River Delta logistics corridors concentrate both production capacity and commercial deployment trials.
Japan
Manufacturing facilities deploy hybrid units for mixed-environment cleaning where production floor autonomy meets loading dock manual control. METI industrial automation incentives support robotics adoption in precision manufacturing settings. Kansai and Chubu industrial corridors anchor demand for convertible autonomous-manual systems.
South Korea
Commercial tender specifications mandate sub-centimeter LiDAR precision for overnight cleaning route reliability in airport and logistics applications. MFDS and KTL certification requirements filter available vendor categories for public-space deployments. Seoul Capital Area and Busan-Ulsan logistics hubs concentrate specification-driven procurement.
Sweeper Robot Market Competitive Landscape
Player mix skews toward diversified electronics conglomerates with captive robotics divisions and specialized autonomous cleaning pure-plays. Market structure exhibits tiered consolidation around three to four scale leaders with meaningful share, flanked by mid-cap regional specialists and emerging Asian fabricators. Strategic archetypes separate navigation-technology originators, component-integrated manufacturers, and brand-leveraged consumer electronics entrants. Dominant competitive moves include backward integration into sensor and motor production, plus firmware subscription models that extend customer lifetime value beyond hardware margins.
Among the established tier, iRobot Corporation and Ecovacs Robotics Co., Ltd occupy positions representing divergent strategic paths—one anchored in decades of navigation R&D heritage, the other in supply-chain control through in-house component production. Roborock exemplifies the specification-driven specialist archetype competing on mapping precision, while Samsung Electronics Co., Ltd. and LG Electronics represent diversified conglomerate entries leveraging brand distribution and cross-category technology transfer. Xiaomi sits within the ecosystem-integrated tier, utilizing platform economics to compress price points.
| Leading Market Players |
|---|
| iRobot Corporation |
| Ecovacs Robotics Co., Ltd |
| Samsung Electronics Co., Ltd. |
| Xiaomi |
| Roborock |
| LG Electronics |
| SharkNinja |
| Neato Robotics |
| Haier Group Corporation |
| Others |
Pricing and Supply Chain Analysis
ISO 18646-1 certification gates both supplier qualification and price differentiation in the sweeper robot sector, forcing vendors to absorb compliance costs that stratify offerings across certified premium tiers and uncertified economy alternatives while buyers weigh total cost of ownership against firmware longevity.
Pricing Analysis
Cost-plus contracts with LiDAR sensor indexation dominate commercial fleet procurement, particularly among German logistics operators and California third-party logistics providers. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified autonomous units from semi-automatic alternatives and manual equipment, with certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from Asian component suppliers compressing margins on navigation systems. Residential buyers exhibit highest price sensitivity, while industrial fleet operators prioritize runtime reliability over upfront hardware costs.
Supply Chain Analysis
Inventory buffers for precision optical components stretch lead times to twelve weeks for manufacturers competing on sub-centimeter mapping accuracy. Component production concentrates in China, South Korea, and Japan, with LiDAR sensors and brushless motors drawing from Pearl River Delta electronics clusters. Single-source vulnerability in VCSEL laser diodes creates exposure to export control fluctuations. Distribution runs through direct sales teams for enterprise fleet contracts and online platforms for replacement consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sweeper robot market is recovering from a cyclical trough as warehouse automation capex rebounds from pandemic-era overbuild, with overnight cleaning contract renewals driving replacement demand across OECD logistics hubs.
For Market Incumbents: Consolidate firmware subscription revenue streams by extending algorithm update commitments to ten-year horizons, matching the depreciation cycles of German automotive suppliers. Deepen backward integration into sensor production to offset LiDAR supply concentration risks. Lock in ISO 18646-1 certification moats ahead of EU AI Act enforcement waves.
For New Entrants and Emerging Players: Differentiate on hybrid autonomous-manual architectures for Japanese manufacturing facilities where production floor autonomy meets loading dock manual control. Target South Korean airport tenders with sub-centimeter LiDAR precision as the most penetrable specification-driven segment. Pursue direct online distribution for replacement brushes and filters where specification familiarity reduces retail intermediary dependence.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-sensor fusion engineering capabilities as navigation reliability demands scarce robotics software talent. Five-to-ten year viability favors vendors with captive component production and installed base scale for recurring firmware revenue. Target acquisition archetype: mid-cap regional specialists with ISO certification and established fleet references. Watch for inflection in unbundled maintenance contract penetration at US distribution hubs exceeding ten units per facility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Production | Ecovacs Robotics anchors margin control through captive motor and LiDAR module manufacturing. |
| Firmware Subscription Model Expansion | iRobot Corporation extends customer lifetime value beyond hardware through navigation algorithm updates. |
| ISO 18646-1 Pre-Certification Investment | Roborock wins German commercial tenders by embedding safety compliance eighteen months ahead of market entry. |
| Direct Online Channel for Consumables | US buyers bypass retail intermediaries for specification-known replacement brushes and filters. |
| Hybrid Autonomous-Manual Product Development | Japanese manufacturing facilities deploy convertible units for mixed-environment cleaning workflows. |
Research Methodology
A spread of perspectives from warehouse operations directors, fleet procurement managers, robotics R&D leads, and aftermarket service heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with facility managers at German automotive suppliers and California distribution hubs with secondary validation against customs records, SEC filings from disclosed robotics divisions, and ISO certification registries. Bottom-up unit economics triangulated against top-down addressable facility counts across logistics corridors.
Segmentation dimensions modeled include autonomy level, end-use intensity, sensor technology tier, and distribution channel sophistication across the projection horizon. CAGRs were derived from installed base growth rates and replacement cycle compression. Forecast inputs incorporated overnight cleaning contract penetration curves and EU AI Act compliance cost pass-through assumptions.
Forecasts assume regulatory continuity in EU AI Act risk classification and US FAA-OSHA coordination protocols; material policy shifts would require re-modeling navigation failure mode documentation burdens. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Robot Charging Station Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Autonomous Mobile Robots for Logistics and Warehousing Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Underwater Robot Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
LAMEA Demolition Robot Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
Healthcare Companion Robots Market