
 Global Adaptive Robotics Market | 2026-2036
Global Adaptive Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adaptive Robotics Market Foresight
The EU Green Deal's industrial decarbonization targets are consolidating demand for adaptive systems that cut energy waste and material scrap in European manufacturing. ABB leverages its robotics software stack to anchor automation contracts across German automotive suppliers. FANUC sustains its position through captive servo motor production and dense service networks in East Asian electronics hubs. KUKA competes on payload flexibility for mixed-model assembly lines where retooling speed determines contract economics.
Adaptive robotics denotes programmable manipulators and mobile platforms that modify trajectory, force, or task sequence in real time through sensor feedback and machine learning inference. These systems typically integrate torque-controlled joints, LiDAR arrays, and edge compute modules to operate safely alongside human workers without fixed caging. Collaborative robots lead current shipment volumes because SMEs prioritize low-footprint deployment over full-line automation. Machine learning is the fastest-expanding technology segment as vision-guided grasping and predictive maintenance algorithms mature from pilot to production scale. Pharmaceutical production applications command premium pricing due to FDA validation requirements and batch-level traceability demands.
FDA validation protocols for pharmaceutical robotics and EU MDR compliance for surgical automation systems shape product development roadmaps and market access timelines. China's SAMR enforces GB standards for collaborative robot safety zones that differ from ISO/TS 15066, forcing dual-certification strategies for vendors serving both markets. Japan's METI funds next-generation robotics through its Society 5.0 framework, directing public R&D toward eldercare and disaster-response adaptive platforms. Stakeholders must monitor divergent safety standard harmonization progress across FDA, EMA, and NMPA jurisdictions to anticipate certification cost shifts and regional competitive entry barriers.
Market Dynamics
The EU Green Deal's manufacturing efficiency mandates are forcing European electronics producers to replace fixed automation with sensor-fed adaptive systems that eliminate material scrap and retooling downtime.
Growth Catalysts
- EU Green Deal industrial mandates:Binding decarbonization targets for German automotive suppliers are accelerating cobot deployments that cut energy waste through real-time trajectory optimization.
- Semiconductor fabrication clustering:South Korea's concentrated fab infrastructure generates concentrated demand for vision-guided adaptive systems handling fragile wafer transfer operations.
- Machine learning inference at the edge:Predictive maintenance algorithms trained on torque sensor data are reducing unplanned downtime in pharmaceutical batch production.
Market Restraints
- Captive servo motor supply concentration:East Asian electronics hubs face input cost volatility when Japanese and German precision motor suppliers ration capacity during demand surges.
- Dual-certification cost burden:China's SAMR GB standards for collaborative robot safety zones force vendors serving both Chinese and ISO/TS 15066 markets to maintain parallel validation pipelines.
- Legacy PLC integration friction:Brownfield manufacturing lines running decades-old programmable logic controllers resist seamless sensor feedback loops without expensive gateway hardware.
Strategic Opportunities
- Pharmaceutical FDA validation premiums:Batch-level traceability requirements create pricing power for adaptive systems vendors willing to absorb 18-24 month certification timelines.
- Eldercare robotics under METI funding:Japan's Society 5.0 framework directs public R&D toward adaptive platforms for assisted living, opening reimbursement pathways for compliant hardware.
- 5G-enabled remote teleoperation:Convergence of low-latency private networks and haptic feedback controllers is enabling service providers to offer adaptive robotics as managed services to SMEs.
Industry Challenges
- Multi-disciplinary systems integration talent:Deployments require simultaneous expertise in mechanical engineering, edge computing architecture, and safety-certified software development.
- FDA-EMA-NMPA harmonization gaps:Divergent validation protocols for surgical automation systems force vendors to run parallel clinical evidence collection, compressing margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adaptive Robotics Market |
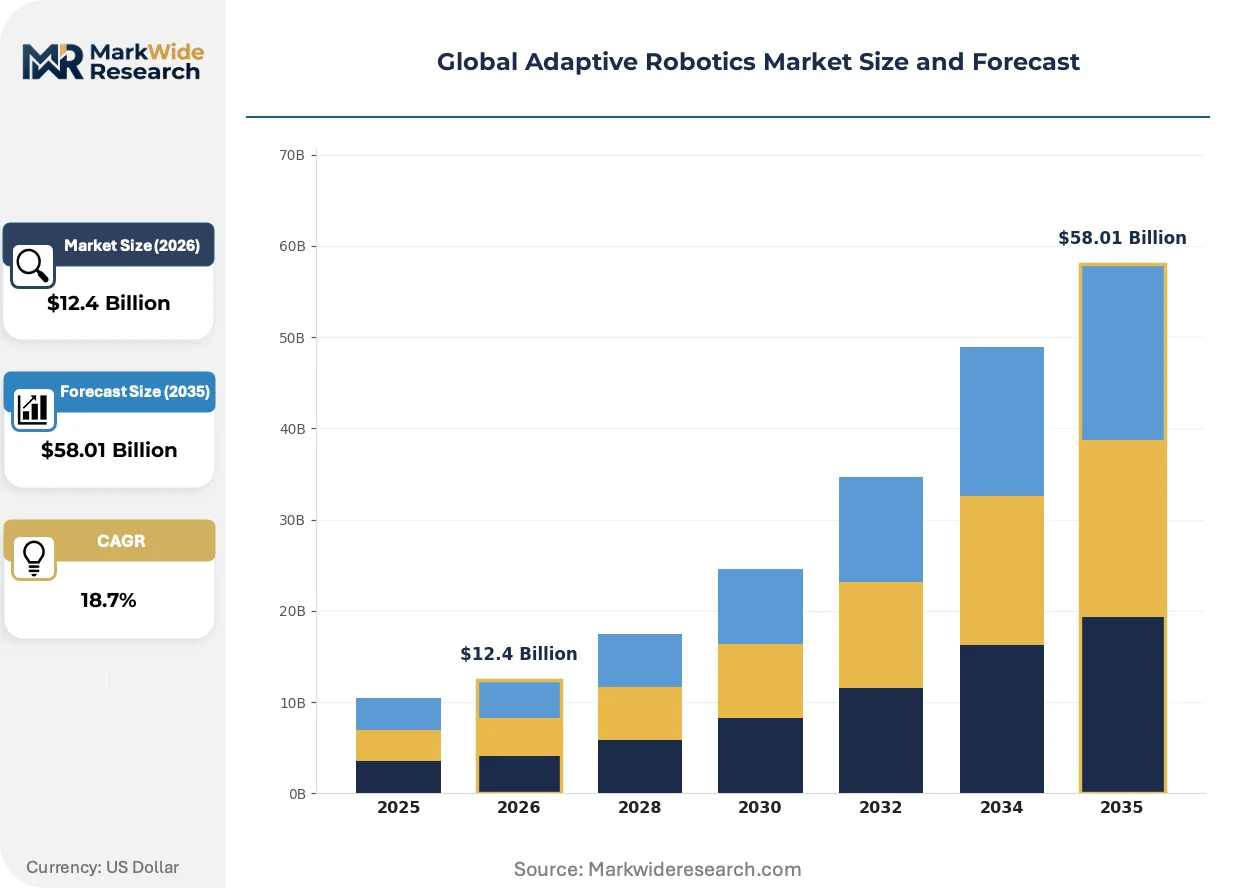
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Robots, Collaborative Robots, Industrial Robots, Autonomous Guided Vehicles, Circuit Assembly Robots Technology: Machine Learning, Computer Vision, Sensor Fusion, Reinforcement Learning, Adaptive Control Algorithms Application: Electronics Manufacturing, Semiconductor Handling, Precision Assembly, Food Processing Automation, Pharmaceutical Production End User: Electronics Manufacturers, Semiconductor Fabricators, Food & Beverage Companies, Pharmaceutical Producers, Consumer Goods Firms |
| Companies Covered | ABB, KUKA, FANUC, Yaskawa Electric Corporation, Universal Robots, SoftBank Group Corp, Boston Dynamics, Robotiq Inc, Flexiv Robotics Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adaptive Robotics Market Shifts & Advancements
Edge compute modules are redistributing processing load away from centralized cloud infrastructure, enabling millisecond-loop adaptive responses that cloud-dependent systems cannot match.
Embedded GPU-accelerated vision processors are decentralizing machine learning inference from factory servers to individual robot joints. Tier-one automotive suppliers in Germany now specify on-device grasp planning for mixed-model lines. This architecture is decentralizing control system procurement decisions from central IT departments to plant-floor engineering teams.
The EU AI Act's risk-classification framework for industrial automation systems is tightening documentation requirements for high-risk adaptive robotics applications. Manufacturers must now maintain algorithmic audit trails and human oversight protocols. Pharmaceutical packaging lines in Ireland and the Netherlands are absorbing compliance costs fastest, with contract clauses shifting liability to system integrators.
SME buyers are unbundling after-sales service contracts from hardware purchases, preferring third-party maintenance providers with multi-vendor expertise. This fragmentation is pressuring original equipment margins in Italy and Spain. Machine tool distributors in Turin and Barcelona are responding by certifying in-house adaptive robotics technicians to capture recurring revenue streams.
Global Adaptive Robotics Market Segmentation
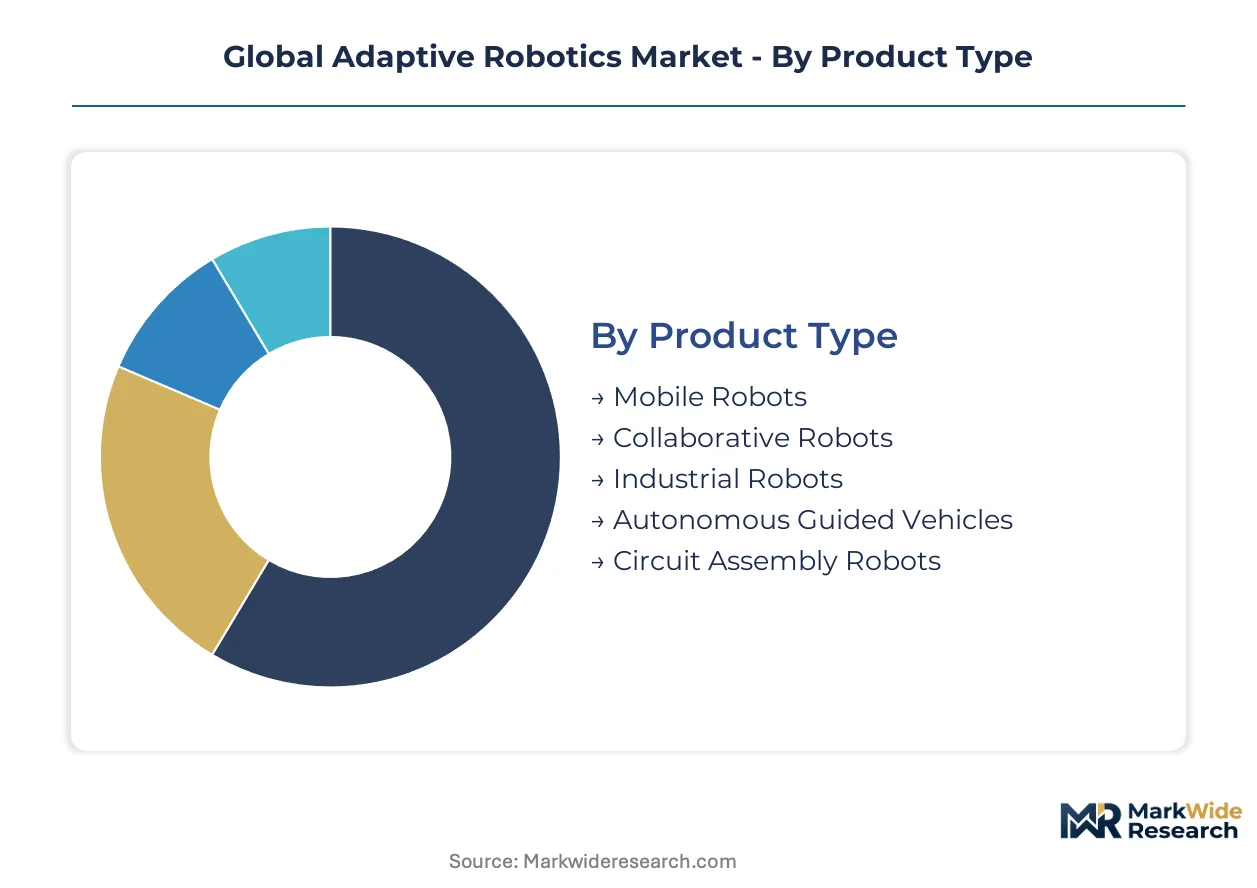
Segmentation in adaptive robotics reveals how purchasing priorities diverge across capital intensity thresholds, regulatory exposure, and integration complexity. Buyers in semiconductor fabrication prioritize precision over payload, while food processors weight washdown compatibility against cycle speed.
Product Type:
Capital deployment scale and safety certification requirements drive product selection more than raw performance specifications.
- Collaborative Robots:Torque-limited joints and force-sensing skins enable fenceless deployment alongside human operators. German automotive suppliers under EU Green Deal mandates favor these for mixed-model lines where retooling speed determines contract economics.
- Mobile Robots:LiDAR-guided autonomous platforms transport materials across unstructured factory floors. South Korea's concentrated semiconductor fab infrastructure generates concentrated demand for fleet coordination systems handling fragile wafer cassettes between cleanroom zones.
- Industrial Robots:High-payload articulated arms dominate heavy assembly operations.
- Autonomous Guided Vehicles:Magnetic and vision-guided transport systems serve predictable route environments.
- Circuit Assembly Robots:Specialized SCARA configurations target PCB population and inspection tasks.
Collaborative robots lead on scale; mobile robots lead on momentum.
Technology:
Processing location—edge versus cloud—shapes architecture decisions more than algorithmic sophistication alone.
- Machine Learning:Vision-guided grasp planning and predictive maintenance algorithms trained on torque sensor data reduce unplanned downtime. Edge inference deployment is climbing fastest as pharmaceutical batch producers absorb FDA validation requirements for algorithmic audit trails.
- Computer Vision:Embedded GPU-accelerated processors decentralize object detection from factory servers to individual joints. Tier-one German automotive suppliers now specify on-device grasp planning for mixed-model assembly lines.
- Sensor Fusion:Integration of LiDAR, tactile arrays, and inertial measurement units enables robust localization.
- Reinforcement Learning:Trial-and-error task optimization remains largely experimental outside research partnerships.
- Adaptive Control Algorithms:Real-time trajectory modification based on force feedback handles compliant materials.
Computer vision dominates installed base; machine learning gains share fastest.
Application:
Regulatory validation burden and contamination sensitivity create pricing tiers that override pure efficiency metrics.
- Pharmaceutical Production:FDA batch-level traceability requirements and 21 CFR Part 11 compliance create 18-24 month certification timelines. Vendors absorbing these costs command premium pricing for validated adaptive systems in Irish and Dutch packaging lines.
- Semiconductor Handling:Vision-guided wafer transfer operations in South Korea's fab cluster demand sub-micron positioning repeatability. Fragility constraints favor adaptive force control over rigid automation.
- Electronics Manufacturing:Miniaturization trends drive precision assembly demand across German and Chinese production bases.
- Precision Assembly:Mixed-model automotive lines require rapid reprogramming capabilities.
- Food Processing Automation:IP69K washdown ratings and allergen segregation protocols shape system design.
Electronics manufacturing leads on scale; pharmaceutical production leads on momentum.
End User:
Integration capability and maintenance infrastructure separate deployable demand from aspirational interest.
- Semiconductor Fabricators:Concentrated capital bases in South Korea and Taiwan support dedicated automation engineering teams. These buyers specify custom end-effectors for 300mm wafer handling and vacuum chamber loading.
- Pharmaceutical Producers:FDA and EMA validation protocols force dual-track certification strategies. Brownfield sites running legacy PLCs resist seamless sensor feedback without expensive gateway hardware.
- Electronics Manufacturers:German suppliers under EU Green Deal efficiency mandates scale cobot deployments fastest.
- Food & Beverage Companies:Hygienic design requirements limit viable vendor pools.
- Consumer Goods Firms:Seasonal demand volatility favors flexible automation over fixed lines.
Semiconductor fabricators lead on scale; pharmaceutical producers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adaptive robotics traces its industrial lineage to Japanese automotive plants of the 1980s, where programmable manipulators first achieved mass deployment. German engineering subsequently refined precision assembly applications, while South Korean semiconductor infrastructure drove vision-guided handling innovations.
Germany
Automotive suppliers under EU Green Deal mandates deploy torque-limited cobots for mixed-model retooling. KBA vehicle certification protocols and REACH chemical safety standards shape end-effector material selection. Stuttgart's precision engineering cluster hosts validation centers for pharmaceutical packaging robotics serving EMA-regulated exports.
United States
FDA-regulated pharmaceutical producers absorb 18-24 month validation timelines for batch-traceable adaptive systems. OSHA collaborative robot safety directives and SEC climate disclosure rules pressure capital deployment decisions. Boston's robotics R&D corridor concentrates machine learning talent for surgical automation ventures.
Japan
METI's Society 5.0 framework funds eldercare robotics through public-private partnerships. PMDA medical device approval pathways and JIS safety standards govern rehabilitation exoskeleton commercialization. Nagoya's manufacturing belt sustains captive servo motor supply chains for precision motion control.
South Korea
Concentrated semiconductor fab infrastructure generates concentrated demand for wafer-handling adaptive systems. MFDS medical device regulations and KOSHA industrial safety standards apply to cleanroom automation deployments. Pyeongtaek's memory fabrication complex specifies sub-micron positioning repeatability for vision-guided transfer operations.
China
Electronics manufacturers scale cobot deployments for consumer device assembly under MIIT intelligent manufacturing directives. SAMR GB collaborative robot safety standards differ from ISO/TS 15066, forcing dual-certification strategies. Shenzhen's hardware ecosystem integrates edge compute modules with cost-optimized joint actuators.
Global Adaptive Robotics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. Japanese and European incumbents maintain captive component manufacturing and dense service networks. Chinese challengers exploit modular hardware ecosystems and rapid iteration cycles. Strategic moves concentrate on backward integration into precision motion control and geographic expansion through localized certification partnerships.
Among Swiss-Swedish and German industrial conglomerates, ABB and KUKA occupy positions anchoring automotive automation contracts. Japanese precision manufacturers exemplify scale-driven archetypes through FANUC and Yaskawa Electric Corporation. Danish collaborative specialists and Chinese adaptive hardware ventures represent emerging competitive vectors.
| Leading Market Players |
|---|
| ABB |
| KUKA |
| FANUC |
| Yaskawa Electric Corporation |
| Universal Robots |
| SoftBank Group Corp |
| Boston Dynamics |
| Robotiq Inc |
| Flexiv Robotics Inc |
| Others |
Supply & Pricing Matrix
Edge compute module proliferation simultaneously compresses hardware costs and fragments supplier power across precision motion control vendors. This technology shift concentrates pricing leverage among buyers who can specify open-architecture controllers, while forcing legacy servo motor producers into defensive bundling strategies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates adaptive robotics procurement. Premium tiers command substantial markups through FDA validation documentation and ISO/TS 15066 safety certification, while economy tiers compete on actuator cost and stripped-down sensor packages. Pricing pressure stems from Chinese modular hardware ecosystems undercutting European precision engineering on consumer electronics assembly lines. SME buyers exhibit highest price sensitivity, whereas semiconductor fabricators prioritize sub-micron repeatability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Tier-one German automotive suppliers mandate qualified secondary suppliers for torque sensors and harmonic drives. Component production concentrates in Japan, Germany, and China, with precision gearboxes drawing from Nagoya's manufacturing belt and servo motors anchored in Stuttgart's engineering cluster. Rare-earth magnet supply rests on Chinese processing dominance, creating tariff exposure for non-domestic vendors. Distribution runs through certified system integrators who absorb validation liability for pharmaceutical end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive robotics has entered a late-cycle quality phase where FDA-validated systems and EU AI Act-compliant platforms capture disproportionate value. Demand is concentrating toward premium specifications as pharmaceutical producers and automotive suppliers prioritize traceability over hardware cost.
For Market Incumbents: Deepen captive production of precision motion components to offset Japanese and German motor supplier rationing. Expand validation center footprints in Stuttgart and Boston to compress EMA and FDA certification timelines. Consolidate service networks in East Asian electronics hubs before Chinese modular vendors achieve comparable response density.
For New Entrants and Emerging Players: Launch via robotics-as-a-service models targeting Italian and Spanish SMEs who unbundle maintenance from hardware purchases. Penetrate food processing automation where IP69K washdown requirements limit incumbent vendor pools. Target eldercare applications under Japan's METI Society 5.0 framework where reimbursement pathways reduce upfront buyer friction.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier sensor fusion specialists with pharmaceutical validation pipelines. Five-to-ten year viability hinges on algorithmic audit trail capabilities under tightening EU AI Act enforcement. Watch FDA-EMA-NMPA harmonization progress as the inflection signal for margin expansion or compression across surgical automation ventures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Motion Control | Captive servo motor production insulates FANUC and Yaskawa from supplier rationing during demand surges. |
| Pharmaceutical Validation Pipeline Investment | 18-24 month FDA certification timelines create pricing power for vendors absorbing compliance costs in Irish packaging lines. |
| Edge Compute Module Partnership | Shenzhen's hardware ecosystem enables cost-optimized joint actuators that challenge European precision engineering margins. |
| 5G-Enabled Remote Teleoperation Launch | Low-latency private networks allow service providers to offer adaptive robotics as managed services to capital-constrained SMEs. |
| Dual-Certification Strategy Expansion | Parallel ISO/TS 15066 and SAMR GB standard compliance opens access to Chinese electronics manufacturers scaling cobot deployments. |
Research Methodology
Multiple input streams — plant engineer interviews, procurement manager surveys, and regulatory filing analysis — were reconciled to construct demand estimates. Primary conversations spanned automation engineering directors at German automotive suppliers, FDA regulatory affairs leads at pharmaceutical packaging firms, and service heads at East Asian electronics manufacturing clusters. Secondary validation drew from SAMR GB standard publications, EMA medical device guidance documents, and METI Society 5.0 funding disclosures. Bottom-up shipment data from precision motion component vendors was cross-checked against top-down capital expenditure tracking across semiconductor fabrication facilities.
Historical growth patterns were cross-referenced against panel input from robotics OEM strategists and system integrator engineering teams. The analytical framework modeled volume and value across product type, technology layer, application vertical, and end-user sophistication tier throughout the forecast period. CAGRs were derived from weighted scenario analysis incorporating edge compute adoption curves, regulatory harmonization timelines, and pharmaceutical validation backlog projections. Forecast inputs included torque sensor data training volumes for predictive maintenance algorithms and LiDAR array cost decline trajectories.
Several conditions sit outside the modeled scope, including sudden trade restriction imposition on rare-earth magnet exports and unanticipated FDA validation protocol revisions. Forecasts reflect documented assumptions regarding EU AI Act enforcement consistency and 5G private network deployment pace across manufacturing zones. Deviation in semiconductor capital expenditure cycles or pharmaceutical batch production automation mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Rotary Gripper Module Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Healthcare Robots Market
Robotics and Automation
Claytronics Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Japan Agricultural Robot Market