
 Asia-Pacific Cloud Robotics Market | 2026-2036
Asia-Pacific Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cloud Robotics Market Analytics
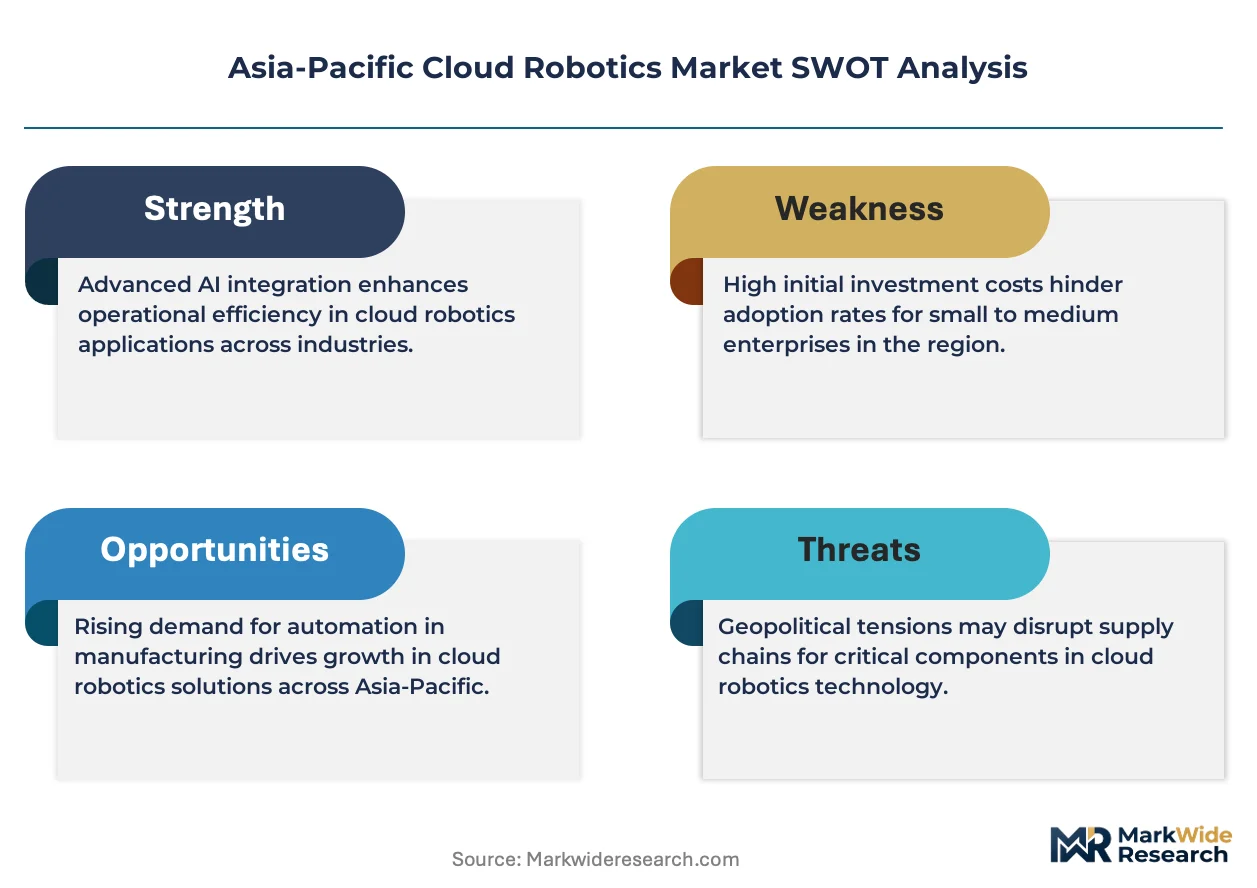
Multi-source cloud platform procurement is restructuring how Asia-Pacific manufacturers contract robotics infrastructure. Huawei anchors its position through in-house production of edge-to-cloud orchestration layers for factory deployments. Rapyuta Robotics specializes in managed robot fleet software, competing against Amazon Web Services' broader industrial cloud portfolio. SoftBank Robotics sustains brand strength in service robot segments through channel control of hospitality and retail installations across Japan.
Asia-Pacific cloud robotics denotes distributed robot systems that offload computation, data storage, and machine learning model execution to remote cloud servers via low-latency connectivity, typically operating with sub-100ms response thresholds for real-time task coordination. These systems serve industrial and commercial users by enabling centralized fleet management, continuous algorithm updates, and collaborative task allocation across heterogeneous robot populations. Industrial robots dominate current deployment value due to established manufacturing automation budgets, while collaborative robots represent the fastest-expanding segment as small and medium enterprises adopt pay-per-use cloud orchestration. Hybrid cloud deployments capture expanding margin pools by balancing sensitive operational data on-premises with elastic compute bursting to public infrastructure during peak demand cycles.
Japan's METI enforces robotics safety and data governance protocols that shape product certification requirements for cloud-connected systems entering Japanese industrial facilities. China's MIIT cloud service security assessment and South Korea's MFDS medical device software standards constrain market access for platforms lacking localized compliance architecture. India's TRAI data localization directives and Australia's TGA therapeutic device frameworks add further jurisdictional complexity for regional platform providers. Stakeholders must monitor evolving cross-border data flow restrictions and determine whether distributed edge-node architectures or country-specific cloud instances better satisfy fragmented regulatory expectations.
Market Dynamics
Cloud-native orchestration platforms are compressing deployment timelines for autonomous robot fleets across Asia-Pacific manufacturing corridors, forcing infrastructure providers to restructure pricing models around compute consumption rather than hardware ownership.
Growth Catalysts
- MIIT Cloud Computing Standards:China's interoperability mandates accelerate platform consolidation among domestic robot manufacturers, reducing integration friction for multi-vendor fleet deployments.
- Warehouse Automation Surge:Third-party logistics operators in Japan and South Korea expand autonomous mobile robot procurement to address labor shortages in e-commerce fulfillment centers.
- Edge-Cloud Hybrid Architectures:Sub-100ms latency requirements for real-time task coordination drive demand for distributed compute nodes positioned near manufacturing clusters.
Market Restraints
- Cross-Border Data Friction:India's TRAI data localization directives and China's cybersecurity review processes fragment cloud infrastructure deployment strategies across national boundaries.
- Specialized Talent Scarcity:Shortages of robotics-cloud integration engineers constrain rollout velocity for mid-tier manufacturers lacking in-house DevOps capabilities.
- Semiconductor Supply Concentration:Dependence on Taiwan and South Korea for advanced AI accelerators exposes fleet operators to input cost volatility and allocation rationing.
Strategic Opportunities
- Pay-Per-Use Orchestration:Small and medium enterprises across Southeast Asia adopt consumption-based cloud robotics models, bypassing capital-intensive on-premise infrastructure investments.
- Medical Device Software Pathways:South Korea's MFDS standards create compliance templates for cloud-connected surgical and rehabilitation robots entering regulated healthcare environments.
- 5G Network Slicing:Dedicated low-latency connectivity layers from telecom operators enable deterministic control for collaborative robot applications in precision assembly.
Industry Challenges
- Fragmented Certification Timelines:Divergent safety protocols between Japan's METI robotics roadmaps and Australia's TGA therapeutic device frameworks extend product validation cycles for regional platform providers.
- Legacy System Integration:Brownfield manufacturing facilities struggle to interface cloud-native robot swarms with decades-old programmable logic controller architectures and proprietary industrial networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cloud Robotics Market |
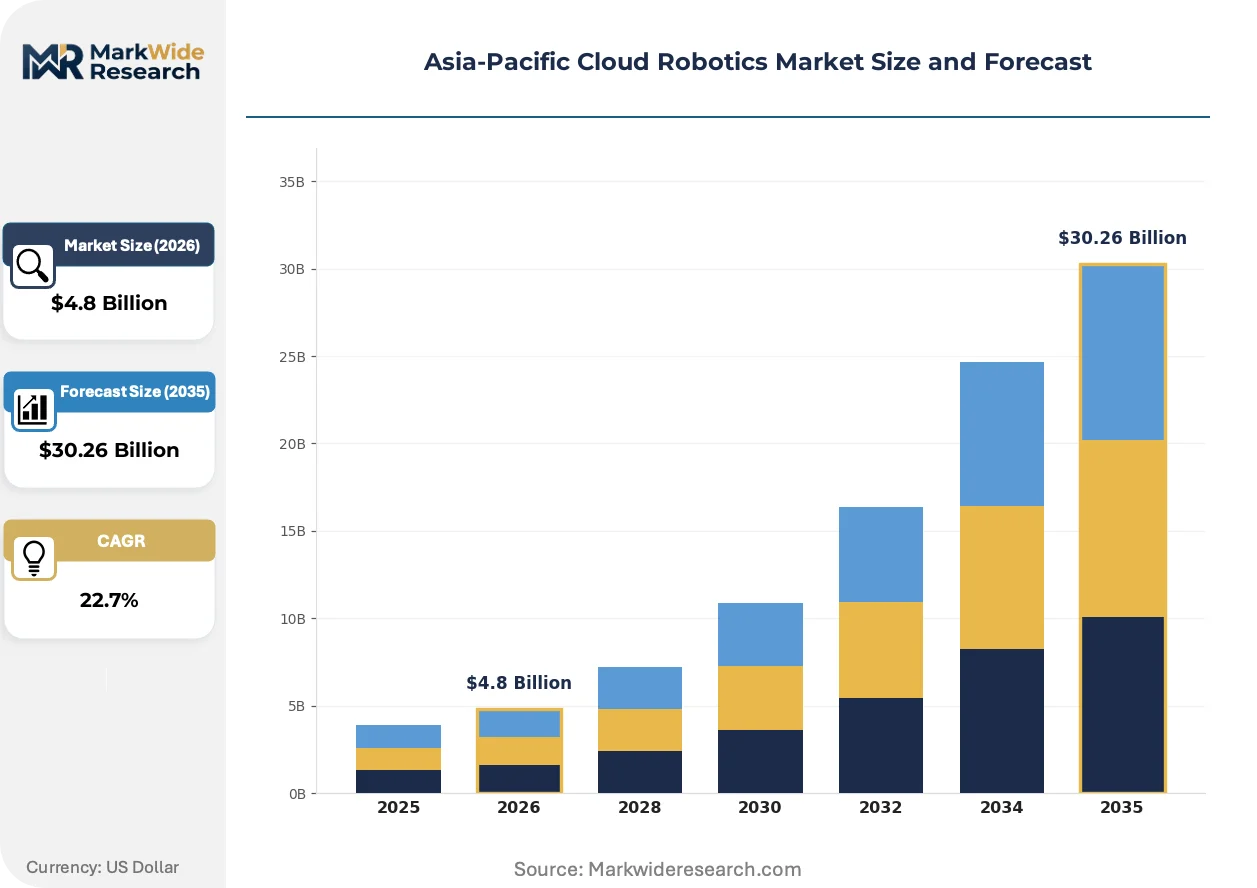
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Service Robots, Industrial Robots, Collaborative Robots, Humanoid Robots Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Manufacturing, Healthcare, Retail, Logistics Technology: Machine Learning, Artificial Intelligence, Edge Computing, IoT |
| Companies Covered | Rapyuta Robotics, CloudMinds, Huawei, Hit Robot Group, SoftBank Robotics, Omron Corporation, UBTECH Robotics, Hanwha Robotics, Amazon Web Services, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cloud Robotics Market Evolving Landscape
Artificial intelligence model serving at the edge is restructuring how robot fleets learn and adapt, shifting competitive advantage toward platforms that can deploy algorithm updates without disrupting production continuity.
Digital twin simulation environments are integrating with live cloud robotics deployments, allowing Foxconn-tier manufacturers to validate swarm behaviors virtually before physical commissioning. Automotive and electronics contract manufacturers in China's Yangtze River Delta adopt these tools aggressively, compressing pilot-to-production cycles from quarters to weeks and reducing field failure rates for multi-robot coordination protocols.
METI's robotics safety and data governance protocols are mandating granular audit trails for cloud-connected systems entering Japanese industrial facilities. These requirements force platform providers to architect localized compliance modules, increasing development overhead but creating certification barriers against non-compliant foreign competitors. Medical and collaborative robot segments face the steepest compliance burdens under these evolving frameworks.
Subscription-based fleet management contracts are displacing perpetual software licenses among Asia-Pacific logistics operators, aligning vendor revenue with operational uptime metrics rather than initial deployment scale. This shift concentrates purchasing authority within procurement functions rather than engineering departments, favoring vendors with established enterprise sales infrastructure. The transformation is most visible in Japan's third-party logistics sector, where pay-for-outcome structures now dominate new robot procurement decisions.
Asia-Pacific Cloud Robotics Market Segmentation
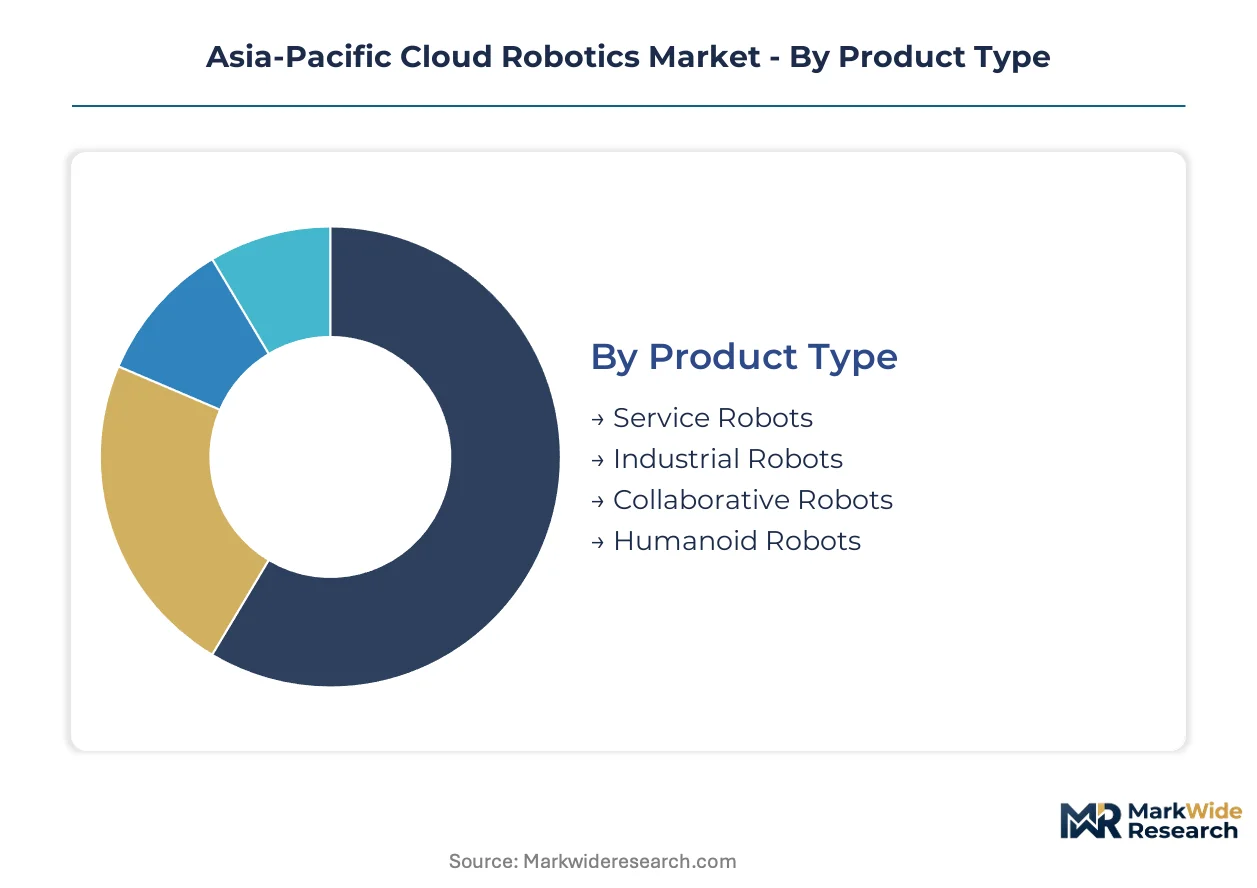
Cloud robotics segmentation reveals how computation offloading strategies differ across robot form factors and infrastructure models. Manufacturers in China's Yangtze River Delta prioritize deployment architectures that balance latency sensitivity against capital efficiency.
Product Type:
Upgrade cycles vary sharply across robot categories, with industrial installations running 7-10 year replacement horizons while collaborative units refresh every 3-4 years.
- Industrial Robots:Heavy-duty articulated systems with six-plus axes dominate automotive and electronics assembly lines across Japan and South Korea. Foxconn-tier contract manufacturers in China's Yangtze River Delta anchor demand, driven by MIIT cloud interoperability mandates requiring centralized fleet orchestration.
- Collaborative Robots:Force-limited cobots with integrated safety sensors enable human-robot workspace sharing without physical guarding. Small and medium enterprises across Southeast Asia adopt these fastest, bypassing legacy automation infrastructure through pay-per-use cloud orchestration models.
- Service Robots:Autonomous mobile units for hospitality and facility management deploy across SoftBank Robotics' Japanese retail channel.
- Humanoid Robots:Bipedal platforms with cloud-hosted locomotion planning remain experimental, concentrated in Japanese R&D corridors under METI robotics roadmaps.
Industrial robots sit at the top of the volume ranking, with collaborative robots climbing the fastest.
Deployment:
Cost tiering separates enterprise-grade private infrastructure from consumption-based public alternatives, with hybrid architectures capturing expanding margin pools.
- Hybrid Cloud:Distributed architectures keep sensitive operational data on-premises while bursting compute to public infrastructure during peak demand cycles. Japan's METI data governance protocols and India's TRAI localization directives make this the default choice for multi-national fleet operators.
- Public Cloud:Elastic compute pools from hyperscale providers enable rapid scaling without capital commitment. Southeast Asian logistics operators favor this tier for seasonal e-commerce fulfillment spikes.
- Private Cloud:Dedicated infrastructure meets South Korea's MFDS medical device software standards for surgical robot deployments.
- On-Premises:Fully localized stacks persist in defense-sensitive Chinese manufacturing facilities subject to cybersecurity review processes.
Hybrid cloud deployments command premium pricing, while public cloud options expand fastest among capital-constrained entrants.
End User:
Application maturity spans decades-old automotive automation against emerging healthcare pathways shaped by medical device software standards.
- Manufacturing:Electronics contract manufacturers pilot cloud-native robot swarms at scale, with digital twin validation compressing commissioning timelines from quarters to weeks.
- Logistics:Third-party operators in Japan and South Korea expand autonomous mobile robot procurement to address e-commerce labor shortages, with subscription-based fleet management displacing perpetual licenses.
- Healthcare:Cloud-connected surgical and rehabilitation robots navigate South Korea's MFDS compliance templates and Australia's TGA therapeutic device frameworks.
- Retail:Inventory scanning and customer service robots deploy through channel-controlled hospitality installations across Japanese urban centers.
Manufacturing dominates current deployment value, with healthcare gaining share fastest as regulatory pathways crystallize.
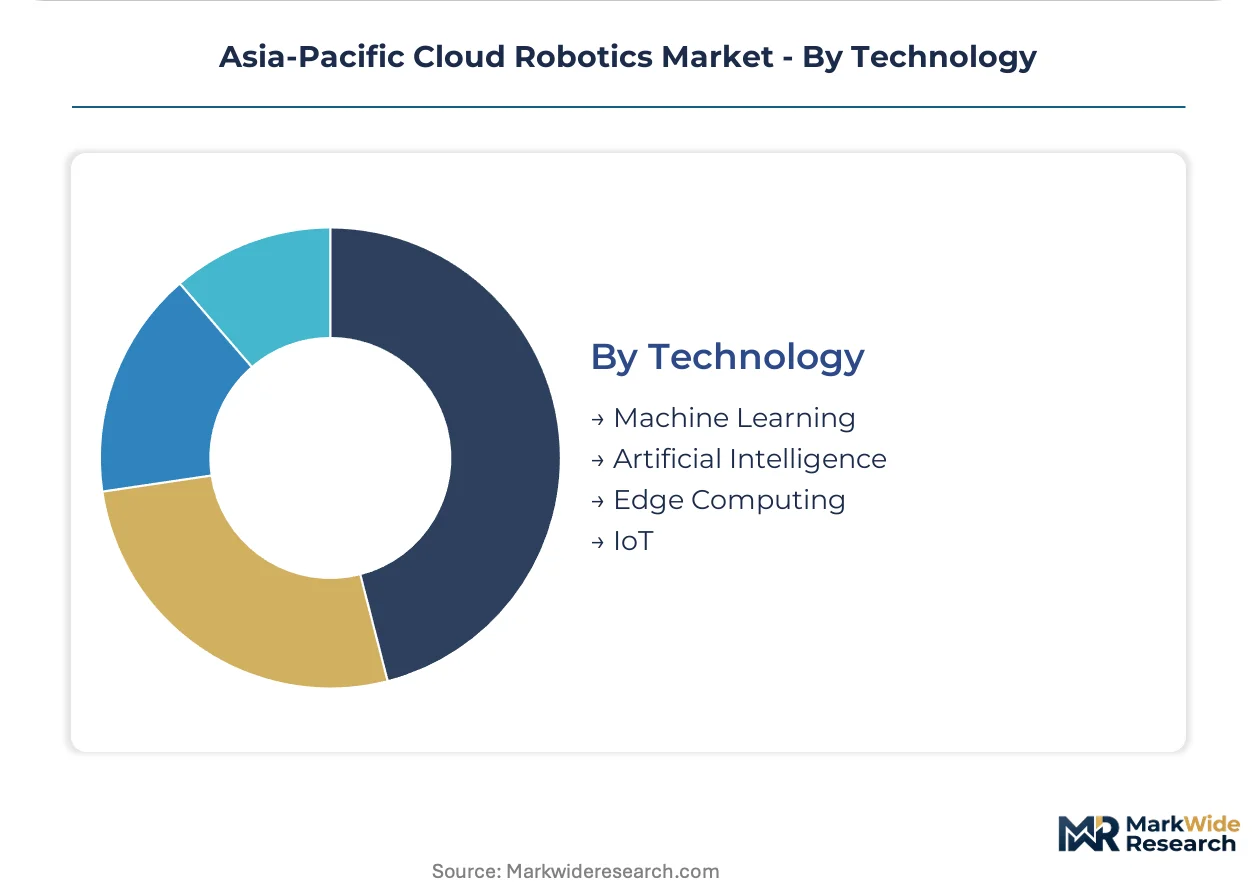
Technology:
Supply concentration in Taiwan and South Korea for advanced AI accelerators shapes how robot fleets embed intelligence at the edge versus cloud.
- Artificial Intelligence:Cloud-hosted model serving enables continuous algorithm updates without production disruption, with sub-100ms latency thresholds determining edge-cloud partitioning.
- Edge Computing:Distributed nodes positioned near manufacturing clusters satisfy real-time task coordination requirements. 5G network slicing from telecom operators enables deterministic control for precision assembly applications.
- Machine Learning:Fleet-wide learning loops aggregate operational data across heterogeneous robot populations to improve path planning and grasp strategies.
- IoT:Sensor fusion pipelines feed telemetry into cloud-based digital twins for predictive maintenance and virtual behavior validation.
Artificial intelligence anchors platform differentiation, with edge computing expanding most quickly as latency requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta manufacturing corridors anchor cloud robotics deployment density across the Asia-Pacific region, with contract electronics manufacturers piloting native robot swarms at scale. Japan's METI robotics roadmaps and South Korea's MFDS medical device software standards create divergent compliance pathways that fragment platform architecture requirements. India's TRAI data localization directives add jurisdictional complexity for multi-national fleet operators seeking seamless cross-border orchestration.
China
Foxconn-tier contract manufacturers drive fleet-scale deployments of cloud-connected industrial robots in Shenzhen and Dongguan facilities. MIIT cloud computing standards enforce interoperability mandates that consolidate domestic platform providers around unified orchestration protocols. The Yangtze River Delta corridor concentrates pilot programs where digital twin validation compresses commissioning timelines from quarters to weeks.
Japan
Third-party logistics operators in Osaka and Nagoya expand autonomous mobile robot procurement to address acute e-commerce fulfillment labor shortages. METI enforces granular audit trail requirements for cloud-connected systems entering industrial facilities, forcing localized compliance module development. SoftBank Robotics maintains channel control across hospitality and retail robot installations throughout Tokyo and Kansai urban centers.
South Korea
Semiconductor and electronics manufacturers in Suwon and Pyeongtaek deploy edge-cloud hybrid architectures for sub-100ms latency task coordination. MFDS medical device software standards create compliance templates for cloud-connected surgical and rehabilitation robots entering regulated healthcare environments. Hanwha Robotics anchors domestic supply for manufacturing automation alongside multinational platform competition.
India
Small and medium enterprises in Pune and Bengaluru manufacturing corridors adopt pay-per-use cloud orchestration models to bypass capital-intensive infrastructure investments. TRAI data localization directives fragment cloud infrastructure deployment strategies, forcing decisions between distributed edge-node architectures and country-specific cloud instances. Talent scarcity in robotics-cloud integration engineering constrains rollout velocity for mid-tier manufacturers lacking DevOps capabilities.
Australia
Mining and resources automation in Western Australia drives demand for remote fleet management capabilities across distributed extraction sites. TGA therapeutic device frameworks impose certification burdens on cloud-connected medical robots entering healthcare supply chains. 5G network slicing from telecom operators enables deterministic control for precision applications in isolated operational environments.
Asia-Pacific Cloud Robotics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-cloud hybrid orchestration and consumption-based service models. The vendor base stratifies across three tiers: hyperscale cloud providers with industrial IoT portfolios, specialized robot fleet software vendors, and hardware-integrated platform operators with captive manufacturing relationships. Strategic archetypes include full-stack integrators, pure-play orchestration specialists, and telecom-affiliated connectivity-layer providers. Competitive intensity concentrates around M&A activity targeting DevOps talent pools and strategic partnerships linking robot hardware OEMs with cloud infrastructure operators.
Within the specialized orchestration tier, Rapyuta Robotics and CloudMinds exemplify managed fleet software approaches that compete against broader industrial cloud portfolios. Huawei anchors the full-stack integrator archetype through in-house production of edge-to-cloud orchestration layers for factory deployments. SoftBank Robotics occupies a distinct position in service robot segments through channel control of hospitality and retail installations.
| Leading Market Players |
|---|
| Rapyuta Robotics |
| CloudMinds |
| Huawei |
| Hit Robot Group |
| SoftBank Robotics |
| Omron Corporation |
| UBTECH Robotics |
| Hanwha Robotics |
| Amazon Web Services |
| Others |
Value Network & Pricing Analysis
Subscription-based fleet procurement from Japan's third-party logistics operators is compressing upfront revenue recognition and forcing platform providers to absorb hardware financing costs into recurring service contracts. This shift toward pay-per-outcome structures concentrates purchasing authority within procurement functions and intensifies margin pressure on vendors lacking captive manufacturing scale.
Pricing Analysis
Input-cost pass-through from Taiwan and South Korea AI accelerator sourcing runs through tiered service contracts rather than hardware markups. Pricing stratifies across premium compliance-certified, standard interoperability, and economy connectivity-only tiers based on METI audit trail capabilities and MIIT localization requirements. Cost compression in the economy tier intensifies because Southeast Asian logistics operators prioritize capital efficiency over edge-computing performance. Small and medium enterprises exhibit highest price sensitivity, while Foxconn-tier manufacturers accept premium positioning for digital twin integration.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Tokyo, and Singapore anchor hub-and-spoke fulfillment patterns for cloud robotics hardware. Manufacturing concentration centers on China for mechanical assemblies, Taiwan for advanced AI accelerators, and South Korea for precision sensors. Component dependencies include high-bandwidth memory modules, 5G modem chipsets, and force-torque sensors. Single-source vulnerability from Taiwan semiconductor fabrication exposes fleet operators to allocation rationing during supply shocks. Distribution runs through authorized system integrators with METI certification for Japanese industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific cloud robotics functions as a stable compounder anchored by MIIT interoperability mandates that lock in recurring platform revenue across multi-year fleet replacement cycles.
For Market Incumbents: Deepen edge-cloud hybrid orchestration capabilities to defend against hyperscaler encroachment into factory automation. Invest in localized compliance modules for India's TRAI data localization directives. Secure captive supply of AI accelerators through strategic partnerships with Taiwan foundries to mitigate semiconductor allocation risk. For New Entrants and Emerging Players: Enter via pay-per-use orchestration models targeting India's capital-constrained mid-tier manufacturers lacking DevOps capabilities. Prioritize Pune and Bengaluru manufacturing corridors where talent scarcity constrains incumbent rollout velocity. Pursue telecom partnerships for 5G network slicing integration as a differentiated go-to-market pathway. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized robot fleet software vendors possessing DevOps talent pools and MIIT-certified interoperability layers. Long-term viability hinges on recurring revenue concentration rather than hardware shipment volume. Monitor MFDS medical device software standard adoption as an inflection signal for healthcare robotics valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Cloud Hybrid Architecture Deployment | Balances METI data governance with elastic compute scaling for Japanese manufacturers. |
| 5G Network Slicing Partnership | Enables deterministic sub-100ms control for South Korean precision assembly applications. |
| MIIT Interoperability Certification | Unlocks Foxconn-tier contract manufacturer procurement in Yangtze River Delta corridors. |
| DevOps Talent Acquisition | Addresses robotics-cloud integration scarcity constraining India's mid-tier rollout velocity. |
| Digital Twin Platform Integration | Compresses commissioning timelines from quarters to weeks for electronics contract manufacturers. |
Research Methodology
Bottom-up manufacturing automation modeling reconciled against top-down cloud infrastructure tracking forms the analytical core of this study. Primary interviews with robotics fleet managers, cloud platform engineers, METI compliance officers, and third-party logistics procurement directors combined with secondary validation from MIIT policy filings, METI robotics roadmap documents, and hyperscaler industrial IoT capex disclosures. Triangulation against customs data for robot component trade flows and 5G network deployment statistics anchored volume estimates.
Historical trendline analysis of industrial robot replacement cycles and cloud service consumption patterns informed projection frameworks across the modeling period. Segmentation dimensions modeled include robot form factor, deployment architecture, end-use industry, and regulatory compliance tier. CAGRs derived from elasticity-adjusted adoption curves incorporating labor shortage severity indices and interoperability mandate implementation timelines. Edge computing node density and 5G base station rollout served as industry-specific forecast inputs.
Inputs from primary fieldwork and regulatory documentation were available through the study window; gaps in real-time fleet utilization telemetry from private cloud deployments introduce uncertainty bands around operational efficiency assumptions. Forecasts reflect documented assumptions regarding MIIT standard enforcement velocity and cross-border data flow policy stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
Asia Pacific Warehouse Robotics Market
Robotics and Automation
North America Data Center Robotics Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Global Adaptive Robot Market
Robotics and Automation
Human-Robot Collaborative Picking Optimization Platforms Market
Robotics and Automation
Non-Medical Biomimetic Robots Market
Robotics and Automation
Europe Agricultural Robot Market
Robotics and Automation
Nanorobotics Market
Robotics and Automation
Eldercare-Assistive Robots Market
Robotics and Automation
Assistive Technology Market