
 North America Agricultural Robots and Mechatronics Market | 2026-2036
North America Agricultural Robots and Mechatronics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Robots and Mechatronics Market Analytics
The EPA's Tier 4 Final emissions standards for off-road diesel engines is realigning the cost-of-entry calculus for equipment manufacturers serving North American growers. Deere & Company anchors its competitive position through captive manufacturing of powertrain and autonomy stacks at Iowa and Illinois facilities. AGCO Corporation differentiates via targeted R&D intensity in sensor-fusion architectures for mixed-fleet environments. Trimble Inc. extends its influence through channel control of correction-service networks that underpin GPS-dependent robotic systems across the Great Plains.
Agricultural robots and mechatronics denote electro-mechanical systems integrating actuators, sensors, and control algorithms to perform crop production tasks with minimal human intervention, typically operating at sub-inch GPS accuracy and processing visual data at 30-60 frames per second for real-time decision loops. Their primary commercial purpose centers on substituting capital for labor in planting, cultivation, and harvest operations while reducing input waste through variable-rate application. Autonomous tractors occupy the largest installed base and margin pool, reflecting decade-long amortization cycles and dealer finance ecosystems that lock in replacement demand. Weed control robots represent the fastest-expanding category, driven by computer-vision platforms that enable mechanical removal without herbicide application in organic and conventional systems alike. Sensor technology underpins differentiation across all product categories, with LiDAR and multispectral imaging modules becoming standard configuration rather than premium option.
The FAA governs commercial drone operations above farmland through Part 107 waivers and beyond-visual-line-of-sight rulemaking that directly shapes aerial robotics deployment timelines. OSHA and state-level agricultural safety boards set operator- proximity standards for autonomous ground vehicles, influencing kill-switch architecture and geofencing requirements in equipment design. The USDA's Climate-Smart Commodities program creates compliance-linked revenue streams for producers who document precision-agriculture adoption, effectively subsidizing robotic system purchases. Stakeholders must monitor how NHTSA's evolving autonomous-vehicle classification framework eventually absorbs farm equipment operating on public roadways between fields.
Market Dynamics
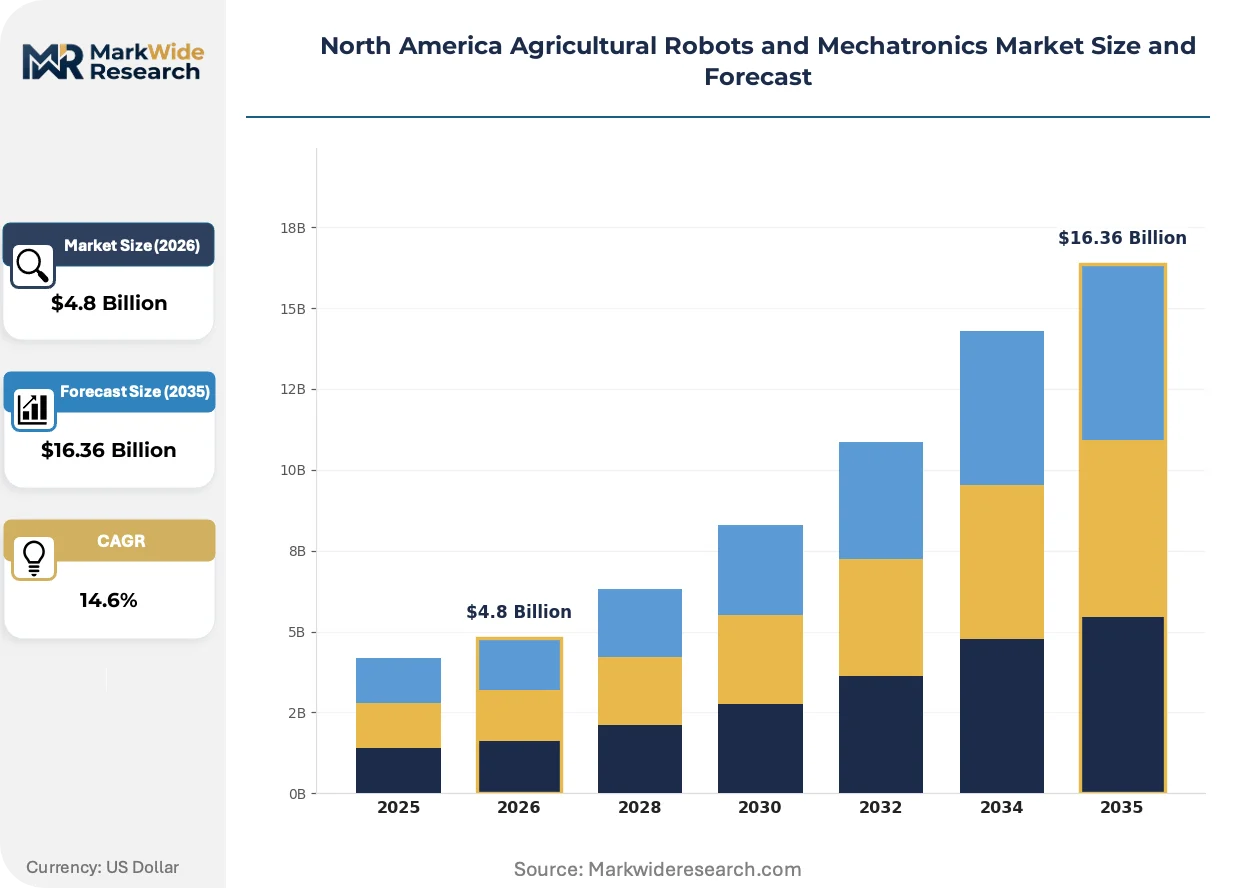
The USDA's precision agriculture incentives and EPA Tier 4 Final emissions standards are compressing equipment replacement cycles across North American row-crop and specialty crop operations. Capital allocation is pivoting from incremental machinery upgrades toward integrated autonomy stacks that satisfy dual compliance requirements.
Growth Catalysts
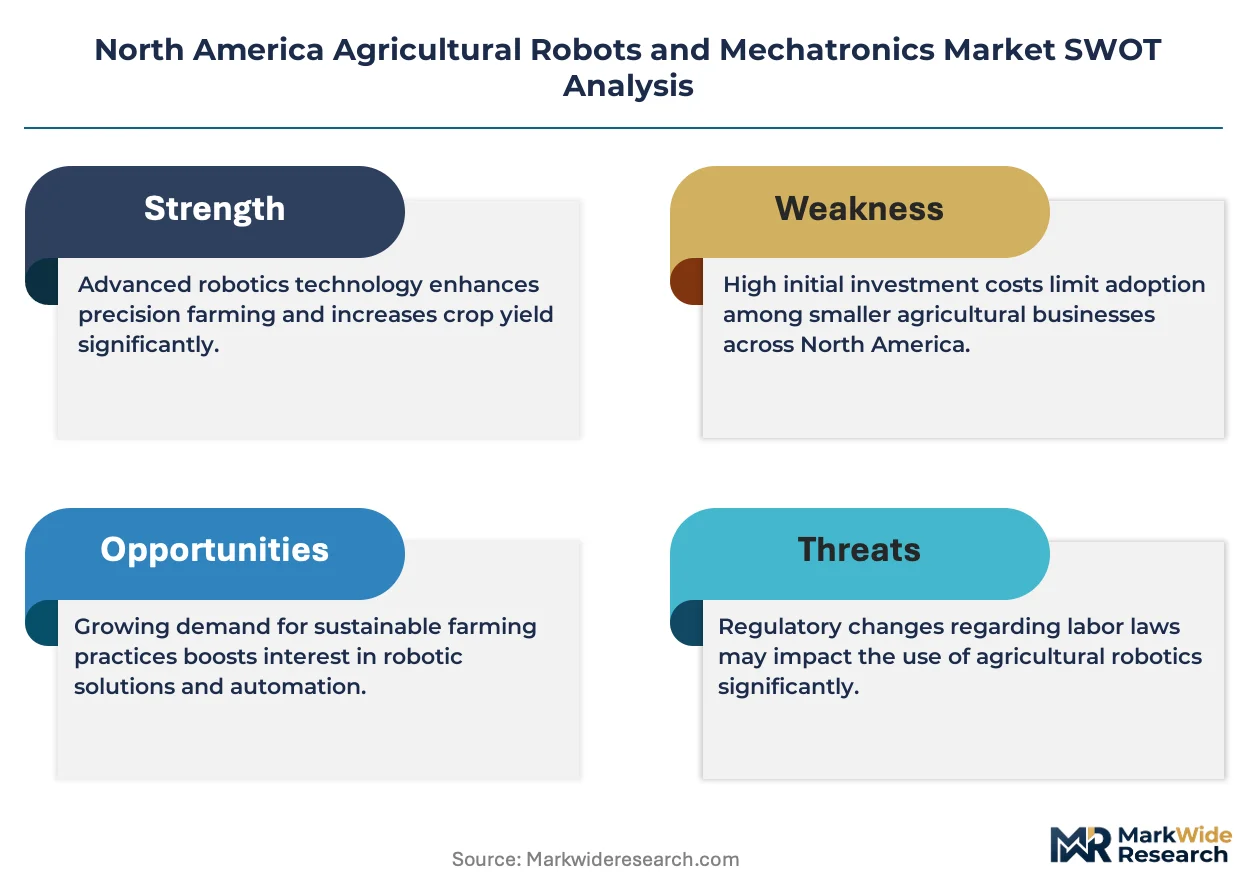
- Labor scarcity in California's Central Valley:Specialty crop producers deploy computer-vision weeding systems to offset seasonal workforce gaps while meeting state-level pesticide reduction mandates.
- USDA Climate-Smart Commodities program:Compliance-linked revenue streams subsidize robotic system purchases for producers who document precision-agriculture adoption.
- LiDAR cost curves:Solid-state sensor modules are dropping below the threshold for standard configuration on mid-range autonomous tractors rather than premium option status.
Market Restraints
- Dealer finance ecosystem concentration:Captive lending programs through major OEM networks lock producers into replacement cycles that delay third-party robotics adoption.
- Public roadway classification uncertainty:NHTSA has not resolved autonomous-vehicle framework absorption for farm equipment transiting between fields, creating insurance and liability friction.
- Powertrain retooling capex:Electrification roadmaps require foundry and battery-pack investments that compress R&D budgets for smaller equipment manufacturers.
Strategic Opportunities
- Canadian Prairie Provinces:Large-scale grain operations in Saskatchewan and Manitoba remain underpenetrated by autonomous cultivation systems relative to the US Corn Belt.
- FAA Part 107 BVLOS rulemaking:Beyond-visual-line-of-sight waivers for aerial application drones will unlock aerial robotics deployment at scale once finalized.
- Sensor-fusion convergence:Integration of multispectral imaging with real-time soil moisture telemetry enables variable-rate application decisions without human-in-the-loop intervention.
Industry Challenges
- Autonomy software talent scarcity:Recruitment of robotics engineers with agricultural domain expertise lags demand from both incumbent OEMs and venture-backed entrants.
- Legacy fleet integration complexity:Mixed-farm environments with 10-15 year equipment amortization cycles create interoperability requirements that slow full-autonomy deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Robots and Mechatronics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harvesting Robots, Seeding Robots, Weed Control Robots, Autonomous Tractors Technology: Machine Learning, Computer Vision, Sensor Technology, GPS Navigation Application: Field Crops, Greenhouse, Livestock, Horticulture End User: Farmers, Agricultural Producers, Agribusiness, Research Institutes |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., AG Leader Technology, DroneDeploy, Trimble Inc., Harvest Automation, Clearpath Robotics, Autonomous Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Robots and Mechatronics Market Evolving Landscape
Electrification and computer-vision autonomy are converging to redefine equipment architecture across North American agriculture. The transition from diesel-mechanical to electric-drive platforms is compressing powertrain supplier bases while expanding software-defined functionality.
Computer-vision weeding platforms are integrating mechanical removal actuators with sub-inch GPS guidance to eliminate herbicide passes in organic and conventional systems alike. California specialty crop producers are adopting these systems fastest due to state pesticide restrictions. The technology is integrating cultivation and planting workflows into unified autonomy stacks that reduce equipment count per acre.
EPA emissions standards for off-road diesel engines are forcing electrification roadmaps that favor battery-electric and hydrogen fuel-cell powertrains in equipment categories above 100 horsepower. Manufacturers serving the Corn Belt are responding with modular battery-pack architectures that preserve frame compatibility. The regulatory pressure is accelerating dealer technician retraining requirements and service bay electrical infrastructure investment.
Service contract unbundling is fragmenting the traditional dealer revenue model across the Great Plains. Large row-crop operators are negotiating direct telemetry subscriptions with autonomy software providers, bypassing equipment dealer networks for updates and diagnostics. This pattern is most visible in Iowa and Illinois where autonomous tractor fleets exceed 50 units per operation.
North America Agricultural Robots and Mechatronics Market Segmentation
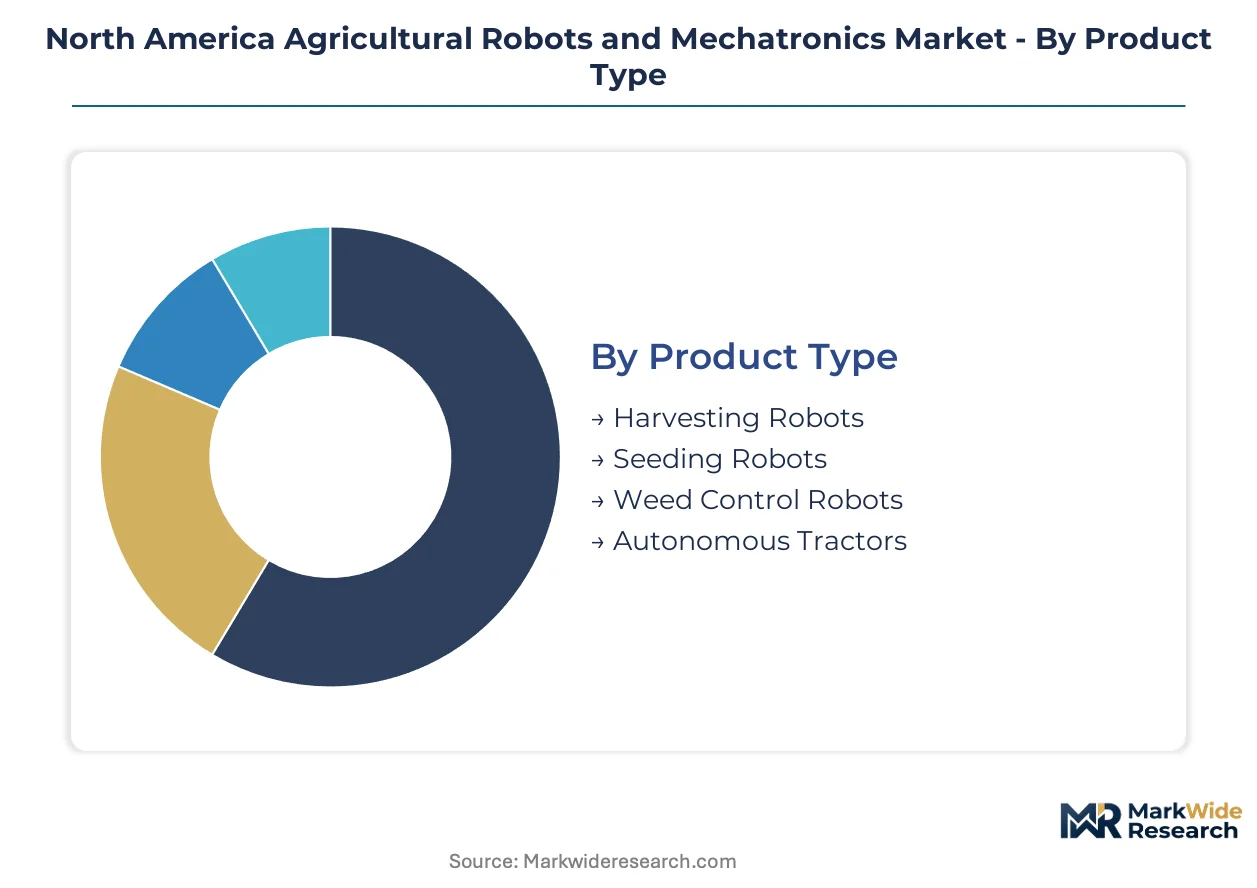
Segmentation in agricultural robotics reveals how distinct technology stacks, operational environments, and buyer economics create divergent commercialization pathways. Each dimension carries specific regulatory burdens and capital intensity profiles that shape vendor go-to-market strategies.
Product Type:
EPA Tier 4 Final certification applies to diesel-powered autonomous tractors and large harvesting platforms, while electric-drive weed control robots navigate OSHA proximity standards and state-level organic certification requirements.
- Autonomous Tractors:Electro-mechanical platforms integrating GPS guidance, variable-rate controllers, and implement automation for tillage through harvest operations. Demand concentrates in Iowa and Illinois row-crop operations where dealer finance ecosystems and decade-long amortization cycles lock in replacement demand. EPA emissions compliance and NHTSA roadway classification uncertainty create dual regulatory friction for fleet expansion.
- Weed Control Robots:Computer-vision systems with mechanical removal actuators operating at sub-inch accuracy without herbicide application. California Central Valley specialty crop producers deploy these fastest to satisfy state pesticide reduction mandates while offsetting seasonal labor scarcity. OSHA operator-proximity standards influence kill-switch architecture and geofencing requirements.
- Harvesting Robots:Robotic arms with end-effectors calibrated to crop-specific bruise thresholds and maturity detection algorithms.
- Seeding Robots:Precision planting platforms with real-time seed spacing adjustment and depth control based on soil resistance telemetry.
Autonomous tractors sit at the top of the volume ranking, with weed control robots climbing the fastest.
Technology:
Cost tier separation is pronounced: GPS navigation and basic sensor packages occupy mid-range equipment, while machine learning inference engines and multispectral computer vision command premium positioning.
- Computer Vision:Multispectral imaging systems processing 30-60 frames per second for real-time crop health, weed identification, and maturity assessment. California organic operations and Florida citrus groves drive adoption where labor substitution intersects with input reduction mandates. Solid-state LiDAR cost curves are pushing this from premium option toward standard configuration.
- Machine Learning:Edge-computing inference models trained on region-specific crop and soil databases for autonomous decision loops. Large-scale Corn Belt operators negotiate direct telemetry subscriptions with software providers, bypassing dealer networks for model updates. Talent scarcity for agricultural-domain robotics engineers constrains development velocity.
- Sensor Technology:Integrated LiDAR, radar, and soil moisture telemetry modules enabling closed-loop variable-rate application.
- GPS Navigation:RTK correction-dependent positioning systems requiring channel control of correction-service networks for sub-inch accuracy.
GPS navigation commands the largest installed base, though machine learning is gaining share fastest through software-defined functionality expansion.
Application:
Application maturity correlates with operational scale and labor elasticity: field crops permit full autonomy, while horticulture and livestock retain human-in-the-loop requirements for biological variability.
- Field Crops:Large-scale grain and oilseed operations across the US Corn Belt and Canadian Prairie Provinces. Autonomous cultivation and harvest systems amortize across thousands of acres with minimal crop variability. USDA Climate-Smart Commodities program documentation requirements subsidize precision-agriculture adoption.
- Horticulture:Specialty fruit and vegetable production with high-value per-acre economics and delicate handling requirements. Greenhouse and open-field strawberry operations in California and Florida deploy computer-vision platforms for selective harvesting. Biological variability forces slower autonomy deployment than row crops.
- Greenhouse:Controlled-environment operations with fixed infrastructure enabling robotic gantry systems for planting through packaging.
- Livestock:Dairy and poultry automation for feeding, milking, and health monitoring with animal welfare compliance overlays.
Field crops dominate current volume, with horticulture showing steepest expansion trajectory as computer-vision platforms mature for selective handling tasks.
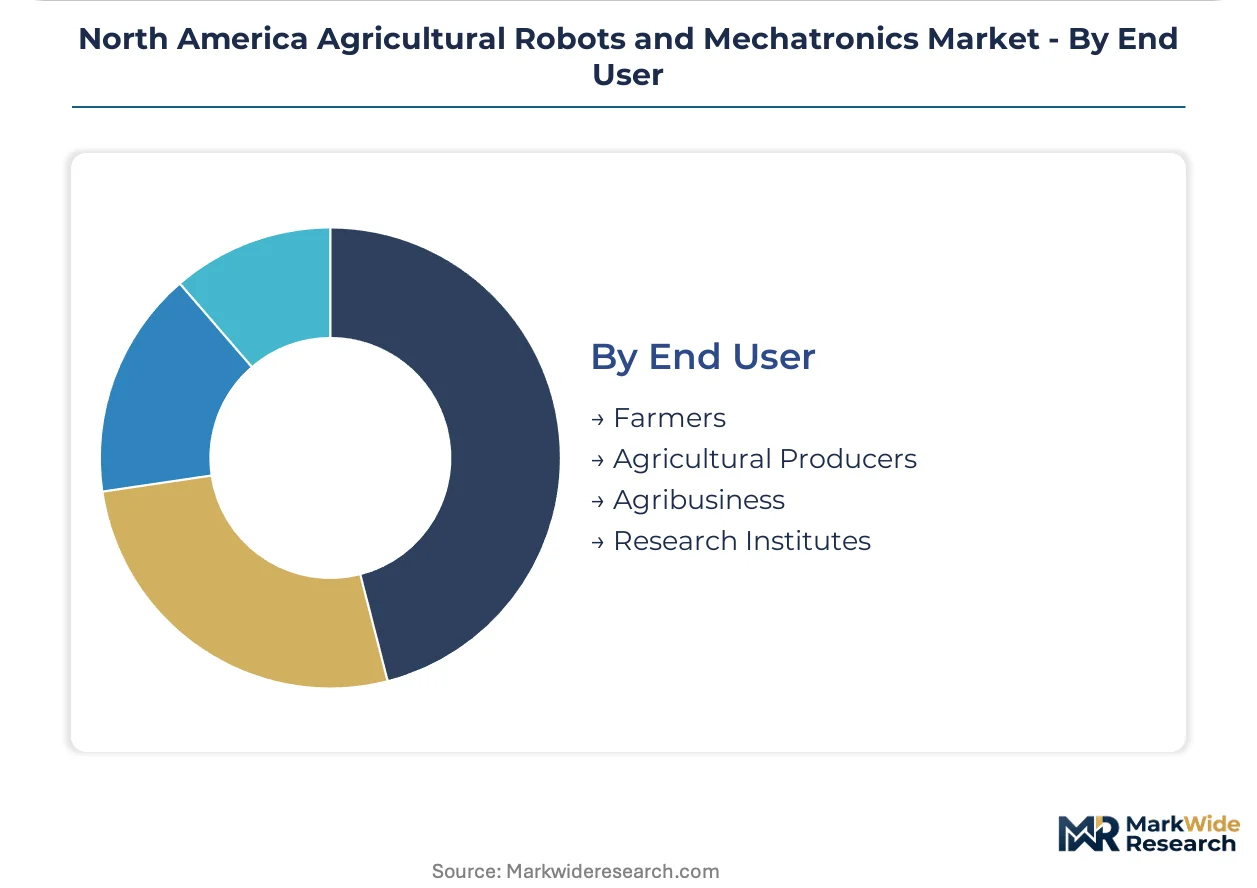
End User:
Customer type determines procurement modality: agribusiness entities negotiate enterprise telemetry contracts, while individual farmers remain tethered to dealer finance ecosystems.
- Agribusiness:Vertically integrated operators with autonomous fleets exceeding 50 units and direct software provider relationships. Iowa and Illinois-based operations unbundle service contracts from equipment purchase, subscribing to autonomy stacks independently of dealer networks. Capital allocation prioritizes integrated compliance solutions for EPA and USDA program requirements.
- Farmers:Owner-operators with 1,000-5,000 acre holdings dependent on captive lending programs through major OEM networks. Replacement cycles delay third-party robotics adoption despite precision-agriculture incentive eligibility. Technician retraining and service bay electrical infrastructure investments create switching costs.
- Agricultural Producers:Mid-scale cooperatives and family partnerships with mixed-fleet environments and 10-15 year equipment amortization cycles.
- Research Institutes:USDA extension services and land-grant university programs testing autonomy platforms for commercialization pathway validation.
Agribusiness entities lead current procurement volume, with farmers representing the largest addressable expansion pool as financing models evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Robotics engineering talent concentrates in Midwest university corridors and California research clusters, anchoring North American agricultural automation development. Equipment procurement patterns diverge sharply between US Corn Belt scale operations and Canadian Prairie grain systems. Mexican specialty crop zones remain underpenetrated by autonomous cultivation platforms.
United States
Iowa and Illinois host the densest autonomous tractor fleet concentrations, where agribusiness operators exceed 50 units per site and negotiate direct telemetry subscriptions. EPA Tier 4 Final emissions compliance accelerates electrification roadmaps for diesel-powered platforms above 100 horsepower. California's Central Valley specialty crop producers deploy computer-vision weeding systems fastest to satisfy state pesticide reduction mandates.
Canada
Saskatchewan and Manitoba grain operations remain underpenetrated by autonomous cultivation systems relative to US benchmarks, creating expansion headroom for GPS-guided platforms. Health Canada's PMRA pesticide regulations are less restrictive than California's, slowing mechanical weeding adoption despite comparable labor scarcity. Prairie equipment dealers face technician retraining investments for battery-electric service bay infrastructure.
Mexico
Bajío Region berry and vegetable producers confront seasonal workforce gaps that mirror California's Central Valley dynamics. Mexico's national agricultural regulator SADER lacks precision-agriculture incentive programs comparable to USDA Climate-Smart Commodities, compressing robotic system procurement budgets. Jalisco's agro-industrial corridor shows early drone deployment for aerial application under provisional COFEPRIS operational waivers.
North America Agricultural Robots and Mechatronics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across North America's agricultural robotics sector. Equipment manufacturing consolidates around incumbent OEMs with captive dealer finance ecosystems, while software-defined autonomy stacks fragment toward venture-backed entrants. Three archetypes dominate: integrated powertrain-autonomy manufacturers, sensor-fusion platform specialists, and correction-service network operators. Competitive dynamics center on M&A absorption of computer-vision startups and strategic partnerships bridging legacy fleet interoperability gaps.
Among Midwest-anchored industrial conglomerates, Deere & Company and AGCO Corporation exemplify integrated manufacturing archetypes with captive production facilities. Trimble Inc. occupies a distinct position anchoring GPS-dependent system accuracy through correction-service channel control. These three entities represent divergent strategic postures: equipment-centric vertical integration versus infrastructure-layer platform dominance.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| AG Leader Technology |
| DroneDeploy |
| Trimble Inc. |
| Harvest Automation |
| Clearpath Robotics |
| Autonomous Solutions Inc. |
| Others |
Value Network & Pricing Analysis
Lithium carbonate spot indices and rare-earth magnet benchmarks cascade through North American agricultural robotics supply chains, compressing margins on electric-drive powertrains while amplifying price stratification between premium autonomy stacks and standard GPS-guided platforms. Equipment manufacturers absorb input volatility through modular battery-pack architectures that preserve frame compatibility across tiered product lines.
Pricing Analysis
The bundled-vs-unbundled service split now defines competitive positioning across the Great Plains and Corn Belt. Three-tier pricing structure across premium, standard, and economy levels separates agribusiness operators negotiating direct telemetry subscriptions from farmers tethered to captive dealer finance programs. Price differentiation hinges on software-defined functionality depth and EPA Tier 4 Final certification status. Pricing pressure stems from solid-state LiDAR cost curves dropping below standard-configuration thresholds. Farmers with 1,000-5,000 acre holdings exhibit highest price sensitivity due to technician retraining and service bay electrical infrastructure switching costs.
Supply Chain Analysis
Regional distribution centers in Iowa, Illinois, and California anchor hub-and-spoke patterns that feed dealer networks across the Corn Belt and Central Valley. Manufacturing concentration in the US Midwest, Mexico's Bajío Region, and Canadian Prairie Provinces creates geographic clustering around agricultural demand centers. Battery-cell supply draws from South Korean and Japanese producers, while solid-state LiDAR modules source from Taiwanese optical foundries. Single-source vulnerability in RTK correction-service networks threatens GPS-dependent system accuracy. Distribution runs through OEM-captive dealer ecosystems with decade-long amortization cycle lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American agricultural robotics functions as a geographic-arbitrage play where Canadian Prairie underpenetration relative to US Corn Belt benchmarks offers expansion headroom at lower customer acquisition cost, while California's state-level pesticide restrictions create compliance-premium pricing power unavailable in Health Canada PMRA jurisdictions.
For Market Incumbents: Hedge against software-defined unbundling by deepening captive control over correction-service networks and autonomy stack telemetry channels. Acquire computer-vision startups with California organic-certification domain expertise to defend against venture-backed entrants targeting specialty crop weeding. Prioritize R&D intensity in sensor-fusion architectures for mixed-fleet interoperability. For New Entrants and Emerging Players: Direct-to-farm digital sales channels bypass dealer finance concentration in Saskatchewan and Manitoba grain operations. Target Canadian Prairie Provinces for GPS-guided cultivation platforms where autonomous penetration lags US benchmarks. White-space exists in greenhouse gantry systems for controlled-environment horticulture. Pursue FAA Part 107 BVLOS waiver partnerships for aerial application drone deployment. For Investors and Strategic Acquirers: Consolidation pressure builds where autonomy software talent scarcity intersects with legacy fleet integration complexity. Five-to-ten year viability favors sensor-fusion platform specialists with agricultural-domain machine learning training datasets. Target acquisition archetype: venture-backed computer-vision startups with California pesticide-reduction compliance traction. Watch NHTSA autonomous-vehicle classification framework resolution for farm equipment roadway transit as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Fusion Platform Integration | Unifies LiDAR, radar, and soil telemetry into closed-loop variable-rate application systems for Corn Belt operators. |
| Direct Telemetry Subscription Launch | Bypasses dealer networks for autonomy software updates, capturing recurring revenue from Iowa and Illinois agribusiness fleets. |
| Canadian Prairie Geographic Expansion | Addresses underpenetrated Saskatchewan and Manitoba grain markets with GPS-guided cultivation platforms. |
| Battery-Pack Backward Integration | Secures supply of modular electric-drive architectures compliant with EPA Tier 4 Final emissions roadmaps. |
| FAA BVLOS Waiver Partnership | Unlocks aerial robotics deployment at scale for California Central Valley specialty crop producers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with agricultural equipment procurement directors, autonomy software engineers, dealer network operations managers, and USDA extension service specialists with secondary validation. Primary sources included OEM product development executives, Tier 1 sensor module suppliers, and large-scale farm operators exceeding 10,000 acres. Secondary data drew from EPA Tier 4 Final certification filings, FAA Part 107 waiver databases, USDA Climate-Smart Commodities program documentation, SEC 10-K equipment manufacturer disclosures, and state-level pesticide regulation compendia. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Comparable-period anchoring tied projection models to historical replacement cycle patterns across decade-long equipment amortization horizons. Segmentation dimensions modeled included product type, technology stack, application maturity, and end-user procurement modality. CAGRs derived from equipment shipment trajectories, software subscription attach rates, and regulatory compliance deadline impacts. Forecast inputs incorporated LiDAR cost curve velocity, dealer finance ecosystem concentration effects, and precision-agriculture incentive program uptake elasticity.
Commodity price volatility, regulatory timeline slippage, and autonomy talent recruitment bottlenecks are the dominant revision risks that could compress or extend modeled growth trajectories. Forecasts reflect documented assumptions around EPA emissions enforcement consistency and USDA program continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Nanorobots in Healthcare Market
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Healthcare Companion Robots Market