
 Bakery Packaging Market | 2026-2036
Bakery Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Packaging Market Analysis
Packaging engineering talent is bifurcating between legacy polymer specialists and fiber-based material scientists, creating a skills gap that slows plant conversions. Amcor Plc leverages its global film extrusion footprint to sustain supply agreements with multinational bread brands. Mondi Group anchors European demand through integrated kraft paper and corrugated operations. Huhtamaki competes in molded fiber trays for artisan bakery segments where grease resistance specifications exceed standard offerings.
Bakery packaging encompasses primary and secondary containment systems engineered from paperboard, plastic films, aluminum laminates, or molded pulp, designed to preserve moisture barriers, prevent oil migration, and extend shelf stability of flour-based goods. The material dimension shows paper grades capturing premium positioning as bakeries abandon polystyrene foam under regulatory pressure, while plastic films retain dominance in high-speed automated bread lines where heat-seal throughput dictates operational economics. Flexible packaging formats lead volume across the product type dimension, though rigid clamshells command margin pools in patisserie and cake segments where visual presentation drives purchase decisions.
The FDA governs indirect food contact substances through 21 CFR regulations that limit additive migration into baked goods, while EPA rules on per- and polyfluoroalkyl substances are forcing coating reformulations across US manufacturing bases. In Europe, EFSA migration limits and the EU Packaging and Packaging Waste Regulation are reshaping material specifications, with REACH compliance adding testing burdens for imported films. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to internalize recycling infrastructure or outsource compliance to specialized waste management partners.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing conversion timelines for industrial bakeries, forcing simultaneous retooling of extrusion lines and coating systems while polymer engineers and fiber scientists operate on divergent knowledge bases.
Growth Catalysts
- Extended Producer Responsibility schemes:Germany's packaging ordinance mandates recyclability quotas that accelerate demand for mono-material films and water-based barrier coatings in bread packaging.
- Artisan bakery expansion:Windowed paperboard boxes with compostable films capture premium positioning as patisseries abandon polystyrene foam for visual merchandising.
- High-speed automation:Heat-seal plastic films retain dominance in automated bread lines where throughput economics favor polymer over fiber alternatives.
Market Restraints
- Pulp price volatility:Kraft paper input costs fluctuate with Nordic softwood supply constraints, compressing margins for integrated corrugated operations.
- Coating reformulation lag:EPA rules on per- and polyfluoroalkyl substances force migration away from grease-resistant fluorinated chemistries before alternatives achieve scale.
- Skills bifurcation:Legacy polymer specialists and emerging fiber-based material scientists occupy non-overlapping talent pools, slowing plant conversion engineering.
Strategic Opportunities
- Molded fiber tray penetration:Grease-resistant specifications in artisan segments exceed standard offerings, creating white space for advanced barrier technologies.
- REACH compliance services:Testing burdens for imported films into Europe generate outsourced revenue streams for specialized certification providers.
- In-store bakery counters:Retail chains expand fresh bakery footprints, demanding localized packaging supply with shorter lead times than multinational bread brands.
Industry Challenges
- Barrier coating certification timelines:EFSA migration limit testing extends product development cycles for water-based alternatives to polyethylene laminates.
- Legacy extrusion asset stranding:Multilayer film lines face accelerated obsolescence under single-material recyclability mandates, requiring capital redeployment decisions.
- Supply chain reconfiguration friction:Integrated kraft-to-corrugated operations must coordinate fiber sourcing with converting capacity across divergent regional demand patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Packaging Market |
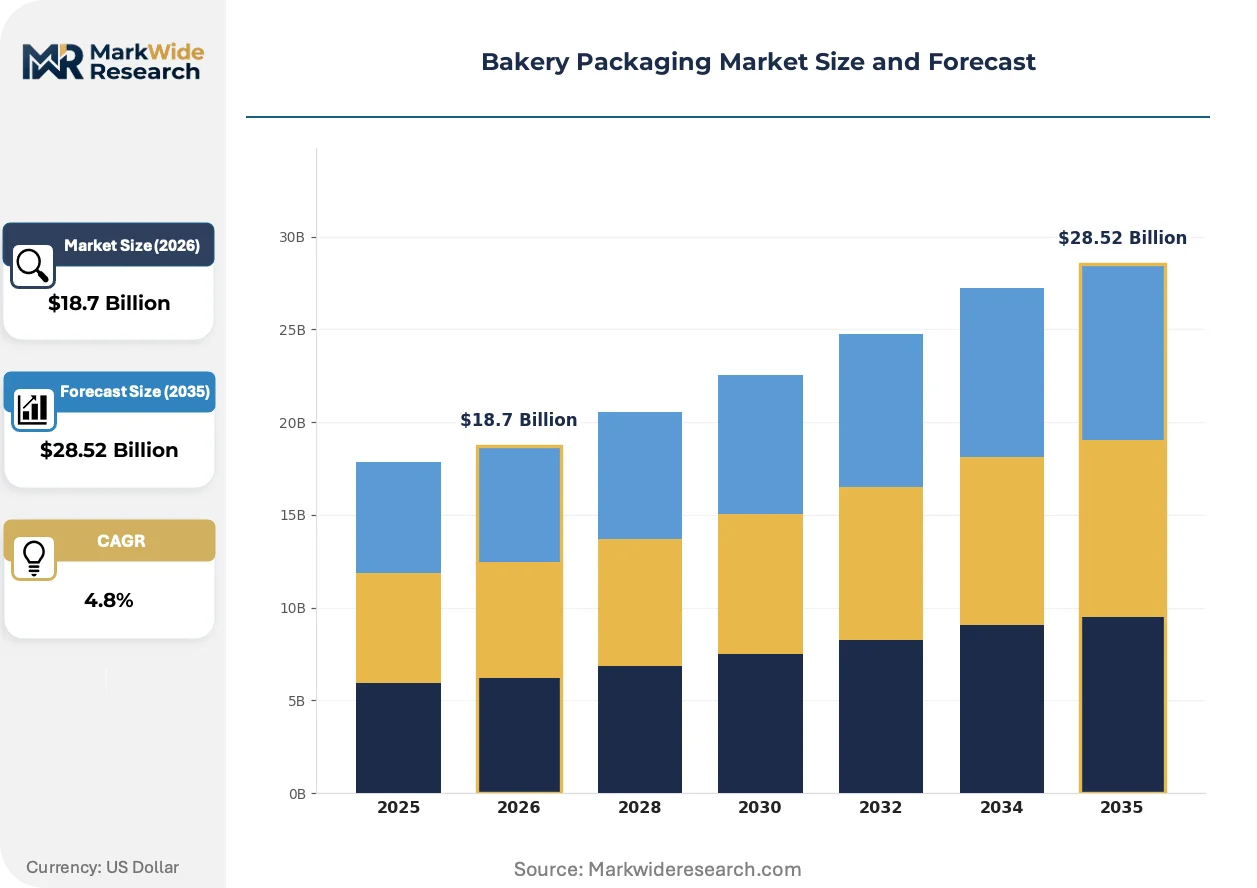
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Trays, Wraps Material: Paper, Plastic, Glass, Foam End User: Retailers, Bakeries, Food Service, Wholesalers Packaging Type: Flexible, Rigid, Resealable, Take-Out |
| Companies Covered | Amcor Plc, Mondi Group, Sealed Air, Berry Global Inc., Smurfit Kappa, WestRock Company, Huhtamaki, TC Transcontinental, Bemis Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Packaging Market Emerging Trajectories
Material science advances and regulatory compression are converging to redefine barrier performance standards, with sustainability specifications now dictating equipment investment priorities ahead of pure cost optimization.
Water-based barrier coatings are supplanting polyethylene laminates in premium bread bags and pastry wraps. Artisan bakeries in France and Belgium adopt these films for compostability certifications. The shift is compressing demand for conventional multilayer structures while elevating coating chemistry to core competitive capability.
REACH compliance requirements are reshaping raw material qualification protocols for any packaging destined for European markets. ECHA substance restrictions now cover slip agents and colorants previously standard in bakery films. Small and mid-sized converters face disproportionate testing cost burdens, accelerating consolidation toward integrated suppliers with captive laboratories.
Direct-store-delivery networks are fragmenting procurement authority away from centralized national bakery chains. Regional distributors now specify packaging formats based on local shelf-life requirements and municipal composting infrastructure availability. This pattern is most pronounced in Italy and Spain, where bakery cooperatives retain stronger channel influence than northern European markets.
Bakery Packaging Market Segmentation
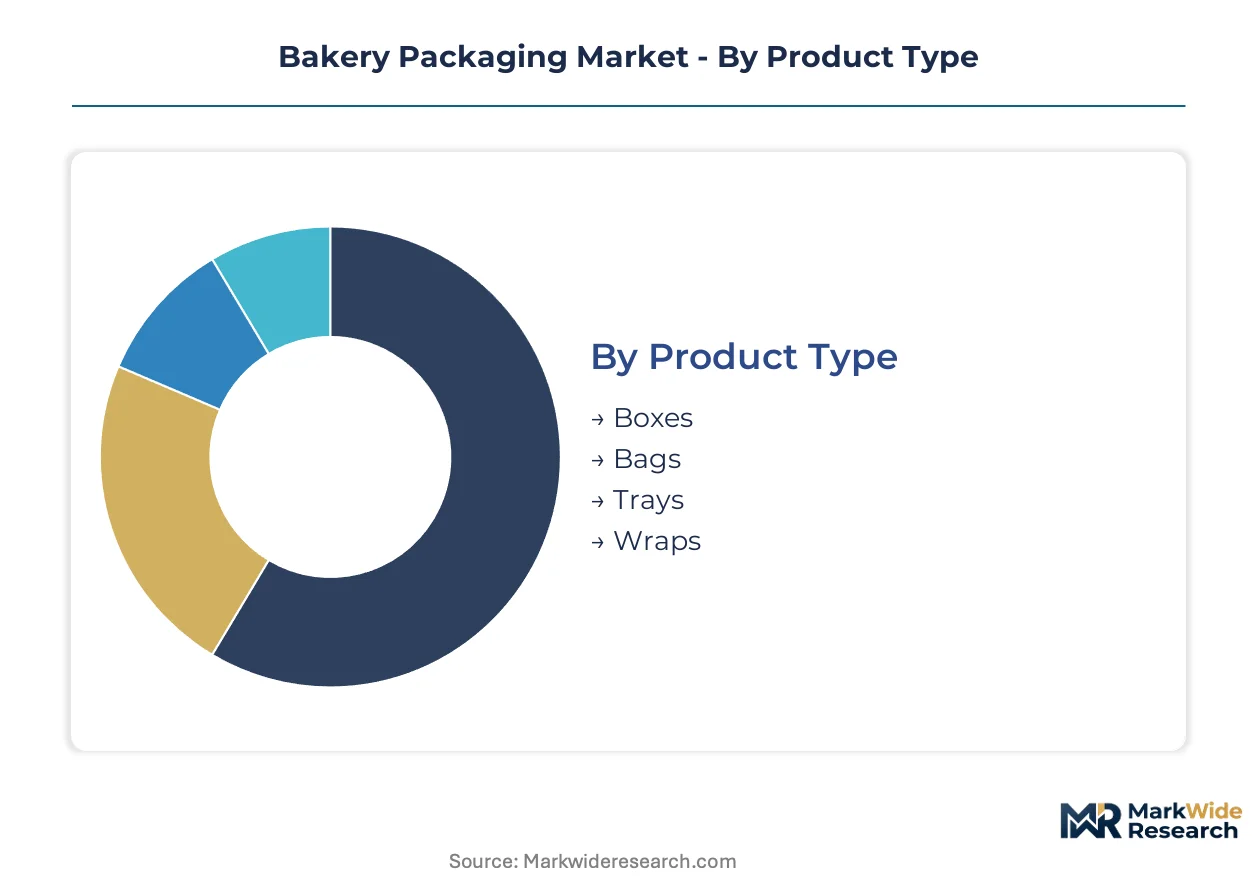
Bakery packaging segmentation reveals how margin pools concentrate in formats balancing barrier performance with regulatory compliance. Material choices and end-use specifications diverge sharply between artisan patisseries and industrial bread operations.
Product Type:
Margin pools concentrate in formats enabling visual merchandising while meeting grease-resistance specifications.
- Boxes:Windowed paperboard constructions with compostable film windows command premium positioning in patisserie and cake segments. French and Belgian artisan bakeries drive specifications requiring structural integrity for layered desserts combined with biodegradability certifications. The segment captures the highest unit margins where presentation directly influences purchase decisions.
- Bags:Heat-sealable plastic films dominate high-speed automated bread lines where throughput economics favor polymer over fiber alternatives. German industrial bakeries specify mono-material polyethylene structures to meet recyclability quotas under extended producer responsibility schemes. This format represents the largest volume pool across all bakery packaging.
- Trays:Molded fiber constructions with advanced barrier coatings serve grab-and-go bakery counters in retail chains.
- Wraps:Grease-resistant papers and films handle individual pastry protection in food service distribution.
The dominant share belongs to Bags, while Boxes is closing the gap fastest through premium positioning in patisserie segments.
Material:
Cost tiers separate legacy polymer systems from emerging fiber-based alternatives facing coating reformulation timelines.
- Paper:Kraft paper and paperboard grades capture positioning as bakeries abandon polystyrene foam under regulatory pressure. Nordic softwood supply constraints create input cost volatility for integrated corrugated operations. The material commands premium positioning in European markets where EFSA migration limits and EU Packaging and Packaging Waste Regulation accelerate transitions.
- Plastic:Multilayer films retain dominance in applications where moisture barrier and heat-seal throughput dictate operational economics. EPA rules on per- and polyfluoroalkyl substances are forcing coating reformulations before alternatives achieve commercial scale. Legacy extrusion assets face accelerated obsolescence under single-material recyclability mandates.
- Glass:Limited application in premium dessert presentations where reusability programs operate.
- Foam:Polystyrene constructions face phase-out across EU markets under regulatory compression.
Plastic retains volume leadership, though Paper is expanding most quickly through regulatory-driven substitution.
End User:
Procurement authority fragmentation creates divergent specification requirements across channel types.
- Retailers:In-store bakery counters demand localized packaging supply with shorter lead times than national bread brands. Italian and Spanish retail chains specify formats based on municipal composting infrastructure availability. Direct-store-delivery networks fragment procurement authority away from centralized purchasing.
- Bakeries:Industrial operations in Germany drive sophisticated specifications for high-speed lines, while artisan patisseries prioritize visual presentation and compostability certifications. The segment spans the widest range of performance requirements from grease resistance to structural aesthetics.
- Food Service:Distribution networks prioritize shelf-life extension and handling durability for catering and institutional channels.
- Wholesalers:Volume procurement emphasizes standardization and cost efficiency across broad product portfolios.
Bakeries holds the established position, while Retailers is gaining share fastest through in-store bakery expansion.
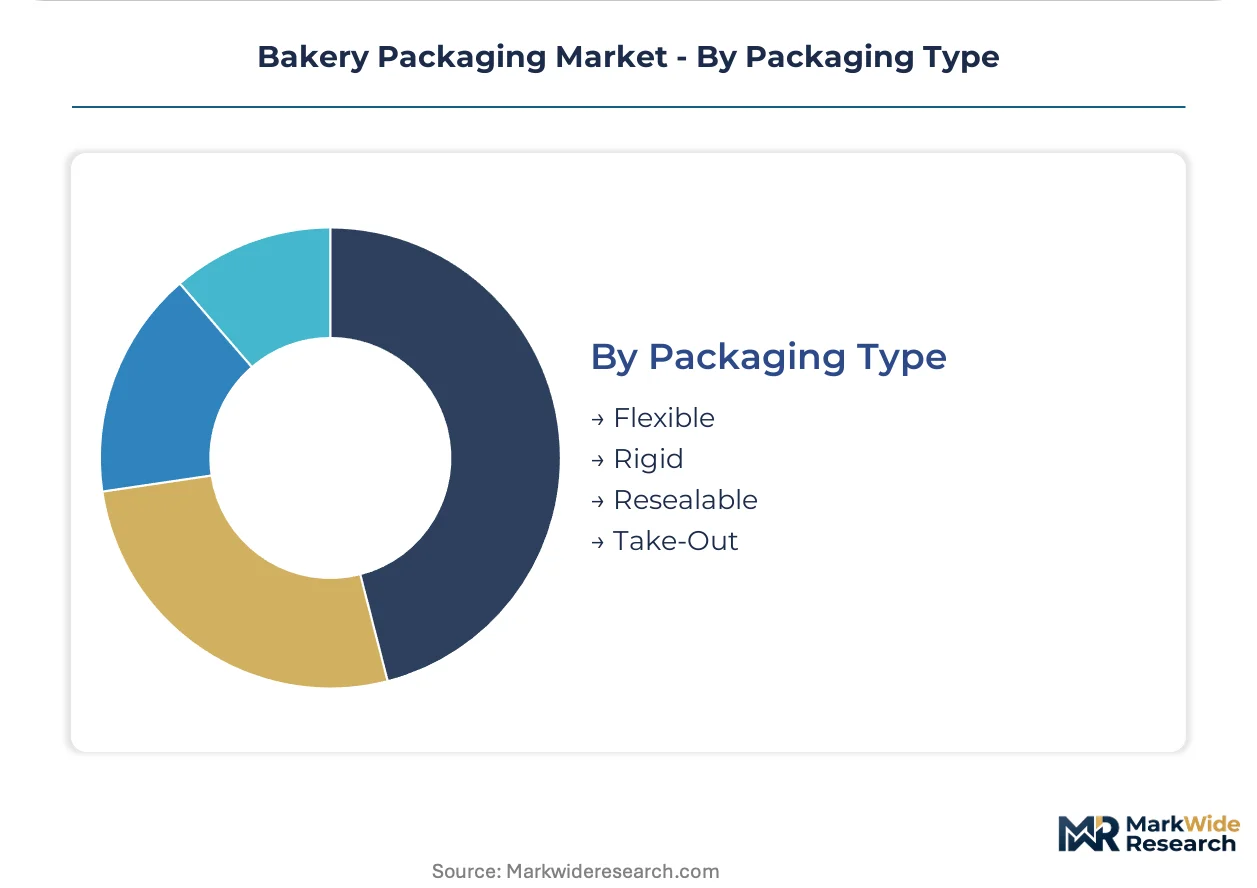
Packaging Type:
Application requirements separate flexible formats for preservation from rigid systems for presentation.
- Flexible:Films and wraps lead volume across bread and pastry applications where conformability and seal integrity matter. Water-based barrier coatings are supplanting polyethylene laminates in premium segments seeking compostability certifications. The format dominates automated production lines.
- Rigid:Clamshells and containers command margin pools in patisserie and cake segments where structural protection and visual access drive purchase decisions. The segment requires precise dimensional tolerance for automated filling equipment.
- Resealable:Zipper and adhesive systems extend consumption occasions for multi-serve bakery products.
- Take-Out:Single-serve formats balance portability with food safety for immediate consumption channels.
Flexible packaging maintains volume dominance, though Rigid formats show the steepest expansion trajectory in premium dessert applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA migration limits and the EU Packaging and Packaging Waste Regulation anchor demand concentration in Germany, where industrial bakeries and premium patisseries enforce the most sophisticated packaging specifications worldwide. Regulatory compression across multiple geographies is fragmenting procurement authority toward regional specifications.
Germany
Industrial bakeries operating high-speed automated lines specify mono-material polyethylene films to meet extended producer responsibility quotas under the national packaging ordinance. EFSA migration testing requirements extend product development cycles for water-based barrier coatings. The Baden-Württemberg and Bavaria corridors host integrated converting operations serving both multinational bread brands and artisan patisseries.
France
Artisan bakeries in Paris and Lyon drive windowed paperboard box specifications requiring structural integrity for layered desserts combined with biodegradability certifications. The EU Packaging and Packaging Waste Regulation accelerates transitions away from polystyrene foam for visual merchandising. The Île-de-France region concentrates premium patisserie packaging demand where presentation directly influences purchase decisions.
United States
EPA rules on per- and polyfluoroalkyl substances force coating reformulations across manufacturing bases before alternatives achieve commercial scale. FDA 21 CFR regulations limit additive migration into baked goods, adding compliance layers for imported films. The Midwest industrial corridor and California's fresh bakery networks represent divergent specification requirements between high-volume automation and compostable presentation formats.
Italy
Direct-store-delivery networks fragment procurement authority away from centralized national chains toward regional distributors specifying formats based on local shelf-life requirements. Municipal composting infrastructure availability varies between northern and southern regions, creating packaging specification fragmentation. The Emilia-Romagna bakery cooperative cluster retains stronger channel influence than northern European markets.
United Kingdom
Retail chains expanding in-store bakery counters demand localized packaging supply with shorter lead times than national bread brands. Post-Brexit regulatory divergence from EU REACH compliance adds testing burdens for imported films. The Greater London area and Midlands manufacturing belt concentrate demand for flexible formats serving grab-and-go bakery counters in urban retail footprints.
Bakery Packaging Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding extrusion and converting assets across multiple continents while the latter focus on coating chemistry or molded fiber niches. The market structure rewards scale in film production alongside agility in barrier formulation. Two strategic archetypes dominate: integrated paper-to-packaging conglomerates with captive fiber supply, and flexible packaging specialists with global heat-seal technology platforms. Competitive moves concentrate on coating reformulation partnerships and regional converting capacity expansion to serve fragmented direct-store-delivery networks.
Within the integrated conglomerate tier, Mondi Group and Smurfit Kappa exemplify operations combining kraft paper production with corrugated converting across European demand centers. Amcor Plc occupies a position representing global film extrusion scale serving multinational bread brands with mono-material structures. Among coating specialists, Huhtamaki sits within the molded fiber segment where grease-resistant specifications exceed standard offerings for artisan bakery applications.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| Sealed Air |
| Berry Global Inc. |
| Smurfit Kappa |
| WestRock Company |
| Huhtamaki |
| TC Transcontinental |
| Bemis Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Nordic kraft paper mills and German corrugated converters lock in fiber supply visibility while insulating integrated producers from spot pulp volatility. These arrangements concentrate pricing power among backward-integrated conglomerates that control both pulping assets and converting capacity across Baden-Württemberg and Bavaria.
Pricing Analysis
German industrial bakeries pay 15-20% premiums over Italian counterparts for mono-material polyethylene films certified under national extended producer responsibility schemes. Three-tier pricing structure across premium, standard, and economy levels separates compostable windowed boxes from conventional multilayer bread bags. Cost compression in standard-grade plastic films is intensifying because EPA-mandated PFAS coating reformulations force premature asset retirement. Artisan patisseries exhibit the lowest price sensitivity, prioritizing biodegradability certifications and visual presentation over unit cost.
Supply Chain Analysis
Nordic softwood pulp exports through Baltic Sea ports underwrite European kraft paper supply, with Swedish and Finnish mills feeding German and French converting operations. The bakery packaging supply chain draws from bleached kraft pulp, polyethylene resin, and water-based barrier coating chemistries as core inputs. Single-source vulnerability concentrates in fluorinated coating alternatives, where commercial-scale PFAS-free formulations remain limited to two specialized suppliers. Distribution runs through direct-store-delivery networks in Italy and Spain alongside centralized procurement hubs serving German industrial bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-store-delivery fragmentation is splintering procurement authority toward regional distributors, creating niche entry points for specialized coating formulators and molded fiber engineers that multinational suppliers cannot address economically.
For Market Incumbents: Fortify backward integration into Nordic pulp supply through long-term fiber offtakes or captive forestry assets, insulating margins from input cost volatility that compresses independent converters. Accelerate water-based barrier coating certification with EFSA to preempt regulatory obsolescence of polyethylene laminate assets. For New Entrants and Emerging Players: Lead with grease-resistant molded fiber tray formulations targeting French and Belgian artisan patisseries, where specifications exceed standard Huhtamaki offerings and buyers prioritize compostability over cost. Establish regional converting partnerships in Emilia-Romagna to serve fragmented Italian bakery cooperatives through localized supply. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among coating chemistry specialists with multi-year supply agreements to multinational bread brands, offering visibility through raw material cycles. Target mid-cap European converters with captive EFSA testing laboratories and established relationships with German packaging ordinance compliance officers. Watch for inflection when water-based barrier coatings achieve commercial scale parity with polyethylene laminates in high-speed automated lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Supply | Captive fiber sourcing insulates Mondi and Smurfit Kappa from kraft paper input cost volatility. |
| Water-Based Barrier Coating Certification | EFSA migration limit approval accelerates substitution of polyethylene laminates in premium bread bags. |
| Regional Converting Capacity Expansion | Localized production in Italy and Spain addresses direct-store-delivery lead time requirements. |
| Molded Fiber Tray Formulation Advancement | Grease-resistant specifications for artisan segments create white space beyond standard offerings. |
| REACH Compliance Service Development | Testing burdens for imported films generate outsourced revenue from small and mid-sized converters. |
Methodological Framework
Desk research of trade association filings, customs records, and ECHA substance restriction databases preceded structured interviews with packaging procurement managers at industrial bakeries, coating R&D directors, and corrugated plant engineers across Germany, France, and Italy. Primary fieldwork with EFSA compliance officers and extended producer responsibility scheme administrators validated secondary estimates. Bottom-up demand modeling triangulated against top-down material flow analysis.
Variance decomposition across product type, material grade, end-user channel, and packaging format dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by regional demand concentration. Forecast inputs incorporated EU Packaging and Packaging Waste Regulation implementation timelines and Nordic softwood supply elasticity assumptions.
Forecasts assume regulatory continuity in EU REACH and German packaging ordinance regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as PFAS coating reformulation timelines and municipal composting infrastructure rollouts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Latin America Travel Retail Market
Others
Flexible PVC Films and Sheets Market
Others
Industrial Computers Market
Others
US Luxury Travel Market
Others
Agitation System Market
Others
Massive Machine Type Communication in Healthcare Market
Others
Egg and Egg Products Market
Others
Smart TV Platforms Market
Others
Global Platform Trolley Market
Others
Synthetic Leather Market
Others
CAR T Cell Therapy Market
Others
Fluorite Market
Others
Balsa Wood Market
Others
Global Animal Feed Protein Ingredients Market
Others
Powder Coating Equipment Market
Others
5G Edge Computing Market