
 Cryogenic Storage Tanks Market | 2026-2036
Cryogenic Storage Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Storage Tanks Market Analytics
Aftermarket service revenue is tilting toward field repair and vacuum-rejuvenation contracts as original equipment margins compress. Chart Industries leverages its integrated lifecycle services to capture recurring revenue from installed base maintenance. Linde plc anchors its position through captive demand from its own industrial gas production network. INOX India Limited specializes in cost-optimized stainless steel fabrication for emerging market buyers.
Cryogenic storage tanks are vacuum-insulated pressure vessels designed to contain liquefied gases below minus 150 degrees Celsius, typically constructed with double-walled stainless steel shells separated by perlite insulation and maintained at pressures from 1 to 37 bar depending on the stored commodity. These vessels serve critical functions in industrial gas distribution, LNG supply chains, and biomedical sample preservation where thermal integrity determines operational safety and economic viability. Stainless steel dominates material selection for LNG and medical oxygen applications where corrosion resistance and weldability outweigh cost premiums, while carbon steel retains share in bulk nitrogen and argon service where thermal cycling demands are less severe. Horizontal tanks lead transportable applications due to lower center of gravity and road-loading compatibility, though vertical configurations prevail in fixed-site installations where footprint optimization matters most.
ASME Section VIII governs pressure vessel design and fabrication in the United States, while the EU Pressure Equipment Directive and ISO 20421 establish conformity benchmarks for European and international trade respectively, with each framework elevating inspection density and traceability requirements that filter marginal fabricators from qualified supplier lists. The EPA and DOT jointly regulate LNG facility siting and hazardous materials transport, creating overlapping compliance obligations that favor vendors with established regulatory affairs capabilities. Stakeholders must monitor evolving hydrogen liquefaction standards as the energy transition creates new cryogenic demand patterns beyond traditional industrial gas markets.
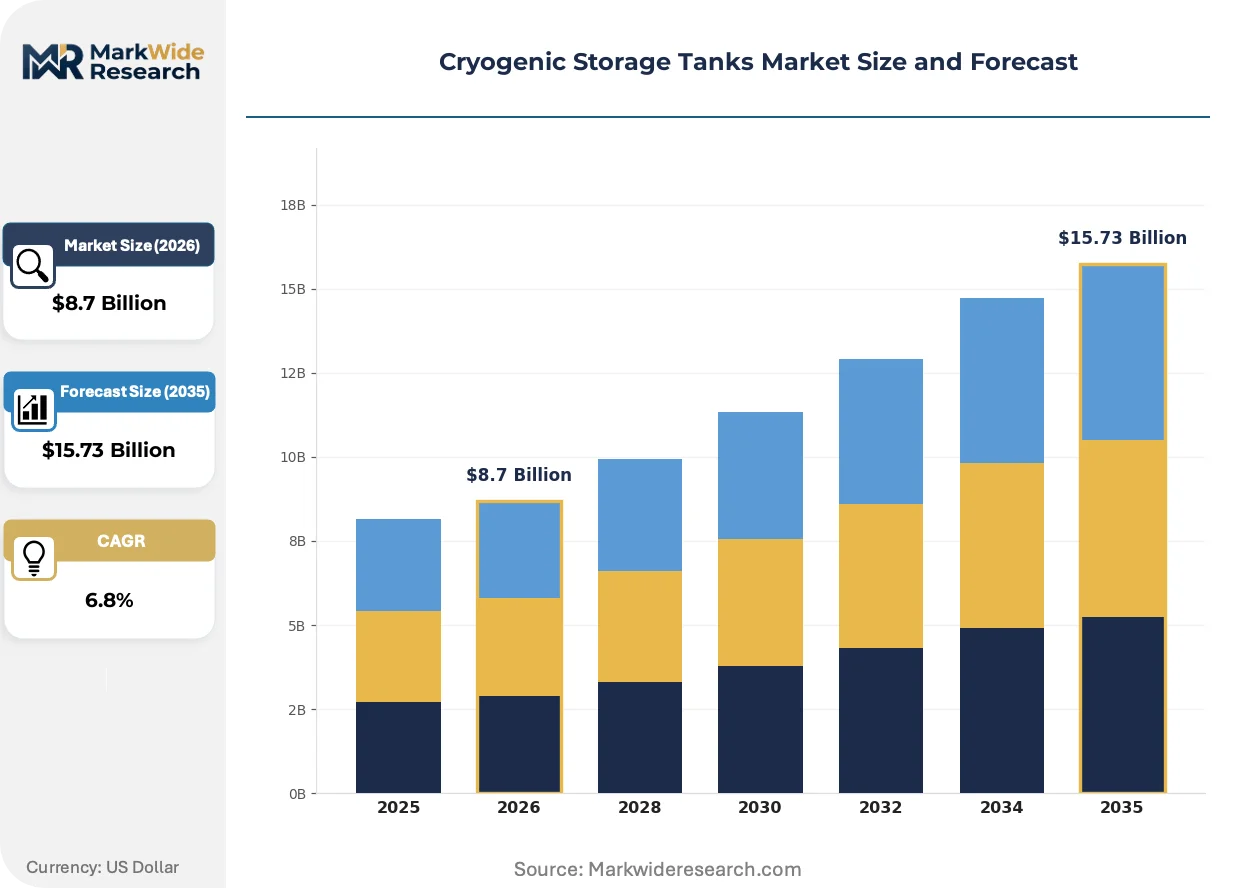
Market Dynamics
LNG export terminal expansions on the United States Gulf Coast are compressing fabrication lead times and concentrating qualified vessel supply among ASME-certified shops with vacuum-insulation expertise.
Growth Catalysts
- IRA hydrogen hub funding:United States Department of Energy allocations for regional clean hydrogen production are stimulating demand for liquid hydrogen storage infrastructure at minus 253 degrees Celsius.
- Liquefaction train scaling:Cheniere Energy and Venture Global are commissioning larger liquefaction blocks that require correspondingly larger cryogenic storage vessels above 200,000 cubic meters.
- Biomedical cold chain:Cell and gene therapy manufacturing facilities in Switzerland and Singapore are installing specialized liquid nitrogen tanks for cryopreservation of clinical samples.
Market Restraints
- Nickel price volatility:Austenitic stainless steel 304/316 feedstock costs fluctuate with Indonesian and Philippine nickel ore export policies, compressing fabrication margins.
- ASME Section VIII certification density:Third-party inspection requirements for vacuum-insulated pressure vessels extend fabrication timelines and filter marginal suppliers from qualified bidder lists.
- On-site vaporization substitution:Pipeline natural gas delivery to industrial clusters in Germany and the Netherlands reduces demand for bulk liquid nitrogen and argon storage.
Strategic Opportunities
- India industrial gas buildout:Reliance Industries and Indian Oil are expanding captive air separation units requiring cost-optimized cryogenic storage fabricated to BIS standards.
- CCUS liquefaction integration:Carbon capture projects in Norway and the Netherlands require liquid carbon dioxide storage at minus 56 degrees Celsius and 5.2 bar pressure.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases are accelerating replacement of mechanical refrigeration with cryogenic systems in food freezing applications.
Industry Challenges
- Vacuum maintenance technician scarcity:Field service engineers capable of detecting and repairing micro-leaks in perlite-insulated annular spaces are concentrated among original equipment manufacturers.
- Legacy vessel integration:Brownfield LNG terminals must reconcile 1970s-era tank designs with modern safety instrumented system requirements under updated NFPA 59A editions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Storage Tanks Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Tanks, Horizontal Tanks, Cylinder Tanks, Double-Walled Tanks Material: Carbon Steel, Stainless Steel, Aluminum, Composite Materials End User: Healthcare, Energy Sector, Food & Beverage, Research Institutions Delivery Mode: On-site Storage, Insulated Transport, Modular Systems, Bulk Delivery |
| Companies Covered | Chart Industries, Linde plc, INOX India Limited, Air Products and Chemicals, Inc., Cryofab, Inc., FIBA Technologies, Inc., Wessington Cryogenics, SURETANK, Air Liquide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Storage Tanks Market Evolving Landscape
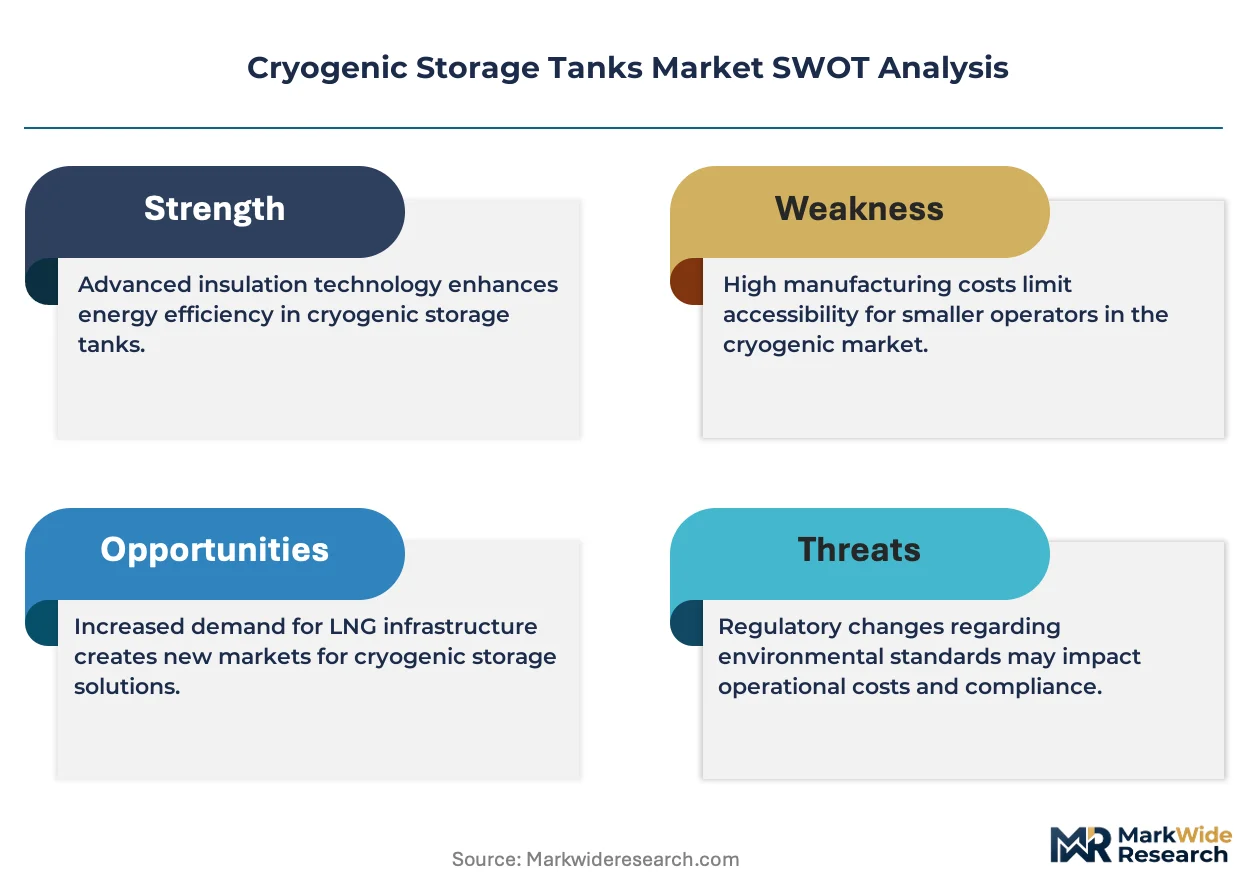
Active insulation monitoring systems and predictive maintenance platforms are transforming vessel lifecycle economics from capital expenditure optimization toward total cost of ownership reduction.
Multi-layer insulation composites incorporating aerogel blankets are collapsing thermal conductivity coefficients to below 0.003 W per meter-Kelvin in liquid hydrogen service. Space launch operators in Florida and French Guiana are specifying these systems for propellant storage tanks with multi-week hold times. The technology is collapsing the trade-off between insulation thickness and boil-off rates that previously constrained tank sizing.
The EU Pressure Equipment Directive 2014/68/EU is tightening conformity assessment procedures for cryogenic vessels above 0.5 bar design pressure. Notified bodies in Germany and France are demanding enhanced material traceability for nickel-alloy welds in low-temperature service. Small fabrication shops in Eastern Europe are exiting the market rather than absorbing certification cost increases.
Lifecycle service contracting is displacing discrete equipment purchases in industrial gas distribution. Linde plc and Air Liquide are bundling tank provision with telemetry monitoring and predictive refill scheduling. This shift concentrates procurement authority at regional headquarters rather than individual plant engineering departments, favoring vendors with integrated service networks.
Cryogenic Storage Tanks Market Segmentation
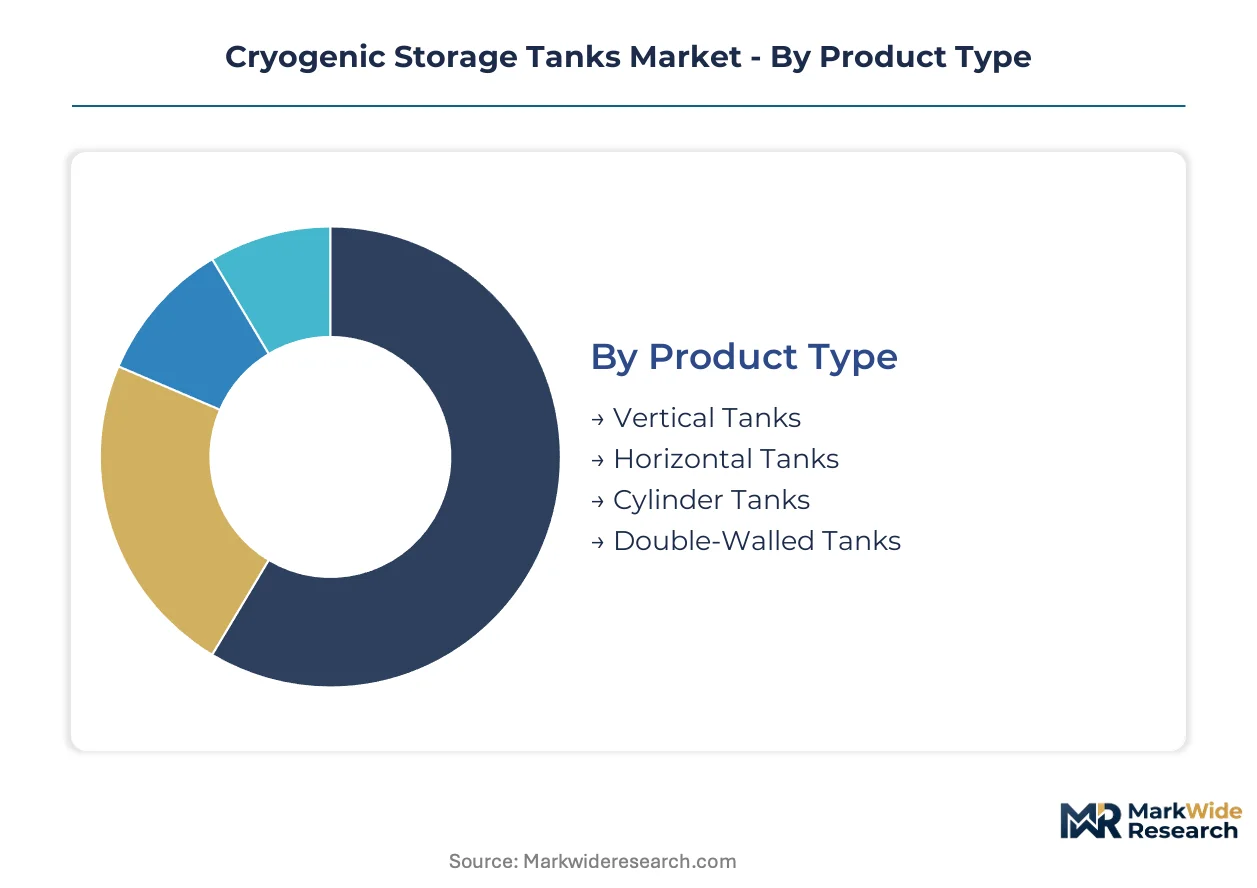
Cryogenic storage tank segmentation reflects divergent engineering requirements across stationary versus mobile applications, with material selection and configuration geometry directly determining thermal performance and regulatory compliance pathways.
Product Type:
Mature vertical designs dominate fixed-site installations while emerging horizontal and modular formats are reshaping transport and distributed storage economics.
- Vertical Tanks:Upright cylindrical vessels with dished heads maximize volumetric efficiency in footprint-constrained industrial facilities. Petrochemical complexes along the United States Gulf Coast specify vertical configurations above 50,000 gallons for LNG peak shaving and argon buffer storage, driven by NFPA 59A siting requirements that favor compact installations.
- Horizontal Tanks:Low-center-of-gravity designs with saddle supports optimize road transport stability and seismic resilience. These configurations concentrate demand in California and Texas for mobile nitrogen delivery to semiconductor fabrication plants, where DOT 406 specification compliance enables highway movement without transloading.
- Cylinder Tanks:Compact dewar vessels serve laboratory and medical point-of-use applications with capacities below 500 liters.
- Double-Walled Tanks:Vacuum-insulated pressure vessels with perlite-filled annular spaces achieve boil-off rates below 0.1% daily for liquid hydrogen service.
Vertical tanks handle the majority of throughput; horizontal tanks are expanding most quickly on share as distributed energy infrastructure proliferates.
Material:
Cost tiers separate commodity carbon steel from premium nickel-alloy grades, with selection hinging on corrosion tolerance and thermal cycling severity.
- Stainless Steel:Austenitic grades 304 and 316 deliver weldability and cryogenic toughness down to minus 196 degrees Celsius. Singapore biomedical facilities specify 316L for liquid nitrogen storage in cell therapy manufacturing, where FDA cGMP validation requires surface finish control and full material traceability.
- Carbon Steel:Lower-alloy grades with post-weld heat treatment retain structural integrity in bulk nitrogen and argon service where temperatures stay above minus 150 degrees Celsius. Indian industrial gas distributors favor carbon steel for 1,000-ton air separation unit storage, exploiting BIS IS 2825 fabrication standards that permit simplified inspection protocols versus ASME alternatives.
- Aluminum:5083-O temper plate offers weight reduction for aerospace and portable medical oxygen applications.
- Composite Materials:Glass-reinforced polymer liners with vacuum barriers emerge in satellite propellant tanks.
Stainless steel commands the premium tier on margin; carbon steel retains volume leadership in emerging market procurement.
End User:
Customer type determines specification intensity, from life-science traceability to energy-sector scale economics.
- Energy Sector:LNG export terminals and hydrogen liquefaction plants specify ASME Section VIII vessels with active insulation monitoring. Cheniere Energy's Corpus Christi expansion sources tanks above 200,000 cubic meters, with FERC environmental review driving extended lead times that compress supplier availability.
- Healthcare:Hospital systems and biorepositories demand liquid nitrogen storage with temperature uniformity within 2 degrees Celsius. Swissmedic-regulated cell banks in Basel specify 21 CFR Part 11-compliant telemetry for cryopreserved therapeutic samples, with validation documentation adding 15-20% to equipment cost.
- Food & Beverage:Cryogenic freezing tunnels and modified atmosphere packaging drive bulk carbon dioxide storage demand.
- Research Institutions:National laboratories and university facilities prioritize flexibility for multiple cryogen types.
The energy sector absorbs the largest unit volumes; healthcare represents the steepest expansion trajectory on per-tank value.
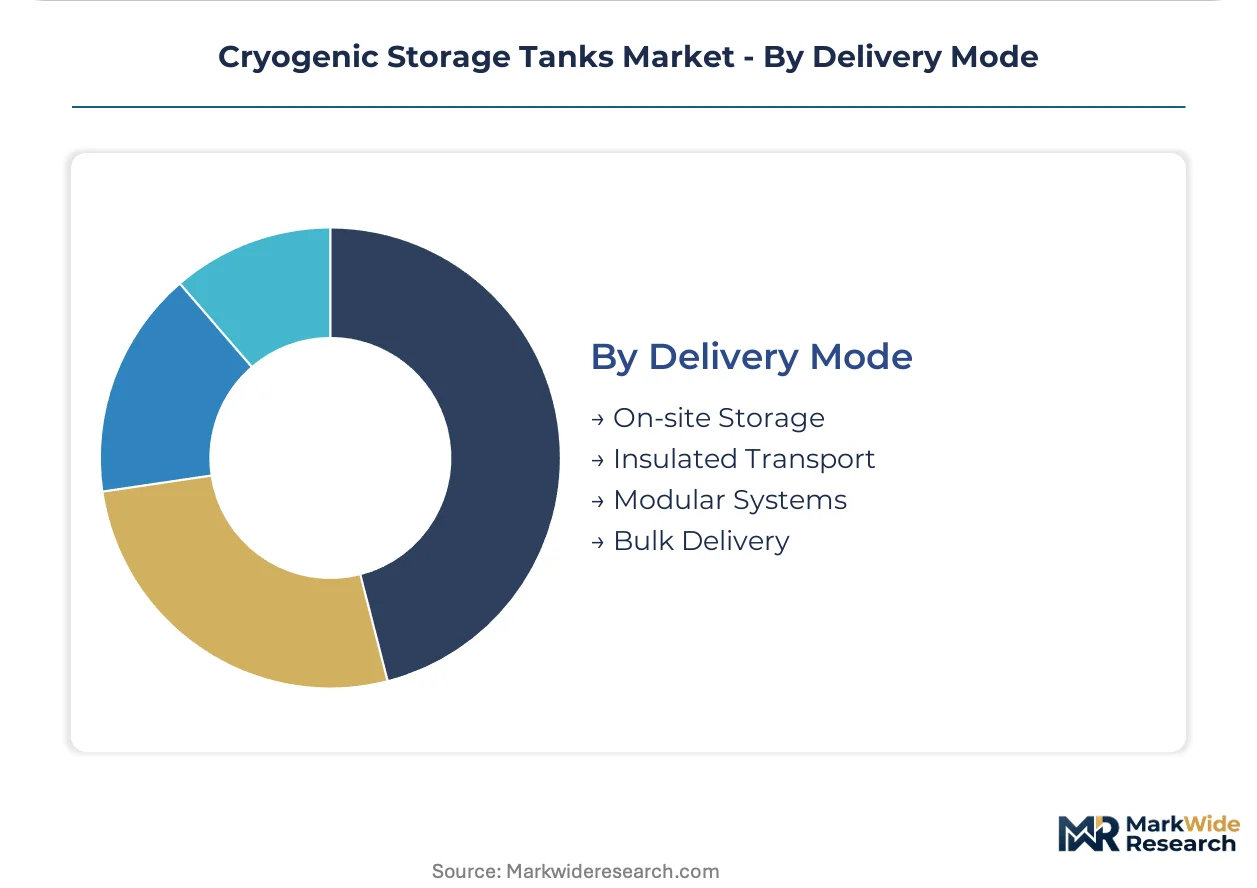
Delivery Mode:
Supply chain configuration spans capital-intensive on-site installation through service-based bulk delivery contracts.
- On-site Storage:Permanent tank installation with vaporizer skids enables continuous gas supply to steel mills and chemical plants. ThyssenKrupp's Duisburg facility operates 3,000-ton liquid oxygen tanks with pipeline distribution, eliminating cylinder handling labor and securing supply continuity for basic oxygen furnace operations.
- Bulk Delivery:Microbulk and liquid cylinder exchange programs substitute capital expenditure with per-gallon service fees. Linde plc's MAGNUM series tanks serve mid-sized welding shops across Ohio and Pennsylvania, with telemetry-enabled automatic refill reducing inventory management burden on small customers.
- Insulated Transport:ISO tank containers and cryogenic trailers bridge production and consumption geography.
- Modular Systems:Skid-mounted tank-vaporizer packages accelerate deployment for temporary or remote applications.
On-site storage anchors industrial gas infrastructure; bulk delivery is gaining share fastest among small and mid-sized consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Gulf Coast consumes cryogenic storage tanks predominantly for LNG export infrastructure, while European demand clusters around hydrogen liquefaction and biomedical cold chain applications, and emerging Asian markets prioritize cost-optimized industrial gas distribution.
United States
Cheniere Energy and Venture Global drive vessel procurement above 200,000 cubic meters for liquefaction train expansions. FERC environmental review extends lead times, compressing qualified supplier availability. Corpus Christi and Cameron Parish anchor fabrication demand where ASME-certified shops concentrate vacuum-insulation expertise.
Germany
ThyssenKrupp's Duisburg steel complex operates 3,000-ton liquid oxygen tanks with pipeline distribution to basic oxygen furnaces. The EU Pressure Equipment Directive 2014/68/EU tightens conformity assessment for vessels above 0.5 bar design pressure. Industrial clusters along the Rhine-Ruhr corridor integrate cryogenic storage with carbon capture and hydrogen hub development.
India
Reliance Industries and Indian Oil expand captive air separation units requiring BIS IS 2825-compliant fabrication. The PLI scheme for specialty steel reduces nickel-alloy import dependency for austenitic grades. Gujarat and Maharashtra host emerging fabrication capacity serving domestic industrial gas buildout.
Singapore
Cell and gene therapy manufacturing facilities install liquid nitrogen tanks for cryopreservation with FDA cGMP validation requirements. Swissmedic-equivalent standards from the Health Sciences Authority govern clinical sample storage traceability. Biomedical clusters in Tuas and one-north specify 316L stainless steel with full material documentation.
Norway
Carbon capture projects require liquid carbon dioxide storage at minus 56 degrees Celsius and 5.2 bar pressure for offshore injection. The government's Longship project and Northern Lights consortium drive vessel specification for CCUS integration. Equinor-operated facilities on the western coast anchor demand for specialized pressure-rated cryogenic systems.
Cryogenic Storage Tanks Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated structure where vacuum-insulation expertise filters marginal fabricators while integrated industrial gas operators leverage captive demand. The vendor base separates into ASME-certified specialists, diversified industrial gas conglomerates, and emerging-market cost optimizers. Consolidation pressure favors vendors with established regulatory affairs capabilities and lifecycle service networks. Dominant competitive moves include backward integration into nickel-alloy supply chains and geographic expansion through joint ventures in India and Southeast Asia.
Within the integrated industrial gas tier, Linde plc and Air Liquide occupy positions defined by captive demand from proprietary production networks and bundled service contracting. Chart Industries exemplifies the specialized equipment archetype, leveraging lifecycle services to capture recurring revenue from installed base maintenance. INOX India Limited represents cost-optimized fabrication for emerging market procurement, operating within BIS standards rather than ASME frameworks. These three anchors illustrate the strategic segmentation between premium-tier certification, integrated service bundling, and value-engineered regional supply.
| Leading Market Players |
|---|
| Chart Industries |
| Linde plc |
| INOX India Limited |
| Air Products and Chemicals, Inc. |
| Cryofab, Inc. |
| FIBA Technologies, Inc. |
| Wessington Cryogenics |
| SURETANK |
| Air Liquide |
| Others |
Value Network & Pricing Analysis
Nickel price volatility between Indonesian ore export policy shifts and Philippine mining restrictions determines both pricing tier spreads and supply chain shape. Fabricators absorbing austenitic stainless steel feedstock swings compress margins on standard-grade vessels while ASME-certified specialists command premium pricing for vacuum-insulation expertise.
Pricing Analysis
Long-term offtake contracts dominate LNG export terminal procurement, locking in vessel supply years ahead of liquefaction train commissioning. Price differentiation separates ASME Section VIII-certified fabricators from BIS-standard competitors, with Gulf Coast project developers paying substantial premiums for vacuum-rejuvenation service bundling. Cost compression in carbon steel nitrogen storage intensifies as Indian distributors exploit simplified inspection protocols. Small welding shops and semiconductor fabs exhibit highest price sensitivity; hydrogen liquefaction developers show least sensitivity due to IRA hub funding availability.
Supply Chain Analysis
Tariff exposure between Indonesian nickel ore and Chinese stainless steel processing dominates raw material risk for austenitic grade fabricators. Vacuum-insulated vessel production draws from concentrated ASME-certified shop capacity in the United States Gulf Coast, German notified body jurisdictions, and emerging BIS-compliant fabrication in Gujarat. Supply chain vulnerability rests on single-source dependency for perlite insulation from Greek and Turkish mining operations. Distribution runs through integrated industrial gas operators bundling tank provision with telemetry-enabled refill scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
On-site vaporization systems and pipeline natural gas delivery to industrial clusters present a substitution threat that incumbent cryogenic storage vendors must navigate through service bundling and lifecycle contracting.
For Market Incumbents: Insulate installed base revenue through vacuum-rejuvenation service contracts and predictive maintenance platforms that lock out third-party field repair competitors. Deepen backward integration into nickel-alloy supply chains to buffer Indonesian ore policy volatility. Prioritize certification investment for hydrogen liquefaction standards before IRA hub construction peaks. For New Entrants and Emerging Players: Pursue white-space opportunities in BIS-standard carbon steel fabrication for Indian captive air separation unit expansion, where Reliance Industries and Indian Oil procurement favors cost-optimized regional supply. Target biomedical cold chain applications in Singapore cell therapy manufacturing, where FDA cGMP validation requirements filter established competitors. Lead with telemetry-enabled bulk delivery service models rather than discrete equipment sales. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors ASME-certified specialists with vacuum-insulation expertise over diversified industrial gas conglomerates. Long-term viability hinges on hydrogen liquefaction infrastructure buildout and carbon capture storage integration. Acquisition candidates should demonstrate established regulatory affairs capabilities and lifecycle service network density. Watch FERC environmental review timelines for Gulf Coast LNG expansions as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Alloy Supply | Captive sourcing from Indonesian ore processing buffers feedstock volatility for austenitic fabrication. |
| Lifecycle Service Contracting | Telemetry-enabled predictive maintenance transforms Chart Industries revenue from capital sales to recurring streams. |
| ASME Section VIII Certification Investment | Third-party inspection density filters marginal fabricators from qualified bidder lists for LNG terminal procurement. |
| Hydrogen Liquefaction Standards Development | Minus 253 degrees Celsius vessel expertise positions vendors for IRA hub infrastructure allocations. |
| Joint Venture in Indian Fabrication | BIS IS 2825-compliant capacity captures Reliance Industries and Indian Oil captive air separation unit demand. |
Research Methodology
Cross-validation between primary interviews with vacuum-insulation fabrication engineers, LNG terminal procurement directors, and biomedical cold chain facility managers anchors the qualitative findings. Secondary validation draws from FERC environmental review filings, ASME Boiler and Pressure Vessel Code documentation, EU Pressure Equipment Directive conformity assessments, and SEC 10-K disclosures from integrated industrial gas operators. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Calibration against historical vessel delivery timelines and liquefaction train commissioning schedules refines projection accuracy. The analytical framework segments by product type, material grade, end-use sector, and delivery mode across the modeling period. CAGRs derive from regression analysis of capital expenditure patterns and service contract renewal rates. Hydrogen hub funding allocation trajectories and nickel ore export policy scenarios constitute industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in energy transition capital allocation or Indonesian mining policy would shift the trajectory. Forecasts reflect documented assumptions regarding IRA hydrogen hub construction pacing and EU F-Gas Regulation enforcement stringency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Virtual Keyboard Market
Others
Europe Aircraft Lighting Systems Market
Others
Global Surface Analysis Market
Others
High Frequency Vibrator Market
Others
Rope Market
Others
IoT Testing Market
Others
Human Enhancement Technology Market
Others
Europe Air Separation Unit Market
Others
Residential Electrical Conduit Market
Others
Hybrid System Market
Others
Vacuum Evaporators Market
Others
Radiation Detection Monitoring and Safety Market
Others
Latin America Fire Sprinklers Market
Others
Legal Services Market
Others
Internet Protocol Television (IPTV) Market
Others
Italy 3D Printing Construction Market