
 AI In Government And Public Services Market | 2026-2036
AI In Government And Public Services Market Size, Share, and Industry Trends Forecast 2026-2036
AI In Government And Public Services Market Insights
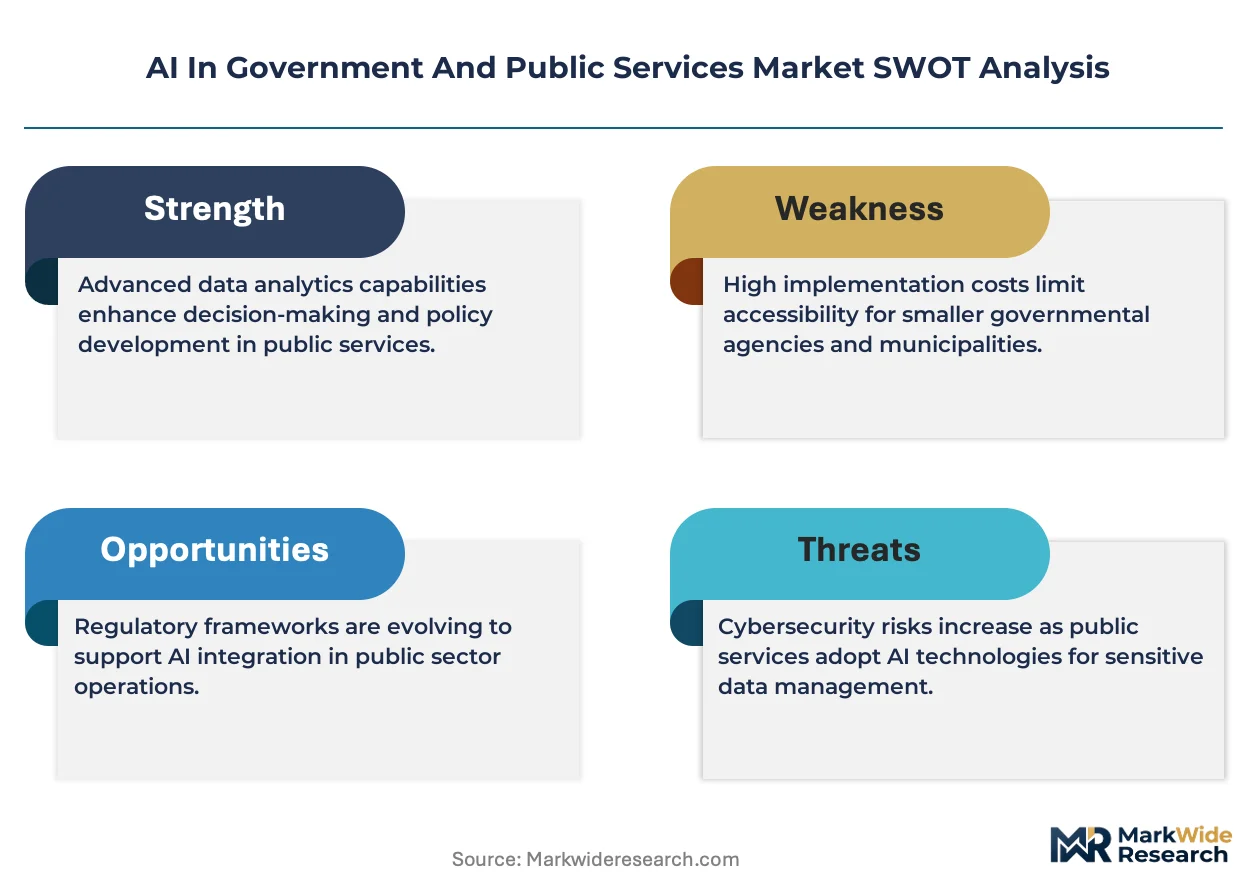
The gap between premium sovereign-cloud deployments and commodity SaaS offerings is hardening across procurement channels. Microsoft anchors its position through Azure Government clouds with FedRAMP authorization, while Palantir Technologies differentiates via specialized data-integration platforms for intelligence and defense workflows. IBM competes through Watson's legacy entrenchment in federal health and social welfare systems.
AI in government and public services encompasses machine-learning systems, natural-language processing engines, and computer-vision platforms designed to automate decision-support, citizen interaction, and resource allocation across administrative functions. These systems typically operate on structured and unstructured data pipelines with explainability requirements for audit trails and legal accountability. Natural language processing leads in mature deployment for citizen chatbots and document classification, while computer vision represents the fastest-growing segment driven by public safety monitoring and urban infrastructure inspection. Machine learning underpins predictive analytics in tax administration and emergency response, where margin pools concentrate around specialized training data and domain-specific model refinement.
The EU AI Act, alongside FDA guidelines for AI-enabled public health tools and India's BIS emerging standards for automated governance systems, is reshaping vendor certification requirements and procurement eligibility. Compliance with risk-tiered algorithmic accountability is becoming a gatekeeper for market access in regulated jurisdictions. Stakeholders must monitor how procurement authorities weigh explainability mandates against performance benchmarks when selecting long-term platform partners.
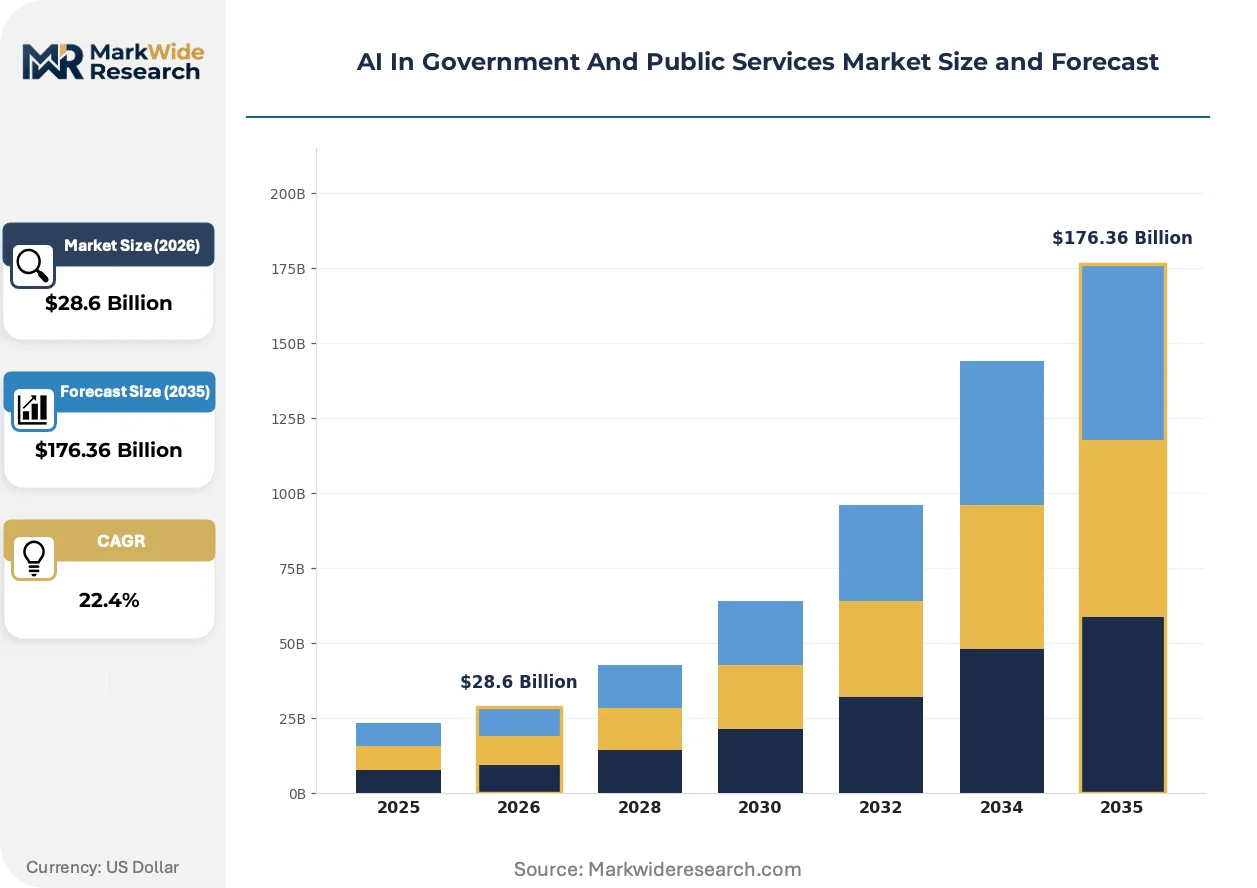
Market Dynamics
Federal procurement officers now mandate explainability-by-design as a non-negotiable checkpoint, compressing vendor qualification timelines and elevating specialized system integrators over generalist cloud providers.
Growth Catalysts
- EU AI Act risk-tier mandates:High-stakes public-sector algorithms now require conformity assessments before deployment, creating certified vendor ecosystems that lock out uncertified competitors.
- India Smart Cities Mission:Municipal corporations deploy computer vision for traffic signal optimization and waste collection routing, generating recurring platform revenue streams.
- FedRAMP authorization pathways:US federal agencies fast-track cloud procurement through standardized security baselines, reducing vendor onboarding from 18 months to under 6 months.
Market Restraints
- Training data scarcity:Sensitive government records resist standard anonymization, forcing vendors to build synthetic data pipelines that inflate model development costs.
- GPU supply concentration:Advanced chip procurement depends on Taiwan Semiconductor Manufacturing and NVIDIA allocation queues, creating 9-12 month deployment delays.
- Algorithmic accountability litigation:Citizens challenge automated benefit determinations under administrative procedure laws, exposing agencies to judicial review risks.
Strategic Opportunities
- Sub-Saharan Africa digital ID systems:National identity authorities seek biometric-AI platforms for voter registration and social benefit distribution with limited incumbent competition.
- Climate resilience modeling:Convergence of satellite imagery and hydrological simulation creates demand for predictive flood and wildfire management systems.
- Interoperability mandates:India's BIS standards for automated governance systems require API-first architectures, rewarding modular platform vendors.
Industry Challenges
- Cross-functional talent scarcity:Teams blending domain expertise in administrative law with machine-learning engineering command 40% salary premiums over pure technical roles.
- Legacy system integration:COBOL-based benefit administration databases resist standard REST API connections, requiring custom middleware that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI In Government And Public Services Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $176.36 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Predictive Analytics, Natural Language Processing, Computer Vision, Robotic Process Automation, Machine Learning Application Area: Law Enforcement, Tax Administration, Public Safety Monitoring, Emergency Response, Urban Planning End User Sector: Municipal Authorities, Federal Agencies, Social Welfare Departments, Defense Units, Regulatory Bodies Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing, SaaS |
| Companies Covered | Microsoft, IBM, Google, Amazon Web Services, Oracle, Accenture, Deloitte, Palantir Technologies, C3.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI In Government And Public Services Market Trends and Innovations
Foundation models fine-tuned on administrative code and case law are compressing the gap between experimental pilots and production deployment across sovereign agencies.
Retrieval-augmented generation architectures are consolidating around constitutional and statutory document corpora, enabling citation-backed responses that satisfy judicial scrutiny requirements. State supreme courts in California and New York pilot these systems for docket summarization. The structural consequence is a shift from general-purpose large language models toward domain-specific implementations with embedded provenance tracking.
Europe's AI Act mandatory risk classification framework is forcing vendors to reengineer training pipelines for high-risk use cases in criminal justice and migration control. Conformity assessment bodies in Germany and France now audit algorithmic impact assessments before market entry. Health screening applications face the strictest scrutiny, with biometrics vendors redesigning facial recognition systems to exclude emotion inference capabilities entirely.
Public procurement officers increasingly require source code escrow and model card documentation as standard contract terms, displacing black-box SaaS subscriptions. Municipal IT departments in Singapore and Dubai lead this transition, writing technical specifications that privilege inspectable algorithms. This behavioral shift rewards vendors with established audit trail infrastructure while marginalizing opaque API-only providers.
AI In Government And Public Services Market Segmentation
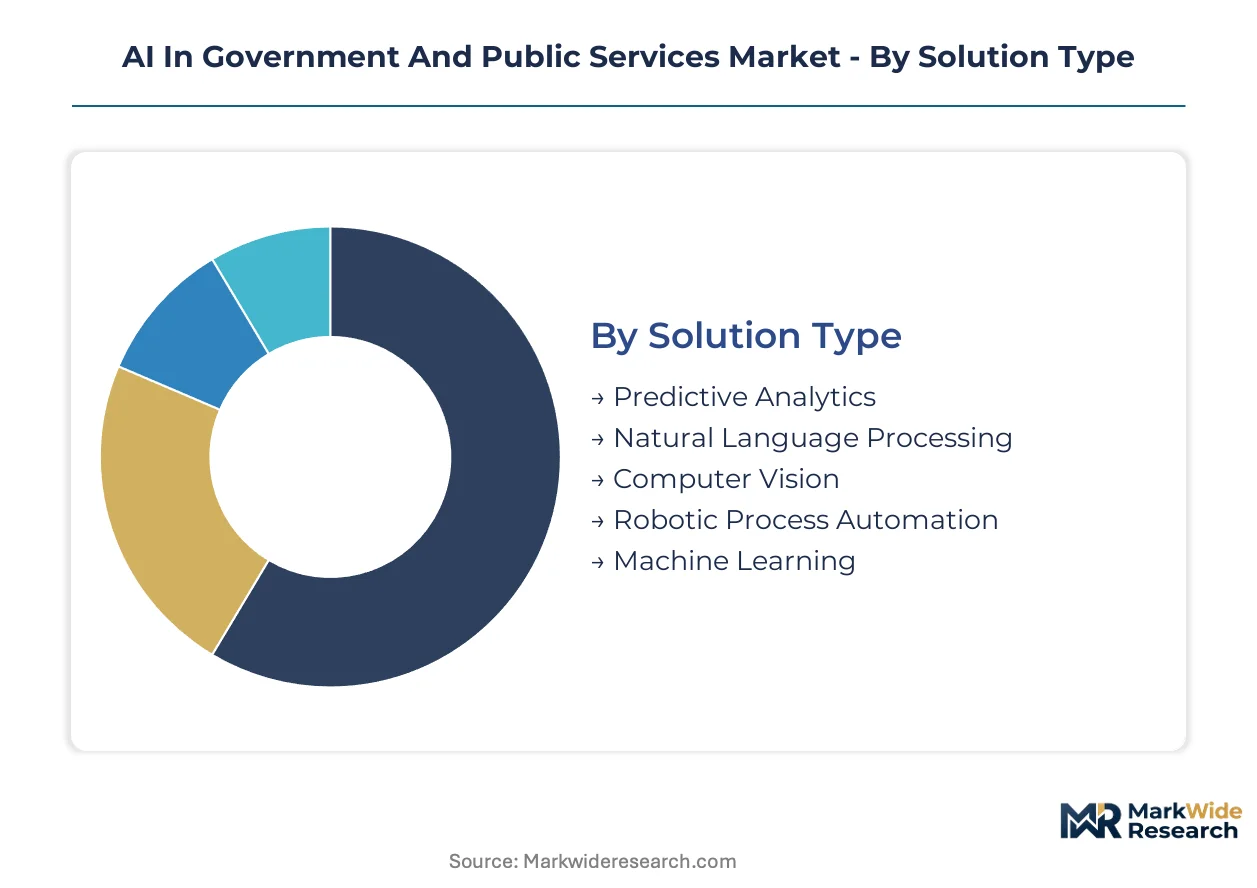
Procurement patterns across public agencies diverge sharply by technical maturity and data sovereignty requirements. Understanding these fault lines reveals where vendor specialization commands premium pricing versus where commoditization pressures dominate.
Solution Type:
Predictive Analytics and Computer Vision deployments absorb the heaviest upfront capital, demanding specialized GPU clusters and synthetic data pipelines for sensitive government records.
- Predictive Analytics:Statistical models trained on historical administrative data forecast tax evasion patterns and benefit fraud. Federal revenue agencies in the United States and municipal corporations in India concentrate procurement here, driven by EU AI Act mandates for algorithmic accountability in high-risk benefit determinations.
- Computer Vision:Image recognition systems process satellite imagery for urban planning and real-time traffic signal optimization. India's Smart Cities Mission generates concentrated demand in Bangalore and Pune, where GPU supply bottlenecks from NVIDIA allocation queues extend deployment timelines.
- Natural Language Processing:Document classification engines and citizen-facing chatbots operate on structured administrative corpora with embedded provenance tracking.
- Robotic Process Automation:Rule-based workflow automation handles repetitive data entry across legacy COBOL benefit administration systems.
- Machine Learning:General-purpose algorithmic frameworks underpin custom model development for agency-specific use cases with FedRAMP-authorized cloud substrates.
Most installed capacity flows through Predictive Analytics. Expansion is steepest in Computer Vision.
Application Area:
Tax Administration and Public Safety Monitoring attract the largest procurement budgets, reflecting revenue protection imperatives and post-incident liability exposure.
- Tax Administration:Machine-learning models flag anomalous return filings and cross-border transfer pricing irregularities. India's Central Board of Direct Taxes and Germany's Federal Central Tax Office deploy these systems, constrained by training data scarcity requiring expensive synthetic pipeline construction.
- Public Safety Monitoring:Computer vision networks analyze CCTV feeds for crowd anomaly detection and perimeter intrusion. Singapore's Safe City program and Dubai's municipal AI initiatives drive demand, with EU AI Act prohibitions on emotion inference forcing architectural redesigns.
- Law Enforcement:Predictive policing algorithms and forensic DNA analysis tools face strictest judicial scrutiny under administrative procedure laws.
- Emergency Response:Flood and wildfire prediction systems converge satellite imagery with hydrological simulation for climate resilience planning.
- Urban Planning:Traffic signal optimization and waste collection routing algorithms reduce municipal operational expenditure.
Tax Administration captures the greatest share of sovereign AI spending. Law Enforcement faces the steepest compliance headwinds from algorithmic accountability litigation.
End User Sector:
Federal Agencies and Defense Units require air-gapped infrastructure with source code escrow, elevating total cost of ownership above municipal deployments.
- Federal Agencies:National-level departments procure through FedRAMP-authorized cloud pathways with standardized security baselines reducing vendor onboarding cycles.
- Defense Units:Intelligence and military workflows demand specialized data-integration platforms with classified network segmentation.
- Municipal Authorities:City corporations in India and the UAE lead API-first architecture adoption under emerging BIS and local interoperability mandates.
- Social Welfare Departments:Benefit determination systems face concentrated judicial challenge risk under administrative procedure frameworks.
- Regulatory Bodies:Conformity assessment organizations audit algorithmic impact assessments before market entry authorization.
Federal Agencies deploy the most mature explainability-by-design infrastructure. Municipal Authorities are climbing the fastest as Smart Cities Mission funding accelerates.
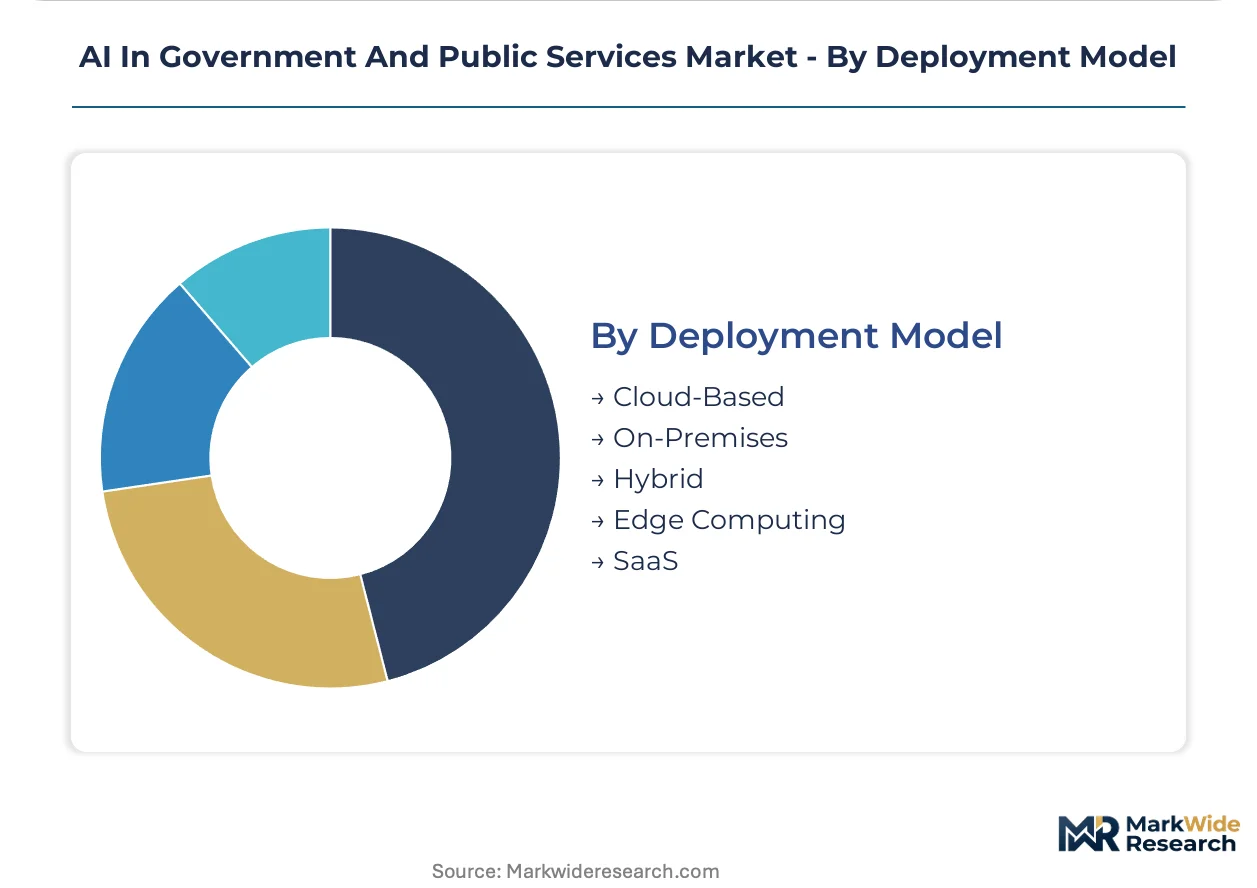
Deployment Model:
On-Premises and Edge Computing configurations impose the steepest capital requirements, demanding dedicated hardware procurement outside shared cloud economies.
- On-Premises:Sovereign data centers host sensitive criminal justice and migration control algorithms subject to EU AI Act high-risk conformity assessments.
- Edge Computing:Localized processing units support real-time public safety monitoring with minimal latency for traffic signal optimization.
- Cloud-Based:FedRAMP-authorized government clouds from hyperscale providers anchor federal procurement with standardized security baselines.
- Hybrid:Split architectures process classified data on-premises while leveraging cloud elasticity for non-sensitive workloads.
- SaaS:Subscription-based citizen chatbots and document classification face displacement by inspectable algorithm mandates favoring source code escrow.
Cloud-Based deployments hold the largest installed base. Edge Computing is gaining share fastest as latency requirements harden for real-time safety systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AI engineering talent clusters in Washington DC, Brussels, and Bangalore anchor government technology procurement decisions across three continents.
United States
FedRAMP-authorized cloud procurement and defense intelligence contracts drive vendor selection. The FDA and federal acquisition regulations mandate explainability-by-design for high-stakes benefit determinations. Washington DC and Northern Virginia host the densest concentration of specialized system integrators serving federal agencies.
India
Municipal corporations under the Smart Cities Mission deploy computer vision for traffic optimization and waste routing. BIS emerging standards for automated governance systems reshape API-first architecture requirements. Bangalore and Pune generate concentrated demand where GPU supply constraints extend deployment timelines.
Germany
Federal tax authorities and conformity assessment bodies anchor algorithmic accountability enforcement. The EU AI Act mandates risk-tiered conformity assessments before high-risk public-sector deployment. Berlin and Munich host specialized vendors reengineering training pipelines for criminal justice and migration control applications.
United Arab Emirates
Dubai's municipal AI initiatives and federal digital transformation programs concentrate procurement budgets. MOHAP guidelines and local interoperability mandates favor inspectable algorithms with source code escrow. Dubai and Abu Dhabi lead regional adoption of real-time public safety monitoring systems.
Singapore
Safe City program investments and smart nation infrastructure drive computer vision network deployment. National IT standards require embedded provenance tracking for judicial scrutiny compliance. The city-state anchors Southeast Asian demand for citation-backed document classification systems.
AI In Government And Public Services Market Competitive Landscape
Top-tier vendors anchor sovereign-cloud deployments with specialized security authorizations, while mid-tier specialists compete on domain-specific model refinement and synthetic data pipelines. The market structure stratifies between hyperscale cloud providers with government certification pathways and boutique integrators serving classified intelligence workflows. Three archetypes dominate: FedRAMP-authorized platform operators, defense-specialized data integration firms, and legacy health system incumbents with entrenched federal relationships. Competitive moves concentrate on strategic partnerships with conformity assessment bodies and portfolio diversification into climate resilience modeling.
Within the hyperscale tier, Microsoft and Amazon Web Services occupy positions defined by standardized security baselines and accelerated federal onboarding pathways. Palantir Technologies exemplifies the defense-specialized archetype, anchoring intelligence and classified network segmentation workflows. IBM sits within the legacy entrenchment category, representing long-standing federal health and social welfare system relationships that resist displacement by newer platform entrants.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Amazon Web Services |
| Oracle |
| Accenture |
| Deloitte |
| Palantir Technologies |
| C3.ai |
| Others |
Pricing and Supply Chain Analysis
Foundation model fine-tuning on administrative code and case law compresses development timelines while concentrating GPU procurement among FedRAMP-authorized cloud operators. This technical shift simultaneously elevates synthetic data pipeline costs and locks pricing power within certified vendor ecosystems.
Pricing Analysis
Subscription-based SaaS tiers dominate for citizen-facing chatbots and document classification, while project-based contracting governs predictive analytics deployments in tax administration. Price differentiation centers on FedRAMP authorization tier and explainability-by-design certification depth. Pricing pressure stems from synthetic data pipeline construction costs for sensitive government records. Municipal authorities exhibit highest price sensitivity; defense units prioritize security authorization over cost.
Supply Chain Analysis
Certification gating through FedRAMP and EU AI Act conformity assessments funnels vendor qualification toward specialized system integrators in the United States, Germany, and India. GPU clusters draw from Taiwan Semiconductor Manufacturing and NVIDIA allocation queues. Single-source vulnerability in advanced chip procurement creates deployment delays. Distribution runs through federal procurement officers and municipal IT departments with standardized security baselines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FedRAMP authorization timelines compressing from 18 months to under 6 months signals late-cycle quality dynamics. Procurement officers now mandate source code escrow and model card documentation, elevating premium-tier vendors with established audit infrastructure.
For Market Incumbents: Hedge against commodity SaaS displacement by deepening synthetic data pipeline capabilities and securing conformity assessment body partnerships in Germany and France. Palantir Technologies exemplifies defensive positioning through specialized data-integration platforms for intelligence workflows. FedRAMP-authorized cloud operators should anchor source code escrow infrastructure to maintain procurement eligibility.
For New Entrants and Emerging Players: Enter via sub-Saharan Africa digital ID systems and climate resilience modeling applications where incumbent presence remains limited. India's Smart Cities Mission computer vision procurement offers the most penetrable municipal entry point. Target API-first architecture compliance under BIS emerging standards to bypass legacy system integration barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among boutique integrators serving classified intelligence workflows with air-gapped infrastructure capabilities. Long-term viability over the projection horizon favors vendors with embedded provenance tracking and constitutional document corpus specialization. Monitor EU AI Act high-risk conformity assessment completion rates as the primary inflection signal for market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Reduces vendor onboarding cycles from 18 months to under 6 months for federal agencies. |
| Synthetic Data Pipeline Investment | Addresses training data scarcity for sensitive government records in tax administration. |
| Conformity Assessment Partnership | Locks market access through EU AI Act high-risk certification in Germany and France. |
| API-First Architecture Compliance | Aligns with India's BIS standards for automated governance systems procurement. |
| Source Code Escrow Infrastructure | Satisfies municipal IT requirements in Singapore and Dubai for inspectable algorithms. |
Research Methodology
Multiple input streams — primary interviews with federal procurement officers, municipal IT directors, and conformity assessment auditors; secondary validation through FedRAMP authorization databases, EU AI Act regulatory filings, and BIS standard documentation — were reconciled through bottom-up and top-down triangulation. Conversations with defense-specialized data integration firms and legacy health system incumbents anchored qualitative assessment of vendor positioning. Secondary sources included SEC filings from hyperscale cloud providers, Smart Cities Mission procurement records, and algorithmic impact assessment publications from German and French conformity bodies.
Historical deployment trajectories were cross-referenced against panel input from procurement officers across the analysis window. Segmentation dimensions modeled encompass solution type, application area, end user sector, and deployment model, with regional regulatory cluster as the industry-specific overlay. CAGRs were derived through iterative reconciliation of installed base growth and replacement cycle dynamics. Forecast inputs included GPU allocation queue lengths and EU AI Act compliance timeline assumptions.
Inputs from federal procurement databases and municipal tender records were available through the study window; gaps in classified defense contract disclosure introduce uncertainty bands around intelligence workflow estimates. Forecasts reflect documented assumptions regarding FedRAMP authorization pathway stability and BIS standard finalization timelines. A model refresh is warranted upon material change in NVIDIA GPU allocation priority or EU AI Act enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Baking Paper Market
Others
Underwater Communication System Market
Others
Digital Supply Chain Market
Others
Smart Badge Market
Others
Cat Food Market
Others
Senior Cat Food Market
Others
Workbench Tanks Market
Others
Mini Personal Computer Market
Others
Global Hardware Acceleration Market
Others
North America Forklift Truck Market
Others
Land Surveying Equipment Market
Others
Traditional PC Market
Others
Process Spectroscopy Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Europe Indoor LBS Market
Others
Medical Simulation Market