
 Idaas Market | 2026-2036
Idaas Market Size, Share, and Industry Trends Forecast 2026-2036
Idaas Market Outlook
The EU AI Act is shifting procurement criteria for automated identity systems across European enterprises. Microsoft leverages its Azure Active Directory ecosystem to anchor cloud-based deployments across multinational clients. Google competes through embedded security tools within its workspace and cloud platforms. Okta specializes in API-first architectures that extend integration flexibility for developer-centric organizations.
Identity-as-a-Service encompasses cloud-delivered identity and access management functions, including single sign-on, multi-factor authentication, and privileged access governance, typically orchestrated through federated protocols such as SAML and OIDC. Its primary commercial purpose is to offload credential lifecycle management from on-premises infrastructure while enforcing zero-trust perimeter policies. Cloud-based deployment models dominate new bookings as enterprises retire legacy Active Directory estates. Managed services within the service-type dimension capture expanding margin pools as customers seek operational offload of identity governance. Large enterprises remain the core customer-type revenue base, though government agencies represent the fastest-growing procurement segment amid classified-cloud mandates.
The US Federal Risk and Authorization Management Program shapes cloud identity procurement standards for agencies, while the EU GDPR and NIS2 Directive enforce breach-notification and access-logging requirements that elevate IAM budget priority. ISO/IEC 27001 certification operates as a de facto market-access filter for vendors serving regulated industries. Stakeholders must monitor the divergence between US zero-trust executive mandates and EU data-sovereignty localization rules when architecting cross-border identity fabrics.
Market Dynamics
Cloud-native identity platforms are displacing on-premises Active Directory estates as enterprises execute zero-trust mandates. The shift compresses deployment timelines from months to weeks while elevating API-first architectures over legacy federation protocols.
Growth Catalysts
- Zero-trust executive mandates:US federal agencies accelerate cloud identity procurement under FedRAMP authorization requirements. Government classified-cloud mandates expand budget allocations for managed identity services.
- EU AI Act authentication requirements:Automated decision systems in European financial services must deploy enhanced identity verification. Procurement criteria now prioritize continuous authentication over static credential checks.
- Legacy infrastructure retirement:Financial services firms dismantle aging on-premises identity stacks. Cloud-based single sign-on and privileged access governance capture displaced maintenance budgets.
Market Restraints
- Data-sovereignty localization rules:EU GDPR and NIS2 Directive impose breach-notification and access-logging requirements that fragment cross-border identity fabric architectures.
- Certification timeline compression:ISO/IEC 27001 certification operates as de facto market-access filter for vendors serving regulated industries, extending sales cycles by six to twelve months.
- Skills concentration in cloud-native protocols:SAML and OIDC expertise concentrates in coastal technology hubs, constraining deployment velocity for mid-market enterprises in secondary markets.
Strategic Opportunities
- API-first developer-centric architectures:Okta-style embedded identity services penetrate SaaS vendors and independent software developers previously served by monolithic platforms.
- Managed identity governance services:Operational offload demand from compliance-heavy sectors creates margin expansion in ongoing administration and attestation workflows.
- Cross-border identity fabric standardization:Divergence between US zero-trust mandates and EU data-sovereignty rules creates consulting and integration service whitespace for neutral architecture vendors.
Industry Challenges
- Federated protocol interoperability:SAML-to-OIDC migration projects stall on legacy application compatibility, forcing parallel authentication stacks that increase operational complexity.
- Privileged access governance skill scarcity:Zero-standing privilege and just-in-time access models require security architects with cloud-native and mainframe hybrid experience, a combination rarely found in single candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Idaas Market |
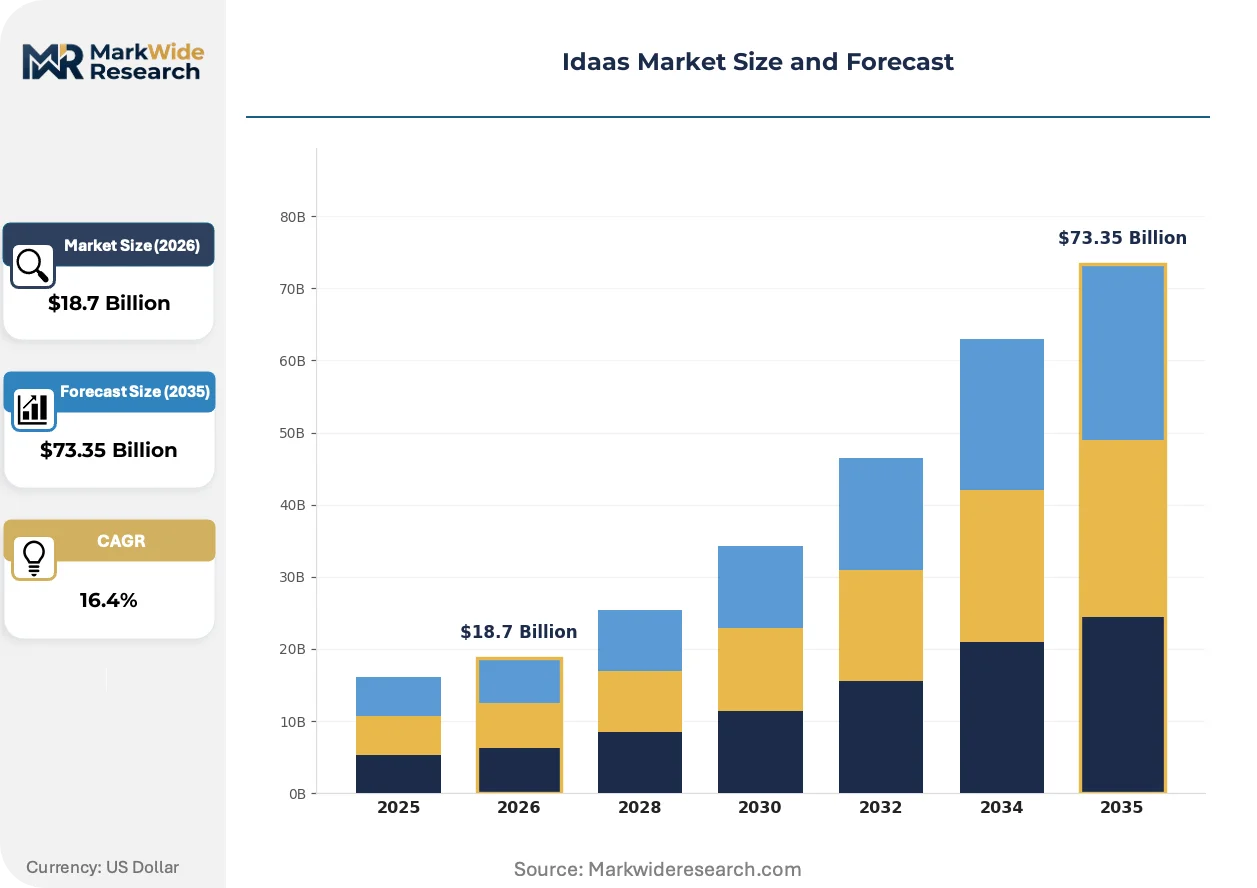
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Consulting, Integration Services, Support Services Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing Customer Type: SMEs, Large Enterprises, Government Agencies, Nonprofits Technology: API Management, Data Analytics, Machine Learning, Security Tools |
| Companies Covered | Okta, Microsoft, Ping Identity, IBM, Thales, Oracle, Salesforce, CyberArk, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Idaas Market Strategic Shifts
Passwordless authentication methods are compressing credential lifecycle management into biometric and cryptographic verification flows. The technology stack is consolidating around FIDO2 standards while vendor differentiation shifts toward developer experience and embedded deployment models.
Passkey implementations are consolidating authentication workflows across consumer and enterprise segments. Financial services firms in North America deploy FIDO2-based biometric verification for high-risk transaction authorization. The technology is consolidating previously separate multi-factor and single sign-on budget lines into unified platform procurement.
EU AI Act compliance requirements are mandating continuous authentication for automated credit and insurance decision systems. European enterprises must reconstruct identity verification pipelines to include real-time behavioral biometrics and step-up challenges. German and French financial institutions represent the most affected segment, with procurement teams rewriting RFP criteria to exclude static password-based systems.
Developer-centric procurement patterns are displacing centralized IT-led identity platform selection. Engineering teams in technology and fintech verticals now specify API-first identity services directly, bypassing traditional security architecture review boards. This pattern is most visible in US coastal technology clusters where product velocity priorities override legacy governance frameworks.
Idaas Market Segmentation
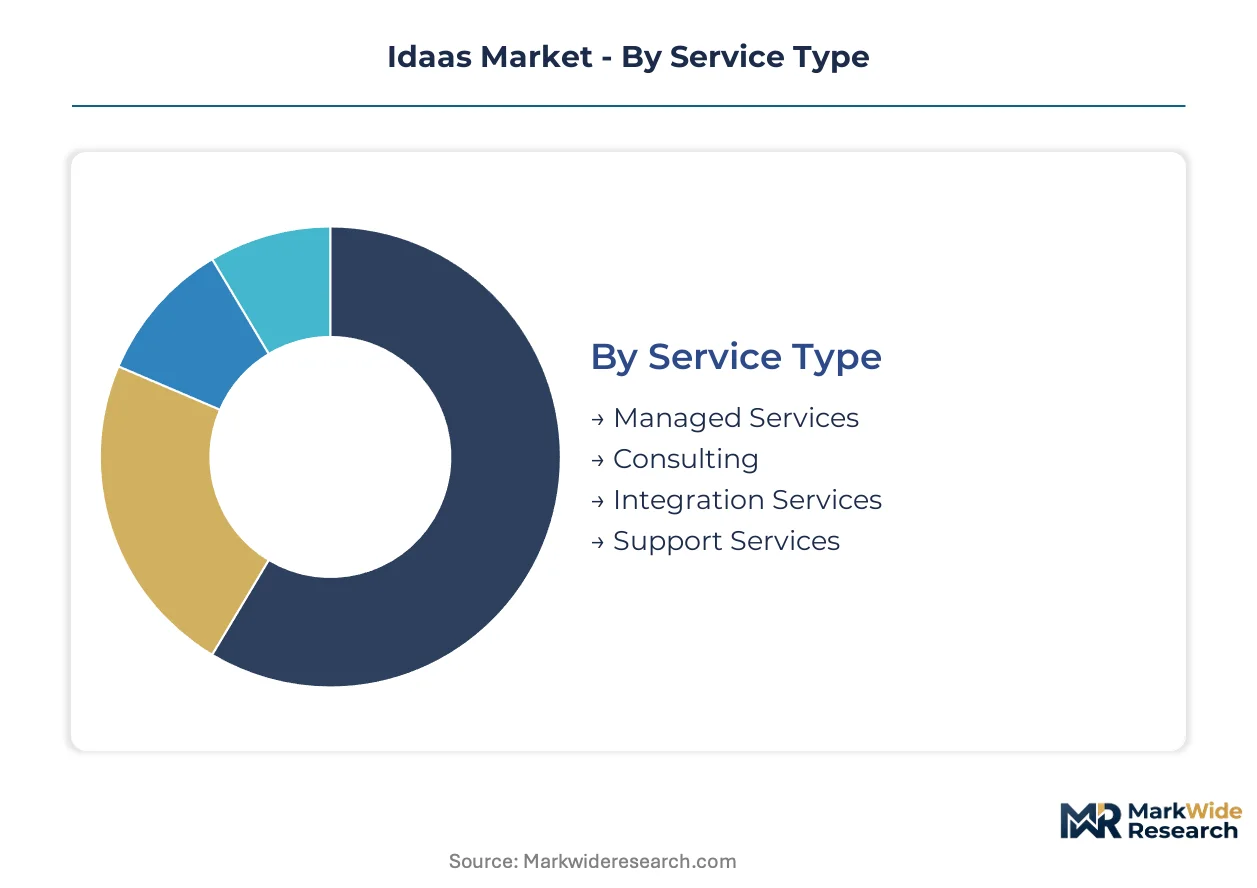
Identity-as-a-Service procurement patterns diverge sharply across service delivery modes and infrastructure choices. Understanding these fault lines reveals where margin pools concentrate and which deployment architectures capture displaced legacy spending.
Service Type:
Volume concentrates in operational offload arrangements, while premium margin accumulates in advisory and integration layers.
- Managed Services:Continuous identity governance administration, including access certification workflows and privileged account monitoring. Demand concentrates in US federal agencies executing FedRAMP-authorized cloud mandates, with classified-cloud requirements expanding budget allocations for ongoing operational support.
- Consulting:Architecture design and zero-trust transformation advisory. European financial services firms under EU AI Act compliance deadlines drive premium pricing for automated decision system authentication redesign.
- Integration Services:SAML-to-OIDC migration and legacy Active Directory consolidation projects.
- Support Services:Break-fix and tiered helpdesk coverage for production identity platforms.
Today's leader: Managed Services. Tomorrow's challenger: Consulting.
Deployment Model:
Cloud-native architectures displace on-premises estates fastest where zero-trust executive mandates apply with regulatory force.
- Cloud-Based:Fully SaaS-delivered identity orchestration through federated protocols. US financial services firms dismantle aging on-premises stacks, redirecting maintenance budgets to API-first platforms that compress deployment timelines from months to weeks.
- Hybrid:Split architecture preserving on-premises directory services with cloud authentication front-ends. German automotive manufacturers favor this model to satisfy works council data-localization requirements while enabling workforce mobility.
- On-Premises:Legacy Active Directory estates and self-hosted identity providers.
- Edge Computing:Distributed authentication nodes for low-latency verification in manufacturing and logistics environments.
Cloud-Based deployment captures the steepest expansion trajectory as enterprises retire legacy infrastructure.
Customer Type:
Large enterprises anchor revenue, while government procurement accelerates fastest under classified-cloud mandates.
- Large Enterprises:Multinational organizations with complex federated identity requirements. Technology and financial services verticals in the United States drive API-first procurement patterns that bypass traditional security architecture review boards.
- Government Agencies:Federal, state, and municipal identity modernization programs. US federal zero-trust mandates and EU NIS2 Directive compliance timelines expand budget priority for continuous authentication systems.
- SMEs:Mid-market organizations adopting packaged cloud identity solutions.
- Nonprofits:Grant-funded identity infrastructure for educational and humanitarian institutions.
Large Enterprises dominate current bookings. Government Agencies are climbing the fastest.
Technology:
Security tooling captures the largest budget allocation, while machine learning investment concentrates in compliance-driven authentication redesign.
- Security Tools:Multi-factor authentication, privileged access governance, and passwordless verification stacks. FIDO2 standardization consolidates previously separate MFA and SSO budget lines into unified platform procurement across North American financial services.
- Machine Learning:Behavioral biometrics and risk-based step-up authentication. EU AI Act requirements for automated credit and insurance decision systems mandate real-time identity verification pipelines in German and French financial institutions.
- API Management:Developer-centric identity service integration and token lifecycle orchestration.
- Data Analytics:Access pattern analysis and compliance attestation reporting.
Security Tools anchor technology spending. Machine Learning represents the fastest-growing investment category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Identity-as-a-Service originated in United States technology corridors during the mid-2000s cloud computing expansion. Early adoption concentrated in Silicon Valley and Seattle before diffusing through financial services hubs. Regulatory divergence now shapes distinct procurement patterns across major economies.
United States
Federal zero-trust mandates and FedRAMP authorization requirements accelerate cloud identity procurement across government agencies. The SEC enforces breach disclosure timelines that elevate IAM budget priority in publicly traded enterprises. Technology clusters in Seattle and San Francisco drive API-first adoption patterns that bypass traditional security governance boards.
Germany
Automotive manufacturers and financial institutions dismantle aging on-premises identity stacks under EU NIS2 Directive compliance pressure. The BSI (Federal Office for Information Security) mandates stringent access-logging standards for critical infrastructure operators. Industrial concentration in Bavaria and Baden-Württemberg favors hybrid deployment models satisfying works council data-localization requirements.
United Kingdom
Financial services firms in the City of London reconstruct identity verification pipelines for automated credit decision systems. The FCA (Financial Conduct Authority) aligns with EU AI Act authentication requirements despite post-Brexit regulatory autonomy. Fintech clusters in London and Manchester pioneer developer-centric procurement patterns displacing centralized IT selection.
France
Major banks and insurers deploy continuous authentication for automated insurance underwriting systems under EU AI Act deadlines. The CNIL enforces GDPR-compliant breach-notification procedures that fragment cross-border identity fabric architectures. Paris-based financial institutions represent the most affected segment, rewriting RFP criteria to exclude static password-based verification.
Japan
Manufacturing conglomerates modernize legacy directory services as METI promotes zero-trust adoption in critical supply chains. The Personal Information Protection Commission tightens consent requirements for biometric authentication deployment. Technology corridors in Tokyo and Osaka concentrate SAML and OIDC expertise, constraining deployment velocity for mid-market enterprises in secondary regions.
Idaas Market Competitive Environment
Premium-margin players sit above commodity-margin players across the deployment complexity spectrum, with specialized API-first architectures commanding valuation multiples above standardized federation stacks. The vendor base organizes into three tiers: hyperscale cloud platforms with embedded identity services, pure-play identity specialists with developer-centric positioning, and legacy infrastructure vendors transitioning subscription revenue models. Consolidation pressure intensifies as customers demand unified platforms spanning workforce and consumer identity use cases. Dominant competitive moves include strategic partnerships embedding identity services into SaaS workflows and geographic expansion through regional data residency compliance.
Within the pure-play specialist tier, Okta and Ping Identity exemplify API-first architectures that penetrate SaaS vendors and independent software developers. Microsoft anchors the hyperscale tier through Azure Active Directory ecosystem leverage across multinational clients. CyberArk occupies a distinct position in privileged access governance, serving compliance-heavy sectors with operational offload demand. These three companies represent the strategic archetypes—developer-centric, platform-embedded, and security-specialized—that structure competitive positioning across procurement segments.
| Leading Market Players |
|---|
| Okta |
| Microsoft |
| Ping Identity |
| IBM |
| Thales |
| Oracle |
| Salesforce |
| CyberArk |
| Others |
Value Chain & Pricing Dynamics
FedRAMP authorization requirements gate qualified supply for US federal agencies and anchor premium-tier pricing access for vendors serving classified-cloud mandates. ISO/IEC 27001 certification operates as a de facto market-access filter, extending sales cycles and concentrating margin pools in compliant providers.
Pricing Analysis
Subscription-based SaaS tiers dominate the pricing architecture, with three-tier pricing structure across premium, standard, and economy levels separating FedRAMP-authorized deployments from commercial offerings. Price differentiation rests on certification grade and integration complexity, with API-first platforms commanding developer-centric premiums. Pricing pressure stems from hyperscale cloud platforms bundling identity services at marginal cost. Mid-market enterprises exhibit highest price sensitivity, while government agencies prioritize compliance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for cryptographic modules and cloud infrastructure mandate multi-supplier qualification across United States, Ireland, and Germany data residency zones. Supply concentration draws from hyperscale cloud providers, FIDO2 hardware authenticator manufacturers, and behavioral biometrics algorithm vendors. Single-source vulnerability in SAML-to-OIDC migration expertise constrains deployment velocity. Distribution runs through direct enterprise sales, systems integrator channels, and embedded SaaS marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Identity-as-a-Service market represents a late-cycle quality story as procurement criteria shift from basic federation to continuous authentication and zero-trust compliance. Premium specifications now center on FedRAMP authorization, EU AI Act alignment, and developer-experience differentiation.
For Market Incumbents: Anchor defensive positioning through backward integration into behavioral biometrics and privileged access governance capabilities. Consolidate API-first architectures to counter hyperscale platform bundling. Prioritize ISO/IEC 27001 certification maintenance as competitive moat against emerging cloud-native entrants. For New Entrants and Emerging Players: Passwordless authentication modules offer technology-first wedge into mid-market financial services segments underserved by legacy federation stacks. Target German and French institutions under EU AI Act compliance deadlines with continuous authentication solutions. Deploy through developer marketplace channels to bypass centralized IT procurement gates. For Investors and Strategic Acquirers: Roll-up economics work for specialized API-first identity vendors because customer concentration in SaaS workflows creates sticky recurring revenue pools with low churn. Favor targets with FedRAMP In Process or Authorized status. Watch for hyperscaler bundling intensity as inflection indicator for pure-play margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Pursuit | Unlocks classified-cloud procurement budgets across US federal agencies under zero-trust mandates. |
| EU AI Act Compliance Certification | Enables automated decision system deployments in German and French financial institutions. |
| API-First Platform Integration | Penetrates developer-centric procurement patterns displacing traditional security review boards. |
| Behavioral Biometrics Acquisition | Consolidates continuous authentication capabilities for step-up verification workflows. |
| Geographic Data Residency Expansion | Satisfies GDPR and NIS2 localization requirements fragmenting cross-border identity fabrics. |
Study Parameters
Bottom-up enterprise adoption modeling reconciled against top-down vendor booking tracking forms the analytical core of this study. Primary interviews with CISOs, identity architects, federal procurement officers, and systems integrator partners cross-validated against secondary sources including FedRAMP authorization databases, SEC SaaS revenue disclosures, EU regulatory filings, and hyperscaler identity service announcements. Triangulation between demand-side budget allocation surveys and supply-side pipeline data ensures segmentation integrity.
Input-output matrices map deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster to identity service consumption patterns across the projection horizon. CAGRs derive from logistic adoption curves fitted to zero-trust mandate implementation timelines and legacy Active Directory retirement schedules. Forecast inputs include FedRAMP authorization velocity, EU AI Act enforcement intensity, and FIDO2 standardization adoption rates.
The model holds under steady regulatory enforcement and cloud migration continuity; deviation in hyperscaler bundling aggression or data-sovereignty rule fragmentation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Versatile Video Coding Market
Others
Global Multi-Access Edge Computing Market
Others
Europe Postal Services Market
Others
South Korea Smart Home Market
Others
Military Sensors Software Market
Others
Digital Mortgage Software Market
Others
Global Animal Feed Protein Ingredients Market
Others
Europe Flow Battery Market
Others
Saudi Arabia Cat Food Market
Others
Dried Fruit Extracts Market
Others
North America Medical Simulation Market
Others
Industrial PC Market
Others
Liquid Density Meters Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market
Others
Coconut Activated Carbon Market
Others
Europe Legal Services Market