
 Global Multi-Access Edge Computing Market | 2026-2036
Global Multi-Access Edge Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multi-Access Edge Computing Market Foresight
The divergence between cloud-native and edge-native deployment tiers is realigning vendor strategies across the Multi-Access Edge Computing landscape. Hewlett Packard Enterprise leverages its integrated hardware-software stack to dominate enterprise edge installations. Cisco Systems anchors its position through deep networking heritage and SD-WAN integration capabilities. Intel Corporation sustains technology leadership via processor architectures optimized for distributed compute workloads.
Multi-Access Edge Computing denotes a distributed IT architecture that positions compute, storage, and network resources within ten milliseconds of end-user devices, typically operating at base stations, central offices, or factory floors. Its primary purpose is to process latency-sensitive workloads locally while maintaining cloud orchestration for non-time-critical analytics. Network Function Virtualization solutions currently occupy the largest solution segment as telcos virtualize core network functions at the edge. Data Analytics offerings represent the fastest-expanding category as industrial enterprises deploy predictive maintenance algorithms on factory-floor nodes. Security Management solutions command premium margins due to zero-trust architecture requirements for distributed attack surfaces.
The Federal Communications Commission shapes US market access through spectrum allocation rules for CBRS and mmWave bands enabling private edge networks. The European Telecommunications Standards Institute and ETSI MEC standards framework define interoperability requirements that equipment vendors must satisfy for carrier deployments. The EU AI Act imposes data sovereignty obligations that directly stimulate on-premises edge processing investments. Stakeholders must monitor evolving national spectrum policies and AI governance frameworks to anticipate where edge infrastructure investments will unlock sustainable returns.
Market Dynamics
The EU AI Act's data sovereignty mandates are forcing telecommunications operators to localize inference workloads, compressing cloud dependency and accelerating distributed infrastructure commitments across manufacturing and mobility verticals.
Growth Catalysts
- Private 5G spectrum allocation:Germany's Bundesnetzagentur and Japan's MIC are releasing localized spectrum blocks that enable factory-floor edge deployments without carrier intermediation.
- ETSI MEC standardization:The framework's interoperability specifications reduce vendor lock-in, accelerating carrier procurement cycles for multi-vendor edge stacks.
- Predictive maintenance algorithms:Automotive and semiconductor fabs in South Korea are deploying real-time vibration analysis at base station nodes to sub-10ms latency thresholds.
Market Restraints
- GPU and specialized accelerator shortages:Supply concentration among Taiwan-based foundries creates 6-9 month lead times for edge inference cards.
- GDPR Article 44 transfer restrictions:The regulation's adequacy decision uncertainty forces redundant edge investments in each jurisdiction rather than centralized processing.
- Optical transport cost inflation:Dense wavelength division multiplexing equipment price volatility compresses margins on backhaul-heavy rural edge nodes.
Strategic Opportunities
- India's smart city mandates:The Ministry of Housing and Urban Affairs' 100 Smart Cities Mission creates demand for traffic management and public safety edge nodes.
- Convergence of AI inference and digital twins:Industrial enterprises are merging real-time simulation with edge-deployed machine vision for closed-loop process control.
- EU Green Deal operational efficiency requirements:The framework's embodied carbon tracking obligations stimulate edge-based energy monitoring in automotive supply chains.
Industry Challenges
- Edge-native software engineering scarcity:Container orchestration expertise for constrained compute environments remains concentrated among hyperscaler alumni.
- Multi-vendor integration complexity:Heterogeneous hardware from server OEMs, telco equipment vendors, and cloud providers creates API fragmentation and testing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multi-Access Edge Computing Market |
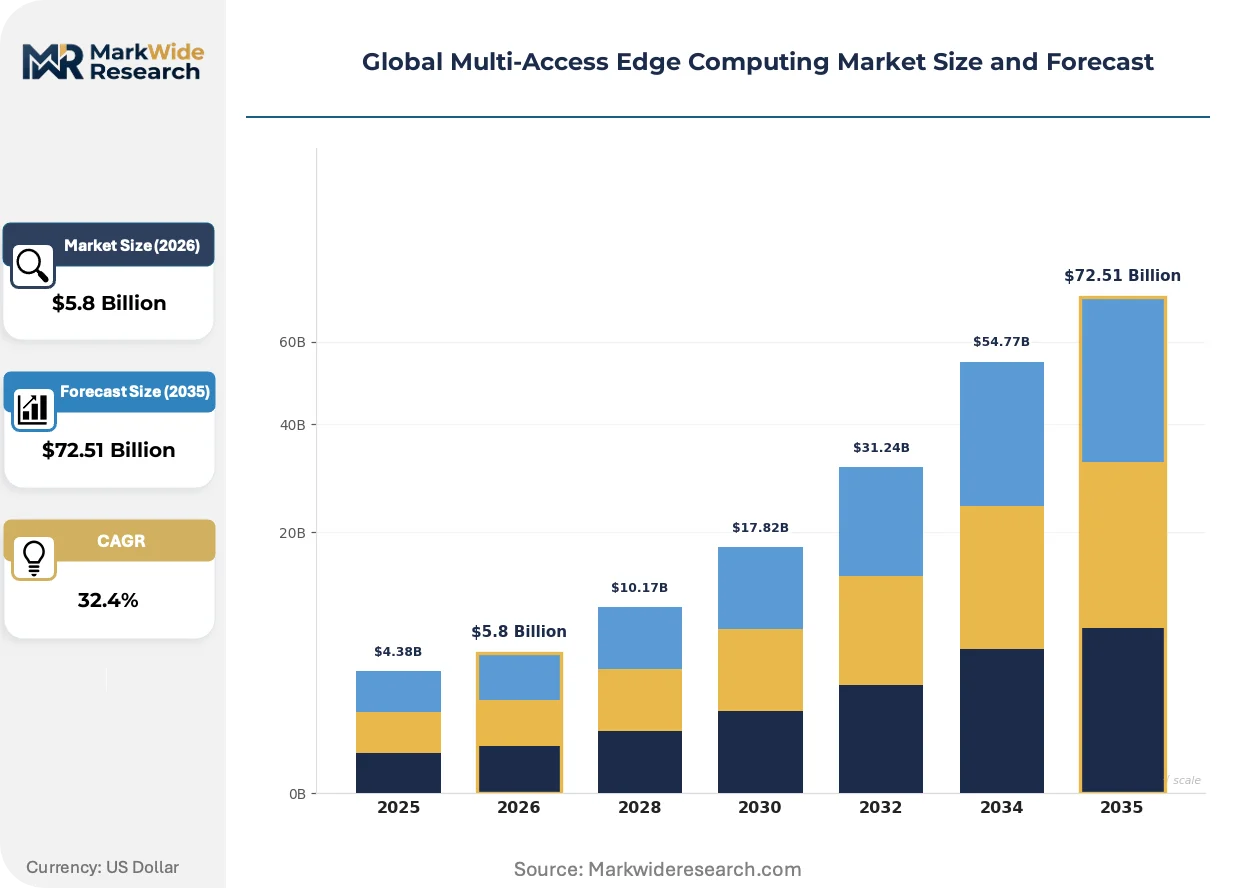
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $72.51 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Native, On-Premises, Hybrid, Edge-Native Solution: Network Function Virtualization, Data Analytics, Security Management, IoT Integration, Content Delivery Use Case: Smart Cities, Industrial Automation, Immersive Gaming, Autonomous Vehicles, Retail Experience End User: Telecommunications, Manufacturing Enterprises, Media & Entertainment, Transportation Providers, Public Safety |
| Companies Covered | Hewlett Packard Enterprise, Cisco Systems, Intel Corporation, Dell Technologies, Huawei Technologies, Nokia, Ericsson, ADLINK Technology, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multi-Access Edge Computing Market Shifts & Advancements
Containerized network functions and AI inference engines are migrating from centralized clouds to radio access network edges, compressing architectural decisions around hardware-software co-design and operational sovereignty.
Software-defined radio platforms with integrated AI accelerators are converging with 5G baseband processing units, collapsing separate hardware tiers into single-board edge servers. Telecommunications operators in Germany and Japan are deploying these converged units at scale to reduce rack space and power draw. The integration is converging with traditional IT server procurement patterns, forcing infrastructure vendors to absorb radio frequency engineering competencies.
The EU AI Act's risk classification system for biometric and critical infrastructure applications is mandating on-premises processing for high-risk inference workloads. Industrial automation vendors must now architect edge nodes with auditable data lineage and human oversight interfaces. Automotive and healthcare segments in France and Germany are responding by specifying ETSI MEC-compliant platforms with embedded compliance documentation.
Buyers are unbundling hardware procurement from managed services, shifting from bundled capex contracts to separate infrastructure ownership and operations subscriptions. Systems integrators are displacing traditional OEM direct sales in South Korean and Japanese manufacturing verticals. This unbundling is most visible in semiconductor fabs, where facility engineering teams specify bare-metal edge servers while outsourcing Kubernetes management to specialized platform operators.
Global Multi-Access Edge Computing Market Segmentation
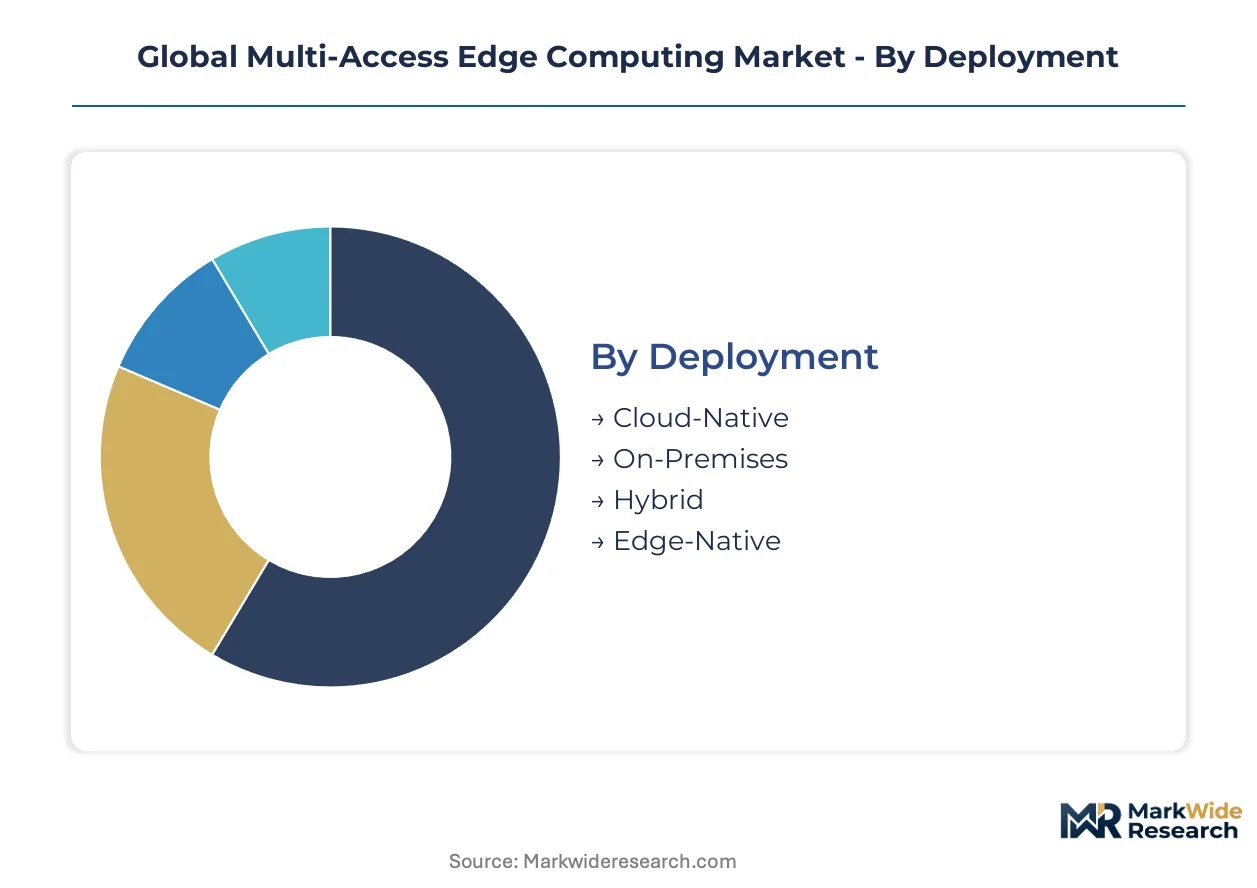
Edge computing architectures fragment across deployment philosophies, solution stacks, and vertical applications. Each segmentation axis reveals distinct procurement patterns and margin structures that vendors must navigate.
Deployment:
Cost tier separates buyers seeking operational flexibility from those prioritizing capital control and data sovereignty.
- Cloud-Native:Containerized workloads orchestrated through hyperscaler-managed platforms with centralized control planes. Manufacturing enterprises in Germany favor this model for predictive maintenance applications where burst compute needs fluctuate seasonally.
- On-Premises:Dedicated hardware installations within customer facilities with full operational ownership. South Korean semiconductor fabs mandate this deployment for EU AI Act compliance, eliminating cross-border data exposure.
- Hybrid:Split workload distribution between edge nodes and central cloud with policy-driven orchestration. Japanese automotive suppliers deploy hybrid architectures to balance real-time quality control with long-term supply chain analytics.
- Edge-Native:Applications architected specifically for constrained compute environments with intermittent connectivity. Mining operations in Western Australia specify edge-native platforms for autonomous haul truck coordination beyond cellular coverage.
On-Premises leads volumes today; Edge-Native is gaining share fastest.
Solution:
Application maturity determines whether buyers seek proven infrastructure or emerging capability layers.
- Network Function Virtualization:Software implementations of routing, switching, and session management functions previously delivered via proprietary hardware. Telecommunications operators in Japan virtualize packet core functions at 5G base stations to reduce proprietary appliance dependency.
- Data Analytics:Real-time stream processing and inference engines deployed at network edges. German automotive paint shops deploy vibration analytics on factory-floor nodes to detect robot arm degradation before quality deviation occurs.
- Security Management:Zero-trust policy enforcement, microsegmentation, and threat detection distributed across edge attack surfaces. French healthcare providers specify ETSI MEC-compliant security stacks for patient data processing under GDPR Article 44 constraints.
- IoT Integration:Protocol translation, device onboarding, and edge-to-cloud data pipelines for sensor networks. Singapore's port authority deploys IoT integration nodes to harmonize container tracking across 12 different terminal operator systems.
- Content Delivery:Caching and request routing optimization for latency-sensitive media distribution. South Korean broadcasters cache 8K video segments at metro edge nodes to support immersive viewing experiences during live esports tournaments.
Network Function Virtualization dominates current procurement; Data Analytics exhibits the steepest expansion trajectory.
Use Case:
Volume concentration and margin profile diverge sharply across latency requirements and regulatory exposure.
- Smart Cities:Traffic signal optimization, public safety video analytics, and environmental monitoring deployed at municipal infrastructure edges. India's 100 Smart Cities Mission drives demand for intersection-mounted inference nodes capable of processing 500+ camera feeds per district.
- Industrial Automation:Closed-loop process control, predictive maintenance, and digital twin synchronization on factory floors. Taiwan semiconductor fabs deploy sub-5ms edge nodes for lithography equipment coordination where cloud latency would destroy yield.
- Immersive Gaming:Cloud gaming stream rendering and haptic feedback processing positioned near subscriber concentrations. NTT Docomo deploys gaming-optimized edge pods in Tokyo and Osaka metro zones to compress motion-to-photon latency below 20 milliseconds.
- Autonomous Vehicles:V2X coordination, high-definition map updates, and sensor fusion offload at roadside units. Germany's KBA mandates ETSI MEC-compliant roadside infrastructure for Level 4 vehicle certification on designated motorway corridors.
- Retail Experience:Computer vision checkout, inventory robots, and personalized digital signage within store environments. French luxury retailers deploy edge nodes for real-time footfall analysis while maintaining GDPR-compliant data localization.
Industrial Automation anchors current spending; Smart Cities is expanding most quickly.
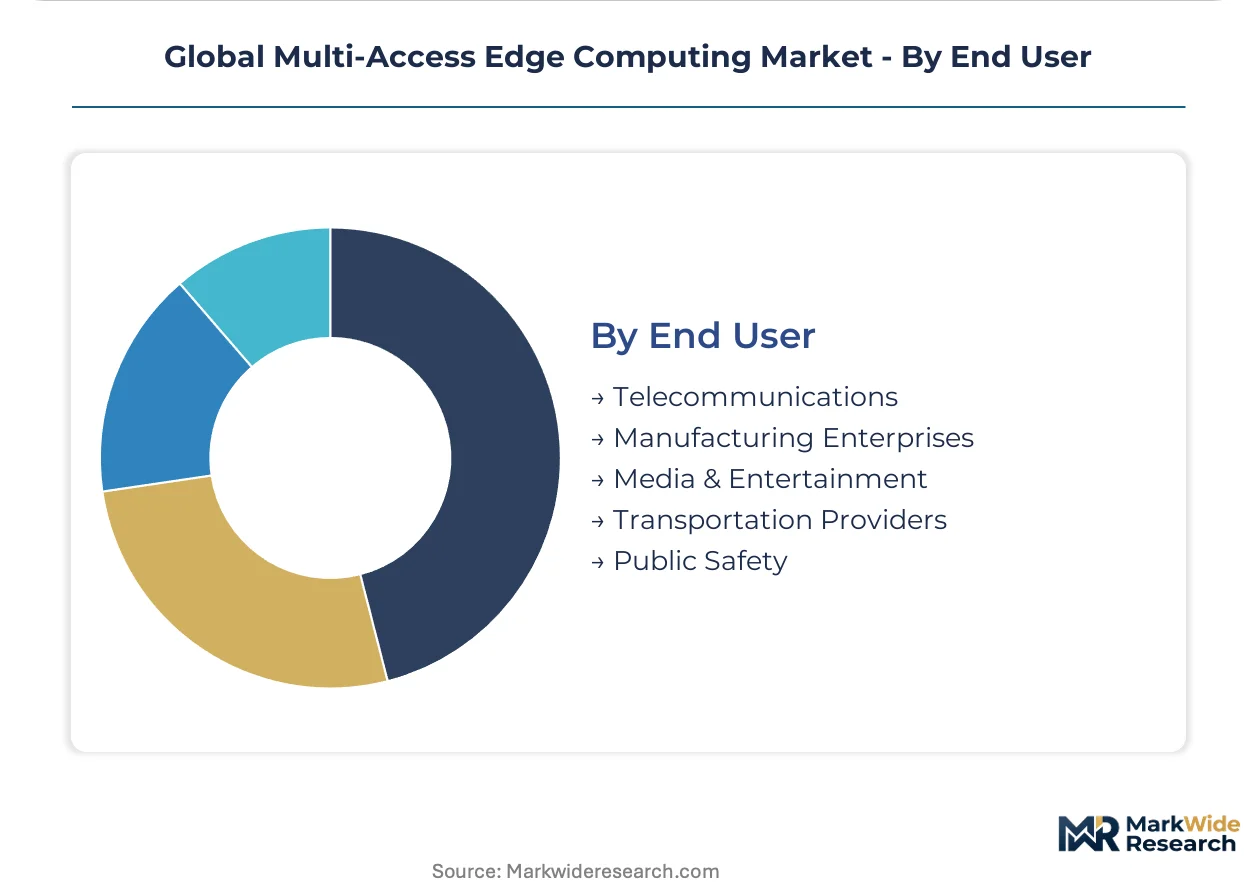
End User:
Procurement sophistication and integration complexity separate legacy infrastructure operators from digital-native verticals.
- Telecommunications:Mobile network operators and fixed-line carriers virtualizing core and access network functions. Deutsche Telekom deploys multi-vendor edge stacks across 2,000+ German cell sites under ETSI MEC interoperability mandates.
- Manufacturing Enterprises:Discrete and process manufacturers automating production lines and supply chains. Hyundai Motor Group operates private 5G edge networks at three Korean vehicle plants for welding robot coordination and quality vision systems.
- Media & Entertainment:Broadcasters, streaming platforms, and live event producers optimizing content delivery. NHK deploys 8K broadcast edge nodes for Olympic coverage compression and regional distribution.
- Transportation Providers:Railways, ports, and logistics operators coordinating mobile assets and infrastructure. JR East operates edge computing at 30 Tokyo stations for passenger flow prediction and emergency response optimization.
- Public Safety:Police, fire, and emergency medical services requiring resilient, sovereign communication networks. France's Ministry of Interior deploys ETSI MEC-compliant edge infrastructure for encrypted first-responder video sharing.
Telecommunications commands the largest installed base; Manufacturing Enterprises is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Edge computing talent clusters concentrate around telecommunications engineering hubs in Germany, semiconductor manufacturing corridors in South Korea, and industrial automation centers in Japan. These workforce concentrations anchor infrastructure investment decisions and shape vendor localization strategies.
United States
Private 5G deployments at manufacturing facilities and defense installations drive edge node procurement. The FCC's CBRS spectrum framework enables localized network buildouts without carrier intermediation. Austin and Dallas-Fort Worth host the densest concentration of edge-native software engineering talent supporting enterprise deployments.
Germany
Automotive paint shops and semiconductor fabs demand sub-10ms processing for predictive maintenance and quality control. The EU AI Act's risk classification system mandates on-premises inference for high-risk industrial applications. Bavaria's manufacturing belt around Munich and Ingolstadt leads private 5G edge installations for welding robot coordination.
Japan
NTT Docomo and KDDI accelerate radio access network virtualization at 5G base stations. METI's digital transformation subsidies reduce procurement friction for factory-floor edge deployments. Osaka and Nagoya automotive suppliers deploy hybrid architectures balancing real-time quality control with cloud analytics.
South Korea
Hyundai Motor Group and Samsung Electronics operate private 5G networks for welding coordination and lithography equipment monitoring. The national smart manufacturing initiative funds edge infrastructure at designated innovation clusters. Hwaseong and Pyeongtaek semiconductor complexes mandate sub-5ms edge nodes for yield-critical process control.
India
The Ministry of Housing and Urban Affairs' 100 Smart Cities Mission creates procurement pipelines for traffic management and public safety edge nodes. TRAI's spectrum harmonization efforts support localized network deployments. Bangalore and Hyderabad technology corridors concentrate systems integrators capable of deploying ETSI MEC-compliant infrastructure.
Global Multi-Access Edge Computing Market Competitive Landscape
Capital-heavy server manufacturers compete with asset-light software orchestrators for control of enterprise edge deployments. The vendor landscape segments into three tiers: integrated hardware-software stacks, networking-centric platforms, and cloud-extended edge services. Consolidation pressure intensifies as telecommunications operators demand multi-vendor interoperability under ETSI MEC specifications. Strategic moves center on absorbing radio frequency engineering competencies and unbundling hardware sales from managed service subscriptions.
Within the integrated infrastructure tier, Hewlett Packard Enterprise and Dell Technologies occupy positions spanning enterprise server installations through telecommunications edge nodes. Cisco Systems exemplifies the networking-centric archetype, leveraging SD-WAN integration capabilities to anchor carrier procurement decisions. Intel Corporation sits within the silicon layer, supplying processor architectures optimized for distributed compute workloads across heterogeneous deployment environments.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Cisco Systems |
| Intel Corporation |
| Dell Technologies |
| Huawei Technologies |
| Nokia |
| Ericsson |
| ADLINK Technology |
| Microsoft |
| Others |
Supply & Pricing Matrix
GPU and specialized accelerator card costs cascade through edge infrastructure tiers, with Taiwan-based foundry pricing transmitting directly to German automotive paint shop procurement budgets and South Korean semiconductor fab capital expenditure plans.
Pricing Analysis
The bundled-vs-unbundled service split now defines vendor revenue capture. Hardware-software bundles command premium positioning through ETSI MEC certification tiers, while bare-metal server sales with separate Kubernetes management subscriptions erode margin pools. Price differentiation hinges on zero-trust security certification levels and after-sales operational support intensity. Pricing pressure stems from hyperscaler cloud extension offerings compressing enterprise edge budgets. Manufacturing enterprises exhibit highest price sensitivity due to volume procurement leverage, whereas public safety agencies prioritize sovereign compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries for AI inference accelerators. Edge server manufacturing concentrates in China, Taiwan, and Mexico for cost-optimized chassis assembly. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and optical transceivers. Supply chain risk centers on export control restrictions affecting GPU shipment clearances. Distribution runs through telecommunications equipment distributors and systems integrators serving manufacturing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge infrastructure procurement has shifted toward late-cycle quality specifications, with EU AI Act compliance and sub-10ms latency guarantees now table stakes for premium vendor selection.
For Market Incumbents: Lock in carrier relationships through ETSI MEC interoperability certification investments before multi-vendor procurement mandates harden. Absorb radio frequency engineering competencies to defend against converged hardware-software entrants. Vertical integration into AI accelerator silicon design hedges Taiwan foundry supply risk. For New Entrants and Emerging Players: Capture India's smart city edge node deployments where systems integrator relationships outweigh incumbent hardware brand equity. Target mining and remote industrial automation for edge-native software specialization. Lead with Kubernetes management subscriptions unbundled from commodity server procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where ETSI MEC compliance documentation and carrier certification backlogs create acquisition premiums for ready-qualified platforms. Long-term viability favors vendors with embedded AI accelerator architectures and sovereign cloud partnerships. Watch Germany's Bundesnetzagentur private 5G spectrum auction velocity as infrastructure deployment inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ETSI MEC Certification Investment | Carrier procurement mandates in Germany and Japan require interoperability documentation for multi-vendor edge stacks. |
| AI Accelerator Silicon Design | In-house inference chip development reduces dependency on Taiwan foundry allocation cycles and six-month lead times. |
| Private 5G Spectrum Partnership | FCC CBRS and Germany BNetzA localized spectrum blocks enable factory-floor deployments without carrier intermediation. |
| Edge-Native Kubernetes Platform | Specialized container orchestration for constrained compute environments commands subscription premiums from mining operators. |
| Zero-Trust Security Stack Integration | GDPR Article 44 and EU AI Act compliance documentation differentiates offerings for French healthcare and German automotive buyers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with telecommunications operators, manufacturing enterprise IT directors, semiconductor fab facility engineers, and systems integrators with secondary validation against ETSI technical specifications, FCC spectrum allocation filings, EU AI Act regulatory texts, and hyperscaler capex disclosures. Bottom-up edge node deployment tallies triangulated against top-down infrastructure investment forecasts.
Historical reference periods anchored the projection horizon through segmented modeling across deployment architecture, solution stack maturity, and vertical application latency requirements. CAGRs derived from policy-driven investment schedules, spectrum auction timelines, and manufacturing automation capex cycles. Edge-native software engineering talent density and private 5G spectrum release velocity served as location-specific forecast inputs.
Spectrum policy reversals, GPU export control expansions, and EU AI Act enforcement variance are the dominant revision risks to infrastructure deployment assumptions. Forecasts reflect documented regulatory trajectories and announced foundry capacity commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Japan Indoor LBS Market
Others
Linear Shaft Market
Others
APAC Smart Home Market
Others
Aircraft Switches Market
Others
Nutricosmetics Market
Others
Enterprise Video Market
Others
Global Hardware As a Service (Haas) Market
Others
Digital Signage Media Player Market
Others
US Luxury Travel Market
Others
Mobile Computing Devices Market
Others
Global Military and Aerospace Sensors Market
Others
Manometers Market
Others
Eye Balm Market
Others
Super Computer Market
Others
Gas Radiators Market
Others
AI In Government And Public Services Market