
 Hydraulic Valves Market | 2026-2036
Hydraulic Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Valves Market Outlook
Modular valve manifold assemblies is hardening as the preferred procurement format for OEMs seeking reduced installation complexity and faster field service turnaround. Bosch Rexroth leverages its integrated drive and control portfolio to bundle manifold systems with electronic control units. Parker Hannifin anchors North American supply through extensive distribution and aftermarket service infrastructure. Eaton Corporation competes on severe-duty applications where mining and offshore specifications demand corrosion-resistant coatings and redundant sealing architectures.
Hydraulic valves are precision-engineered flow control devices, typically machined from ductile iron or forged steel with hardened spool-and-sleeve internals, designed to direct, regulate, or modulate pressurized fluid within closed-loop power transmission circuits. They operate at pressures commonly spanning 3,000 to 6,000 psi, with proportional and servo variants enabling closed-loop position or force control in mobile and industrial machinery. Directional control valves command the largest revenue pool due to universal deployment across mobile equipment, yet pressure control valves are gaining share as load-sensing and energy-recovery architectures proliferate in construction and agriculture. Electric-over-hydraulic actuation technology is expanding fastest among technology segments, displacing pure manual and pneumatic interfaces where remote diagnostics and programmable motion profiles justify the electronics premium.
ISO 4406 cleanliness standards and the EU Machinery Directive shape product design by mandating filtration compatibility and fail-safe positioning for valves deployed in European equipment. The EPA and OSHA in the United States enforce spill containment and operator safety rules that elevate demand for sealed cartridge valves and integrated sensor feedback. Stakeholders must monitor how digital twin integration and predictive maintenance contracts reshape valve specification criteria and supplier qualification protocols.
Market Dynamics
Electric-over-hydraulic actuation is compressing specification cycles as OEMs demand programmable motion profiles and remote diagnostics, forcing valve suppliers to embed sensor feedback and electronic control units into core product architectures.
Growth Catalysts
- EU F-Gas Regulation:Leak-tight design mandates are accelerating R&D investment in zero-emission sealing architectures and lower-GWP hydraulic fluid compatibility across European mobile equipment fleets.
- Construction equipment OEMs:Infrastructure investment waves are concentrating procurement volume in Germany, where precision engineering clusters anchor demand for high-pressure directional control valves.
- Load-sensing architectures:Energy-recovery circuits in agriculture and construction machinery are expanding the addressable market for proportional pressure control valves with integrated electronic feedback.
Market Restraints
- Specialized alloy input costs:Forged steel and ductile iron price volatility compresses margin buffers for mid-tier manufacturers without captive foundry operations or long-term supply agreements.
- German supply concentration:Precision spool-and-sleeve machining capability clusters in Baden-Württemberg and Bavaria, creating geographic single-point-of-failure risk for just-in-time OEM supply chains.
- Electromechanical substitution:All-electric linear actuators are capturing position-control applications below 3,000 psi where battery energy density improvements reduce hydraulic system advantages.
Strategic Opportunities
- Digital twin integration:Valve suppliers embedding real-time flow telemetry can capture predictive maintenance contracts from fleet operators seeking to minimize unplanned downtime in mining and offshore applications.
- EU Machinery Directive compliance services:Fail-safe positioning and filtration compatibility certification support creates recurring revenue streams alongside hardware sales for European equipment exports.
- Modular manifold assemblies:Pre-configured valve blocks with integrated electronic control units reduce field installation complexity, opening specification opportunities with OEMs prioritizing service turnaround speed.
Industry Challenges
- Mechatronics talent scarcity:The convergence of hydraulics engineering and embedded electronics design requires skill sets concentrated in automotive and aerospace sectors, not traditional fluid power education pipelines.
- ISO 4406 cleanliness certification timelines:Extended validation cycles for filtration-compatible valve designs delay product launches and tie up engineering resources across multiple OEM qualification programs.
- Legacy system integration friction:Retrofitting electronic feedback architectures into existing hydraulic circuits demands custom adapter manifolds and complicates aftermarket parts standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Valves Market |
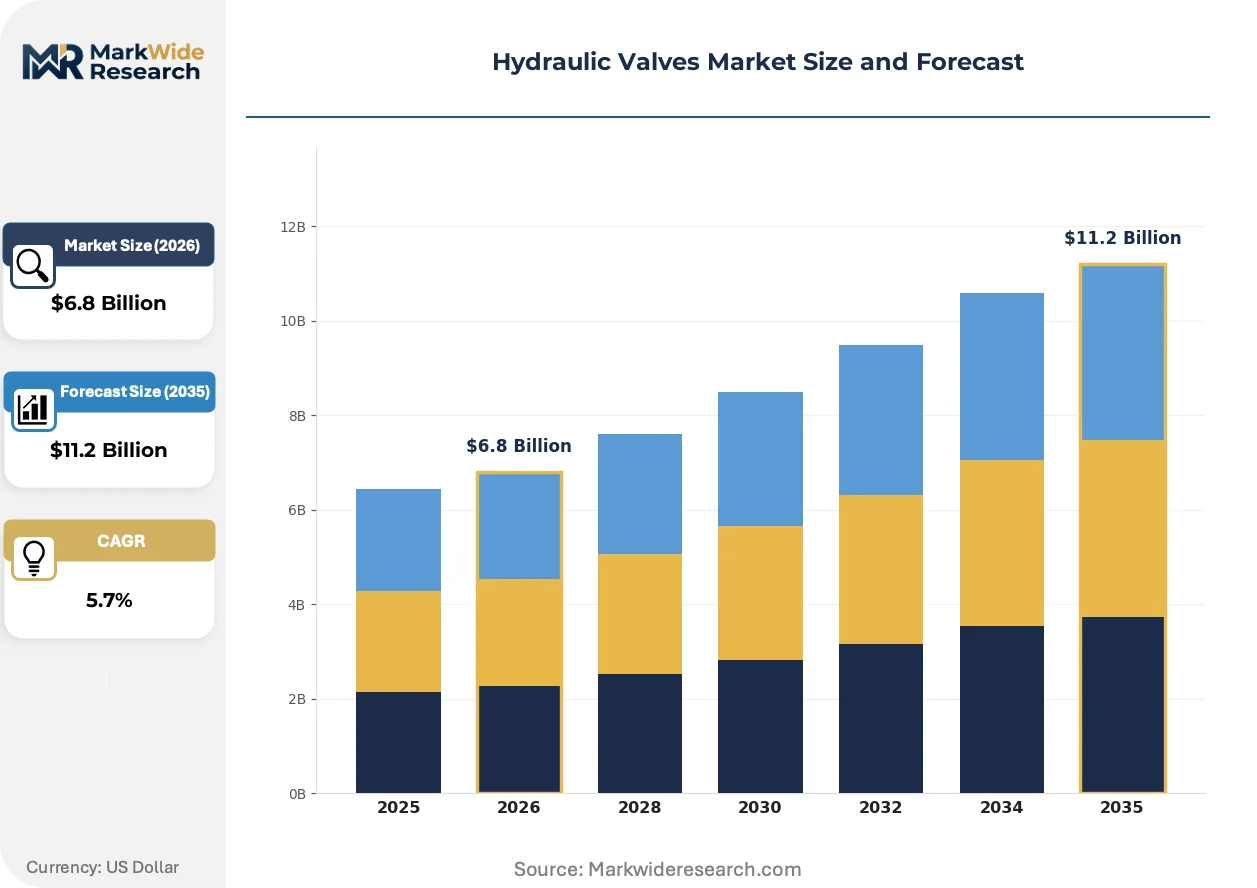
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Directional Control Valves, Pressure Control Valves, Flow Control Valves, Check Valves Technology: Electric, Manual, Pneumatic, Hydraulic End User: Construction, Agriculture, Mining, Manufacturing Size: Small, Medium, Large, Extra Large |
| Companies Covered | Parker Hannifin, Bosch Rexroth, Danfoss, Eaton Corporation, HYDAC International, Kawasaki Heavy Industries, KYB Corporation, HAWE Hydraulik, Daikin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Valves Market Strategic Shifts
Valve architectures are bifurcating between sealed cartridge designs for severe-duty environments and intelligent manifold systems for connected machinery, with cleanliness standards and predictive capability becoming primary specification criteria.
Smart valve positioners with integrated pressure and temperature sensors are absorbing diagnostic functions previously handled by external monitoring equipment. Mining and offshore operators are specifying these units for corrosion-resistant redundant sealing architectures. The technology is absorbing maintenance budget allocations as fleet managers prioritize uptime guarantees over component-first procurement.
EPA spill containment rules and OSHA operator safety mandates are elevating demand for sealed cartridge valves with integrated sensor feedback in United States mobile equipment. Manufacturers are redesigning port geometries and seal grooves to eliminate external leakage paths. Construction OEMs serving North American markets are responding by qualifying suppliers with documented containment testing protocols.
Fleet operators are consolidating valve procurement through authorized distributor networks that bundle specification support with aftermarket service infrastructure. Traditional component distributors are being displaced by integrated fluid power specialists offering manifold assembly and field commissioning. This pattern is most visible in Germany, where automotive-linked hydraulics R&D clusters concentrate technical buying influence.
Hydraulic Valves Market Segmentation
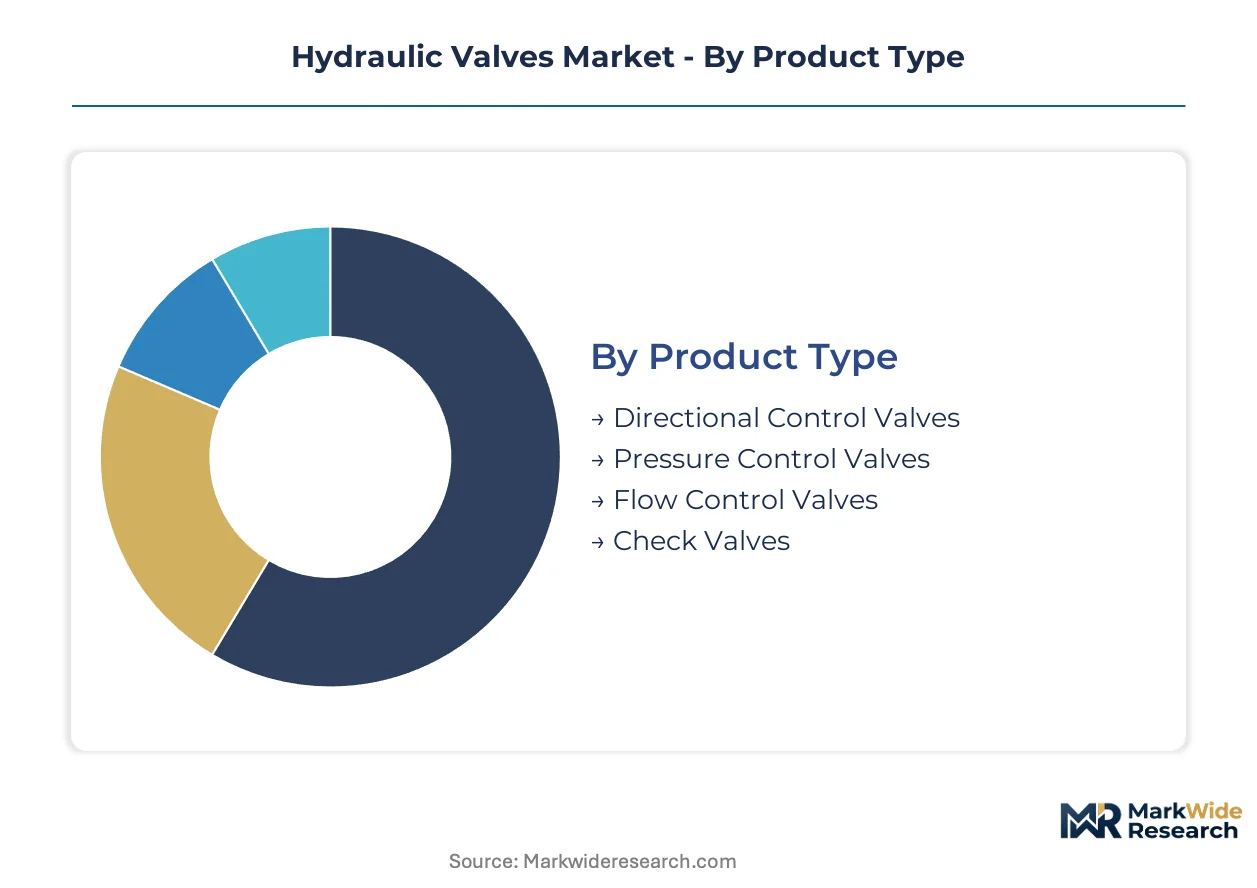
Hydraulic valve specification follows distinct technical hierarchies that determine procurement patterns across mobile and industrial equipment. Understanding how product architecture, actuation technology, and dimensional class intersect reveals where margin concentration and supplier qualification requirements diverge most sharply.
Product Type:
Pressure rating and flow geometry differentiate valve families, with spool-and-sleeve machining precision determining interchangeability standards.
- Directional Control Valves:Spool-type designs with multiple port configurations command the largest revenue pool due to universal deployment across excavators, loaders, and material handlers. Procurement concentrates with German construction equipment OEMs seeking ISO 4406 cleanliness compatibility for load-sensing circuits.
- Pressure Control Valves:Proportional relief and reducing variants enable closed-loop force management in agriculture implements. Demand is climbing fastest as energy-recovery architectures proliferate in combine harvesters and tractor hydraulics.
- Flow Control Valves:Pressure-compensated and non-compensated designs regulate actuator speed in manufacturing automation cells.
- Check Valves:Pilot-operated and spring-loaded configurations prevent reverse flow in mining haul truck braking systems.
Directional control valves lead on scale; pressure control valves lead on momentum.
Technology:
Actuation interface selection determines electronics content, diagnostic capability, and qualification complexity for valve suppliers.
- Electric:Servo and proportional solenoids with integrated position feedback enable programmable motion profiles. Electric-over-hydraulic architectures are expanding most quickly as remote diagnostics justify the electronics premium in fleet-managed construction equipment.
- Manual:Lever and cam-operated directional valves persist in cost-sensitive agricultural implements where operator presence is constant.
- Pneumatic:Air-piloted actuation serves explosion-risk environments in mining and offshore applications where electrical ignition hazards are regulated.
- Hydraulic:Direct pilot pressure actuation remains standard for high-flow, high-pressure circuits in severe-duty mining shovels and draglines.
Electric actuation dominates new specification; hydraulic piloting retains installed-base replacement volume.
End User:
Equipment duty cycles and operating environment severity dictate seal material, coating specification, and redundancy requirements.
- Construction:Infrastructure investment waves concentrate procurement volume in German OEM supply chains. Telematics integration and predictive maintenance contracts are reshaping valve specification criteria for excavators and wheel loaders.
- Mining:Corrosion-resistant coatings and redundant sealing architectures address abrasive slurry exposure and extended mean-time-between-failure requirements in haul trucks and shovels.
- Agriculture:Load-sensing and energy-recovery circuits in tractors and harvesters drive proportional valve demand with electronic feedback.
- Manufacturing:Presses, injection molding machines, and metal forming equipment require precision flow control with ISO cleanliness certification.
Construction anchors procurement volume; mining commands the highest specification premiums.
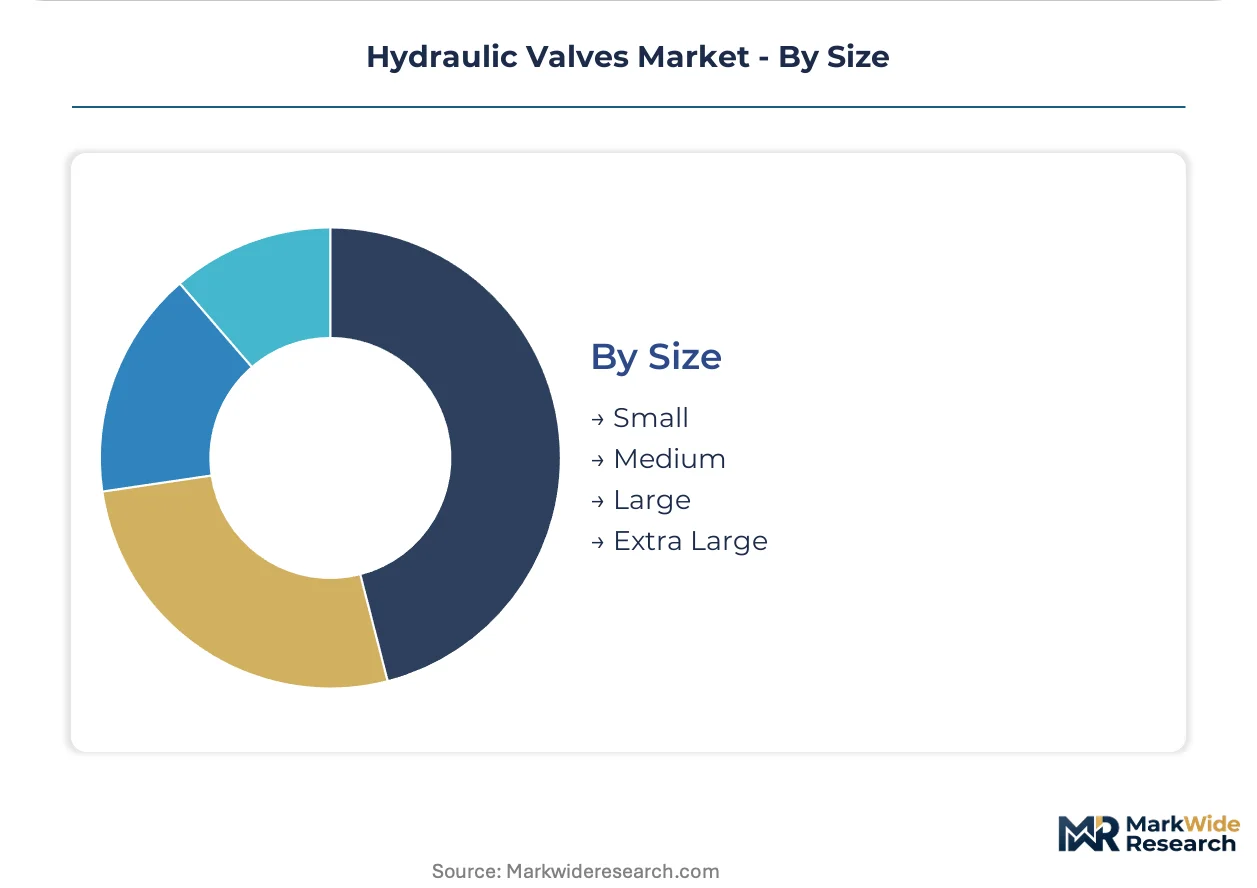
Size:
Port dimension and flow capacity determine foundry capability requirements and machining center specifications for valve manufacturers.
- Medium:Nominal sizes from 3/4 inch to 1-1/2 inch serve the broadest equipment population across construction and agriculture. German precision engineering clusters concentrate machining capacity for this dimensional class.
- Large:Two-inch and above porting addresses mining shovels, offshore winches, and heavy-lift cranes where forged steel bodies and hardened spool coatings are mandatory.
- Small:Sub-3/4 inch cartridge valves integrate into compact agricultural implements and manufacturing automation manifolds.
- Extra Large:Custom-engineered valves above three-inch nominal size serve specialized offshore and mining applications with limited supplier qualification.
Medium sizes lead on unit volume; large sizes lead on revenue per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hydraulic valve industry traces its modern scaling to German precision engineering clusters that pioneered spool-and-sleeve machining for high-pressure mobile equipment in the post-war industrial expansion.
Germany
Construction equipment OEMs concentrate procurement volume in Baden-Württemberg and Bavaria, where automotive-linked hydraulics R&D anchors technical specification authority. The EU F-Gas Regulation mandates leak-tight designs that accelerate zero-emission sealing R&D. Stuttgart and Munich precision engineering clusters supply just-in-time manifold assemblies to global excavator and loader manufacturers.
United States
EPA spill containment rules and OSHA operator safety mandates elevate demand for sealed cartridge valves with integrated sensor feedback. Infrastructure investment waves concentrate procurement with domestic construction equipment fleets. The Midwest industrial corridor hosts distribution networks bundling specification support with aftermarket service infrastructure for mining and agriculture applications.
China
Dual carbon goals and GB standards for industrial machinery emissions reshape hydraulic fluid compatibility requirements. Domestic construction equipment OEMs scale local procurement of directional control valves for excavators and wheel loaders. Yangtze River Delta manufacturing clusters expand machining capacity for medium-size spool valves serving Asian mobile equipment markets.
Japan
METI industrial efficiency standards promote energy-recovery architectures in agricultural and construction machinery. Domestic OEMs specify proportional pressure control valves with electronic feedback for tractor and harvester hydraulics. Kanto and Kansai industrial belts concentrate servo valve R&D for precision motion control in manufacturing automation.
India
PLI scheme incentives for construction and mining equipment manufacturing expand domestic valve demand. BIS certification requirements for industrial machinery safety elevate specification barriers for imported components. Maharashtra and Gujarat industrial corridors attract precision machining investments to serve regional OEM supply chains.
Hydraulic Valves Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive hydraulics divisions. Tiered supplier qualification separates premium manifold integrators from commodity cartridge producers. Three archetypes dominate: integrated motion control specialists bundling valves with electronic units; severe-duty component suppliers serving mining and offshore specifications; and regional fabricators competing on aftermarket service density. Geographic expansion and strategic partnerships represent the dominant competitive moves, with suppliers embedding predictive maintenance capabilities to capture recurring revenue from fleet operators.
Among diversified industrial groups, Parker Hannifin and Eaton Corporation exemplify the integrated systems archetype, while Bosch Rexroth anchors the precision-engineering tier with bundled drive and control portfolios. HYDAC International and HAWE Hydraulik occupy positions within the specialized component segment, with geographic origins in German engineering clusters reflecting historical concentration of spool-and-sleeve machining expertise. Daikin Industries and KYB Corporation represent Japanese industrial diversification into hydraulic actuation, while Danfoss exemplifies European energy-efficiency positioning across mobile and industrial applications.
| Leading Market Players |
|---|
| Parker Hannifin |
| Bosch Rexroth |
| Danfoss |
| Eaton Corporation |
| HYDAC International |
| Kawasaki Heavy Industries |
| KYB Corporation |
| HAWE Hydraulik |
| Daikin Industries |
| Others |
Value Chain & Pricing Dynamics
Precision spool-and-sleeve machinists concentrated in Baden-Württemberg and Bavaria anchor labor-cost differentials that widen pricing-tier spreads between German-engineered premium manifolds and Asian-fabricated commodity cartridges. This workforce scarcity compresses margins for mid-tier suppliers lacking captive machining capacity or long-term OEM contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 4406-certified manifold assemblies with integrated electronics from basic directional control valves and unbranded replacement cartridges. Price differentiation rests on certification grade and after-sales service bundling rather than raw material quality alone. Pricing pressure stems from electromechanical substitution below 3,000 psi applications where all-electric actuators erode hydraulic system value propositions. Construction equipment OEMs in Germany exhibit lowest price sensitivity due to telematics integration requirements, while agricultural implement manufacturers in India and Southeast Asia drive hardest bargain on unit costs.
Supply Chain Analysis
Freight cost volatility for forged steel and ductile iron ingots from China and India complicates just-in-time delivery commitments to German precision engineering clusters. Raw material sourcing draws from Brazilian iron ore, Chinese rare earth processing for magnetic alloys in servo valves, and German specialty steel mills for hardened spool coatings. Single-source vulnerability concentrates in Baden-Württemberg machining centers where multi-axis grinding capability for sub-micron tolerances remains limited to three qualified supplier groups. Distribution runs through authorized fluid power specialists bundling manifold assembly with field commissioning rather than traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as fleet operators shift procurement criteria toward predictive maintenance contracts and ISO-certified cleanliness compatibility rather than component-first pricing.
For Market Incumbents: Acquire mechatronics engineering talent pools concentrated in automotive and aerospace sectors to close skill gaps in embedded electronics design. Consolidate backward integration into specialty steel forging and rare earth magnetic alloy processing to buffer input cost volatility. Defensive positioning requires embedding real-time flow telemetry architectures before electromechanical substitution accelerates in sub-3,000 psi position-control applications. For New Entrants and Emerging Players: Begin with aftermarket service infrastructure in mining and offshore markets where corrosion-resistant redundant sealing specifications create qualification barriers for established suppliers. Target Indian PLI-scheme beneficiaries in Maharashtra and Gujarat industrial corridors seeking localized precision machining partners. White-space exists in digital twin integration services for fleet operators prioritizing uptime guarantees over hardware procurement. For Investors and Strategic Acquirers: Diversified industrial conglomerates with captive hydraulics divisions are the most active acquirer in this space, seeking bolt-on electronic control unit capabilities. Long-term viability hinges on suppliers capturing recurring predictive maintenance revenue rather than transactional hardware margins. Watch for inflection when construction OEM procurement committees elevate telematics integration to mandatory specification criteria rather than optional premium tier.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Forging | Captive supply of ductile iron and forged steel bodies buffers margin compression from commodity price volatility. |
| Digital Twin Integration Partnership | Real-time flow telemetry embedded in manifold assemblies captures predictive maintenance contracts from mining fleet operators. |
| EU Machinery Directive Certification Services | Recurring revenue streams from fail-safe positioning and filtration compatibility support accompany hardware sales. |
| Mechatronics Talent Acquisition | Embedded electronics design capability closes skill gaps as electric-over-hydraulic architectures displace manual interfaces. |
| Authorized Distributor Network Consolidation | Integrated fluid power specialists displace traditional component distributors by bundling specification support with field commissioning. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM procurement teams, aftermarket service directors, plant engineers at mining operations, and fluid power distribution channel partners with secondary validation. Secondary sources included customs and trade flow data for hydraulic component imports, SEC filings from diversified industrial conglomerates, ISO certification registry databases, and EU regulatory filing repositories. Bottom-up unit shipment modeling and top-down value triangulation cross-checked segment outputs.
Historical reference periods anchored projections across the modeling period, with analytical frameworks disaggregating demand by product architecture, actuation technology, end-use equipment class, and dimensional port size. CAGRs derived from curve-fitting techniques applied to OEM capital expenditure cycles and infrastructure investment waves. Industry-specific forecast inputs incorporated fleet telematics adoption rates and EU F-Gas Regulation compliance timelines for zero-emission sealing architectures.
Caveats apply where electromechanical substitution acceleration, rare earth supply disruptions, or German machining capacity constraints could materially shift the outlook. Forecasts reflect documented assumptions about OEM qualification cycle durations and cleanliness standard enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Carbon Seal Rings Market
Valves
Total Containment Vessels Market
Valves
Emergency Shutdown Valves Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
Ball Valves Market
Valves
Tank Hydrogen Valve Market
Valves
Supply Stop Valves Market
Valves
Industrial Vacuum Valves Market
Valves
Global Industrial Thermostatic Control Valves Market
Valves
Valve Manifold Box (VMB) Market
Valves
Global Plug Valve Market
Valves
North America High Voltage Switchgear Market
Valves
Global Solenoid Valves Market
Valves
Global Compression Packing Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Steel Cylinder Market