
 Air Vent Heads Market | 2026-2036
Air Vent Heads Market Size, Share, and Industry Trends Forecast 2026-2036
Air Vent Heads Market Insights
Aftermarket maintenance contracts for marine ventilation systems is realigning how suppliers capture lifetime value from vessel operators. Spirax Sarco leverages its steam system service infrastructure to bundle vent head inspections with broader HVAC maintenance programs. QINGDAO JIS MARINE VALVE CO LTD anchors its competitive position through backward integration into cast steel foundry operations for critical vent body components. NIIKURA differentiates via specialized coating technologies that extend saltwater corrosion resistance in harsh North Pacific routes.
An air vent head is a marine and industrial fitting designed to permit air exchange while preventing water ingress, typically constructed with float-operated closure mechanisms, corrosion-resistant housings, and pressure-rated seals rated for salt-laden environments. Gravity Ventilators dominate commercial marine applications due to zero power dependency and minimal moving-part failure rates, while Powered Ventilators represent the fastest-expanding segment as automated engine room climate control becomes standard on newbuild vessels. Aluminum and steel material categories split along vessel class lines, with coastal craft favoring aluminum weight savings and deep-sea tankers requiring steel structural integrity under ABS and DNV classification rules.
The International Maritime Organization mandates material traceability for ventilation components under SOLAS fire safety protocols, while classification societies including Lloyd's Register and Bureau Veritas enforce pressure-testing standards for vent head float mechanisms. Japan's METI maritime equipment certification program and South Korea's Korean Register of Shipping add national-layer compliance requirements for domestic shipyard suppliers. Buyers must evaluate supplier certification breadth against their target vessel flag registries and operating route environmental conditions.
Market Dynamics
Shipbuilders in Busan and Nagasaki industrial zones are consolidating vent head procurement around corrosion-resistant assemblies that satisfy both IMO ballast water standards and classification society fire safety rules. This concentration is compressing supplier margins while elevating material certification requirements.
Growth Catalysts
- IMO Ballast Water Management Standards:Revised material specifications for marine ventilation components are mandating upgraded vent head assemblies across newbuild fleets operating under SOLAS protocols.
- Automated Engine Room Climate Control:Powered ventilator systems are displacing passive designs on new vessels as shipyards integrate HVAC automation into vessel management platforms.
- East Asian Shipbuilding Clusters:Concentrated demand around South Korean and Japanese port industrial zones is pulling specialized coating and foundry capacity into marine supply chains.
Market Restraints
- Nickel-Alloy Input Volatility:Specialized corrosion-resistant alloys for saltwater-grade vent housings face price swings tied to mining supply disruptions and energy-intensive smelting costs.
- Foundry Capacity Concentration:Critical cast steel vent body production clusters in specific East Asian industrial zones, creating single-source vulnerability for Western shipyards.
- Float Mechanism Pressure Testing:Lloyd's Register and Bureau Veritas certification timelines extend delivery schedules, freezing working capital for smaller fabricators.
Strategic Opportunities
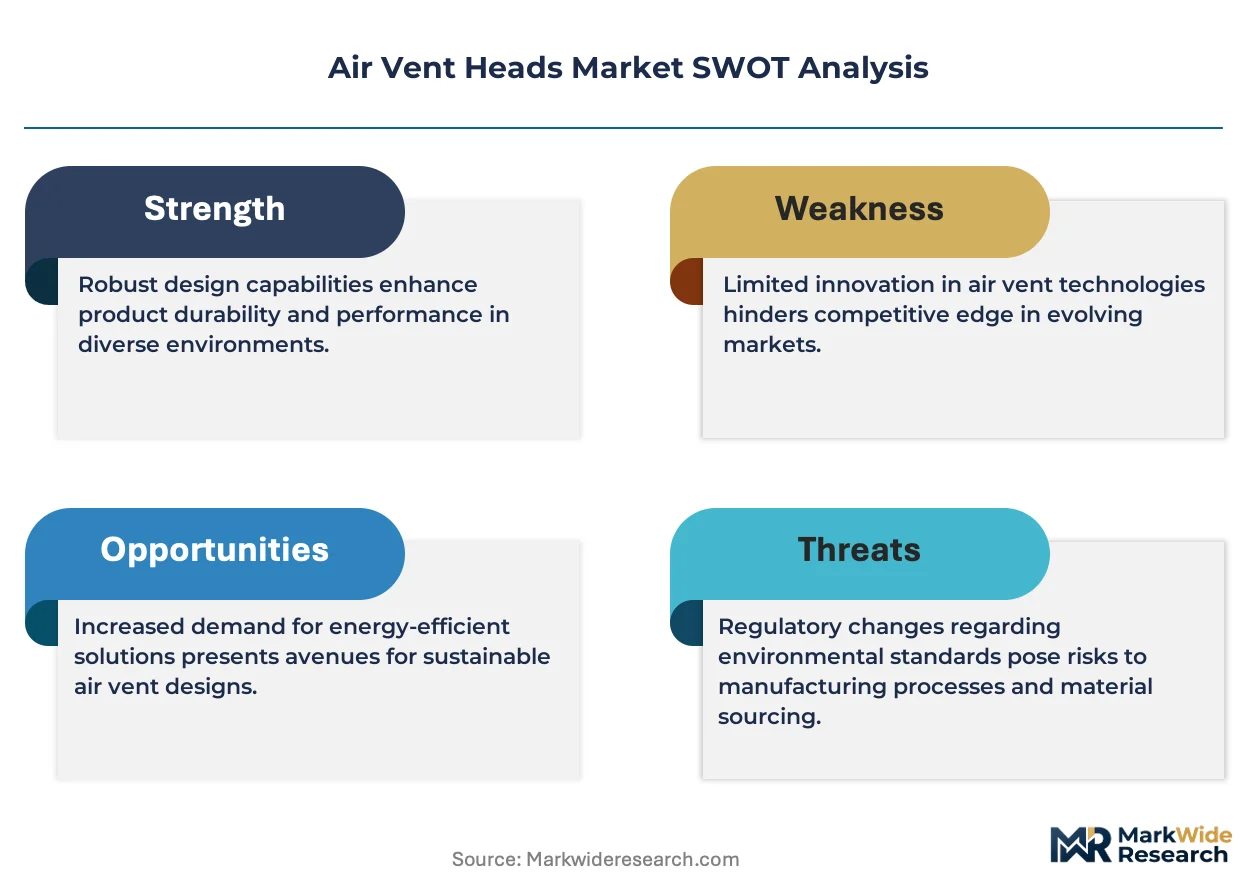
- Aftermarket Service Bundling:HVAC maintenance program integration creates recurring revenue streams from vessel operators seeking unified ventilation system oversight.
- North Pacific Route Specialization:Harsh saltwater corrosion environments on trans-Pacific lanes reward suppliers with advanced coating technologies and extended warranty offerings.
- Backward Integration Into Foundry Operations:Captive supply of critical vent body castings insulates margins from raw material volatility and foundry capacity constraints.
Industry Challenges
- Multi-Jurisdiction Certification Overlap:Japanese METI maritime equipment programs, Korean Register of Shipping requirements, and ABS classification rules create redundant testing burdens for suppliers serving multiple flag registries.
- Legacy Float Mechanism Integration:Automated engine room climate control systems require retrofit compatibility with existing gravity ventilator infrastructure, complicating installation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Vent Heads Market |
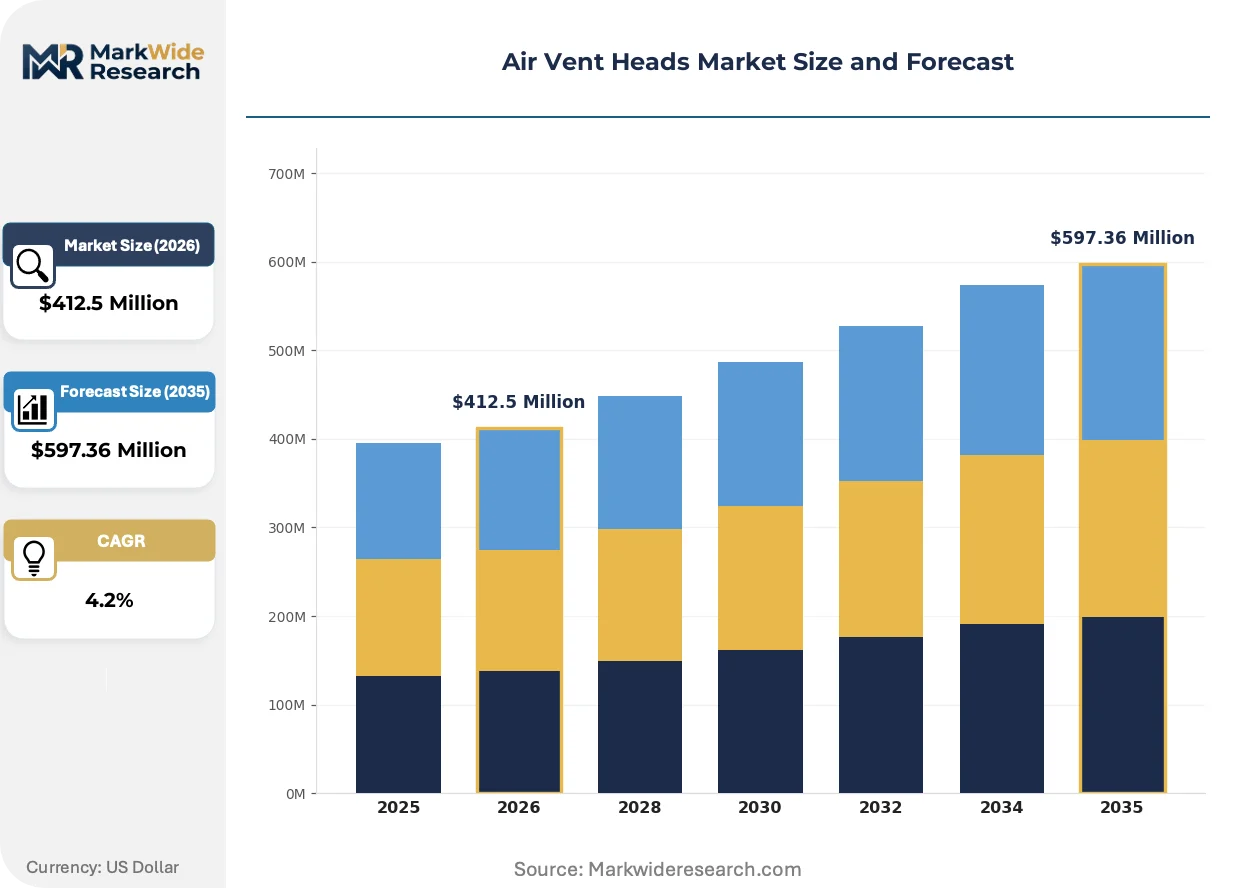
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $597.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Ventilators, Powered Ventilators, Roof Ventilators, Louvers Installation Method: Fixed, Adjustable, Retractable, Modular Material: Plastic, Aluminum, Steel, Copper End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | QINGDAO JIS MARINE VALVE CO LTD, Spirax Sarco, NIIKURA, Soyteknik Shipping and Industry, Blue Sky Marine Machinery CO LTD, MPD Pump Factory Inc, World Heat Ltd, John Gjerde, Jingjiang Sunrises Manufacturing & Trading, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Vent Heads Market Trends and Innovations
Marine ventilation component design is pivoting toward predictive maintenance compatibility and modular replacement architectures. This shift is compressing traditional hardware-only supplier margins while expanding service-contract value capture.
Smart ventilator systems with embedded corrosion sensors and wireless connectivity are expanding into deep-sea tanker and container vessel fleets. Korean and Japanese shipyards are specifying these units on newbuild contracts to reduce unplanned drydock maintenance. The technology is expanding into aftermarket retrofit programs as classification societies begin recognizing sensor data for predictive inspection scheduling.
Japan's METI maritime equipment certification program now mandates material traceability documentation for all pressure-rated ventilation components under revised fire safety protocols. This regulatory tightening is disqualifying uncertified Asian fabricators from domestic shipyard supplier lists. Deep-sea tanker segments face the steepest compliance burden as Korean Register of Shipping aligns with METI documentation standards.
Ship operators are unbundling vent head procurement from vessel construction contracts to negotiate separate lifecycle maintenance agreements. This behavioral shift transfers inventory risk from yards to component suppliers while creating multi-year service revenue streams. The pattern is most visible among Japanese and South Korean container lines operating high-frequency transpacific routes.
Air Vent Heads Market Segmentation
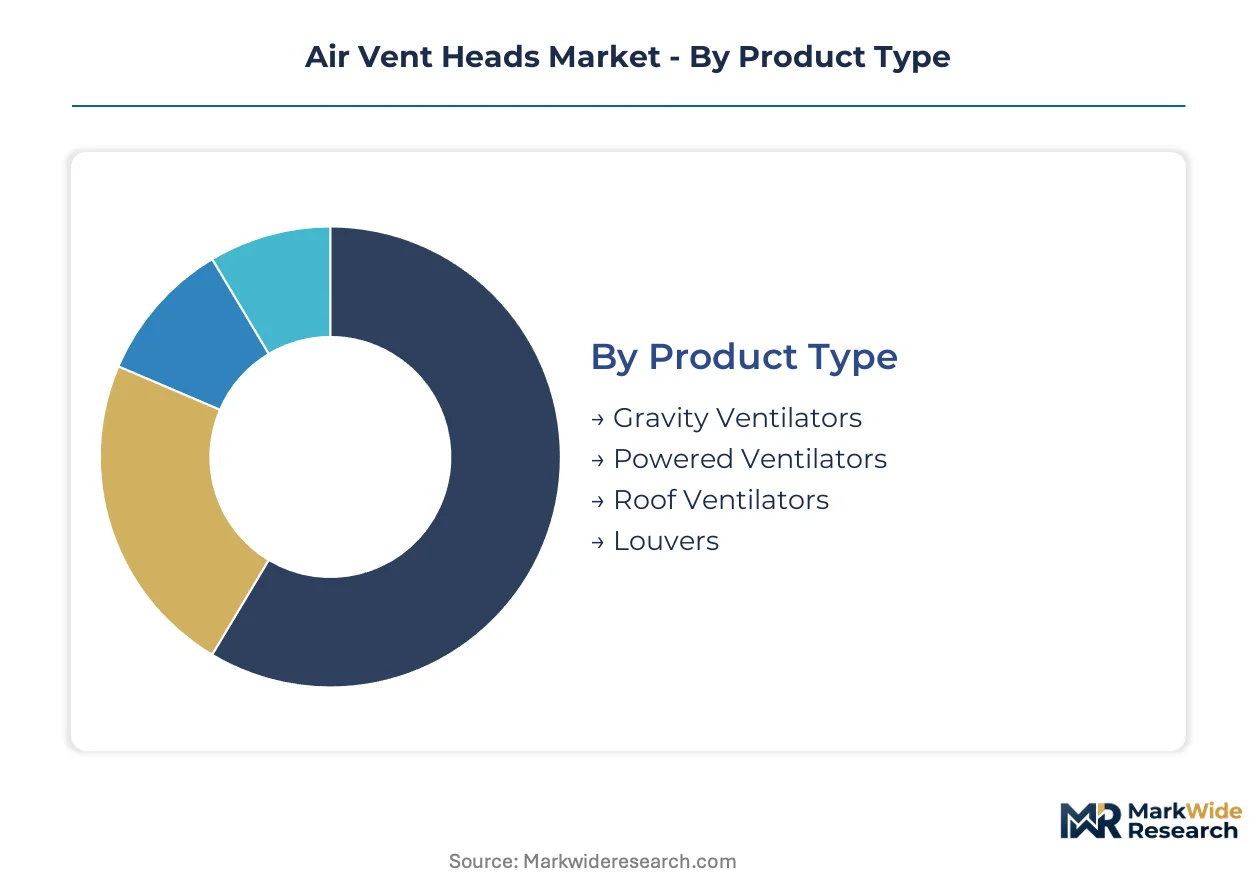
Shipyards and vessel operators select vent head configurations based on classification society rules, engine room automation levels, and route-specific corrosion exposure. Segmentation reveals how procurement splits between passive gravity systems and powered climate control architectures across vessel classes.
Product Type:
Buyers prioritize power dependency and automation compatibility when selecting ventilator architecture for newbuild specifications.
- Gravity Ventilators:Passive float-operated closure mechanisms require zero electrical input and deliver minimal failure rates in salt-laden environments. Deep-sea tanker fleets operating under ABS and DNV classification rules specify these units for redundant safety systems where power loss cannot compromise ventilation integrity.
- Powered Ventilators:Motor-driven airflow systems integrate with vessel management platforms for automated engine room climate control. Korean and Japanese shipyards are specifying these units on newbuild container vessels where HVAC automation reduces crew workload on high-frequency transpacific routes.
- Roof Ventilators:Deck-mounted assemblies with weatherproof housings serve coastal craft and harbor service vessels where vertical exhaust routing simplifies installation.
- Louvers:Fixed-blade directional airflow controls supplement primary ventilator systems in auxiliary machinery spaces with limited headroom.
Volume sits with Gravity Ventilators; growth tilts toward Powered Ventilators.
Installation Method:
Shipyard labor costs and retrofit accessibility determine mounting configuration selection across newbuild and aftermarket channels.
- Fixed:Permanently welded or bolted assemblies dominate deep-sea vessel specifications where structural integrity under SOLAS fire safety protocols is non-negotiable.
- Adjustable:Variable-angle mounting brackets allow airflow redirection without component replacement, concentrating demand in commercial marine segments with changing cargo hold configurations.
- Retractable:Stowable vent heads clear deck space during cargo operations, finding uptake in harbor tugs and offshore supply vessels with multi-role operational profiles.
- Modular:Field-replaceable subassemblies reduce drydock downtime through component-level swaps rather than full unit replacement, expanding in aftermarket maintenance contracts.
Fixed installations capture the largest share; Modular systems are climbing the fastest on lifecycle cost considerations.
Material:
Weight constraints and corrosion resistance requirements split procurement along coastal versus deep-sea operational profiles.
- Aluminum:Lightweight cast and extruded housings reduce topside weight on coastal craft and fast ferries where fuel efficiency prioritizes every kilogram saved. Japanese shipyards specify aluminum vent heads for domestic short-sea routes under METI maritime equipment certification.
- Steel:High-strength cast steel vent bodies withstand pressure ratings and structural loads required by classification society rules for deep-sea tankers and bulk carriers. Korean Register of Shipping documentation standards mandate material traceability for these pressure-rated components.
- Plastic:Composite and polymer housings serve interior ventilation applications with minimal saltwater exposure, concentrating in accommodation spaces and auxiliary machinery compartments.
- Copper:Antimicrobial and corrosion-resistant alloys find limited application in specialized vessel segments with biocidal ventilation requirements.
Steel dominates deep-sea procurement; aluminum is gaining share fastest on coastal fleet renewal cycles.
End User:
Regulatory jurisdiction and operational intensity differentiate buyer requirements across vessel ownership categories.
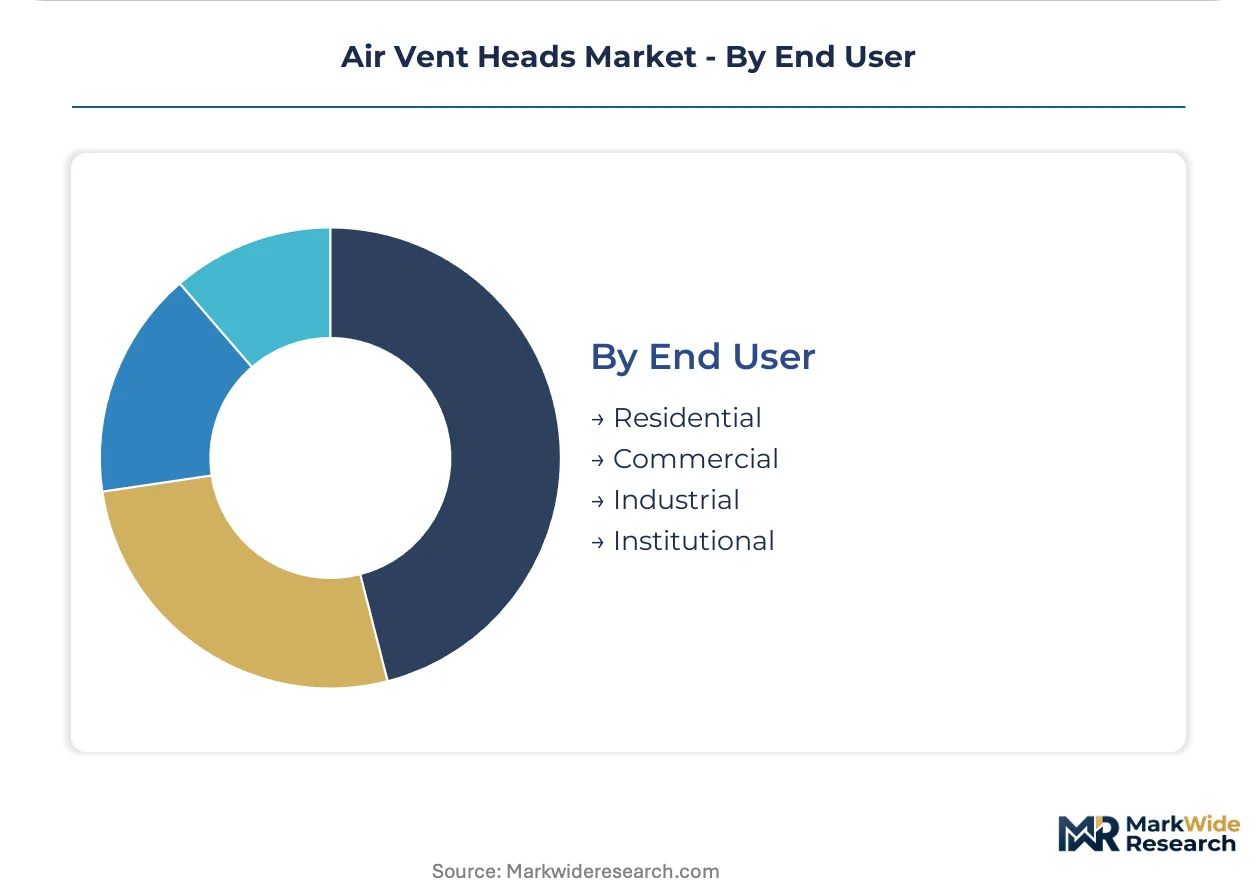
- Commercial:Container lines and bulk operators operating under multiple flag registries drive standardized vent head specifications that satisfy overlapping classification society requirements. South Korean and Japanese container lines are unbundling vent head procurement from construction contracts to negotiate separate lifecycle maintenance agreements.
- Industrial:Offshore supply vessels, tankers, and specialized cargo ships face the steepest compliance burden as IMO ballast water management standards tighten material specifications for marine ventilation components in machinery spaces.
- Residential:Yacht and recreational vessel segments prioritize aesthetic integration and noise reduction over corrosion resistance specifications.
- Institutional:Naval and coast guard fleets impose proprietary technical standards that diverge from commercial classification society rules.
Commercial marine commands the greatest volume; Industrial applications show the steepest expansion trajectory on regulatory compliance upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilding capacity concentrates in East Asian industrial zones while procurement demand distributes across flag registries in Europe and the Americas. Korean and Japanese yards consume corrosion-resistant vent head assemblies at scale. Classification society rules in multiple jurisdictions shape material specification requirements.
South Korea
Busan-Ulsan shipbuilding clusters drive procurement of steel vent bodies for deep-sea tankers under Korean Register of Shipping pressure-testing mandates. The country's national maritime regulator enforces material traceability documentation for SOLAS fire safety compliance. Daegu-Gyeongbuk foundry districts supply cast steel components to domestic yards expanding container vessel output.
Japan
Nagasaki and Kobe industrial zones specify aluminum vent heads for coastal craft and gravity ventilators for redundant safety systems. METI maritime equipment certification requires upgraded material documentation for pressure-rated ventilation components. Yokohama-based container lines unbundle vent head procurement to negotiate separate lifecycle maintenance agreements.
China
Jiangsu and Zhejiang shipyards absorb modular vent head systems for retrofit programs and newbuild automation integration. The Ministry of Industry and Information Technology aligns domestic standards with IMO ballast water management protocols. Dalian and Qingdao port industrial zones concentrate foundry capacity for cast steel vent body production.
Germany
Hamburg and Bremen shipyards source corrosion-resistant assemblies for specialized cargo vessels operating under DNV classification rules. The country's national maritime authority enforces CE marking and pressure equipment directives for machinery space ventilation. North Rhine-Westphalia industrial zones supply engineering services for automated engine room climate control integration.
United States
Gulf Coast repair yards and West Coast container terminals drive aftermarket demand for modular replacement vent head architectures. The Coast Guard enforces SOLAS-aligned fire safety protocols for commercial vessel ventilation components. Pacific Northwest marine clusters specify smart ventilator systems with embedded corrosion sensors for predictive maintenance programs.
Air Vent Heads Market Competitive Landscape
Top-tier vendors anchor premium-tier certification breadth, while mid-scale fabricators compete on foundry integration and coating specialization. The market structures around three tiers: classification society-certified specialists serving deep-sea fleets, backward-integrated foundry operators capturing margin on cast steel components, and regional fabricators supplying coastal craft with aluminum assemblies. Strategic moves concentrate on captive supply of critical vent body castings and aftermarket service bundling with HVAC maintenance programs.
Within the foundry-integrated tier, QINGDAO JIS MARINE VALVE CO LTD anchors Chinese supply capacity through in-house production of cast steel vent body components. Spirax Sarco occupies a position exemplifying service-architecture specialization, leveraging steam system infrastructure to bundle vent head inspections with broader maintenance programs. NIIKURA represents the coating-technology archetype, extending saltwater corrosion resistance for harsh North Pacific route applications.
| Leading Market Players |
|---|
| QINGDAO JIS MARINE VALVE CO LTD |
| Spirax Sarco |
| NIIKURA |
| Soyteknik Shipping and Industry |
| Blue Sky Marine Machinery CO LTD |
| MPD Pump Factory Inc |
| World Heat Ltd |
| John Gjerde |
| Jingjiang Sunrises Manufacturing & Trading |
| Others |
Pricing and Supply Chain Analysis
Automated engine room climate control integration is simultaneously elevating powered ventilator cost structures and concentrating procurement leverage among Korean and Japanese shipyards capable of specifying bundled HVAC-ventilation systems. This technological shift compresses margins for passive gravity ventilator suppliers while rewarding foundry-integrated fabricators with captive casting capacity.
Pricing Analysis
Margin tightening in standard-grade vent heads reflects Korean Register of Shipping pressure-testing mandates extending certification timelines and freezing working capital for smaller fabricators. Three-tier pricing structure across premium, standard, and economy levels splits by certification breadth and foundry integration depth, with Lloyd's Register-certified assemblies commanding substantial premiums over uncertified alternatives. Pricing pressure stems from nickel-alloy input volatility for corrosion-resistant housings. Coastal craft operators exhibit highest price sensitivity, while deep-sea tanker fleets prioritize certification compliance over unit cost.
Supply Chain Analysis
Japan's METI maritime equipment certification program and South Korea's domestic-content preferences for Busan-Ulsan shipyards are reshaping sourcing patterns toward locally verified foundry operations. Critical cast steel vent body production concentrates in China's Jiangsu-Zhejiang industrial zones, South Korea's Daegu-Gyeongbuk districts, and Japan's Nagasaki-Kobe clusters. Raw material dependencies rest on nickel-alloy feedstock, specialized corrosion-resistant coatings, and pressure-rated seal compounds. Single-source vulnerability concentrates in East Asian foundry capacity for ABS and DNV-grade castings. Distribution runs through shipyard-direct procurement channels with growing aftermarket service-contract intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-bundled procurement as IMO ballast water management standards disqualify uncertified fabricators from East Asian shipyard supplier lists.
For Market Incumbents: Lock in captive foundry capacity for critical vent body castings to insulate margins from nickel-alloy volatility and Korean Register of Shipping documentation burdens. Deepen aftermarket service bundling with HVAC maintenance programs to capture recurring revenue from Japanese and South Korean container lines unbundling component procurement from construction contracts. Certification breadth against multiple classification societies remains the essential defensive moat.
For New Entrants and Emerging Players: METI maritime equipment certification program revisions in Japan open a window for specialized coating technology specialists targeting harsh North Pacific route applications. White-space concentrates in smart ventilator retrofit programs for existing deep-sea tanker fleets as classification societies recognize sensor data for predictive inspection scheduling. Target modular replacement architectures for Gulf Coast and Pacific Northwest repair yards seeking drydock downtime reduction.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to marine HVAC consolidators seeking backward-integrated foundry assets. Long-term viability favors fabricators with dual certification coverage across Lloyd's Register and Bureau Veritas standards plus established aftermarket service infrastructure. The signal to watch is classification society recognition of predictive maintenance data for inspection scheduling, which would accelerate smart ventilator retrofit penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive cast steel vent body production insulates margins from Korean foundry capacity constraints. |
| Aftermarket Service Bundling | HVAC maintenance program integration captures recurring revenue from unbundled procurement patterns. |
| Smart Ventilator System Launch | Embedded corrosion sensors align with classification society predictive inspection recognition trends. |
| Specialized Coating Technology Investment | Extended saltwater corrosion resistance addresses harsh North Pacific route warranty requirements. |
| Multi-Jurisdiction Certification Expansion | Dual Lloyd's Register and METI coverage unlocks Japanese and South Korean shipyard supplier status. |
Research Methodology
Independent corroboration across shipyard procurement directors, marine classification society surveyors, and foundry operations managers underwrites the qualitative findings in this study. Primary interviews with HVAC system integrators, aftermarket service contractors, and vessel operators combined with secondary validation from Korean Register of Shipping documentation standards, Lloyd's Register technical bulletins, and IMO ballast water management protocol amendments. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across product type, material grade, and end-use vessel class.
Comparable-period anchoring to historical shipbuilding output and retrofit maintenance cycles structured the projection horizon across the analysis window. Segmentation dimensions modeled include ventilator architecture, installation method, material category, and vessel operational profile. CAGRs derived from shipbuilding orderbook trajectories and regulatory compliance upgrade timelines incorporate nickel-alloy price elasticity assumptions and foundry capacity utilization rates.
The model assumes a particular technology adoption path for powered ventilator integration with vessel management platforms; alternative pathways for gravity ventilator persistence would alter the outlook. Forecasts reflect assumptions regarding classification society alignment on material traceability standards and East Asian shipbuilding cluster concentration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pressure Reducing Valve Market
Valves
Reciprocating Compressor Components Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Europe Medium Voltage Switchgear Market
Valves
Pneumatic Slide Gates Market
Valves
Vacuum Insulated Pipe Market
Valves
Gas Equipment Market
Valves
Emergency Venting System Market
Valves
Vaneometer Market
Valves
Servo Valves Market
Valves
Global Flow Control Market
Valves
Pup Joint Market
Valves
Pipeline Pigging System Market
Valves
Float Traps Market
Valves
Rising Stem Ball Valve Market
Valves
Portable Valve Actuator Market