
 Global CMOS Image Sensors Market | 2026-2036
Global CMOS Image Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global CMOS Image Sensors Market Foresight
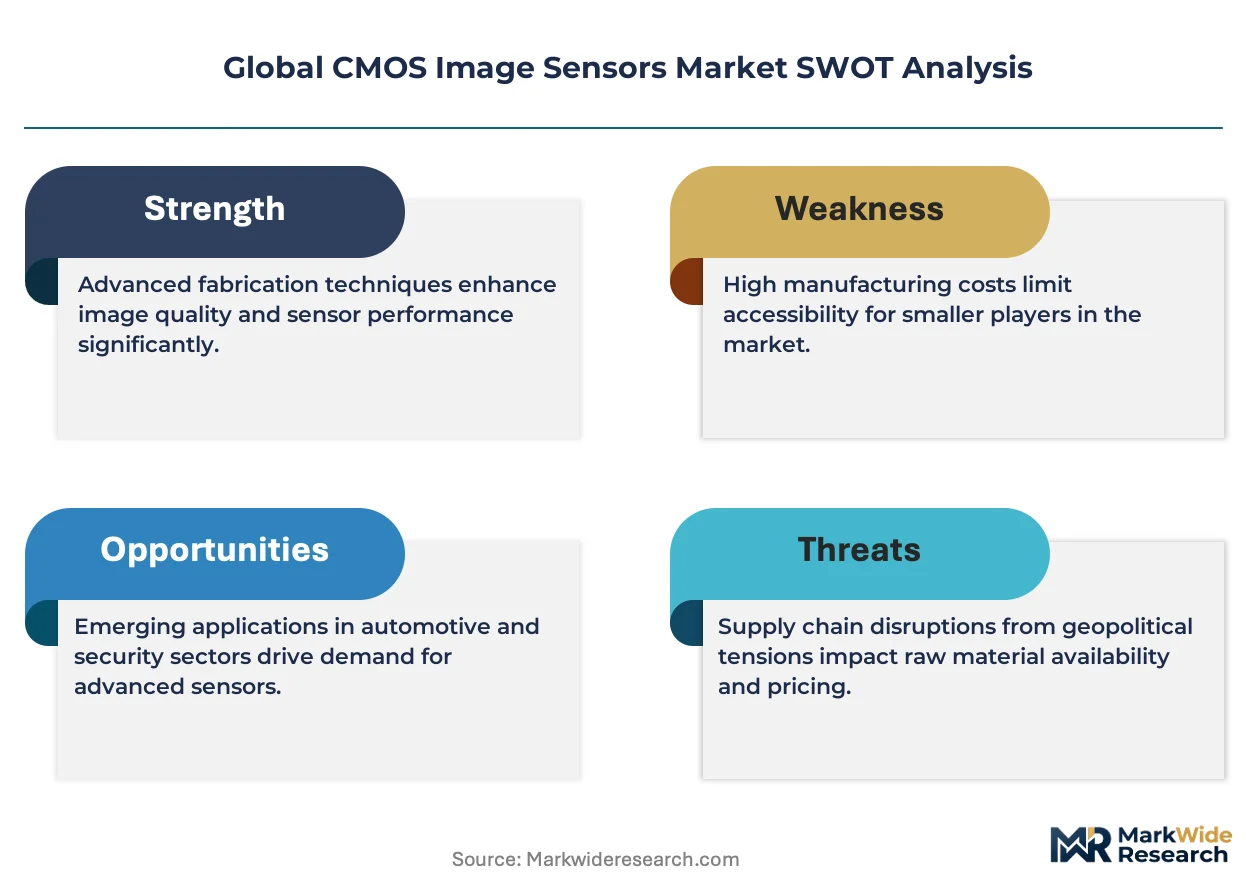
IEC 62676-1 video surveillance certification is reorganizing competitive access for security-grade CMOS suppliers. Sony Group Corporation leverages captive fab capacity to sustain leadership in stacked CMOS architectures. Samsung Electronics Co., Ltd. anchors smartphone supply through vertical control over back-side illuminated wafer processing. OmniVision Technologies, Inc. specializes in compact form factors for automotive ADAS modules, competing against larger integrated rivals.
CMOS image sensors are solid-state electro-optical devices fabricated on silicon substrates using complementary metal oxide semiconductor processes, converting incident photons into digital voltage signals through photodiode arrays with typical pixel pitches ranging below one micron for consumer applications. These devices serve as the primary imaging engines in camera systems spanning mobile terminals, machine vision equipment, and vehicular perception platforms. Back-side illuminated architectures now dominate premium smartphone applications where light sensitivity directly determines low-light capture performance. Stacked CMOS configurations are displacing conventional planar designs in surveillance systems, enabling faster readout speeds that support real-time analytics pipelines. Automotive ADAS represents the fastest-growing application dimension as vehicle integrators mandate higher dynamic range specifications for nighttime object detection.
FDA device classification rules govern medical imaging sensor deployments in the United States, while EU MDR and CE marking requirements shape product qualification cycles for European healthcare providers. ECHA REACH restrictions on cadmium and lead content directly affect die-level metallization choices and packaging material selection across export-bound production lines. RoHS compliance timelines in Europe and parallel substance regulations from China's MEE are forcing foundries to validate alternative solder compositions and passivation layers. Stakeholders must monitor divergence between regional chemical restriction schedules and pixel-scale reliability standards as qualification costs escalate for multi-jurisdiction product families.
Market Dynamics
Automotive ADAS specification escalation is compressing qualification timelines while forcing foundries to reconcile pixel-level performance with ECHA REACH substance restrictions on die-level metallization.
Growth Catalysts
- EU Green Deal emissions standards:Vehicle electrification mandates are accelerating camera module deployment for 360-degree perception systems, expanding sensor counts per vehicle platform.
- Stacked CMOS architectures:Surveillance integrators are adopting faster readout configurations to enable real-time analytics pipelines in smart city deployments.
- China:Domestic smartphone brands and vehicle integrators are scaling local sourcing requirements, concentrating procurement within the country's foundry ecosystem.
Market Restraints
- Silicon wafer input volatility:300mm wafer supply concentration among a limited supplier base creates cost pressure for back-side illuminated processing.
- Sub-0.7 micron pixel pitch limitation:Quantum efficiency degradation at extreme miniaturization creates a technical ceiling for consumer smartphone applications.
- RoHS compliance friction:Divergent substance restriction timelines between EU and China's MEE are forcing duplicate qualification runs for multi-jurisdiction product families.
Strategic Opportunities
- India:PLI scheme incentives for electronics manufacturing are attracting module assembly investments, creating demand for unpackaged die supply.
- Medical imaging convergence:FDA device classification pathways for miniature endoscopic sensors are opening diagnostic applications beyond traditional industrial vision.
- IEC 62676-1 certification:Security-grade video surveillance standards are reorganizing competitive access for qualified CMOS suppliers in European infrastructure tenders.
Industry Challenges
- Multi-jurisdiction chemical compliance:ECHA REACH, RoHS, and China's MEE substance schedules are diverging on cadmium and lead restrictions, escalating validation costs.
- ISO 26262 functional safety:Automotive ADAS qualification timelines for ASIL-rated image sensors are extending development cycles beyond traditional consumer product windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CMOS Image Sensors Market |
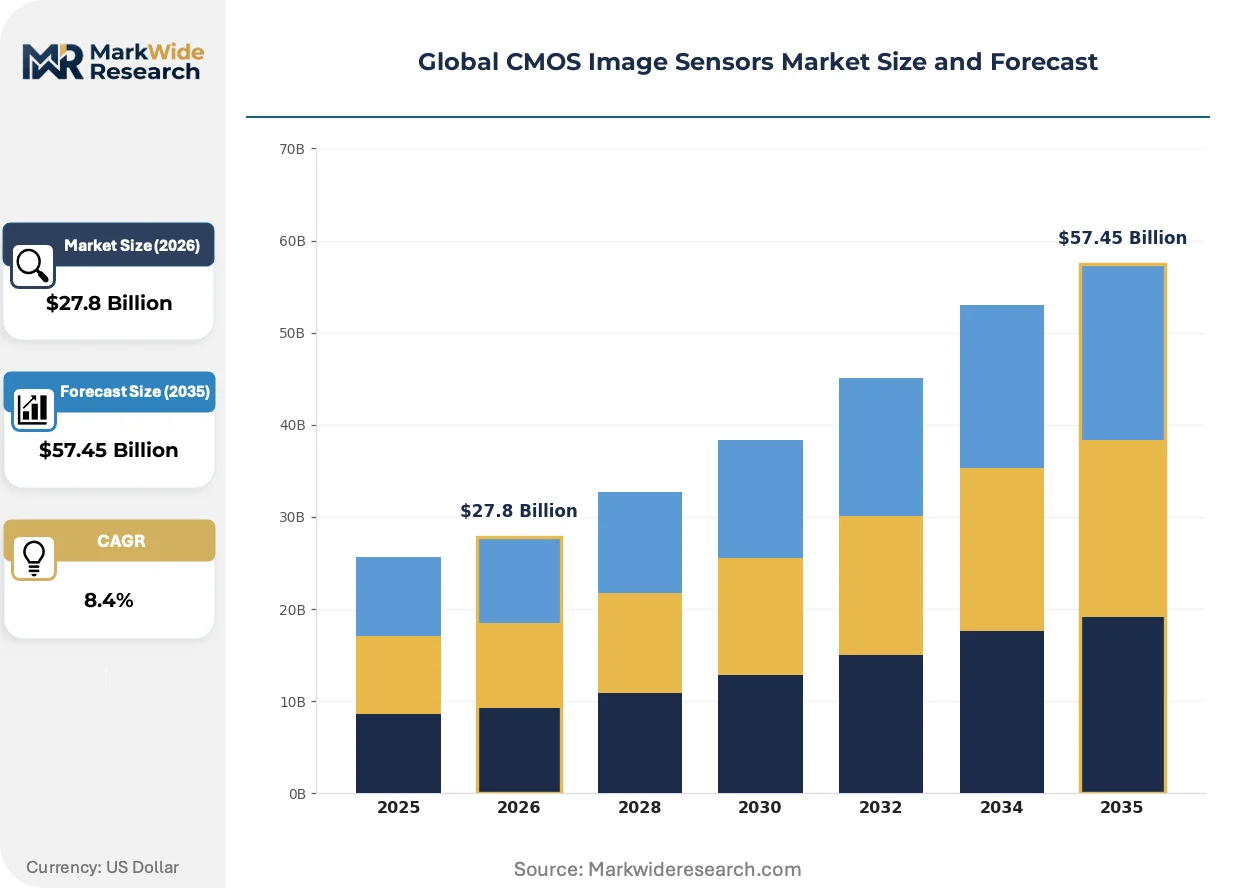
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $57.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front-Side Illuminated, Back-Side Illuminated, Stacked CMOS, 3D CMOS, Global Shutter, Rolling Shutter Application: Smartphones, Surveillance Systems, Automotive ADAS, Industrial Automation, Medical Imaging, Drones Technology: Complementary Metal Oxide Semiconductor, Charge Coupled Device Alternative, Active Pixel Sensor, Digital Signal Processing, Low Light Enhancement, Pixel Binning End User: Consumer Electronics Manufacturers, Security Service Providers, Vehicle Integrators, Manufacturing Plants, Healthcare Providers, Aerial Imaging Companies |
| Companies Covered | Sony Group Corporation, Samsung Electronics Co., Ltd., OmniVision Technologies, Inc., onsemi Corporation, STMicroelectronics N.V., Panasonic Corporation, Canon Inc., GalaxyCore Inc., SK Hynix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CMOS Image Sensors Market Shifts & Advancements
Stacked die configurations and back-side illuminated architectures are compressing form factors while regulatory substance restrictions are forcing material science adaptations across foundry processes.
Global shutter pixel technology is miniaturizing for machine vision applications where motion artifacts must be eliminated. Industrial automation integrators in Germany and Japan are adopting these sensors for high-speed inspection lines. The technology is miniaturizing module footprints while maintaining full-frame capture synchronization, enabling denser camera arrays in compact robotic workspaces.
EU MDR and CE marking requirements are extending product qualification cycles for European healthcare providers deploying CMOS-based diagnostic equipment. FDA parallel classification rules in the United States are creating bifurcated approval pathways that favor established suppliers with dedicated regulatory affairs functions. Medical imaging sensor deployments are consolidating around vendors with dual-jurisdiction certification capabilities.
Certification-driven procurement is displacing specification-only purchasing in security infrastructure tenders. System integrators in France, Germany, and the United Kingdom are prioritizing IEC 62676-1 qualified suppliers over unverified alternatives. This preference shift is most visible in European smart city and critical infrastructure projects where liability exposure drives conservative vendor selection.
Global CMOS Image Sensors Market Segmentation
CMOS image sensor segmentation reveals distinct technology migration patterns across end-use verticals. Architecture choices in one application create spillover effects that reshape competitive positioning in adjacent segments. Understanding these cross-currents illuminates where substitution pressures and margin concentration will concentrate over the forecast window.
Product Type:
Back-side illuminated and stacked architectures are displacing front-side alternatives across premium tiers, while global shutter configurations face emerging pressure from advanced rolling shutter implementations in cost-sensitive machine vision.
- Back-Side Illuminated:Photodiodes positioned at the wafer rear surface capture photons before metal wiring layers obstruct light path. Smartphone manufacturers in China and South Korea specify these sensors for flagship low-light performance, though 300mm wafer supply constraints elevate foundry pricing.
- Stacked CMOS:Pixel and logic layers fabricated on separate wafers then bonded vertically enable faster readout speeds than planar designs. Surveillance integrators in Germany and Japan adopt these for real-time analytics pipelines where latency determines system utility.
- Front-Side Illuminated:Conventional architecture with photodiodes above wiring layers remains viable in cost-optimized consumer applications.
- 3D CMOS:Vertical pixel stacking enables depth sensing for facial authentication and AR applications.
- Global Shutter:Simultaneous full-frame capture eliminates motion artifacts in industrial inspection lines.
- Rolling Shutter:Sequential row readout dominates volume production where absolute synchronization is non-critical.
Back-side illuminated configurations retain volume leadership; stacked CMOS holds the steepest expansion curve.
Application:
Automotive qualification timelines stretch 18-24 months longer than consumer cycles, compressing supplier margins even as per-vehicle sensor counts multiply under EU Green Deal electrification mandates.
- Automotive ADAS:Nighttime object detection specifications demand dynamic range exceeding 120dB for pedestrian identification. Vehicle integrators in Germany and the United States mandate ISO 26262 ASIL-B certification, extending development cycles beyond traditional consumer windows.
- Smartphones:Sub-0.7 micron pixel pitches face quantum efficiency degradation ceilings, forcing foundries to optimize microlens arrays rather than pursue further miniaturization. Chinese OEMs concentrate procurement within domestic foundry ecosystems.
- Surveillance Systems:IEC 62676-1 certification requirements in European infrastructure tenders favor qualified suppliers.
- Industrial Automation:Machine vision integrators prioritize global shutter synchronization for high-speed inspection.
- Medical Imaging:FDA and EU MDR dual-jurisdiction approval pathways favor established vendors with dedicated regulatory functions.
- Drones:Aerial imaging platforms demand compact form factors with stabilization-tolerant readout architectures.
Smartphone procurement retains volume leadership; automotive ADAS commands the steepest expansion trajectory.
Technology:
Active pixel sensor architectures with on-chip integration are accelerating displacement of legacy charge-coupled device alternatives in scientific and industrial imaging.
- Active Pixel Sensor:Each pixel contains its own amplifier, enabling faster readout and lower noise than passive alternatives. Industrial automation integrators in Japan specify these for high-frame-rate inspection where single-photon sensitivity determines defect detection thresholds.
- Low Light Enhancement:Multi-frame stacking and computational algorithms extend usable imaging into near-dark conditions. Security service providers in the United Kingdom deploy these in smart city infrastructure where ambient illumination varies unpredictably.
- Complementary Metal Oxide Semiconductor:Foundry-compatible fabrication enables cost scaling unmatched by specialty processes.
- Charge Coupled Device Alternative:Remains in scientific instruments requiring extreme uniformity.
- Digital Signal Processing:On-chip ISP integration reduces host processor burden in embedded applications.
- Pixel Binning:Adjacent pixel combination trades resolution for sensitivity in low-light scenarios.
Complementary metal oxide semiconductor processes retain volume leadership; low light enhancement features the steepest climb.
End User:
Vehicle integrators and healthcare providers impose the most stringent qualification protocols, segmenting the supplier base between certification-capable incumbents and commodity challengers.
- Vehicle Integrators:Tier-1 automotive suppliers mandate ECHA REACH-compliant metallization and RoHS-validated packaging for export-bound modules. KBA documentation requirements in Germany and NHTSA filings in the United States create dual-jurisdiction validation burdens.
- Healthcare Providers:FDA device classification and EU MDR CE marking extend product qualification cycles. Endoscopic sensor deployments consolidate around vendors with parallel regulatory affairs capabilities in both jurisdictions.
- Consumer Electronics Manufacturers:Smartphone OEMs concentrate procurement in Chinese foundry ecosystems under local sourcing mandates.
- Security Service Providers:European infrastructure tenders prioritize IEC 62676-1 qualified suppliers.
- Manufacturing Plants:Industrial automation buyers specify global shutter synchronization for robotic inspection.
- Aerial Imaging Companies:Drone manufacturers prioritize compact die footprints with vibration-resistant packaging.
Consumer electronics manufacturers retain volume leadership; vehicle integrators show the steepest demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port anchors Asia-Pacific semiconductor logistics, handling wafer shipments for CMOS foundries serving smartphone and automotive module manufacturers across the region.
China
Domestic smartphone OEMs and NEV manufacturers are scaling local sourcing mandates for image sensors. MIIT dual carbon goals and GB standards on electronic substance content are tightening material compliance for export-bound production. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates back-side illuminated wafer processing capacity for flagship mobile applications.
United States
FDA device classification pathways are extending qualification cycles for medical imaging sensor deployments. NHTSA filings for automotive ADAS modules create dual-jurisdiction validation burdens alongside German KBA requirements. The Pacific Northwest and Greater Boston corridors host machine vision integrators specifying global shutter architectures for robotic inspection systems.
Germany
Vehicle integrators mandate ECHA REACH-compliant metallization and ISO 26262 ASIL-B certification for nighttime object detection specifications. EU Green Deal electrification mandates are accelerating camera module deployment for 360-degree perception systems. Bavaria's automotive electronics corridor around Munich anchors Tier-1 supplier engineering centers for stacked CMOS qualification.
Japan
Industrial automation buyers specify high-frame-rate active pixel sensors for defect detection thresholds in robotic workspaces. METI technology roadmaps are guiding foundry investments in low-light enhancement algorithms. The Kanto region around Tokyo concentrates surveillance integrators adopting IEC 62676-1 certified configurations for smart city infrastructure tenders.
South Korea
Smartphone manufacturers specify sub-0.7 micron pixel pitch sensors for flagship low-light performance despite quantum efficiency degradation ceilings. MFDS medical device regulations are parallel-tracking FDA pathways for endoscopic sensor deployments. The Seoul Capital Area anchors vertical control over back-side illuminated wafer processing for captive supply chains.
Global CMOS Image Sensors Market Competitive Landscape
Listed leaders compete with private specialists across certification capabilities and captive fabrication capacity. The vendor base separates between integrated conglomerates with in-house foundry operations and fabless designers reliant on external wafer supply. Three archetypes dominate: vertically integrated semiconductor conglomerates controlling upstream wafer processing, fabless specialists concentrating on compact form factors for automotive modules, and diversified electronics groups leveraging consumer electronics scale. Competitive moves center on backward integration into 300mm wafer supply and strategic partnerships for multi-jurisdiction regulatory certification.
Within the integrated conglomerate tier, Sony Group Corporation and Samsung Electronics Co., Ltd. exemplify players with captive fab capacity sustaining leadership in stacked and back-side illuminated architectures. OmniVision Technologies, Inc. occupies a position among fabless specialists competing on compact form factors for automotive ADAS modules against larger integrated rivals. These three anchors illustrate how competitive positioning diverges between those commanding upstream wafer processing and those optimizing at the design and qualification layer.
| Leading Market Players |
|---|
| Sony Group Corporation |
| Samsung Electronics Co., Ltd. |
| OmniVision Technologies, Inc. |
| onsemi Corporation |
| STMicroelectronics N.V. |
| Panasonic Corporation |
| Canon Inc. |
| GalaxyCore Inc. |
| SK Hynix Inc. |
| Others |
Supply & Pricing Matrix
Inventory cycles of 90-120 days for 300mm silicon wafers concentrate pricing power with foundries in Taiwan and South Korea, while smartphone OEM procurement consolidation in China compresses module-level margins through volume concentration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with ISO 26262 ASIL-B certification and ECHA REACH compliance commanding 15-20% premiums over uncertified alternatives. Price differentiation hinges on qualification grade and captive fab access, with automotive ADAS modules showing lowest price sensitivity due to 18-24 month lock-in periods. Cost compression in consumer smartphone tiers is intensifying because Chinese OEMs are consolidating procurement within domestic foundry ecosystems. Medical imaging sensors exhibit the highest price tolerance, where FDA dual-jurisdiction capabilities justify sustained premiums.
Supply Chain Analysis
Lead-time volatility for specialized 300mm wafers stretches 16-20 weeks during capacity-tight periods, exposing downstream module assemblers to input disruption. Supply concentrates in Taiwan, South Korea, and Japan for front-end wafer processing, with China dominating back-end packaging and module integration. Raw material dependencies center on high-purity silicon substrates, specialized photoresists, and lead-free solder compositions validated under divergent RoHS and MEE substance schedules. Single-source vulnerability pervades EUV lithography equipment for sub-7nm pixel architectures. Distribution runs through Yangtze River Delta hub terminals for Asia-Pacific demand, with dedicated cold-chain logistics for medical-grade sensor shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is recovering from a cyclical trough as automotive electrification mandates under the EU Green Deal restock sensor inventories across German and US vehicle platforms.
For Market Incumbents: Fortify captive 300mm wafer capacity through equipment purchase commitments at foundry partners, locking in allocation before smartphone OEM procurement peaks resume. Deepen ISO 26262 ASIL-D certification pipelines to defend against emerging fabless specialists gaining share in compact automotive modules. Prioritize ECHA REACH-compliant metallization processes to preempt regulatory divergence penalties across export-bound production lines. For New Entrants and Emerging Players: Differentiate on IEC 62676-1 certification acceleration for European security infrastructure tenders, where qualified supplier scarcity creates procurement bottlenecks. Target India's PLI scheme module assembly incentives as the most penetrable geography, supplying unpackaged die to domestic integrators avoiding China sourcing mandates. Pursue hospital system partnerships as the go-to-market angle for miniature endoscopic sensors, leveraging FDA parallel-track filing strategies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics groups with dormant CMOS design teams and existing fab relationships but lacking automotive qualification capabilities. Long-term viability favors vendors bridging consumer scale with medical-grade certification infrastructure over pure-play commodity sensor designers. Watch for inflection signals in German KBA documentation filings, which indicate Tier-1 supplier design-win velocity preceding revenue recognition by 12-18 months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 300mm Wafer Supply | Captive silicon allocation insulates against foundry pricing volatility during demand surges. |
| ISO 26262 ASIL-D Certification Investment | Functional safety qualification opens German automotive Tier-1 procurement channels. |
| IEC 62676-1 Security Standard Qualification | European smart city infrastructure tenders prioritize certified suppliers in vendor selection. |
| India PLI Scheme Module Assembly Partnership | Domestic assembly incentives attract unpackaged die demand from China-averse OEMs. |
| FDA-EU MDR Dual-Jurisdiction Regulatory Buildout | Parallel approval capabilities consolidate medical imaging procurement around established vendors. |
Research Methodology
Operator-level perspectives from foundry process engineers, Tier-1 automotive procurement managers, surveillance system integrators, and medical device regulatory affairs leads anchored the qualitative base. Primary interview insights combined with secondary validation from SEC 10-K filings, MIIT production statistics, ECHA substance restriction updates, and IHS Markit vehicle production databases. Bottom-up sensor shipment modeling and top-down semiconductor equipment capex analysis provided cross-check triangulation.
Sensitivity analysis tested forecast robustness across wafer pricing scenarios, automotive electrification policy acceleration cases, and smartphone replacement cycle variations. Segmentation modeling spanned architecture type, application vertical, certification tier, and regional production cluster dimensions. CAGRs derived from regression against historical foundry utilization rates and content-per-vehicle sensor counts. Industry-specific inputs included ISO 26262 qualification timeline distributions and IEC 62676-1 certification penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt China sourcing mandate relaxation would require recalibration. Forecasts reflect documented assumptions on foundry capacity expansion schedules and automotive platform sensor integration roadmaps. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Small CCTV Camera Market
Imaging
Global Camera Module Market
Imaging
High-Power Objective Lens Market
Imaging
Handheld Imaging Devices Market
Imaging
Semiconductor CD-SEM Systems Market
Imaging
Live Cell Imaging Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Pocket Video Camera Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Camera Technology Market
Imaging
Computer Aided Detection Market
Imaging
Video Microscopes Market
Imaging
Ultraviolet Transilluminator Imaging Systems Market
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Uncooled Infrared Camera Market
Imaging
Camera Accessories Market