
 Mission Critical Communication (MCX) Market | 2026-2036
Mission Critical Communication (MCX) Market Size, Share, and Industry Trends Forecast 2026-2036
Mission Critical Communication (MCX) Market Foresight
REACH compliance is pivoting vendor qualification toward full material disclosure and supply-chain traceability for ruggedized handset assemblies. Motorola Solutions anchors North American public-safety infrastructure through its in-house chip-to-cloud verticality. L3Harris Technologies sustains defense-grade encryption portfolios that dominate military end-user procurement cycles. Nokia Corporation leverages 3GPP standardization leadership to compete in European nationwide public-safety LTE tenders.
Mission Critical Communication denotes interoperable broadband systems engineered to 3GPP Release 16/17 specifications, delivering sub-300-millisecond call setup and priority quality-of-service classes for first-responder coordination during catastrophic infrastructure failure. These systems replace narrowband voice-centric architectures with multimedia group communications, real-time video streaming, and geolocation services essential to unified incident command. Push-To-Talk remains the largest revenue pool across product types, though data services are expanding fastest as agencies integrate IoT sensor feeds and drone telemetry into dispatch workflows. Hybrid network deployment architectures capture widening preference as utilities and transportation operators blend private LTE core assets with commercial roaming for cost-controlled geographic coverage.
The European Telecommunications Standards Institute mandates MCX compliance testing through its MCC (Mission Critical Communications) workgroup, while the FCC governs US 700 MHz Band 14 priority access licensing for FirstNet-eligible entities. Germany's BNetzA and France's ANFR enforce national spectrum carve-outs that shape vendor market-access conditions and domestic partnership requirements. Stakeholders must track 3GPP Release 18 roadmap decisions on ambient IoT integration and satellite-terrestrial convergence as these specifications will determine next-generation platform refresh cycles and incumbent displacement risk.
Market Dynamics
The migration from narrowband TETRA to 3GPP-standardized LTE-MCX infrastructure is compressing vendor margins while expanding total addressable spend across public safety, utilities, and transportation verticals. This technology transition is reshaping procurement patterns toward multi-decade framework agreements.
Growth Catalysts
- Critical Entities Resilience Directive:The European Union's CER Directive mandates broadband interoperability standards for essential service operators, accelerating core network refresh cycles across member states.
- Band 68 Spectrum Allocation:Nordic national regulators in Sweden, Norway, and Finland have carved dedicated 700 MHz frequencies for public protection and disaster relief, enabling guaranteed quality-of-service for first responders.
- Drone Telemetry Integration:Emergency services in Germany and France are embedding unmanned aerial system feeds into dispatch workflows, expanding data service attach rates beyond voice-centric legacy contracts.
Market Restraints
- Semiconductor Supply Concentration:Ruggedized handset assembly depends on constrained gallium nitride foundry capacity concentrated in East Asian contract manufacturers.
- Dual-Network OPEX Burden:Agencies must maintain parallel TETRA and LTE operations during transition windows, straining operational budgets without immediate service decommissioning.
- REACH Material Disclosure:Full supply-chain traceability requirements for flame-retardant polymers and rare-earth magnet content are extending vendor qualification timelines by twelve to eighteen months.
Strategic Opportunities
- Satellite-Terrestrial Convergence:3GPP Release 18 specifications for non-terrestrial network integration will enable coverage extension into remote mining corridors and maritime exclusion zones.
- Hybrid Private-Public Architectures:German utilities and French railway operators are blending captive LTE core assets with commercial roaming for cost-controlled geographic coverage.
- Ambient IoT Sensor Feeds:Integration of low-power wide-area environmental monitors into incident command systems creates new recurring revenue pools for platform vendors.
Industry Challenges
- 3GPP Certification Complexity:Mission-critical push-to-talk compliance testing through ETSI's MCC workgroup requires multi-vendor interoperability validation that extends product launch schedules.
- Legacy System Integration:TETRA console furniture, CAD dispatch software, and recorded audio archives must bridge to IP multimedia subsystems without service interruption during cutover windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mission Critical Communication (MCX) Market |
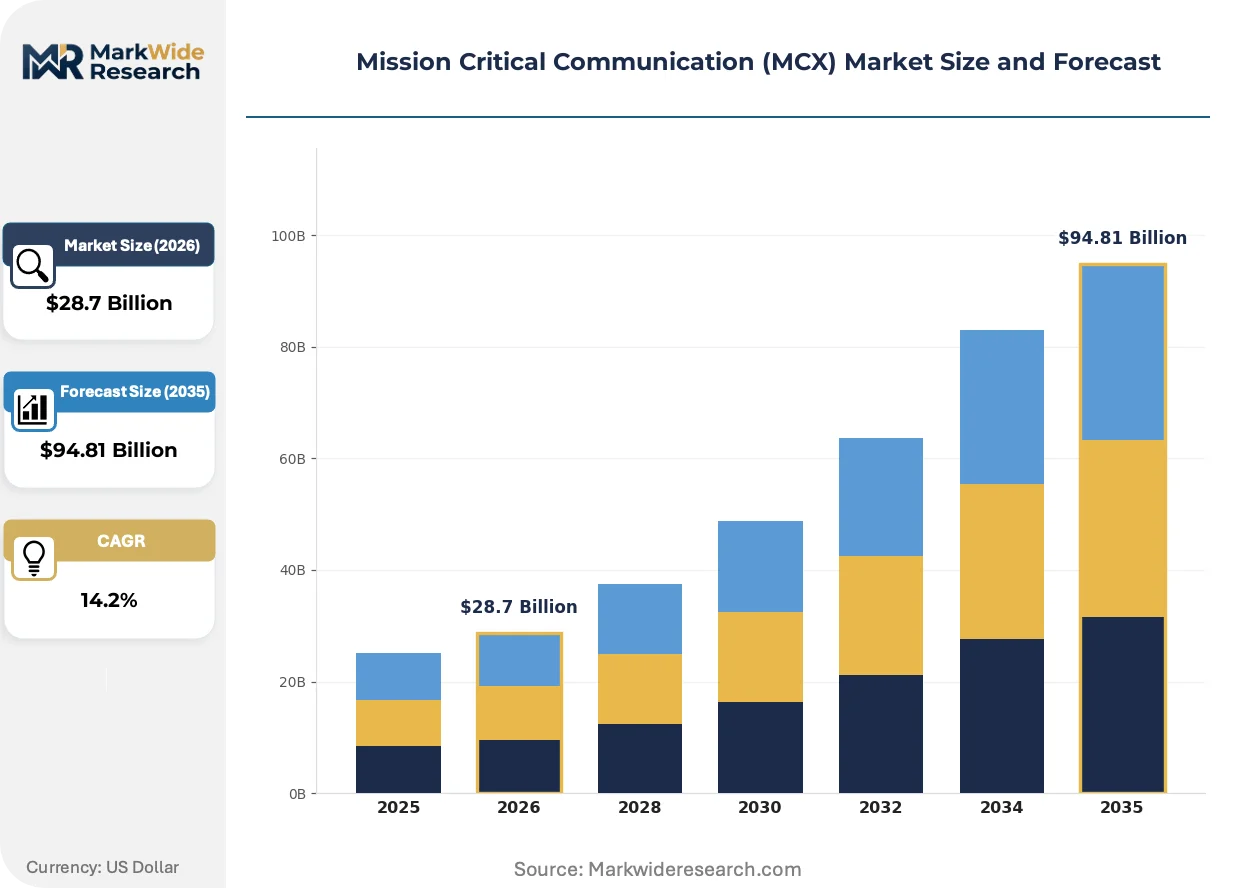
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-To-Talk, Data Services, Video Conferencing, Messaging Services Deployment: Private Network, Public Network, Hybrid Network, Cloud-Based End User: Emergency Services, Transportation, Utilities, Military Technology: LTE, 5G, TETRA, Wi-Fi |
| Companies Covered | Huawei Technologies Co. Ltd., AT&T Inc., Motorola Solutions, Inc., Thales Group, L3Harris Technologies, Inc., Nokia Corporation, ZTE Corporation, Hytera Communications Corporation Limited, Telefonaktiebolaget LM Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mission Critical Communication (MCX) Market Shifts & Advancements
3GPP Release 16/17 feature sets are compressing the technical differentiation window for proprietary narrowband solutions while elevating software-defined core networks as the primary value capture layer.
MCX-compliant group communications is consolidating multimedia incident management around sub-300-millisecond call setup guarantees. German federal police and French gendarmerie units are deploying these capabilities for coordinated counter-terrorism response. The technology is consolidating vendor competitive positions around 3GPP standardization leadership rather than proprietary air-interface intellectual property.
REACH substance restrictions and EECC framework harmonization are forcing material disclosure across ruggedized device supply chains. Industrial consequence includes mandatory full material declaration for flame-retardant housings and battery assemblies. German BNetzA and French ANFR enforcement actions are most directly affecting handset OEM qualification timelines.
Buying committees at Scandinavian public safety agencies are consolidating procurement authority under national framework agreements that span fifteen to twenty-year operational periods. Traditional point-product distributors are losing position to systems integrators with sovereign security clearance. This pattern is most visible in Sweden and Finland where nationwide LTE tenders have concentrated spend among three approved prime contractors.
Mission Critical Communication (MCX) Market Segmentation
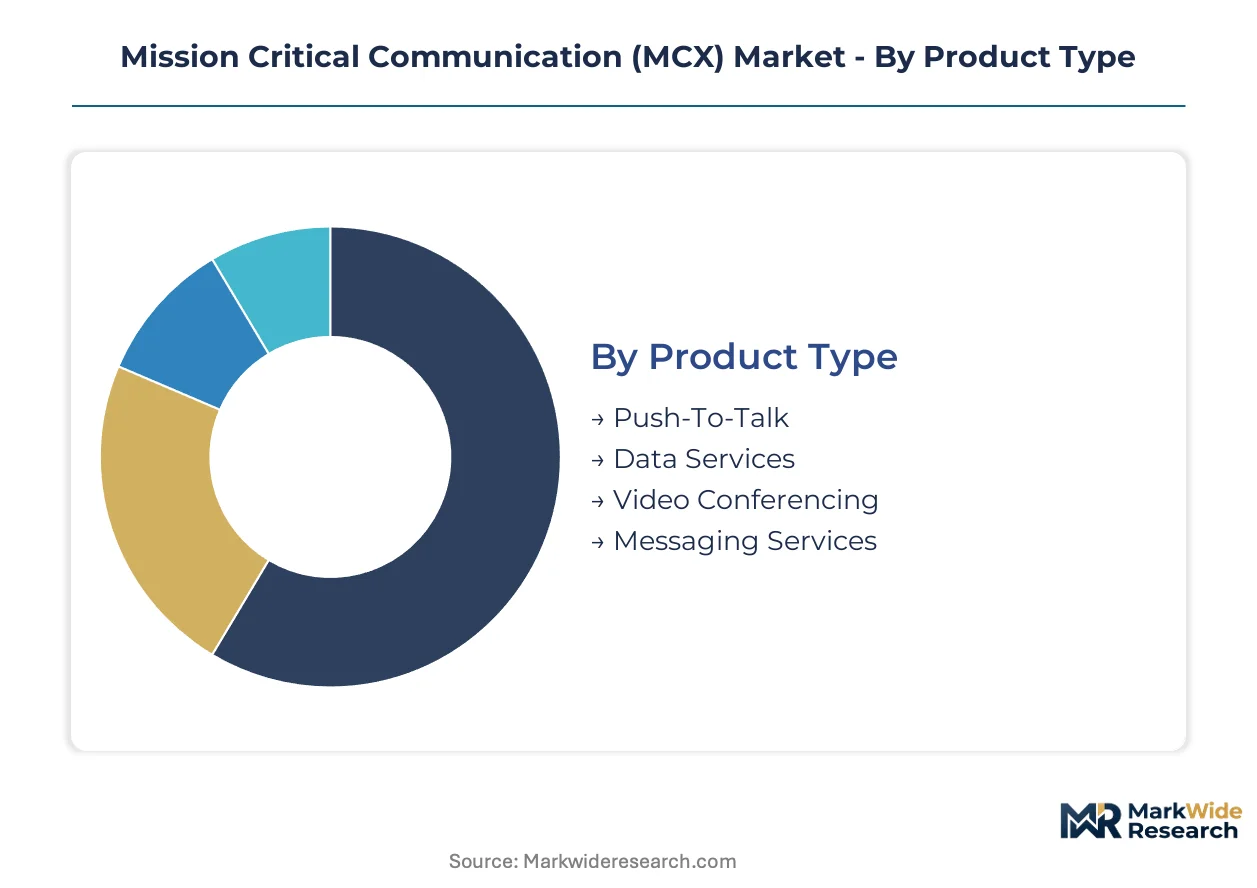
Mission Critical Communication procurement committees evaluate solutions across four intersecting dimensions: product functionality, network architecture, operational context, and underlying radio technology. Each segmentation axis carries distinct compliance burdens and performance benchmarks that reshape vendor competitive positioning.
Product Type:
Budget holders prioritize service reliability metrics and multimedia integration depth when allocating across voice, data, and video capabilities.
- Push-To-Talk:Voice-centric group communication with sub-300-millisecond call setup guarantees under 3GPP Release 16 specifications. German federal police and French gendarmerie units anchor procurement volume for coordinated counter-terrorism response, though attach rates for supplementary data modules are compressing pure-play voice contract values.
- Data Services:IoT sensor integration, drone telemetry feeds, and real-time geolocation streams replacing narrowband dispatch workflows. Scandinavian emergency services in Sweden and Finland are expanding data service attach rates fastest as unmanned aerial systems embed into incident command protocols.
- Video Conferencing:Multimedia group coordination with priority quality-of-service classes for unified incident management during infrastructure failure.
- Messaging Services:Secure text and multimedia messaging with end-to-end encryption for first-responder field coordination.
Push-To-Talk leads on scale; Data Services leads on momentum.
Deployment:
Total cost of ownership calculations dominate architecture selection, with sovereign control requirements competing against coverage extension needs.
- Private Network:Captive LTE core assets with dedicated spectrum assignments ensuring guaranteed quality-of-service for public protection and disaster relief. German utilities and French railway operators favor this model for operational technology isolation from commercial network congestion.
- Hybrid Network:Blended private infrastructure with commercial roaming agreements for cost-controlled geographic coverage extension. Nordic public safety agencies in Norway and Finland are adopting hybrid architectures to bridge urban LTE density with rural satellite backhaul.
- Public Network:Commercial carrier infrastructure with priority access licensing for first-responder traffic classes.
- Cloud-Based:Software-defined core networks with centralized subscriber management and over-the-air feature updates.
Private Network captures the premium tier; Hybrid Network is climbing the fastest.
End User:
Procurement authority concentrates differently across verticals, with sovereign security clearance requirements filtering vendor access.
- Emergency Services:Police, fire, and medical response units requiring sub-300-millisecond call setup for catastrophic infrastructure failure scenarios. National framework agreements in Sweden and Finland spanning fifteen to twenty-year operational periods are consolidating spend among approved prime contractors.
- Transportation:Railway operators and aviation authorities mandating seamless handoff across geographic coverage boundaries. French SNCF and German Deutsche Bahn are blending captive LTE assets with commercial roaming for corridor-specific quality-of-service guarantees.
- Utilities:Grid operators and pipeline controllers prioritizing operational technology isolation from public internet exposure.
- Military:Defense-grade encryption portfolios with multi-level security clearance requirements dominating procurement cycles.
Emergency Services leads on scale; Transportation leads on momentum.
Technology:
Migration timelines and interoperability certification burdens shape technology commitment horizons.
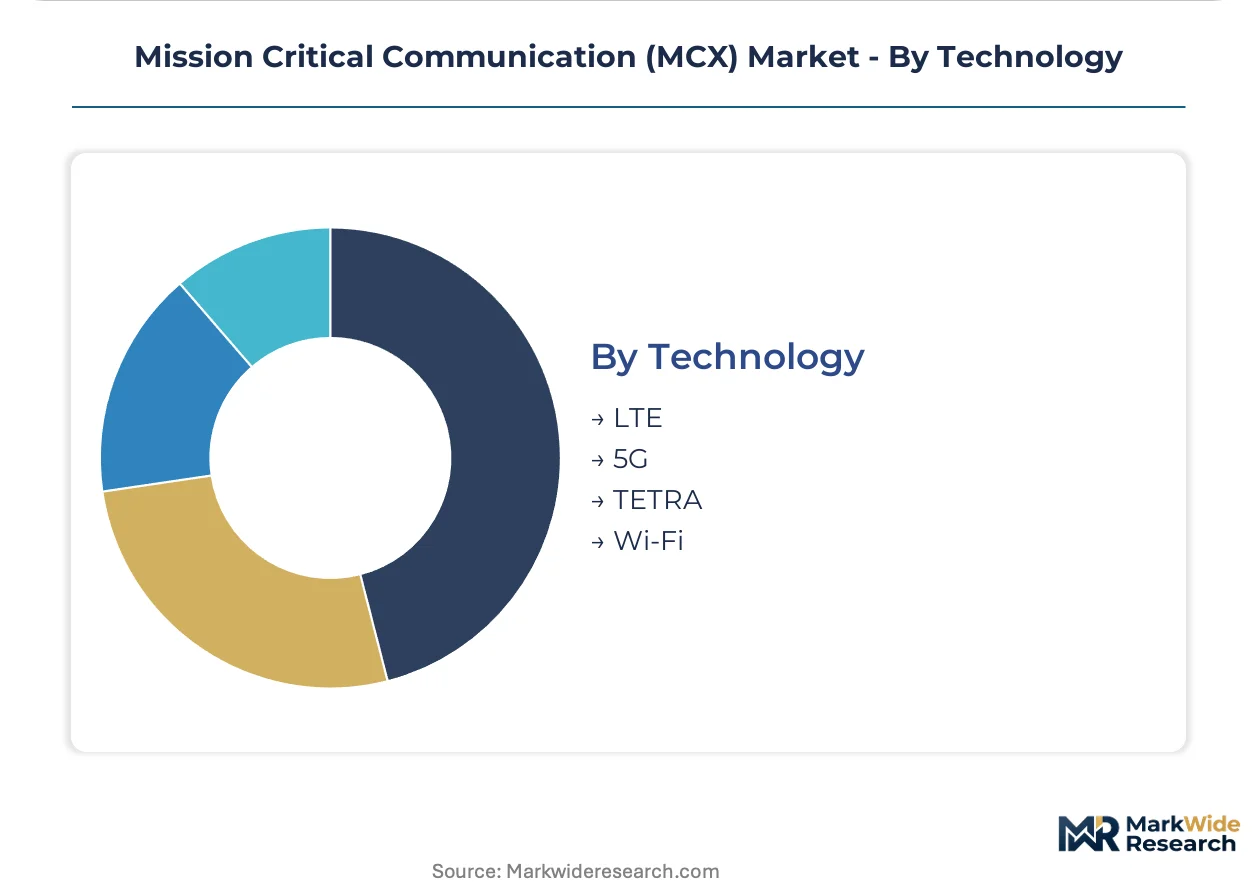
- LTE:3GPP-standardized broadband mission-critical services replacing narrowband voice-centric architectures across European public safety agencies. ETSI's MCC workgroup mandates compliance testing that extends product launch schedules for multi-vendor interoperability validation.
- 5G:Next-generation radio access with ultra-reliable low-latency communication for autonomous system coordination. Release 18 roadmap decisions on ambient IoT integration will determine platform refresh cycles for early adopters.
- TETRA:Legacy narrowband voice systems maintained in parallel during transition windows, straining operational budgets without immediate decommissioning.
- Wi-Fi:Localized broadband offload for indoor coverage supplementation and cost-controlled facility communications.
LTE leads on scale; 5G leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers specializing in 3GPP standardization and public-safety network architecture concentrate procurement authority in national capitals and industrial corridors across Germany, the United States, the United Kingdom, France, and the Nordic region.
Germany
Federal police modernization and Deutsche Bahn corridor upgrades drive MCX infrastructure demand. BNetzA enforces national spectrum carve-outs that shape vendor market-access conditions. Munich and Berlin host the dominant systems integrators managing nationwide LTE tender awards.
United States
FirstNet-eligible entities and state-level emergency management agencies anchor procurement volume. FCC governs 700 MHz Band 14 priority access licensing for public-safety broadband. The Washington-Boston corridor concentrates prime contractor headquarters and federal interoperability testing facilities.
United Kingdom
Home Office-led Emergency Services Network migration compresses legacy TETRA replacement timelines. Ofcom spectrum policy aligns with EECC framework harmonization for critical communications resilience. London and the West Midlands cluster systems integration expertise for nationwide deployment.
France
Gendarmerie counter-terrorism coordination and SNCF railway safety mandates expand multimedia group communications requirements. ANFR enforces domestic partnership requirements through national spectrum assignments. Paris and Lyon anchor the vendor qualification and certification testing ecosystem.
Nordic Region
Swedish and Finnish nationwide framework agreements spanning fifteen to twenty years consolidate spend among approved prime contractors. National regulators in Sweden, Norway, and Finland have allocated dedicated Band 68 frequencies for public protection. Stockholm and Helsinki serve as the procurement decision centers for hybrid satellite-terrestrial architectures.
Mission Critical Communication (MCX) Market Competitive Landscape
The competitive structure tilts toward diversified communications conglomerates with sovereign security clearances. Vendor positioning concentrates around 3GPP standardization leadership, defense-grade encryption portfolios, and captive chip-to-cloud verticality. Three archetypes dominate: infrastructure equipment specialists with cellular R&D heritage, integrated safety-communications platforms with public-safety installed bases, and defense contractors with classified-systems expertise. Capacity expansion into software-defined core networks and strategic partnerships for satellite-terrestrial convergence represent the primary competitive vectors reshaping procurement outcomes.
Among diversified communications conglomerates, Huawei Technologies Co. Ltd. and Nokia Corporation exemplify infrastructure-centric positioning anchored to 3GPP release roadmaps. Motorola Solutions, Inc. occupies a distinctive tier through its integrated safety-communications platform spanning devices through network cores. L3Harris Technologies, Inc. represents the defense-contractor archetype with multi-level security clearance requirements filtering access to military end-user segments. These three patterns illustrate how procurement authority migrates toward entities combining standardization influence with sovereign trust credentials.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| AT&T Inc. |
| Motorola Solutions, Inc. |
| Thales Group |
| L3Harris Technologies, Inc. |
| Nokia Corporation |
| ZTE Corporation |
| Hytera Communications Corporation Limited |
| Telefonaktiebolaget LM Ericsson |
| Others |
Supply & Pricing Matrix
Multi-decade framework agreements consolidating procurement authority under Scandinavian national governments are forcing vendors toward unbundled service pricing and extended warranty structures that compress upfront hardware margins while securing recurring revenue streams.
Pricing Analysis
Bundled network infrastructure contracts versus unbundled software-as-a-service modules define the dominant pricing split across European public safety tenders. Three-tier pricing structure across mission-critical, business-critical, and standard service levels differentiates offerings based on 3GPP certification grade and guaranteed call-setup latency. Cost compression in device hardware is intensifying because REACH material disclosure requirements extend vendor qualification timelines. Transportation operators exhibit the highest price sensitivity due to corridor-specific coverage economics, while military end-users accept premium positioning for defense-grade encryption portfolios.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for gallium nitride foundry capacity essential to ruggedized handset RF front-ends. MCX infrastructure assembly draws from German precision component suppliers, Chinese battery cell manufacturers, and Japanese ceramic substrate providers. Tariff exposure on rare-earth magnet imports from China creates procurement risk for flame-retardant housing assemblies. Distribution runs through sovereign-cleared systems integrators rather than traditional point-product distributors, particularly in Sweden and Finland where national framework agreements concentrate authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mission Critical Communication market functions as a stable compounder anchored by irreversible broadband migration mandates under the EU Critical Entities Resilience Directive and equivalent regulatory frameworks across NATO member states.
For Market Incumbents: Anchor competitive position through captive chip-to-cloud verticality that insulates against gallium nitride foundry bottlenecks. Deepen software-defined core network capabilities to capture value migration from proprietary air-interface hardware. Counter emerging cloud-native entrants by leveraging sovereign security clearance relationships with German BNetzA and French ANFR regulators.
For New Entrants and Emerging Players: Begin with ambient IoT sensor integration modules that attach to existing LTE-MCX infrastructure without requiring full network core certification. Target German utilities and French railway operators adopting hybrid private-public architectures where incumbent lock-in remains incomplete. Pursue partnership-based go-to-market positioning with established systems integrators holding national framework agreement eligibility.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized software-defined core network developers possessing 3GPP Release 18 roadmap influence but lacking device manufacturing scale. Long-term viability rests on satellite-terrestrial convergence capabilities that extend coverage into maritime and remote mining corridors. Monitor 3GPP Release 18 standardization decisions on non-terrestrial network integration as the primary inflection signal for platform refresh cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Core Network Investment | Captures value migration from proprietary hardware toward centralized subscriber management and over-the-air feature deployment. |
| Satellite-Terrestrial Convergence Partnership | Extends guaranteed quality-of-service coverage into Norwegian maritime zones and Finnish Arctic corridors beyond terrestrial LTE density. |
| REACH Compliance Certification Program | Accelerates vendor qualification timelines with German BNetzA and French ANFR through pre-validated material disclosure documentation. |
| Hybrid Network Architecture Deployment | Blends captive LTE assets with commercial roaming for Deutsche Bahn and SNCF corridor-specific quality-of-service economics. |
| Ambient IoT Integration Development | Creates recurring revenue pools through low-power wide-area environmental sensor feeds embedded in Swedish incident command protocols. |
Research Methodology
Bottom-up public safety agency procurement modeling reconciled against top-down infrastructure vendor shipment tracking forms the analytical core of this study. Primary interviews with network architects at German federal police, French gendarmerie procurement officers, and Swedish systems integrators were validated against ETSI MCC workgroup certification records, BNetzA spectrum allocation filings, ANFR tender documentation, and 3GPP Release 16/17 implementation timelines.
Historical technology migration patterns from TETRA to LTE-MCX established baseline penetration curves across the analysis window. Segmentation modeling incorporated product type, deployment architecture, end-user vertical, and radio technology dimensions alongside country-specific regulatory framework clusters. CAGRs were derived from installed base replacement cycles, framework agreement award schedules, and spectrum allocation timelines rather than extrapolated growth rates.
Several conditions sit outside the modeled scope, including geopolitical disruption of gallium nitride foundry supply, accelerated 5G standalone adoption timelines, and unilateral national security exclusions affecting vendor eligibility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G MVNO Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
5G Core Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
Iran Telecom Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Global Telecommunication Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Global Esim Market
Telecommunications
Global LTE Market
Telecommunications
Managed M2M Services Market
Telecommunications
Philippines Telecom Market