
 Global Telecommunication Market | 2026-2036
Global Telecommunication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telecommunication Market Outlook
Enterprise-grade service tiering is unwinding legacy revenue models across the Global Telecommunication Market. Verizon leverages its fiber depth to sustain premium positioning in northeastern US corridors. Deutsche Telekom anchors European 5G rollout through network densification and spectrum discipline. China Mobile dominates subscriber scale across its domestic footprint while extending infrastructure into Belt and Road corridors.
Telecommunication encompasses the transmission of voice, data, and video across wired and wireless infrastructure using electromagnetic spectrum, optical fiber, and satellite relay systems operating at frequencies from sub-1 GHz to millimeter-wave bands. Its primary purpose is enabling real-time information exchange for commercial operations, public administration, and personal connectivity. Mobile services generate the largest revenue pool among service types, while 5G deployment within the technology dimension captures the fastest capital allocation as carriers replace 4G core networks. Fiber optics sustains the highest margin profile due to lower maintenance intensity and superior latency performance versus legacy copper infrastructure.
The FCC governs spectrum allocation and net neutrality principles in the United States, directly shaping carrier investment timelines and service pricing flexibility. EMA and national regulators across Europe enforce cybersecurity and data sovereignty requirements under GDPR and the EU AI Act, tightening compliance costs for cross-border operators. China's MIIT coordinates 5G base station targets and domestic equipment sourcing rules, influencing vendor selection across Asia-Pacific deployments. Stakeholders must monitor spectrum auction calendars and equipment certification timelines to align capital deployment with regulatory windows.
Market Dynamics
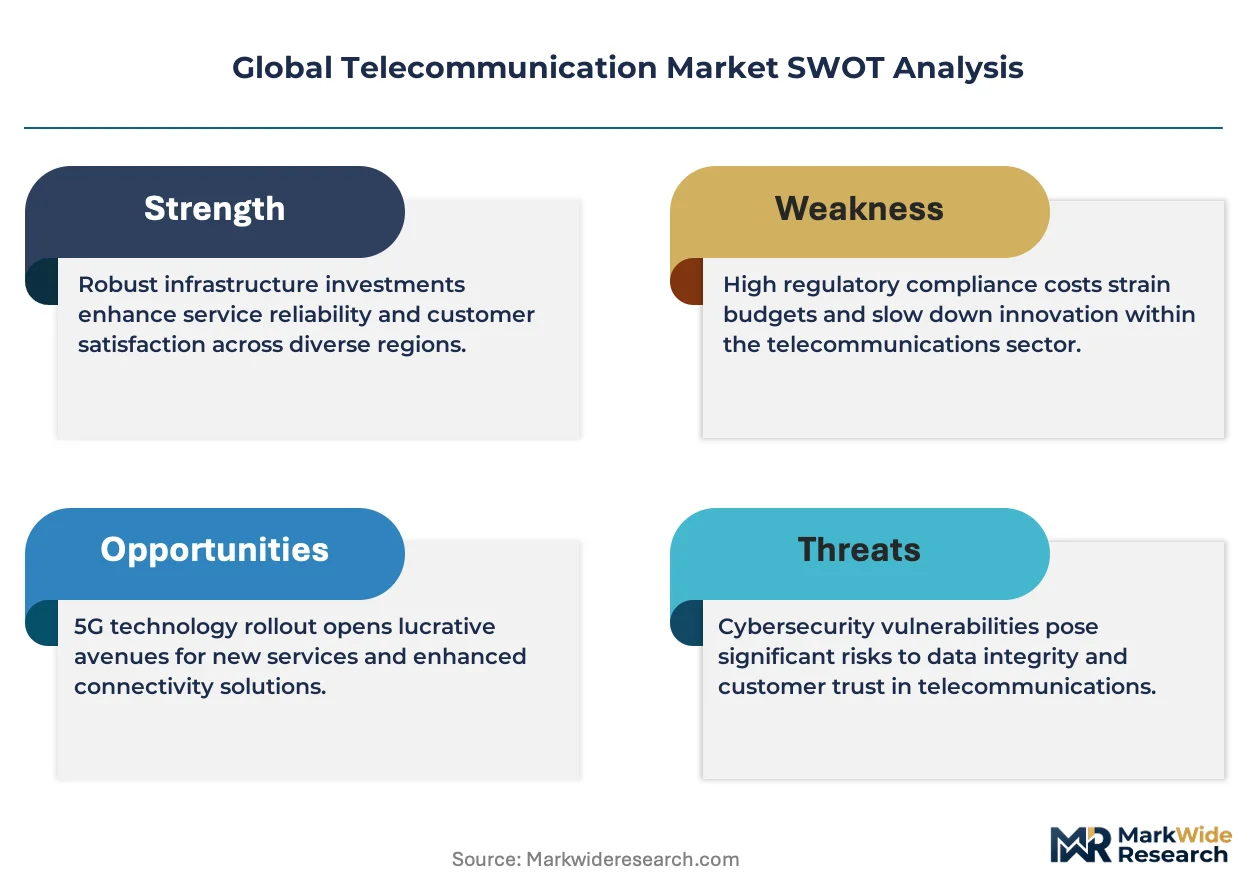
Enterprise cloud connectivity adoption is compressing legacy voice revenue streams while forcing carriers to rearchitect fiber and 5G core networks for latency-sensitive workloads. Spectrum scarcity and the EU AI Act's infrastructure requirements are simultaneously tightening capital deployment windows across major economies.
Growth Catalysts
- 5G Network Densification:Carriers in India are deploying massive MIMO arrays to support industrial IoT and smart city backbones. TRAI's spectrum harmonization rules accelerate base station permitting timelines.
- GDPR-Driven Edge Computing:Data sovereignty mandates force European enterprises to localize processing. This pulls fiber investment into secondary cities and enterprise campus networks.
- Fiber-to-the-Home Mandates:National broadband targets in multiple jurisdictions require copper replacement. Government subsidy programs de-risk last-mile deployment economics for infrastructure investors.
Market Restraints
- Millimeter-Wave Propagation Limits:5G signals above 24 GHz degrade rapidly through physical obstacles. Dense urban environments require 3-4x more small cells than sub-6 GHz alternatives.
- Optical Component Concentration:Laser diode and coherent DSP supply concentrates among East Asian foundries. Geopolitical friction threatens equipment delivery timelines for Western carriers.
- EU AI Act Compliance Burden:Telecommunication infrastructure classified as high-risk AI systems faces mandatory conformity assessments. Certification costs and documentation requirements extend deployment cycles.
Strategic Opportunities
- Rural Broadband Gaps:India's BharatNet program and comparable initiatives in Brazil and Indonesia create addressable subscriber pools outside saturated urban markets. Low-ARPU economics require shared infrastructure models.
- Network API Monetization:5G standalone cores expose latency, bandwidth, and location capabilities to application developers. This creates developer ecosystem revenue adjacent to connectivity pipes.
- Satellite-Cellular Convergence:Low-earth orbit constellations integrate with terrestrial 5G cores. Direct-to-device messaging and emergency coverage extend carrier service portfolios without spectrum investment.
Industry Challenges
- Legacy Billing System Migration:Decades-old BSS/OSS architectures resist API-native service orchestration. Carriers face multi-year transformation timelines to support dynamic network slicing.
- Radio Frequency Engineer Scarcity:Specialized talent for massive MIMO optimization and interference management commands premium compensation. Training pipelines lag deployment targets in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecommunication Market |
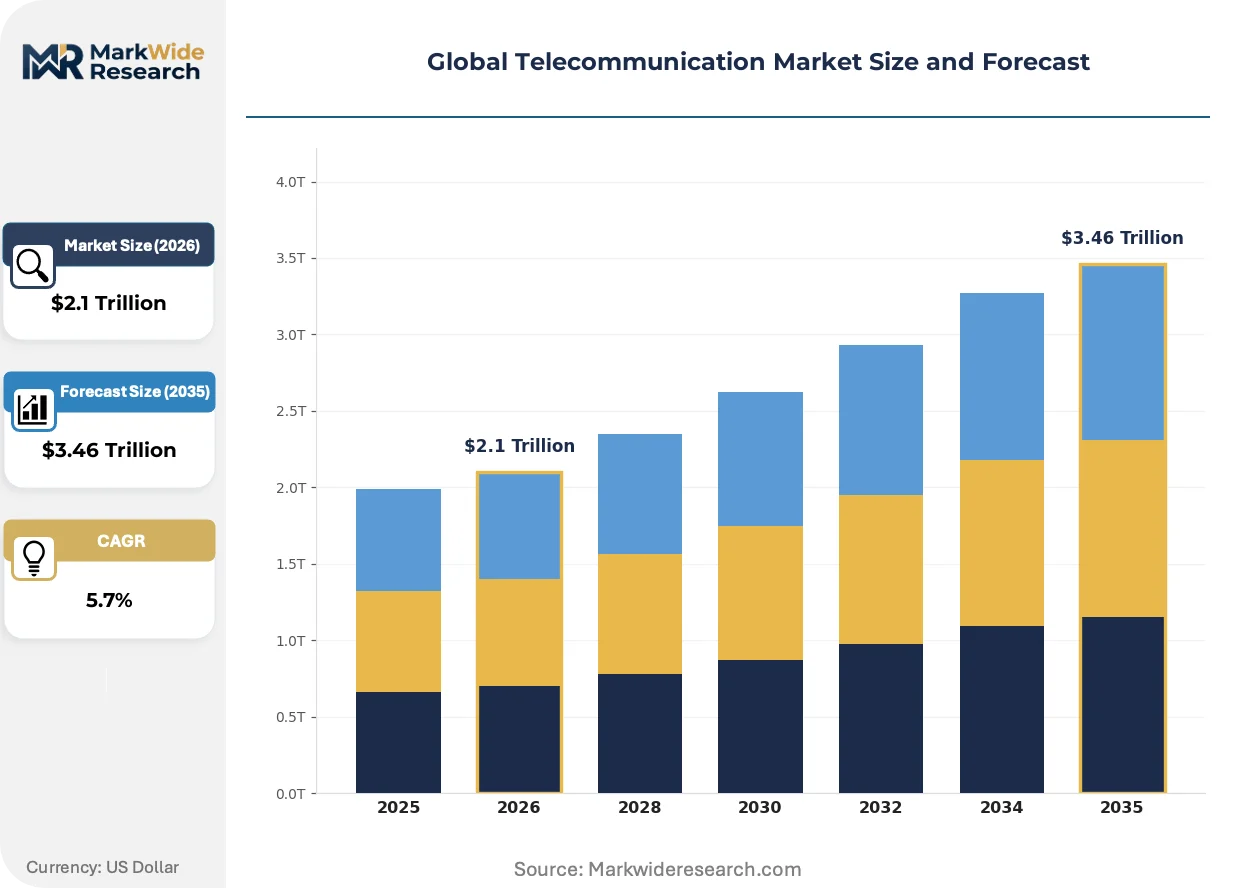
| Market Size in 2026 | $2.1 Trillion |
| Market Size in 2035 | $3.46 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed Broadband, VoIP, IPTV Technology: 4G, 5G, Fiber Optics, Satellite End User: Residential, SMEs, Large Enterprises, Government Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services |
| Companies Covered | China Mobile, Verizon, AT&T, Deutsche Telekom, China Telecom, Nippon Telegraph and Telephone, China Unicom, Vodafone, Telefónica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecommunication Market Strategic Shifts
Open radio access network architectures are fragmenting vendor lock-in patterns while forcing incumbent equipment suppliers to disaggregate hardware and software portfolios. This shift restructures procurement evaluation criteria across carrier technology functions.
Massive MIMO antenna arrays are miniaturizing through advanced gallium nitride power amplifiers and integrated RF front-ends. Rural carriers in India and Indonesia adopt compact 64T64R units for simplified tower loading and reduced site preparation costs. The technology is miniaturizing deployment footprints, enabling faster rollout in markets with limited civil infrastructure and restrictive zoning.
The EU AI Act's high-risk system classification applies directly to network management automation and predictive maintenance algorithms. European carriers must implement human oversight mechanisms and algorithmic transparency documentation. German and French operators are front-loading compliance investments ahead of enforcement timelines, prioritizing vendor contracts with pre-certified AI components.
Enterprise buyers are consolidating connectivity procurement through managed service aggregators rather than direct carrier relationships. Financial services and manufacturing verticals favor single-source accountability for multi-site WAN, cloud access, and security stacks. This pattern is most pronounced in the United States, where Fortune 500 technology procurement teams negotiate framework agreements spanning three to five-year horizons.
Global Telecommunication Market Segmentation
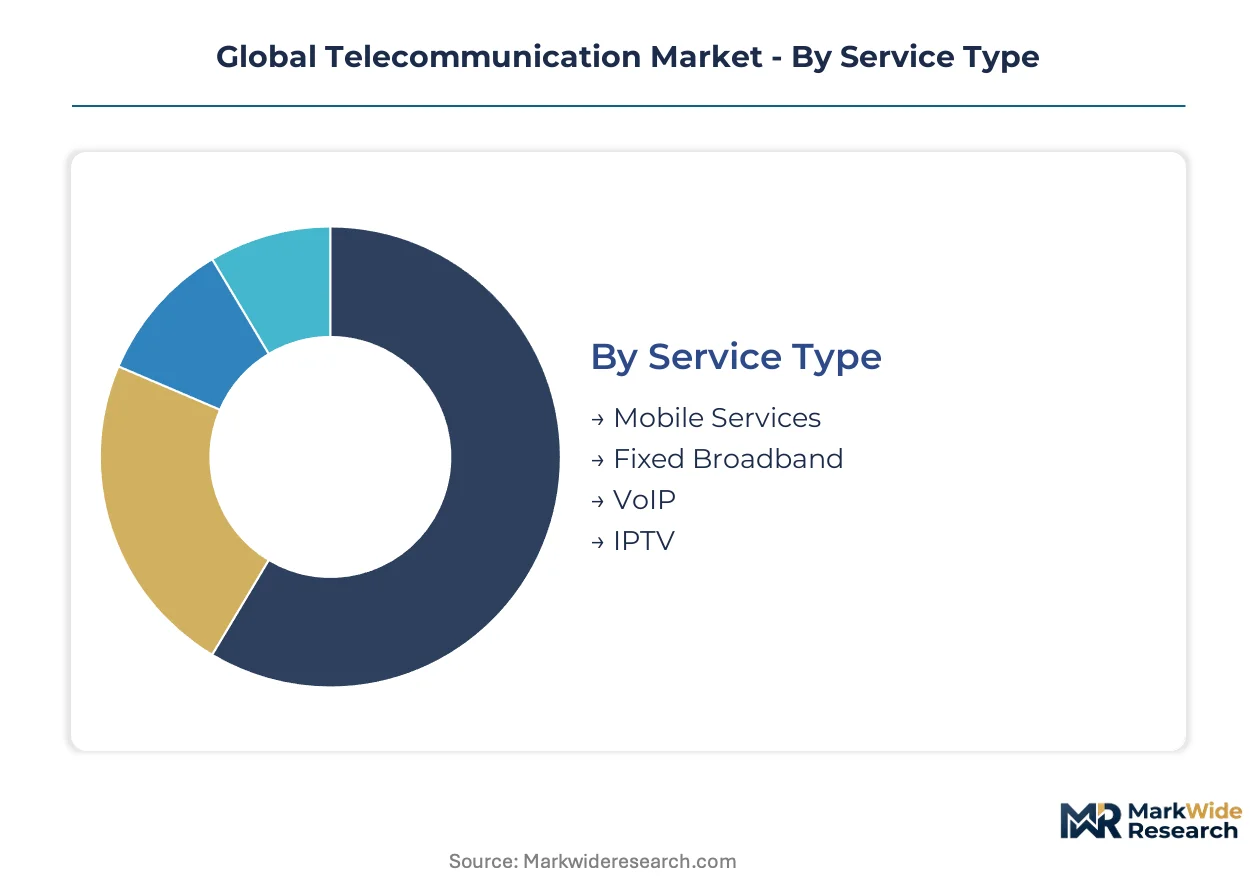
Telecommunication operators structure product portfolios around distinct service tiers, infrastructure technologies, and customer scale requirements. Segmentation discipline separates commodity connectivity from premium latency-guaranteed offerings and determines capital allocation across fiber, wireless, and orbital assets.
Service Type:
Channel mix varies sharply across service categories, with mobile services flowing through retail storefronts and digital self-service portals while fixed broadband relies on field technician networks and installation partnerships. VoIP and IPTV increasingly distribute through over-the-top platforms and device-embedded activation.
- Mobile Services:Voice and data plans delivered over cellular infrastructure generate the largest revenue pool through subscription and usage-based billing. Demand concentrates in India as TRAI's spectrum harmonization accelerates 5G base station permitting and smart city backbone deployment.
- Fixed Broadband:Wireline internet access through fiber, cable, or DSL termination points carries superior margin profiles due to lower churn and infrastructure control. European carriers prioritize fiber-to-the-home under national broadband mandates and subsidy programs that de-risk last-mile economics.
- VoIP:Packet-switched voice services displace circuit-switched PSTN traffic through enterprise PBX replacement and consumer messaging app integration.
- IPTV:Managed television delivery over IP multicast networks bundles with broadband subscriptions to reduce customer acquisition costs and extend average revenue per user.
By volume, Mobile Services leads. By growth pace, Fixed Broadband is ahead.
Technology:
Cost tier stratification separates legacy 4G and copper infrastructure from premium 5G and fiber deployments, with satellite occupying a specialized high-latency, wide-coverage niche.
- 4G:LTE macro networks provide baseline connectivity across mature markets with depreciated capital bases. Rural carriers in Indonesia and India extend 4G coverage through government universal service obligations before 5G overlay.
- 5G:New radio standards in sub-6 GHz and millimeter-wave bands enable network slicing and ultra-reliable low-latency communication. Deployment concentrates in manufacturing corridors and financial exchanges where deterministic performance commands premium pricing.
- Fiber Optics:Optical transmission through silica waveguides sustains the highest margin profile with superior bandwidth-distance products and electromagnetic immunity.
- Satellite:Geostationary and low-earth orbit constellations address coverage gaps beyond terrestrial economic reach.
By installed base, 4G dominates. By capital allocation intensity, 5G is expanding most quickly.
End User:
Customer type determines contract structure, with residential subscribers on standardized plans and large enterprises negotiating customized service level agreements with penalty clauses.
- Residential:Individual households consume mass-market voice, broadband, and entertainment bundles through standardized pricing tiers. Demand clusters in urban India and Brazil where smartphone penetration drives data plan upgrades.
- SMEs:Small and medium enterprises purchase connectivity through managed service aggregators rather than direct carrier relationships, favoring single-source accountability for multi-site requirements.
- Large Enterprises:Multinational corporations procure dedicated fiber, software-defined WAN, and cloud access with guaranteed latency and bandwidth commitments.
- Government:Public administration contracts mandate data sovereignty compliance and certified security classifications under GDPR and national procurement rules.
By subscriber count, Residential leads. By revenue per connection, Large Enterprises is climbing the fastest.
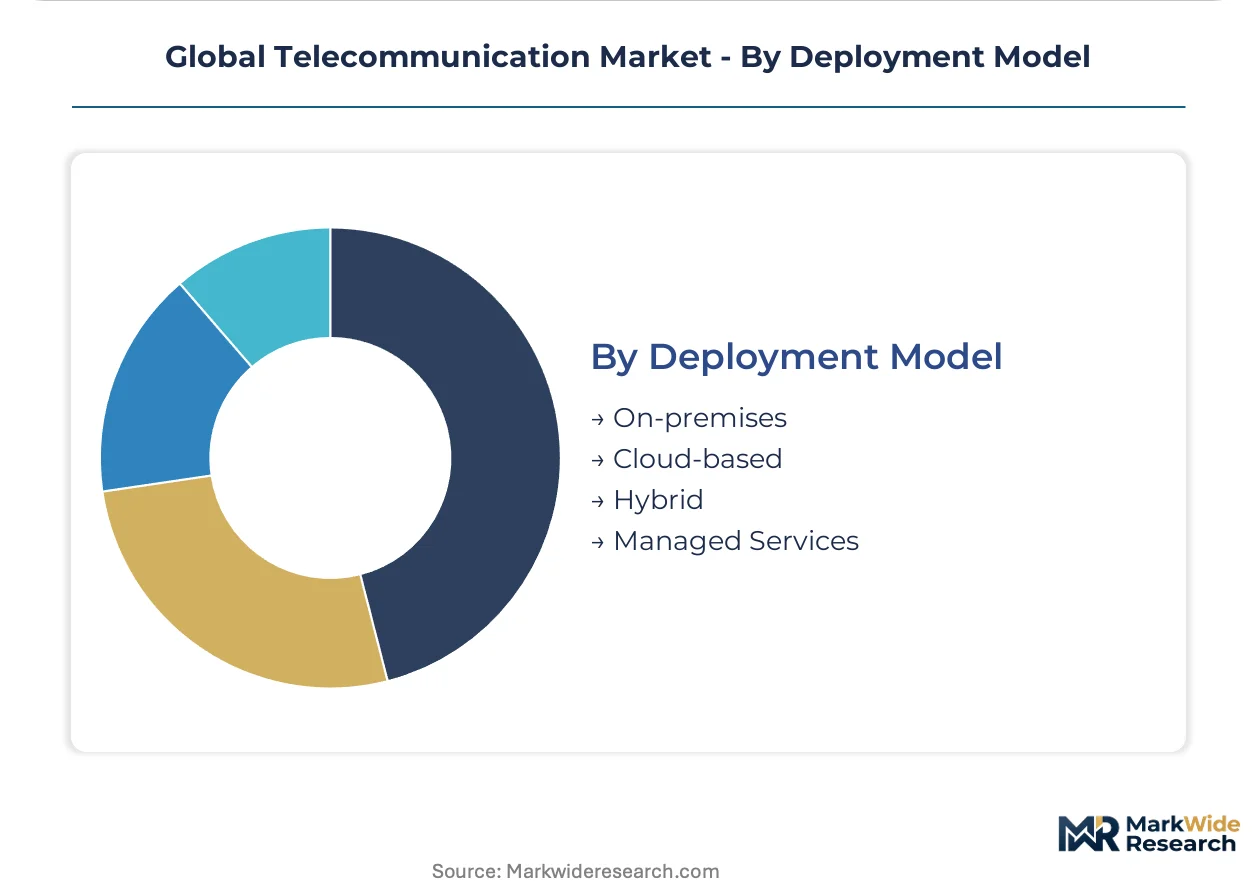
Deployment Model:
Application criticality drives infrastructure placement, with latency-sensitive workloads requiring on-premises termination and variable workloads shifting to cloud orchestration.
- On-premises:Physical infrastructure owned and operated at customer sites provides deterministic performance for trading floors and industrial control systems. Financial services in Frankfurt and London demand sub-millisecond fiber termination.
- Cloud-based:Virtualized network functions running on hyperscaler infrastructure enable rapid scaling without capital commitment. GDPR-driven data sovereignty mandates pull European processing into regional cloud zones.
- Hybrid:Split architectures combine controlled on-premises elements with burst capacity from cloud orchestration.
- Managed Services:Outsourced network operations transfer operational risk to carrier or specialist providers through outcome-based contracts.
By current deployment share, On-premises leads. By transition momentum, Cloud-based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier infrastructure investment concentrates in national markets where spectrum policy and subsidy programs align with scale deployment economics. The United States, China, Germany, India, and Japan collectively anchor capital allocation intensity across fiber and 5G rollout timelines.
United States
Fiber-to-the-home builds accelerate in northeastern corridors and Sun Belt metros as carriers replace aging copper plant. The FCC's spectrum auction calendar and net neutrality principles shape permitting timelines and service pricing flexibility. Verizon leverages dense fiber depth across Boston-Washington corridor markets to sustain premium enterprise positioning.
China
Domestic 5G base station targets drive equipment procurement at scale while Belt and Road infrastructure extension pulls capital into Southeast Asia and Africa. MIIT coordinates spectrum harmonization and domestic vendor sourcing rules that influence Asia-Pacific deployment patterns. China Mobile dominates subscriber scale across coastal manufacturing clusters and inland provincial capitals.
Germany
Network densification and spectrum discipline anchor European 5G rollout as enterprises localize processing under GDPR mandates. The EU AI Act's high-risk system classification imposes conformity assessments on predictive maintenance algorithms and network automation. Deutsche Telekom front-loads compliance investments across Frankfurt industrial corridors and Rhine-Ruhr manufacturing zones.
India
TRAI's spectrum harmonization rules compress base station permitting timelines for massive MIMO deployment in smart city backbones. The BharatNet program extends addressable subscriber pools into rural districts outside saturated urban markets. Tower loading constraints in secondary cities favor compact 64T64R units for faster civil infrastructure rollout.
Japan
Enterprise cloud connectivity adoption forces core network rearchitecture for latency-sensitive financial and manufacturing workloads. METI coordinates 5G private network licensing for industrial IoT in Nagoya automotive clusters and Osaka port logistics zones. Nippon Telegraph and Telephone anchors fiber investment in Tokyo-Yokohama corridor data center interconnection.
Global Telecommunication Market Competitive Environment
Concentration sits with integrated national carriers that control spectrum licenses and last-mile infrastructure across major economies. Scale advantages compound through subscriber density and fiber depth rather than technology differentiation. Three archetypes dominate: state-affiliated Asian champions with domestic market control, European multi-nationals managing cross-border regulatory complexity, and North American carriers monetizing enterprise connectivity premiums. Competitive moves center on fiber asset acquisitions and 5G standalone core deployment to expose network APIs for developer ecosystem capture.
Among state-affiliated Asian champions, China Mobile exemplifies subscriber-scale dominance through infrastructure extension into Belt and Road corridors. Deutsche Telekom AG represents European multi-national positioning through network densification and EU AI Act compliance front-loading. Verizon Communications Inc. anchors North American premium-tier competition through fiber depth in enterprise-dense northeastern corridors.
| Leading Market Players |
|---|
| China Mobile |
| Verizon |
| AT&T |
| Deutsche Telekom |
| China Telecom |
| Nippon Telegraph and Telephone |
| China Unicom |
| Vodafone |
| Telefónica |
| Others |
Value Chain & Pricing Dynamics
Long-term spectrum lease contracts lock in both supply access and price visibility for carriers navigating TRAI's auction calendars in India and the FCC's allocation timelines in the United States. These arrangements stabilize capital deployment while exposing buyers to regulatory window risk.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for high-risk network automation systems across European deployments. Three-tier pricing structure across premium, standard, and economy levels separates latency-guaranteed enterprise fiber from mass-market broadband and basic voice services. Pricing pressure stems from optical component concentration among East Asian foundries. Residential subscribers exhibit highest price sensitivity while large enterprises negotiating software-defined WAN contracts show lowest.
Supply Chain Analysis
Strategic stockpiling of coherent DSPs and laser diodes dominates inventory strategy as lead times extend for 5G massive MIMO deployment. Component manufacturing concentrates in China, South Korea, and Taiwan. Raw material dependencies include gallium nitride substrates, silica fiber preforms, and rare-earth doped amplifiers. Single-source vulnerability threatens equipment delivery timelines. Distribution runs through carrier-direct procurement and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed service attach rates are expanding faster than raw connectivity subscriptions as enterprises consolidate procurement through single-source aggregators. Recurring revenue from network API exposure and edge computing orchestration outpaces hardware margin compression.
For Market Incumbents: Shield fiber depth advantages through accelerated last-mile overbuilds in northeastern US corridors and Rhine-Ruhr manufacturing zones. Open RAN disaggregation threatens vendor lock-in patterns. Prioritize certification investments for EU AI Act compliance on predictive maintenance algorithms. For New Entrants and Emerging Players: CE marking fast-track for low-risk network equipment categories opens European market entry ahead of full high-risk system compliance. Rural broadband gaps in India's BharatNet program and Indonesia's universal service zones offer lowest competitive density. Pursue shared infrastructure models with tower companies to de-risk civil works investment. For Investors and Strategic Acquirers: Fiber-rich regional carriers with enterprise customer density represent prime acquisition targets for platform consolidation plays. Long-term viability hinges on 5G standalone core deployment timing and API monetization traction. Watch satellite-cellular convergence partnership announcements as inflection indicators for terrestrial carrier strategic positioning.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Standalone Core Deployment | Network slicing capabilities expose latency APIs to developer ecosystems beyond commodity connectivity. |
| Fiber-to-the-Home Overbuild | Verizon leverages dense Boston-Washington fiber plant to sustain premium enterprise positioning. |
| EU AI Act Compliance Investment | Deutsche Telekom front-loads conformity assessments for predictive maintenance algorithms. |
| Open RAN Architecture Migration | Disaggregated hardware-software procurement fragments vendor lock-in patterns across Asian deployments. |
| Satellite-Cellular Convergence Partnership | Low-earth orbit integration extends carrier portfolios without spectrum auction capital commitment. |
Study Parameters
Operator-level perspectives from chief technology officers, network planning directors, regulatory affairs managers, and procurement heads anchored the qualitative base. Primary interviews combined with secondary validation from FCC spectrum auction records, TRAI consultation papers, ETSI technical specifications, and carrier capex disclosures. Bottom-up subscriber and infrastructure deployment estimates triangulated against top-down market sizing.
Sensitivity analysis tested forecast robustness across spectrum auction timing variations and subsidy program continuity assumptions. Segmentation dimensions modeled include service type, technology generation, end-user scale, and deployment architecture across the analysis window. CAGRs derived from infrastructure investment trajectories, subscriber penetration curves, and ARPU evolution patterns. Industry-specific inputs encompassed 5G base station deployment schedules and fiber route-mile expansion targets.
Decision-makers should treat outputs as directional under stable regulatory enforcement and subsidy continuity assumptions; material deviation would warrant model refresh. Revision becomes warranted when spectrum auction delays or geopolitical trade restrictions cross thresholds affecting equipment procurement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Brazil Telecom Market
Telecommunications
Finland Telecom Market
Telecommunications
Voip Phone Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
Cloud RAN Market
Telecommunications
Voice Communication Control System Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
5G Transport Networks Market
Telecommunications
Oman Telecom Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
Australia Telecom Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
Belgium ICT Market
Telecommunications
Promotional Sms Market
Telecommunications
Qatar Telecom Market