
 Super High Frequency Communication Market | 2026-2036
Super High Frequency Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Super High Frequency Communication Market Intelligence
Defense procurement channels is tilting toward sole-source and indefinite-delivery contracts for classified SHF programs. L3Harris Technologies, Inc. leverages its secure communications pedigree to anchor classified military satellite terminal programs across multiple agencies. Cobham Limited competes through specialized antenna and radome manufacturing for maritime and aerospace platforms. Northrop Grumman dominates integrated electronic warfare suites where SHF modules serve as core transmit-receive elements.
Super high frequency communication encompasses electromagnetic signal transmission in the three to thirty gigahertz range, typically employing waveguide feeds, solid-state power amplifiers, and phased-array architectures for directional beam steering. These systems enable radar, satellite, and secure military links where atmospheric absorption and narrow beamwidths suit point-to-point or point-to-multipoint architectures. Microwave technology leads installed base volume but ultra wideband segments capture disproportionate R&D investment for cognitive radio and software-defined waveforms. Military application commands the largest committed budgets, while telecommunications backhaul shows the fastest policy-driven expansion as regulators release contiguous blocks for 5G millimeter-wave deployment.
The FCC governs civilian spectrum allocation and equipment authorization, while the Department of Defense mandates MIL-STD-188 interoperability for all SHF tactical radios, creating a bifurcated compliance landscape. ETSI and national regulators across Europe enforce CE marking and spectrum harmonization under the Radio Equipment Directive, restricting non-compliant hardware from NATO procurement pools. Stakeholders must monitor pending spectrum auctions and export control reclassifications that could redraw component sourcing strategies without warning.
Market Dynamics
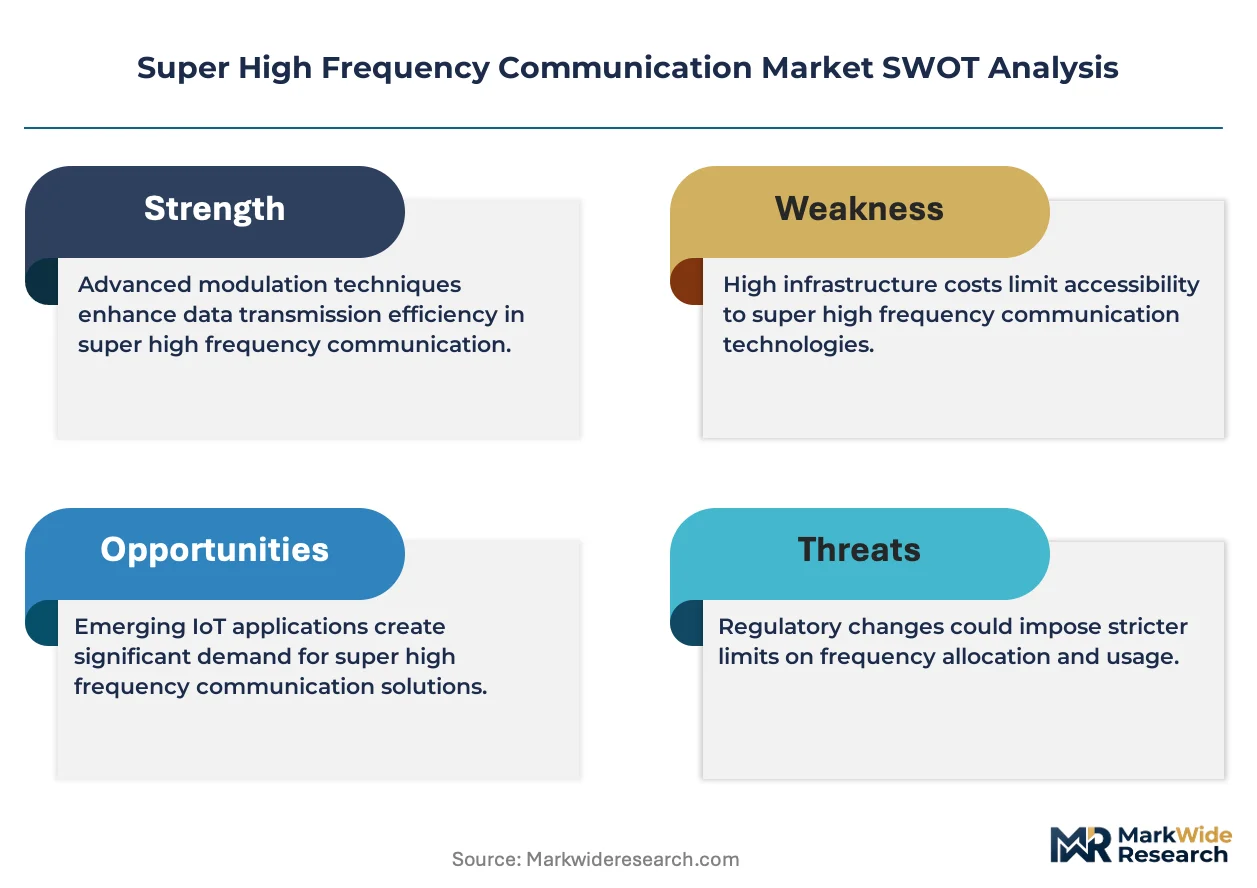
Defense procurement concentration around classified satellite terminals is compressing vendor margins while accelerating hardware refresh cycles mandated by spectrum reallocation policies.
Growth Catalysts
- MIL-STD-188 Mandates:The Department of Defense's interoperability standards force uniform procurement of tactical SHF radios across all military branches, eliminating fragmented legacy systems.
- 5G Millimeter-Wave Backhaul:Telecommunications carriers are deploying SHF bands for urban small-cell connectivity as the FCC releases contiguous spectrum blocks for commercial use.
- Phased-Array Miniaturization:Gallium nitride semiconductor advances enable lighter, cooler transmit-receive modules for unmanned aerial platforms and portable terminals.
Market Restraints
- Gallium Nitride Substrate Costs:Single-crystal wafer supply concentrates among Japanese and German specialty chemical suppliers, creating input price volatility for amplifier manufacturers.
- Atmospheric Absorption Physics:Oxygen and water vapor attenuation at Ka-band frequencies above 27 GHz limits link reliability without adaptive power control, constraining commercial adoption in humid climates.
- Export Control Reclassification:The Wassenaar Arrangement's periodic updates to dual-use technology lists disrupt component sourcing for non-NATO defense contractors without warning.
Strategic Opportunities
- Software-Defined Waveform Convergence:Cognitive radio architectures combining SHF hardware with AI-driven spectrum sensing open civilian emergency-response and disaster-relief applications previously reserved for military use.
- Maritime Connectivity Gaps:Commercial shipping fleets operating beyond geostationary coverage zones represent underpenetrated demand for steerable SHF flat-panel antennas.
- EU Radio Spectrum Policy Programme:Harmonized 26 GHz and 28 GHz band allocations across member states create standardized addressable market scale for equipment vendors.
Industry Challenges
- Waveguide Engineering Talent Scarcity:Specialized electromagnetic simulation and precision machining skills required for low-loss feedhorn production concentrate among aging workforces in aerospace clusters.
- Legacy System Integration Friction:New SHF terminals must interface with decades-old cryptographic units and antenna control systems, extending deployment timelines and testing costs.
- CE Marking Certification Delays:ETSI's evolving electromagnetic compatibility standards for 5G base stations create unpredictable approval timelines for integrated SHF subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super High Frequency Communication Market |
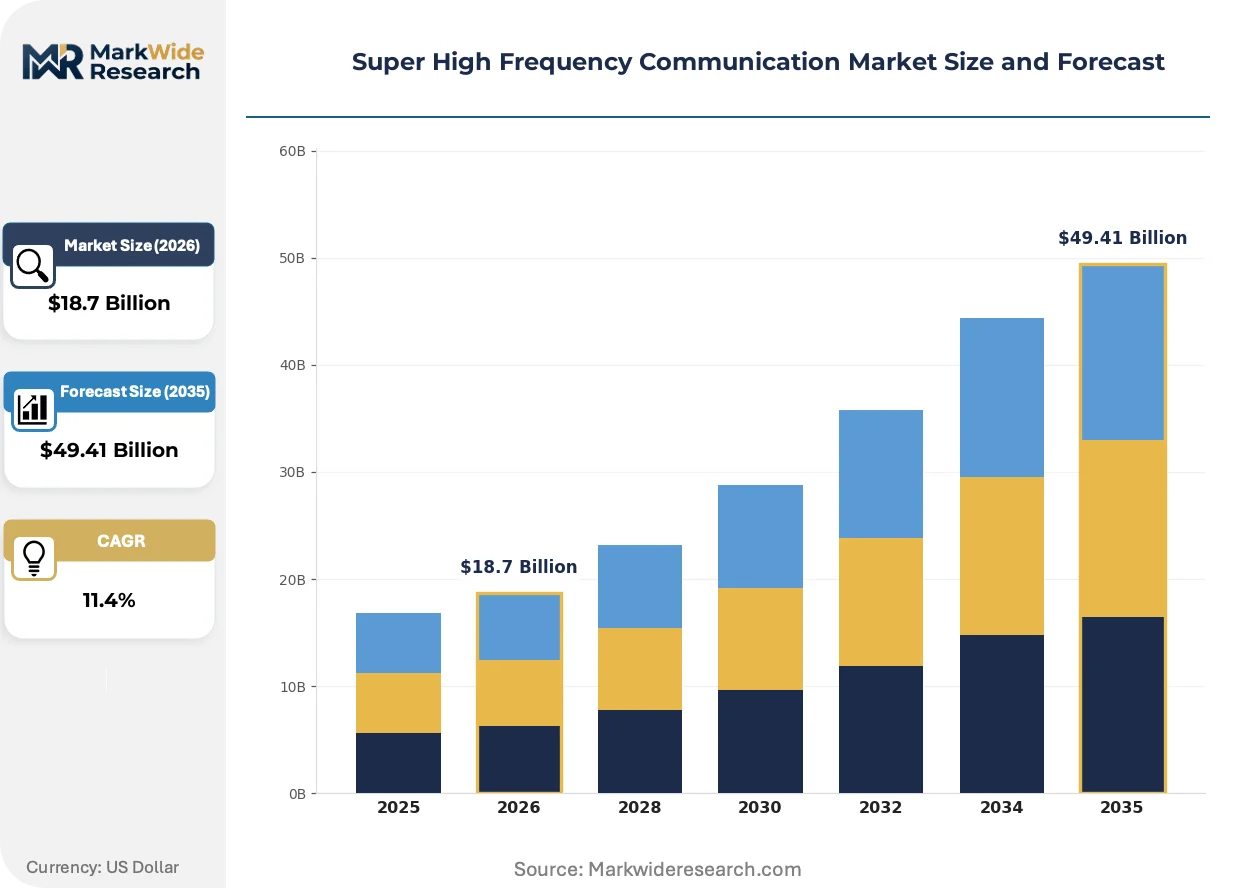
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Analog, Digital, Microwave, Ultra Wideband Application: Aerospace, Maritime, Military, Telecommunications End User: Government, Enterprises, SMEs, Educational Institutions Service Type: Managed Services, Professional Services, Consulting, Support |
| Companies Covered | Astronics Corporation, Cobham Limited, Raycap, General Dynamics Corporation, L3Harris Technologies, Inc., Northrop Grumman, Hensoldt, JENOPTIK AG, Raytheon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super High Frequency Communication Market Strategic Shifts & Innovations
Solid-state power amplification is displacing traveling-wave tube technology across multiple end-use segments while regulatory pressure compresses development cycles for hardware certification.
Gallium nitride monolithic microwave integrated circuits are collapsing the cost-performance frontier for high-power SHF transmission. Military satellite terminal programs in the United States and allied nations are mandating GaN-based solid-state amplifiers for all new procurements. This technology shift is collapsing the installed base of vacuum-tube amplifiers and eliminating their associated warm-up delays and mechanical failure modes.
The FCC's 3.45 GHz and 28 GHz auction frameworks are mandating accelerated equipment authorization timelines for 5G infrastructure vendors. Commercial base station manufacturers must now submit modular certification packages rather than system-level approvals. This regulatory compression is forcing component suppliers to pre-certify amplifier and filter subassemblies, shifting compliance burden upstream in the supply chain.
Defense agencies are consolidating satellite terminal procurement under indefinite-delivery, indefinite-quantity contract vehicles with single-source awards. Prime contractors are absorbing subsystem integration responsibilities previously held by tier-two suppliers. This buying-pattern concentration is most visible in classified programs managed by the Space Development Agency and National Reconnaissance Office, where procurement officers prioritize vendor pedigree over competitive bidding.
Super High Frequency Communication Market Segmentation
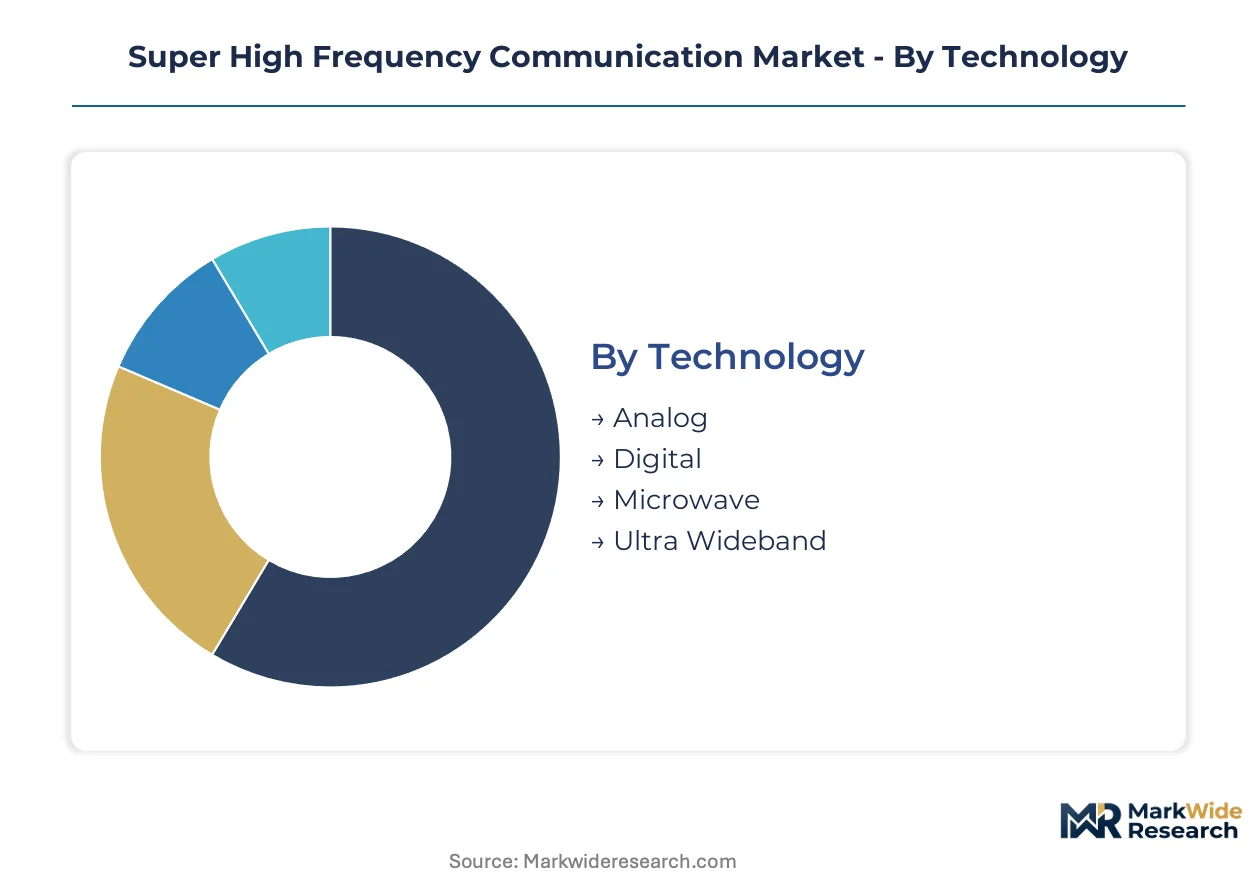
SHF equipment manufacturers configure product portfolios across four orthogonal dimensions: signal processing architecture, operational environment, customer procurement authority, and post-sale revenue model. Each segmentation axis carries distinct margin profiles and certification burdens that reshape vendor strategy.
Technology:
Mature transmission architectures dominate installed base volume while emerging digital and wideband formats capture disproportionate R&D allocation.
- Microwave:Conventional waveguide-based systems using magnetron or solid-state oscillators for fixed-link backhaul and radar illumination. Defense procurement in the United States and allied NATO programs sustains the bulk of replacement demand despite slower feature evolution.
- Digital:Software-defined radio platforms employing direct digital synthesis and FPGA-based modulation for adaptive waveform agility. Telecommunications carriers in Germany and South Korea are deploying these systems for 5G millimeter-wave base stations as spectrum auctions release contiguous blocks.
- Analog:Legacy amplitude and frequency modulation hardware with minimal signal processing overhead. Remaining demand concentrates in cost-sensitive maritime distress beacons and developing-world broadcast relay stations.
- Ultra Wideband:Impulse-radio and multiband OFDM architectures spanning multiple gigahertz instantaneously. Research investment from automotive radar developers in Japan and precision indoor positioning vendors in the United States is accelerating module miniaturization.
Microwave handles the majority of throughput; Ultra Wideband is gaining share fastest on experimental deployment momentum.
Application:
Operational environment dictates environmental sealing, shock tolerance, and electromagnetic interference hardening requirements.
- Military:Tactical radios, satellite terminals, and electronic warfare suites requiring MIL-STD-188 interoperability and NSA-certified cryptographic modules. Procurement officers at the Space Development Agency and allied defense ministries are consolidating awards under sole-source indefinite-delivery vehicles.
- Telecommunications:5G small-cell backhaul and fixed wireless access equipment for urban density coverage. The FCC's accelerated equipment authorization timelines are compressing development cycles for base station manufacturers in California and Texas.
- Aerospace:In-flight connectivity terminals and air-to-ground datalinks for commercial and military aircraft. Certification burdens from the FAA and EASA extend lead times for new antenna form factors.
- Maritime:Shipboard satellite terminals and coastal radar for commercial fleets and naval vessels. Underpenetrated demand exists among container operators beyond geostationary coverage zones in the Pacific and Indian Ocean corridors.
Military commands the largest committed procurement budgets; Telecommunications is expanding most quickly on regulatory spectrum release.
End User:
Customer scale and procurement authority determine contract structure, payment terms, and integration service intensity.
- Government:National defense agencies, civilian emergency services, and regulatory bodies with classified program requirements. The Department of Defense mandates MIL-STD-188 compliance for all tactical SHF acquisitions.
- Enterprises:Mining, energy, and logistics corporations operating private microwave networks across dispersed facilities. These customers prioritize managed service arrangements over capital ownership.
- SMEs:Regional internet service providers and industrial automation integrators with limited in-house RF engineering. Price sensitivity drives preference for modular, field-upgradeable hardware.
- Educational Institutions:University research laboratories and radio astronomy observatories requiring specialized low-noise amplifiers and precision frequency references. Funding cycles tied to national science budgets create lumpy demand patterns.
Government absorbs the highest absolute spend; Enterprises are the fastest adopter of outsourced network operations.
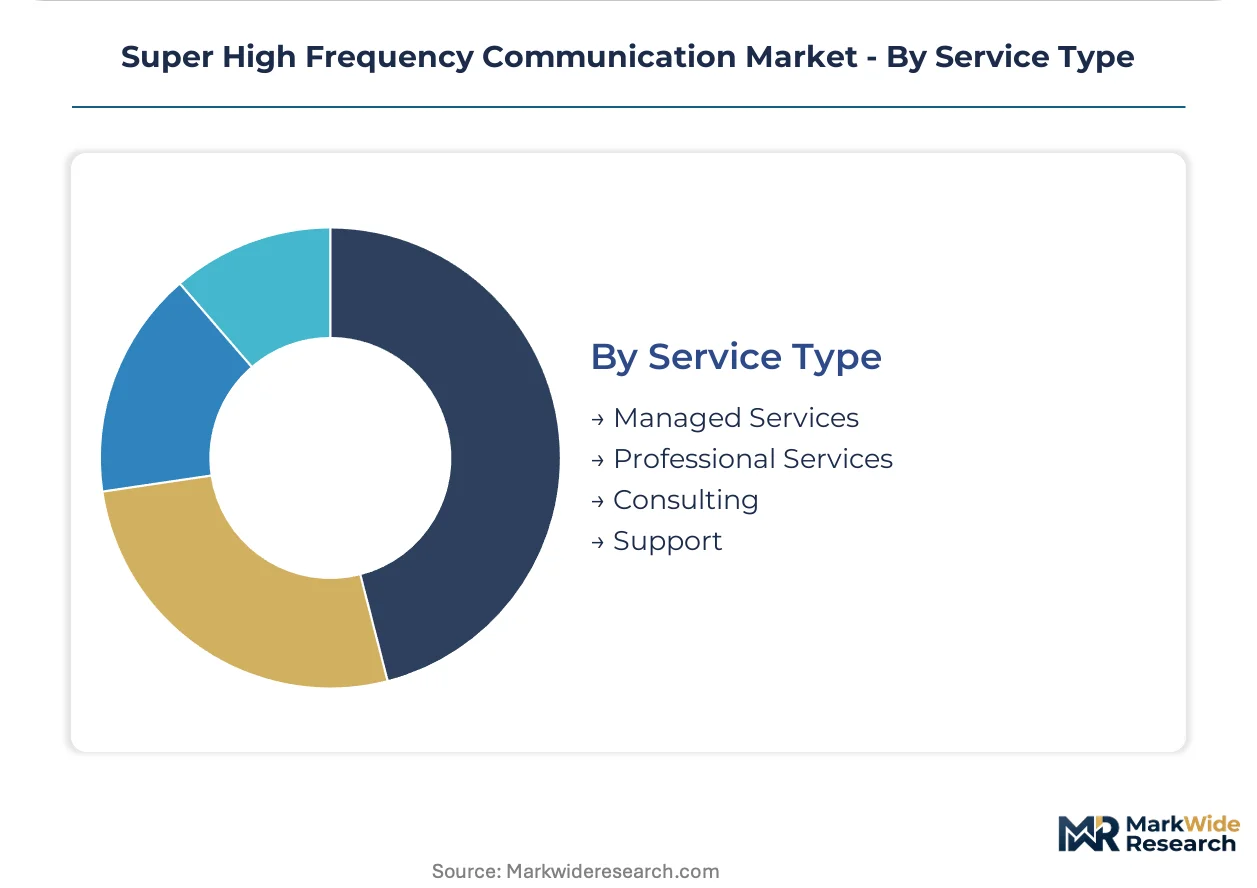
Service Type:
Revenue model selection reflects customer technical capability and operational risk tolerance.
- Managed Services:Complete network operation including spectrum monitoring, interference mitigation, and capacity planning. Telecommunications carriers in the United States and Germany are outsourcing SHF backhaul operations to specialized vendors.
- Professional Services:System integration, installation, and commissioning for complex multi-vendor deployments. Defense prime contractors are absorbing these responsibilities previously held by subsystem suppliers.
- Consulting:Spectrum strategy, regulatory filing preparation, and link budget analysis. Demand concentrates among enterprises navigating FCC and ETSI equipment authorization processes.
- Support:Maintenance contracts, spare parts logistics, and firmware update subscriptions. Gallium nitride amplifier reliability improvements are extending mean-time-between-failures and compressing attach rates.
Managed Services captures the dominant share of recurring revenue; Professional Services is climbing fastest on defense integration consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement premiums in the United States command pricing power that German telecommunications equipment cannot match, creating a structural asymmetry that shapes vendor strategy across both markets.
United States
Military satellite terminal programs and 5G millimeter-wave backhaul deployments drive procurement concentration. The FCC accelerates equipment authorization timelines for commercial base station manufacturers. Defense corridors in California and Virginia anchor classified program management, while aerospace clusters in Texas concentrate phased-array manufacturing.
Germany
Telecommunications carriers deploy digital SHF platforms for urban small-cell density coverage. ETSI enforces electromagnetic compatibility standards under the Radio Equipment Directive. Industrial centers in Bavaria and Baden-Württemberg host precision waveguide machining operations serving both NATO defense and commercial aviation.
Japan
Automotive radar developers and precision electronics manufacturers drive ultra-wideband module demand. METI coordinates national spectrum strategy for 28 GHz 5G allocation. Manufacturing clusters in the Kanto and Chubu regions concentrate gallium nitride semiconductor fabrication for high-power transmission.
South Korea
Telecommunications infrastructure vendors pursue aggressive 5G millimeter-wave rollout schedules. The country's national spectrum regulator releases contiguous blocks in the 26 GHz and 28 GHz bands. The Seoul Capital Area anchors system integration capabilities for export-oriented base station production.
United Kingdom
Defense electronics suppliers and maritime connectivity providers sustain dual-use demand channels. National regulators enforce CE marking harmonization aligned with NATO procurement requirements. Aerospace and defense engineering concentrates in the South East and South West regions, with satellite terminal development clustering around established military research facilities.
Super High Frequency Communication Market Key Industry Players
Defense prime contractors and specialized component suppliers split the market into distinct capability tiers. The vendor base concentrates around classified program pedigree and pre-certified subsystem integration. Three archetypes dominate: integrated electronic warfare suite providers, secure communications specialists, and precision antenna manufacturers. Competitive positioning hinges on sole-source contract capture and accelerated hardware refresh cycles driven by spectrum reallocation mandates.
Within the secure communications tier, L3Harris Technologies, Inc. and Northrop Grumman exemplify vendors whose classified program experience anchors indefinite-delivery contract positioning. Cobham Limited occupies a specialist role in maritime and aerospace platform integration. These three represent the dominant procurement channel access patterns visible across defense agency satellite terminal programs.
| Leading Market Players |
|---|
| Astronics Corporation |
| Cobham Limited |
| Raycap |
| General Dynamics Corporation |
| L3Harris Technologies, Inc. |
| Northrop Grumman |
| Hensoldt |
| JENOPTIK AG |
| Raytheon Technologies |
| Others |
Cost & Logistics Intelligence
Gallium nitride substrate concentration among Japanese and German specialty chemical suppliers determines both the premium spread for GaN-based SHF amplifiers and the geographic shape of component sourcing networks. Defense prime contractors absorb input cost volatility through sole-source contract structures while telecommunications vendors face compressed margins on standardized 5G backhaul equipment.
Pricing Analysis
Configured-to-order pricing for classified military satellite terminals commands substantial premiums over commercial 5G backhaul hardware. Three-tier pricing structure across MIL-STD-188 certified, CE-marked commercial, and uncertified industrial tiers reflects divergent compliance burdens. Price differentiation hinges on cryptographic module integration and volume procurement scale. Cost compression in telecommunications equipment intensifies as FCC-mandated modular certification shifts compliance burden upstream. Government buyers exhibit lowest price sensitivity; regional internet service providers demonstrate highest.
Supply Chain Analysis
Extended payment terms from defense prime contractors to tier-two amplifier manufacturers have become standard practice across classified program supply chains. Gallium nitride semiconductor fabrication concentrates in Japan and South Korea; precision waveguide machining clusters in Germany and the United States. Raw material dependencies include single-crystal sapphire substrates, high-purity copper for waveguide feeds, and rare-earth elements for magnetic components. Single-source vulnerability persists for GaN wafer supply. Distribution runs through defense procurement channels and telecommunications equipment OEMs with limited spot-market activity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics dynamics are reshaping competitive positioning as software-defined waveform convergence erodes hardware-specific moats. Interoperability mandates from the Department of Defense and ETSI are creating ecosystem-level switching costs that favor incumbents with pre-certified module portfolios.
For Market Incumbents: Entrench position through backward integration into gallium nitride semiconductor fabrication and captive supply of precision waveguide components. Absorb subsystem integration responsibilities from tier-two suppliers to capture sole-source indefinite-delivery contract vehicles. The Space Development Agency's consolidation of satellite terminal procurement threatens margin compression for non-integrated vendors. Certification investment in MIL-STD-188 and CE marking creates defensive barriers against modular competitors. For New Entrants and Emerging Players: Establish a beachhead in maritime connectivity gaps beyond geostationary coverage zones where steerable flat-panel antenna demand remains underpenetrated. Target commercial shipping fleets operating Pacific and Indian Ocean corridors with software-defined platforms bypassing defense certification burdens. White-space opportunities exist in cognitive radio architectures for emergency-response applications. Go-to-market leverage rests on AI-driven spectrum sensing capabilities that differentiate from legacy hardware-defined systems. For Investors and Strategic Acquirers: FCC spectrum reclassification and EU Radio Spectrum Policy Programme harmonization reshape the acquisition landscape toward vendors with pre-certified 5G millimeter-wave subsystems. Long-term viability across the analysis window favors specialists with classified program pedigree and modular platform architectures. Acquisition target archetype: mid-cap GaN amplifier manufacturers with defense contract history and telecommunications certification pipeline. Watch Wassenaar Arrangement dual-use technology list updates as inflection indicators for component sourcing disruption.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Backward Integration | Captive wafer supply insulates margins from Japanese and German substrate volatility. |
| Software-Defined Waveform Platform | FPGA-based architectures enable cognitive radio penetration of civilian emergency markets. |
| MIL-STD-188 Certification Investment | Department of Defense interoperability mandates eliminate non-compliant vendors from procurement pools. |
| Maritime Flat-Panel Antenna Development | Steerable SHF terminals address container fleet connectivity gaps in Pacific corridors. |
| Modular Pre-Certification Program | FCC accelerated timelines shift compliance burden upstream to component suppliers. |
Research Approach
Cross-validation between primary interviews with defense procurement officers and telecommunications infrastructure vendors anchors the qualitative findings on sole-source contract dynamics and 5G deployment timelines. Secondary validation draws from SEC filings of listed defense contractors, FCC equipment authorization databases, ETSI electromagnetic compatibility standards, and Department of Defense budget justification documents. Bottom-up triangulation across gallium nitride amplifier shipment volumes and top-down reconciliation against satellite terminal procurement awards ensures consistency.
Calibration against historical defense procurement cycles and spectrum auction outcomes informs the analytical framework across the projection horizon. Segmentation dimensions modeled include signal processing architecture, operational environment, customer procurement authority, and post-sale revenue model. CAGRs derive from installed base replacement rates and policy-driven spectrum release schedules. Industry-specific forecast inputs incorporate MIL-STD-188 mandate compliance timelines and gallium nitride semiconductor cost-performance trajectories.
Stress conditions across gallium nitride substrate supply disruption, Wassenaar Arrangement reclassification, and FCC spectrum auction timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding defense budget continuity and 5G millimeter-wave deployment velocity. Macroeconomic contraction, regulatory delay, or GaN technology substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Mobile Virtual Network Operator (MVNO) Market
Telecommunications
IoT Telecom Services Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
South Korea Telecom Market
Telecommunications
Belgium ICT Market
Telecommunications
5G Technology Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Managed M2M Services Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Kenya Telecom Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
IP Telephony Market
Telecommunications
Global 5G Enterprise Market