
 Global LTE Market | 2026-2036
Global LTE Market Size, Share, and Industry Trends Forecast 2026-2036
Global LTE Market Outlook
Industrial IoT is pivoting toward LTE-M and NB-IoT connectivity as manufacturers replace aging SCADA systems with cellular-enabled sensors. Ericsson leverages its Radio System portfolio to dominate private network deployments for mining and port operators across Scandinavia and Australia. Nokia Corporation anchors its position through Deepfield analytics integration, helping carriers manage congestion from enterprise video traffic.
Long-Term Evolution (LTE) refers to the 4G wireless broadband standard defined by 3GPP Release 8, operating at frequencies from 700 MHz to 2.6 GHz with peak downlink rates of 300 Mbps in LTE-Advanced configurations using carrier aggregation. The technology serves as the backbone for mobile broadband, mission-critical communications, and massive machine-type connectivity across public and private networks. FDD LTE occupies the largest installed base among technology segments due to early carrier adoption in paired spectrum bands, while TDD LTE gains share in Asia-Pacific markets where unpaired spectrum allocation prevails. Enterprise end users represent the fastest-expanding category as manufacturers, utilities, and logistics operators deploy private LTE networks for deterministic latency and guaranteed coverage.
The FCC in the United States, ETSI in Europe, and MIIT in China govern spectrum allocation, equipment certification, and interference standards that determine which bands carriers may deploy and which vendors qualify for procurement. These frameworks directly shape vendor market access, with CE marking and FCC Part 27 certification acting as gatekeepers for base station and terminal equipment sales. Stakeholders must monitor spectrum auction calendars and open RAN mandates as these will determine whether incumbent infrastructure suppliers retain their installed base or face displacement by multi-vendor alternatives.
Market Dynamics
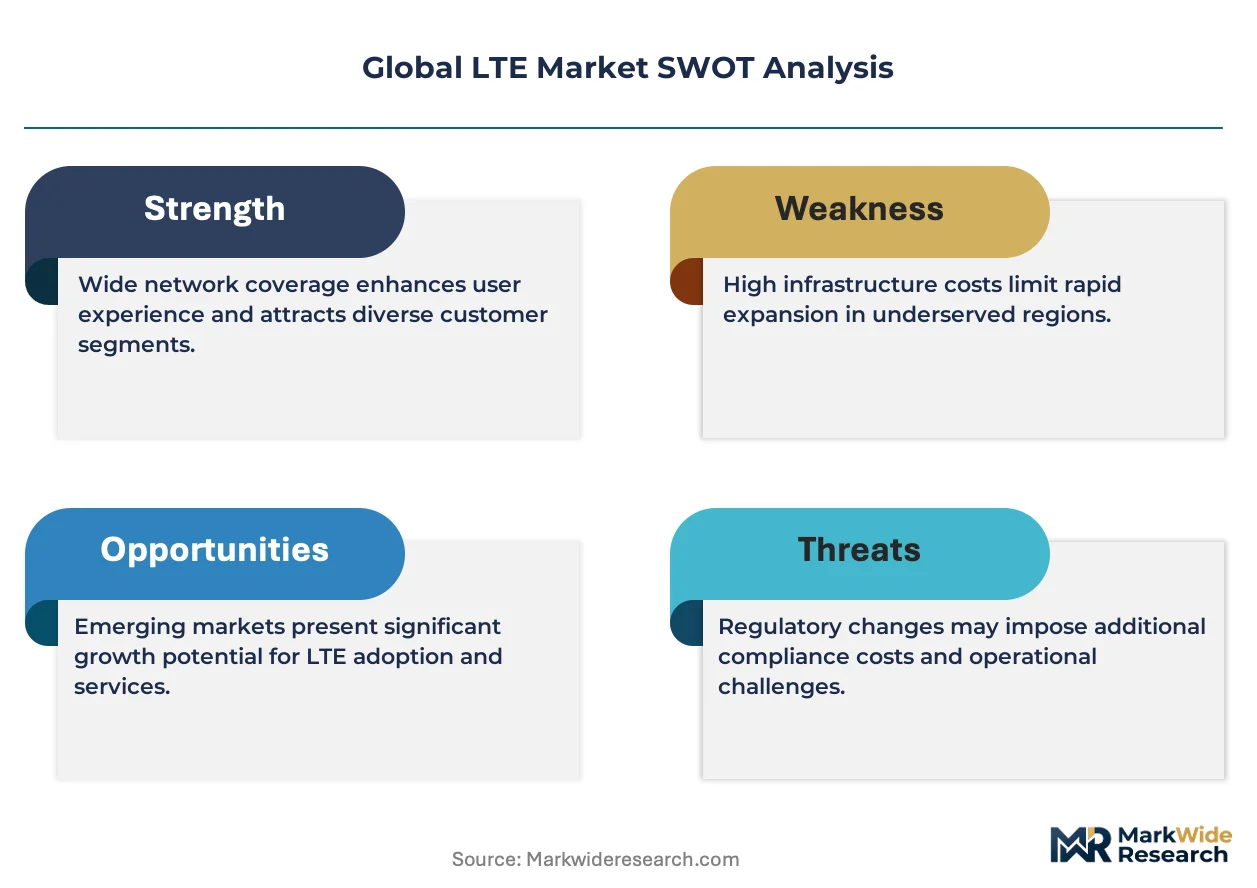
Carrier migration from legacy 2G/3G infrastructure toward LTE-Advanced and private network deployments is compressing equipment replacement cycles and reshaping vendor procurement priorities across industrial and public safety verticals.
Growth Catalysts
- Spectrum Reallocation Mandates:The FCC's 3.5 GHz CBRS auction and subsequent priority access license framework have unlocked private LTE deployments for manufacturing campuses and agricultural operators seeking deterministic coverage.
- Industrial Sensor Proliferation:Mining and port operators in Australia and Scandinavia are replacing hardwired SCADA with LTE-M enabled vibration and environmental sensors, driving base station density requirements.
- Nationwide Coverage Obligations:India's TRAI-mandated rural connectivity targets compel Reliance Jio and Bharti Airtel to expand macro site deployment into previously unserved districts.
Market Restraints
- Semiconductor Supply Concentration:Baseband processor fabrication depends on TSMC's 7nm capacity in Taiwan, creating single-source vulnerability for macro and small cell equipment.
- Spectrum Licensing Costs:India's auction reserve prices and annual spectrum usage charges compress carrier margins and delay network densification timelines.
- 5G-NR Substitution Pressure:Enterprise buyers in South Korea and Japan increasingly specify 5G private networks for new greenfield deployments, bypassing LTE infrastructure entirely.
Strategic Opportunities
- Brazilian Agricultural Automation:Soybean and sugarcane operators in Mato Grosso and São Paulo states lack fiber backhaul, creating addressable demand for LTE-based precision farming platforms.
- EU Critical Infrastructure Mandates:The NIS2 Directive compels water utilities and energy distributors to deploy redundant cellular connectivity, favoring hardened LTE equipment over consumer-grade alternatives.
- LTE-5G Convergence Architectures:Dual-mode radios supporting both LTE-Advanced and 5G-NR non-standalone operation allow carriers to sweat existing spectrum assets while future-proofing site investments.
Industry Challenges
- RF Engineering Talent Scarcity:Private network deployment requires specialized expertise in propagation modeling and interference mitigation that outstrips current vocational training output in Germany and the United States.
- Multi-Vendor Integration Complexity:Open RAN specifications from the O-RAN Alliance create interoperability testing burdens when combining radio units from Samsung with baseband software from Mavenir.
- Legacy PTT System Replacement:Public safety agencies in France and Italy face decade-long migration timelines from TETRA to LTE-based mission-critical voice due to coverage equivalence requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LTE Market |
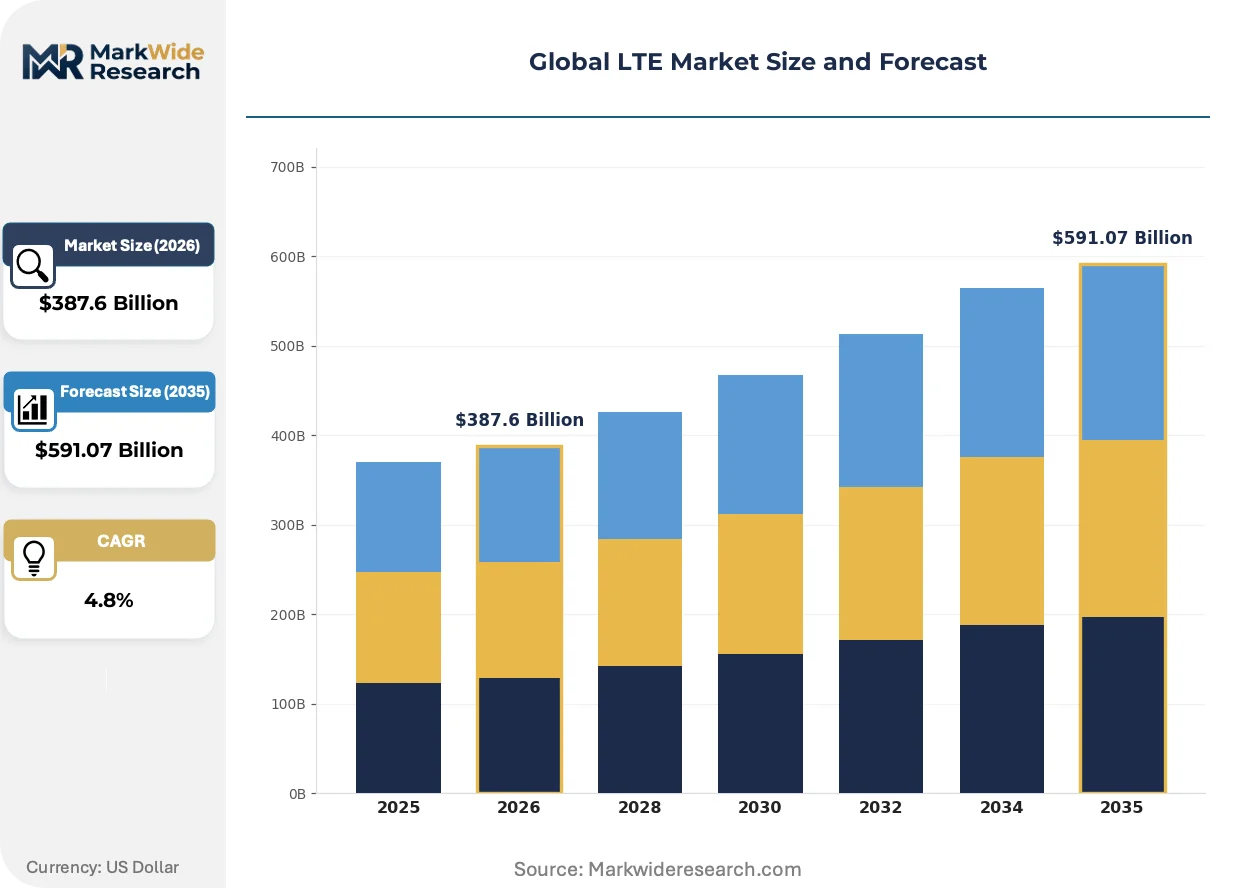
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: FDD LTE, TDD LTE, LTE-Advanced, LTE-M Device Type: Smartphones, Tablets, IoT Devices, Routers End User: Consumers, Enterprises, Government, Educational Institutions Deployment Type: On-Premises, Cloud, Hybrid, Others |
| Companies Covered | Ericsson, Nokia Corporation, Huawei Technologies, Samsung Electronics, Qualcomm Incorporated, Cisco Systems, Verizon Communications, NEC Corporation, Motorola Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LTE Market Strategic Shifts
Network architecture disaggregation and software-defined radio platforms are compressing equipment development cycles while enabling carrier-specific customization previously locked behind integrated vendor stacks.
Carrier aggregation across disparate licensed and unlicensed bands is electrifying throughput capabilities for fixed wireless access providers. Rural operators in the United States and Canada combine 700 MHz coverage propagation with 2.5 GHz capacity layers to challenge cable incumbents. This multi-band approach compresses the addressable market for traditional DSL and satellite broadband services in exurban geographies.
The EU's Radio Equipment Directive and associated harmonized standards under ETSI EN 301 908 are mandating stricter electromagnetic compatibility testing for base station equipment. Vendors must now demonstrate coexistence performance across adjacent bands before CE marking approval. This regulatory friction most affects small cell manufacturers targeting multi-country deployment, forcing them to front-load certification costs and extend product launch timelines.
Enterprise buyers increasingly unbundle network equipment procurement from managed services contracts, reversing the integrated sourcing model that dominated 4G rollout phases. Manufacturing conglomerates in India and Germany now issue separate RFPs for radio hardware, core software licenses, and ongoing operational support. This fragmentation favors specialized vendors with narrow technical excellence over full-stack suppliers, compressing account control for incumbent infrastructure providers.
Global LTE Market Segmentation
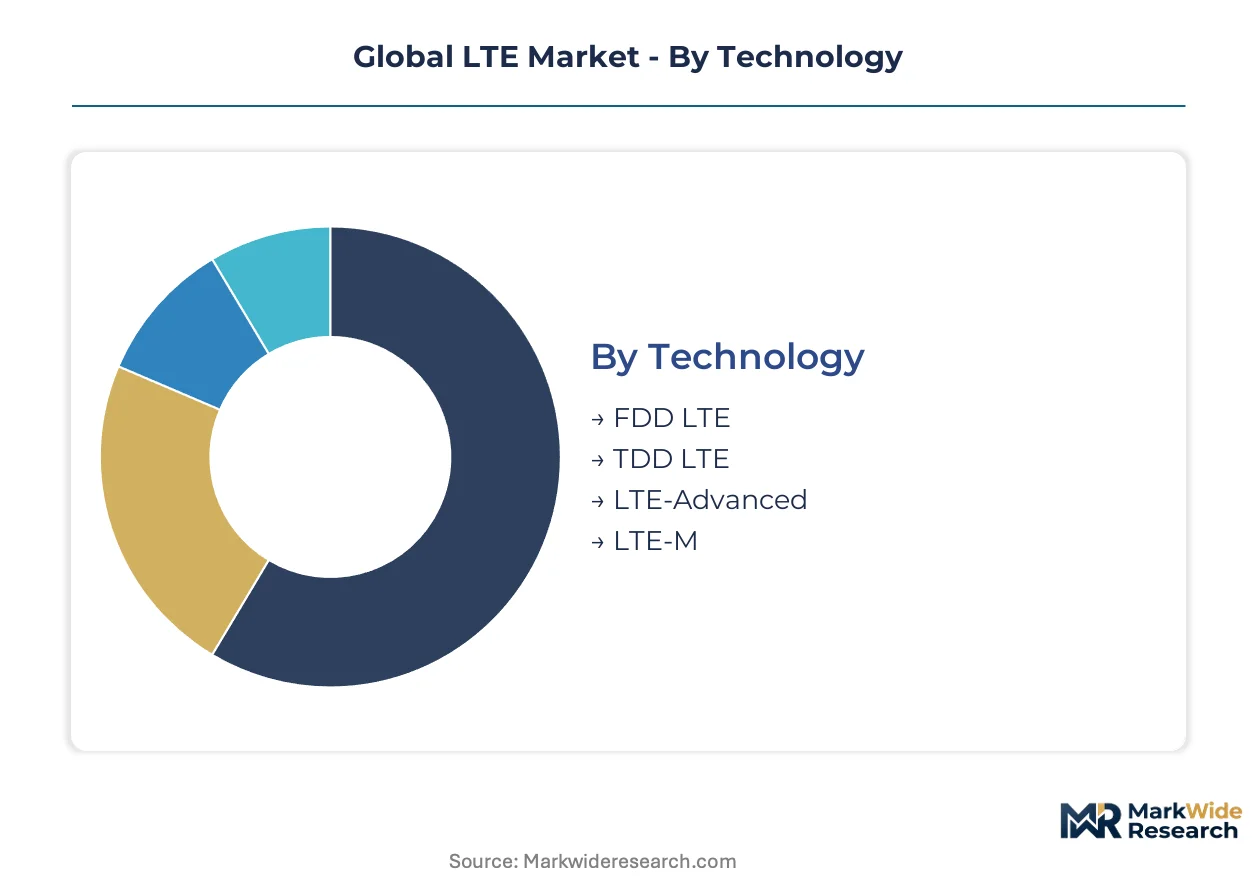
Technology heterogeneity across LTE standards creates distinct procurement clusters where carrier spectrum holdings and enterprise latency requirements determine equipment selection. Segmentation reveals how FDD dominance in paired bands contrasts with TDD concentration in unpaired Asian allocations, while device and deployment categories track the shift from consumer mobile broadband toward industrial sensor networks.
Technology:
Supply concentration among baseband vendors favors integrated radio platforms that span multiple LTE variants, with TSMC fabrication capacity constraining availability of discrete modem chipsets for specialized TDD and LTE-M applications.
- FDD LTE:Frequency-division duplexing employs paired spectrum blocks for simultaneous uplink and downlink transmission. Carriers in Germany, the United States, and Brazil leverage FDD deployments in 700 MHz and 800 MHz bands for suburban and rural coverage extension where propagation range outweighs spectral efficiency.
- TDD LTE:Time-division duplexing alternates transmission direction within a single unpaired band, enabling dynamic uplink-downlink ratio adjustment. China and India concentrate TDD deployment in 2.3 GHz and 2.6 GHz bands to accommodate asymmetric mobile video consumption patterns.
- LTE-Advanced:Carrier aggregation and enhanced MIMO configurations boost peak throughput through spectrum bonding across disparate bands.
- LTE-M:Narrowband IoT variant operates within 1.4 MHz channels for low-power machine-type communications in smart metering and asset tracking.
Today's leader: FDD LTE. Tomorrow's challenger: LTE-M.
Device Type:
Cost tier differentiation separates premium smartphone modems with multi-band aggregation capability from economy IoT modules constrained to single-band operation.
- Smartphones:Multi-mode terminals supporting LTE-Advanced carrier aggregation dominate subscriber equipment procurement volumes. Samsung and Apple source integrated Qualcomm and MediaTek platforms for flagship devices targeting South Korea and Japan markets where 256 QAM modulation is standard.
- IoT Devices:LTE-M and NB-IoT modules for industrial sensors and trackers represent the steepest expansion trajectory. Mining operators in Western Australia deploy vibration monitoring endpoints with decade-long battery life requirements.
- Tablets:Consumer and enterprise slate devices with embedded LTE connectivity serve field service and logistics applications.
- Routers:Fixed wireless access CPE units aggregate multiple LTE bands to challenge cable broadband in exurban United States and Canadian markets.
Volume concentrates in smartphones. Margin expansion favors IoT devices.
End User:
Customer type segmentation tracks procurement authority migration from centralized carrier retail toward distributed enterprise IT departments specifying private network equipment.
- Enterprises:Manufacturing conglomerates and logistics operators deploy private LTE networks for deterministic latency in warehouse robotics and port automation. German automotive plants specify 3.5 GHz CBRS equipment for campus-wide mobility.
- Government:Public safety agencies in France and Italy mandate mission-critical voice grade LTE for TETRA replacement, requiring hardened base stations with backup power and encryption.
- Consumers:Individual subscribers drive mass-market smartphone turnover and data plan revenue for mobile network operators.
- Educational Institutions:Universities deploy campus-wide LTE for student mobility and research network segmentation.
Procurement authority shifts from consumers to enterprises.
Deployment Type:
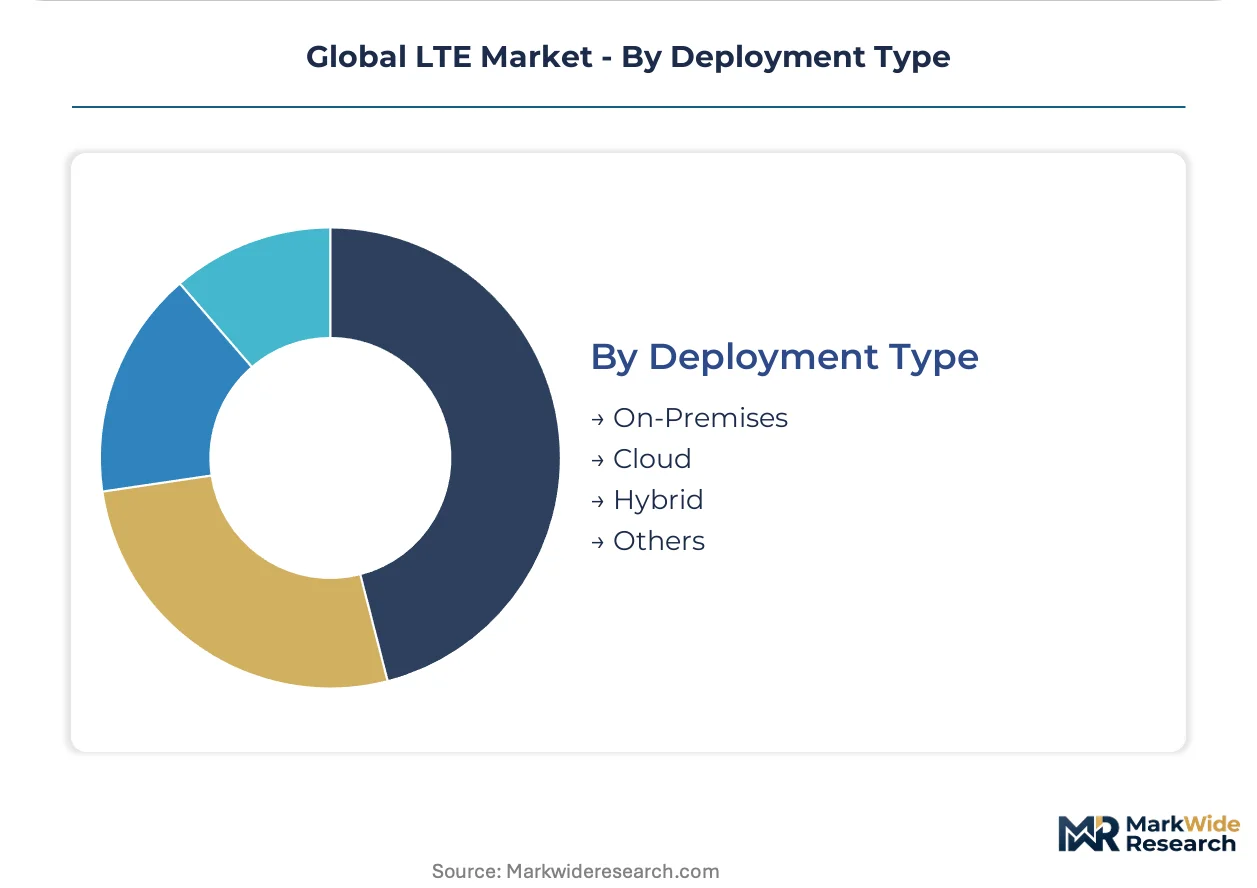
Maturity gradients separate established on-premises core networks from emerging cloud-native implementations that virtualize packet core functions.
- On-Premises:Traditional hardware-based EPC and 5G NSA cores installed in carrier data centers maintain largest installed base. Reliance Jio operates massive on-premises facilities across Mumbai, Delhi, and Bangalore to serve India's subscriber base.
- Cloud:Containerized core network functions deployed on hyperscaler infrastructure enable rapid scaling for MVNOs and private network operators. Rakuten Mobile in Japan pioneered fully virtualized cloud-native architecture.
- Hybrid:Split architectures combine on-premises control plane with cloud user plane for selective traffic offload.
- Others:Edge computing deployments and satellite backhaul integration represent emerging architectural variants.
On-premises retains share. Cloud gains fastest among new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reliance Jio's nationwide deployment in India concentrates equipment procurement and subscriber growth, while spectrum reallocation policies in the United States and TRAI-mandated rural connectivity targets reshape carrier infrastructure priorities across multiple geographies.
United States
Private LTE deployments for manufacturing campuses and agricultural operators accelerate following the FCC's 3.5 GHz CBRS auction and priority access license framework. The FCC's Part 27 certification requirements govern base station equipment sales as gatekeepers for vendor market access. Rural operators in the Midwest and Great Plains combine 700 MHz coverage propagation with 2.5 GHz capacity layers to challenge cable incumbents in exurban geographies.
India
TRAI-mandated rural connectivity targets compel Reliance Jio and Bharti Airtel to expand macro site deployment into previously unserved districts across Bihar, Uttar Pradesh, and Rajasthan. Annual spectrum usage charges and auction reserve prices compress carrier margins and delay network densification timelines. Mumbai, Delhi, and Bangalore host massive on-premises EPC facilities serving India's subscriber base.
Germany
Automotive plants in Bavaria and Baden-Württemberg specify 3.5 GHz CBRS equipment for campus-wide mobility and warehouse robotics. The EU's Radio Equipment Directive and ETSI EN 301 908 mandate stricter electromagnetic compatibility testing for base station equipment before CE marking approval. Industrial conglomerates in the Ruhr Valley and Stuttgart region issue separate RFPs for radio hardware, core software licenses, and operational support.
China
MIIT governs spectrum allocation and equipment certification for TDD LTE deployment in 2.3 GHz and 2.6 GHz bands to accommodate asymmetric mobile video consumption patterns. Unpaired spectrum allocation prevails across the Yangtze River Delta and Pearl River Delta regions. Baseband processor fabrication depends on TSMC's 7nm capacity, creating single-source vulnerability for macro and small cell equipment procurement.
Australia
Mining operators in Western Australia deploy LTE-M enabled vibration and environmental sensors, replacing hardwired SCADA systems and driving base station density requirements across remote extraction sites. The country's national communications regulator oversees spectrum allocation for deterministic coverage in resource extraction zones. Port operators in Perth and Darwin anchor private network deployments for automation and environmental monitoring.
Global LTE Market Competitive Environment
Portfolio diversification dominates the current landscape as infrastructure vendors unbundle network equipment procurement from managed services contracts. The vendor base concentrates among integrated radio platform suppliers spanning multiple LTE variants, with discrete modem chipset availability constrained by fabrication capacity. Three archetypes prevail: full-stack infrastructure providers, specialized radio hardware vendors, and cloud-native core software suppliers. M&A activity and strategic partnerships represent the dominant competitive moves as carriers seek multi-vendor alternatives.
Within the full-stack infrastructure tier, Ericsson and Nokia Corporation exemplify integrated suppliers with established carrier relationships across Scandinavia and European markets. Samsung Electronics occupies a position among diversified electronics conglomerates leveraging semiconductor and display capabilities for radio system integration. These three entities represent contrasting geographic origins and corporate structures while anchoring distinct strategic positions in carrier procurement cycles.
| Leading Market Players |
|---|
| Ericsson |
| Nokia Corporation |
| Huawei Technologies |
| Samsung Electronics |
| Qualcomm Incorporated |
| Cisco Systems |
| Verizon Communications |
| NEC Corporation |
| Motorola Solutions |
| Others |
Value Chain & Pricing Dynamics
RF engineering talent concentration in Germany and the United States widens pricing-tier spreads between premium private network deployments and economy macro cell installations, as labor-cost differentials compound with certification complexity to stratify vendor margins across deployment archetypes.
Pricing Analysis
Input-cost pass-through from TSMC's 7nm baseband fabrication capacity constrains pricing flexibility across equipment tiers. Three-tier pricing structure across premium, standard, and economy levels separates mission-critical hardened base stations from commercial-grade small cells and consumer CPE units. Cost compression in economy IoT modules is intensifying because MediaTek and Qualcomm compete for smart metering and asset-tracking contracts. Carrier procurement teams exhibit highest price sensitivity, while mining operators in Western Australia prioritize deterministic coverage over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with TSMC's Taiwan fabrication capacity for 7nm baseband processors, creating concentrated dependency for macro and small cell equipment. Component sourcing draws from South Korea for RF front-end modules, Japan for precision passive components, and China for PCB substrates and enclosure manufacturing. Tariff exposure on semiconductor equipment imports threatens cost stability for European and North American vendors. Distribution runs through carrier-direct procurement for public networks and systems integrators for private LTE deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through LTE-5G dual-mode radio architectures that extend equipment replacement cycles and command premium positioning against single-mode alternatives.
For Market Incumbents: Cement installed-base retention through Deepfield analytics integration and carrier aggregation software roadmaps that complicate multi-vendor displacement. Defend against Open RAN fragmentation by accelerating certification timelines for CE marking and FCC Part 27 compliance. Prioritize captive supply of 7nm baseband capacity through foundry partnerships that secure allocation priority over emerging entrants. For New Entrants and Emerging Players: Cloud-native core virtualization offers the most penetrable wedge for MVNOs and agricultural automation operators in Brazil's Mato Grosso region lacking fiber backhaul. Target Brazilian soybean and sugarcane cooperatives with precision farming platforms bundling LTE-based sensors and edge analytics. Lead with subscription pricing models that shift capital expenditure to operational expenditure for capital-constrained plantation operators. For Investors and Strategic Acquirers: Hyperscaler cloud providers are the most active acquirer in this space, seeking edge computing infrastructure to anchor distributed cloud services. Long-term viability hinges on convergence playbooks that bridge LTE-Advanced and 5G-NR non-standalone architectures across the analysis window. Monitor Open RAN interoperability certification milestones as inflection indicators for multi-vendor displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Radio Development | LTE-5G convergence future-proofs site investments for Reliance Jio and Bharti Airtel expansion. |
| Private Network Certification | CE marking and FCC Part 27 approval unlocks German automotive and US manufacturing campus deployments. |
| Cloud-Native Core Virtualization | Containerized EPC functions enable Rakuten-style MVNO scaling without hardware lock-in. |
| Open RAN Interoperability Testing | O-RAN Alliance compliance reduces Samsung-Mavenir integration burdens for multi-vendor procurement. |
| Spectrum Auction Participation | CBRS priority access licenses anchor US agricultural automation and manufacturing private networks. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with carrier network planning executives, base station procurement managers, industrial IoT deployment leads, and RF engineering specialists informed demand-side assumptions. Secondary sources include FCC spectrum auction records, ETSI harmonized standard filings, TRAI rural connectivity mandates, MIIT equipment certification databases, and customs data for base station import volumes. Bottom-up equipment shipment tallies triangulate against top-down carrier capex disclosures.
Granularity-level modeling distinguishes FDD LTE, TDD LTE, LTE-Advanced, and LTE-M technology variants across public carrier and private enterprise deployment types. Segmentation dimensions include device category, end-user vertical, and deployment architecture. CAGRs derive from equipment procurement pipeline analysis and carrier spectrum auction calendars. Forecast inputs incorporate semiconductor foundry capacity allocation announcements and regulatory mandate timelines for 2G/3G sunset.
The model holds under stable spectrum policy and foundry capacity allocation; deviation in tariff regimes or Taiwan supply disruption would shift equipment availability and pricing trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
Chile Telecom Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Algeria Telecom Market
Telecommunications
South Korea Telecom Market
Telecommunications
Mexico MNVO Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Medical 5G Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
5G MVNO Market
Telecommunications
Europe Telecom Expense Management Market
Telecommunications
Software Defined Radio Market