
 Iran Telecom Market | 2026-2036
Iran Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Telecom Market Outlook
Project finance tied to network infrastructure leasing is reshaping competitive dynamics among Iranian operators. MTN Irancell leverages its scale to sustain nationwide 4G coverage while negotiating equipment financing with Chinese vendors. Huawei Technologies anchors Tehran's 5G pilot programs through vendor-backed deferred payment structures. Telecommunication Company of Iran competes via its state-backed access to sovereign credit lines for rural fiber expansion.
Iran Telecom encompasses wired and wireless communication services, network infrastructure, and associated equipment operating across radio frequency spectrum and physical transmission media including fiber optic cable, copper DSL lines, and cellular base stations serving voice, data, and video transmission needs for consumer and enterprise users. Mobile Services generate the largest revenue pool given prepaid subscriber density, while Broadband Services represent the fastest expansion corridor as fiber-to-the-home displaces aging DSL infrastructure. 5G technology attracts concentrated capital despite spectrum constraints, whereas 4G LTE maintains dominant traffic volume across all provinces.
The Communications Regulatory Authority of Iran governs licensing, spectrum allocation, and interconnection tariffs, while the Ministry of Information and Communications Technology oversees infrastructure security mandates and data localization requirements. BIS-equivalent technical standards for network equipment certification create compliance thresholds that favor established suppliers with testing relationships. Stakeholders must monitor regulatory shifts around foreign vendor restrictions and domestic content requirements that could abruptly alter equipment procurement options.
Market Dynamics
Spectrum reallocation mandates from the Communications Regulatory Authority of Iran are forcing operators to accelerate infrastructure modernization while navigating constrained capital access and vendor financing dependencies.
Growth Catalysts
- Enterprise cloud migration:Iranian corporations are consolidating legacy PBX systems into unified communications platforms, creating sustained demand for high-bandwidth connectivity and managed services.
- Fiber-to-the-home rollout:The Ministry of Information and Communications Technology has prioritized urban densification targets that channel public investment into last-mile fiber deployment.
- 5G pilot zone expansion:Tehran's metropolitan corridor hosts concentrated base station upgrades that validate network slicing capabilities for industrial IoT applications.
Market Restraints
- Equipment import constraints:International banking restrictions limit vendor payment mechanisms and extend procurement timelines for core network hardware.
- Copper infrastructure lock-in:Rural DSL networks require costly maintenance while generating diminishing returns against fiber substitution economics.
- Spectrum scarcity:Limited sub-6 GHz allocations constrain capacity expansion for mobile data traffic growth in dense urban cells.
Strategic Opportunities
- Mashhad corridor penetration:Second-tier metropolitan zones exhibit underserved enterprise demand for dedicated leased-line services and data center interconnectivity.
- Smart city integration:Municipal traffic management and utility monitoring systems require converged 5G and fiber backhaul infrastructure.
- Domestic equipment sourcing:Local content requirements create openings for indigenous base station component manufacturing and software-defined networking development.
Industry Challenges
- Network engineering specialization:Shortages of RF planning expertise and fiber splicing technicians delay rollout schedules and inflate contractor costs.
- Legacy billing integration:Prepaid platform architectures resist seamless migration to convergent charging systems for bundled voice-data-video offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Telecom Market |
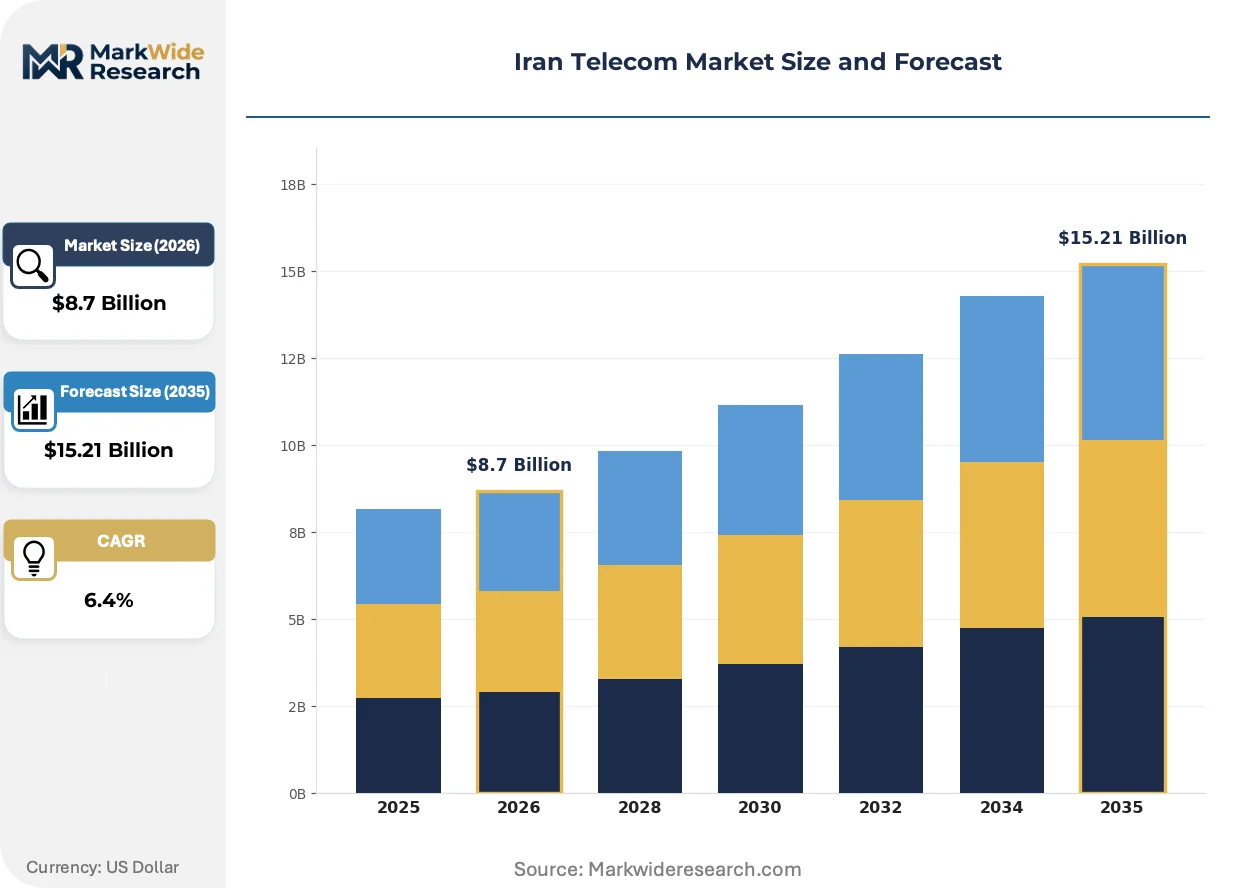
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-line Services, Broadband Services, VoIP Services Technology: 4G LTE, 5G, Fiber Optic, DSL End User: Residential, Enterprises, Government, Educational Institutions Distribution Channel: Direct Sales, Online Sales, Retail Stores, Indirect Partners |
| Companies Covered | Rightel, Ericsson, Telecommunication Company of Iran, ZTE, Huawei Technologies, Mobile Communications of Iran, Shatel, Orange, MTN Irancell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Telecom Market Strategic Shifts
Operational transformation across Iranian telecom infrastructure is accelerating through vendor financing restructuring, regulatory-driven spectrum efficiency mandates, and enterprise procurement model evolution toward managed service consumption.
Software-defined networking architectures are rendering obsolete traditional hardware-centric core network designs that dominated Iranian operator capex planning. Large enterprises and government agencies are piloting SD-WAN overlays to aggregate multiple access technologies. This shift is compressing equipment refresh cycles and redirecting spending toward software licensing and professional services.
The Communications Regulatory Authority of Iran's infrastructure security mandates are tightening equipment certification protocols and data localization requirements. Domestic testing laboratory capacity constraints are extending approval timelines for imported network hardware. Operators are responding by pre-qualifying alternative vendors and accelerating in-house technical documentation capabilities.
Enterprise buyers are consolidating multi-year managed service agreements that bundle connectivity, security, and collaboration tools. System integrators and specialized telecom resellers are displacing direct operator relationships in mid-market segments. Tehran-based financial services and manufacturing verticals exhibit the strongest concentration of this procurement transformation.
Iran Telecom Market Segmentation

Service type, technology platform, and end-user profile determine capital allocation patterns across Iranian telecom infrastructure. Each dimension shapes regulatory compliance requirements and vendor financing negotiations differently.
Service Type:
Mature prepaid voice services coexist with emerging fiber broadband platforms across Iranian operator portfolios.
- Mobile Services:Prepaid subscriber density drives revenue concentration through voice and data bundles on 4G LTE infrastructure. Tehran's metropolitan corridor absorbs disproportionate network investment for capacity expansion.
- Broadband Services:Fiber-to-the-home deployment displaces aging copper DSL in urban zones, with the Ministry of Information and Communications Technology channeling public investment into last-mile densification targets.
- Fixed-line Services:Legacy PSTN infrastructure maintains rural coverage obligations while subscriber migration accelerates toward mobile substitution.
- VoIP Services:Enterprise unified communications adoption creates demand for managed SIP trunking and cloud-based collaboration platforms.
Mobile Services handles the majority of throughput; Broadband Services is the fastest mover on share.
Technology:
Cost tier stratification separates capital-intensive next-generation deployments from maintenance-heavy legacy infrastructure.
- 4G LTE:Dominant traffic volume across all provinces with nationwide coverage sustaining prepaid data consumption. MTN Irancell leverages scale advantages to maintain rural cell density.
- 5G:Tehran pilot zones validate network slicing for industrial IoT through Huawei-backed deferred payment structures. The Communications Regulatory Authority of Iran's spectrum reallocation policies pressure operators toward these upgrades.
- Fiber Optic:Metro and long-haul transmission backhaul converges mobile and fixed traffic with software-defined networking architectures displacing hardware-centric designs.
- DSL:Copper infrastructure lock-in generates diminishing returns against fiber substitution economics while requiring costly rural maintenance.
4G LTE carries the dominant traffic load; 5G deployment is expanding most quickly in capital deployment terms.
End User:
Customer type determines pricing power and contract structure across Iranian telecom procurement.
- Residential:Prepaid mobile and fiber broadband bundles dominate household expenditure with price sensitivity concentrated in tier-two metropolitan zones.
- Enterprises:Cloud migration and SD-WAN adoption drive managed service consolidation for high-bandwidth connectivity and security requirements.
- Government:Data localization mandates and infrastructure security requirements shape procurement specifications for sovereign network segments.
- Educational Institutions:Campus connectivity upgrades and e-learning platform support create demand for subsidized fiber deployment.
Residential users generate the volume base; Enterprises are climbing the fastest in average revenue per account.
Distribution Channel:
Volume concentration favors direct operator relationships in enterprise segments while retail fragmentation persists in consumer markets.
- Direct Sales:Large enterprise and government accounts negotiate multi-year managed service agreements bundling connectivity and security.
- Retail Stores:Prepaid SIM distribution and subscriber acquisition maintains physical presence in Tehran's commercial corridors.
- Indirect Partners:System integrators and specialized resellers displace direct operator relationships in mid-market enterprise segments.
- Online Sales:Digital self-service platforms support plan management and top-up transactions with limited hardware procurement.
Direct Sales captures the enterprise value pool; Indirect Partners are gaining share fastest in mid-market penetration.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tehran's metropolitan corridor commands pricing premiums that exceed provincial markets by margins reflecting infrastructure density and enterprise demand concentration. Provincial operators absorb higher unit costs for rural coverage obligations while metropolitan zones capture disproportionate capital deployment.
Tehran Province
Enterprise cloud migration and smart city integration drive fiber densification across the capital region. The Communications Regulatory Authority of Iran's spectrum reallocation policies channel 5G pilot investments into base station upgrades. Tehran's central business district hosts concentrated network slicing validation for industrial IoT applications.
Isfahan Province
Manufacturing verticals generate dedicated leased-line demand for data center interconnectivity and managed services. Provincial infrastructure security mandates from the Ministry of Information and Communications Technology shape procurement specifications for sovereign network segments. Isfahan's industrial zones absorb capital for converged fiber and cellular backhaul.
Mashhad Region
Second-tier metropolitan corridors exhibit underserved enterprise demand for high-bandwidth connectivity and unified communications platforms. The Ministry of Information and Communications Technology's urban densification targets extend public investment into last-mile fiber deployment. Mashhad's commercial corridors attract retail presence for prepaid subscriber acquisition.
Tabriz and Northwest Provinces
Cross-border trade corridors generate demand for secure voice and data services linking commercial operators. Data localization requirements from central regulators influence equipment certification timelines for imported network hardware. Tabriz maintains copper infrastructure obligations while fiber substitution economics pressure legacy DSL maintenance budgets.
Shiraz and Southern Provinces
Educational institution connectivity upgrades and e-learning platform support create subsidized fiber deployment demand. Rural coverage obligations extend 4G LTE cell density into diminishing-return territories. Shiraz anchors provincial network operations while smaller cities absorb disproportionate technician deployment costs.
Iran Telecom Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying infrastructure elements. The Iranian telecom market structures around state-backed incumbents with sovereign credit access, international vendors with deferred financing arrangements, and domestic specialists with localized service capabilities. Three archetypes dominate: nationwide mobile operators leveraging scale for coverage density, equipment vendors anchoring technology transitions through vendor-backed payment structures, and fixed-line incumbents exploiting infrastructure ownership for wholesale positioning. Competitive moves concentrate on equipment financing restructuring and spectrum efficiency mandates compliance.
Among international equipment vendors, Huawei Technologies and ZTE occupy positions exemplifying vendor-backed deferred payment structures that enable capital-constrained operators to advance infrastructure modernization. Telecommunication Company of Iran represents the state-backed incumbent archetype with access to sovereign credit lines for rural fiber expansion. MTN Irancell anchors the scale-driven mobile operator tier sustaining nationwide 4G coverage through subscriber density advantages.
| Leading Market Players |
|---|
| Rightel |
| Ericsson |
| Telecommunication Company of Iran |
| ZTE |
| Huawei Technologies |
| Mobile Communications of Iran |
| Shatel |
| Orange |
| MTN Irancell |
| Others |
Value Chain & Pricing Dynamics
Chinese vendor financing concentration for core network equipment anchors margin pools downstream with Iranian operators, shifting procurement economics toward deferred payment structures that compress near-term cash outflows while extending total cost obligations across equipment lifecycles.
Pricing Analysis
Configured-to-order pricing for customized 5G base station deployments commands substantial premiums over standard 4G LTE equipment packages. Three-tier pricing structure across premium, standard, and economy levels segments enterprise managed services from mass-market prepaid subscriptions. Pricing pressure stems from international banking restrictions that constrain vendor payment mechanisms and extend procurement timelines. Residential prepaid subscribers exhibit highest price sensitivity while government accounts tolerate premium positioning for sovereign network segments.
Supply Chain Analysis
Export-control regimes limiting restricted-technology flows from the United States and European Union constrain Iranian operators' access to advanced semiconductor components and optical transmission gear. Supply concentration centers on China for radio access network equipment, South Korea for memory and display components, and domestic assembly for passive infrastructure elements. Critical dependencies include RF power amplifiers, fiber optic transceivers, and baseband processing units. Single-source vulnerability pervades core network hardware procurement. Distribution runs through state-affiliated procurement channels and vendor-direct relationships with limited wholesale intermediation.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortages of RF planning expertise and fiber splicing technicians constrain rollout velocity across Iranian infrastructure deployment, creating capability bottlenecks that advantage operators with in-house training programs and established contractor relationships.
For Market Incumbents: Pre-empt spectrum efficiency mandates by accelerating 5G pilot zone densification in Tehran's metropolitan corridor before regulatory deadlines tighten. Secure vendor-backed deferred payment structures with Chinese equipment suppliers to preserve capital access amid international banking restrictions. Invest in captive technical training programs to reduce contractor dependency for fiber splicing and RF optimization. For New Entrants and Emerging Players: Mid-market enterprise segments in Mashhad and Isfahan represent the most penetrable entry points for specialized SD-WAN and managed security service offerings. Second-tier metropolitan zones exhibit underserved demand for dedicated leased-line services with limited incumbent focus. Partner with system integrators already displacing direct operator relationships rather than building proprietary sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward domestic equipment sourcing specialists positioned to benefit from local content requirements and infrastructure security mandates. Long-term viability hinges on regulatory alignment with the Communications Regulatory Authority of Iran's certification protocols and data localization trajectory. Monitor foreign vendor restriction announcements as the critical inflection signal for equipment procurement optionality.| Strategic Initiative | Industry Significance |
|---|---|
| Vendor Financing Restructuring | Deferred payment structures with Huawei and ZTE enable capital-constrained operators to advance 5G infrastructure modernization despite banking restrictions. |
| Spectrum Efficiency Investment | Network slicing capabilities in Tehran pilot zones validate industrial IoT applications ahead of Communications Regulatory Authority reallocation deadlines. |
| Domestic Equipment Sourcing | Local content requirements create openings for indigenous base station component manufacturing and software-defined networking development. |
| Enterprise Managed Service Bundling | Multi-year agreements consolidating connectivity, security, and collaboration tools capture mid-market procurement transformation away from direct operator relationships. |
| Fiber Densification Partnership | Public-private coordination with the Ministry of Information and Communications Technology channels investment into last-mile urban deployment targets. |
Study Parameters
Initial hypotheses were tested against primary input from network engineering directors, procurement leads at Iranian mobile operators, regulatory affairs specialists at the Communications Regulatory Authority of Iran, and enterprise IT managers in Tehran's financial services vertical and refined through secondary validation against equipment vendor disclosures, customs import records, Ministry of Information and Communications Technology policy documents, and operator financial filings. Bottom-up subscriber and traffic volume estimates were triangulated against top-down infrastructure capacity and capital expenditure allocations.
Demand-supply balance modeling across the analysis window integrated service type segmentation by mobile, broadband, fixed-line, and VoIP platforms with technology tier stratification across 4G LTE, 5G, fiber optic, and DSL infrastructure. End-user archetypes spanning residential, enterprise, government, and educational institutions shaped pricing elasticity assumptions. CAGRs were derived from equipment deployment trajectories, spectrum allocation timelines, and enterprise cloud migration velocity without reliance on single-source projections.
Practitioners should monitor foreign vendor restriction announcements, spectrum reallocation timeline adjustments, and international banking sanction modifications for early signals of forecast revision. Cross-checking against Infrastructure and Telecommunications Company of Iran capex disclosures and Communications Regulatory Authority licensing data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Denmark Telecom Market
Telecommunications
Brazil Telecom Market
Telecommunications
MVNO Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Global Telecommunication Market
Telecommunications
Germany ICT Market
Telecommunications
South Africa Telecom Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
Poland Telecom Market
Telecommunications
5G Transport Networks Market
Telecommunications
France Telecom Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Austria ICT Market