
 Missiles and Missile Defense Systems Market | 2026-2036
Missiles and Missile Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Missiles and Missile Defense Systems Market Foresight
Naval modernization is recalibrating procurement priorities across NATO and Indo-Pacific fleets. Lockheed Martin Corporation dominates directed-energy and hit-to-kill interceptor development for Aegis-equipped destroyers. RTX Corporation (Raytheon Technologies) sustains production of Standard Missile family interceptors with continuous software-defined upgrades. MBDA specializes in naval point-defense systems, leveraging European consortium access to Franco-Italian and British fleet requirements.
Missiles and missile defense systems comprise propulsion, guidance, and warhead subsystems engineered to Mach 3+ velocities with infrared and radar dual-mode seekers for terminal engagement. Their primary purpose spans strategic deterrence, area air defense, and precision strike against fixed and mobile targets. Ballistic Missiles and Surface-to-Air Missiles capture the largest value pools given nuclear delivery mandates and integrated air defense network replacements. Sea-Based installations represent the fastest-expanding segment as naval theaters multiply and destroyer hull counts rise across Pacific Rim navies.
The U.S. Department of Defense, NATO's NATO Support and Procurement Agency, and Japan's Ministry of Defense shape demand through cooperative development frameworks and foreign military sale protocols. U.S. Missile Defense Agency test schedules and Japanese BMD system deployments directly determine production lot sizes and technology transfer permissions. Stakeholders must track hypersonic defense test outcomes and allied burden-sharing negotiations to anticipate procurement cycle timing and interceptor architecture shifts.
Market Dynamics
Hypersonic glide vehicle proliferation is forcing a fundamental recalibration of interceptor kinematics and sensor fusion architectures across NATO and Indo-Pacific defense planners. The gap between threat velocity and defensive response time has compressed from minutes to seconds, demanding entirely new propulsion and guidance paradigms.
Growth Catalysts
- Japan's BMD System Deployments:Tokyo's Ministry of Defense procurement schedules for Aegis Ashore alternatives and ship-based SM-3 Block IIA interceptors sustain multi-year production commitments from U.S. prime contractors.
- Directed-Energy Maturation:Solid-state laser and high-power microwave systems are transitioning from testbed to operational deployment aboard U.S. Navy destroyers, creating demand for power management and thermal control subsystems.
- Indo-Pacific Territorial Disputes:Layered defense deployments across the South China Sea and East China Sea theater drive procurement of short-range point defense and medium-range area air defense batteries.
Market Restraints
- Rare Earth Magnet Supply Concentration:Guidance system actuators and radar T/R modules depend on neodymium and dysprosium processing concentrated in Chinese refining facilities, creating single-source vulnerability.
- ITAR Classification Friction:U.S. State Department export control protocols restrict technology transfer to allied cooperative development programs, lengthening procurement cycles for integrated NATO and Indo-Pacific systems.
- Hypersonic Interceptor Cost Structure:Hit-to-kill vehicles with multi-spectral seekers and divert thrusters require precision manufacturing tolerances that resist scale economies, constraining procurement volume.
Strategic Opportunities
- Australian Nuclear-Powered Submarine Integration:The AUKUS framework creates demand for vertical launch system-compatible interceptors and undersea communications relay infrastructure.
- Modular Open Systems Architecture:U.S. Department of Defense mandates for software-defined upgrades and hardware interchangeability enable non-traditional suppliers to enter subsystem markets.
- Space-Based Sensor Layer:Hypersonic and Ballistic Tracking Space Sensor deployment schedules create procurement pull for ground station integration and data fusion processors.
Industry Challenges
- Seeker Algorithm Talent Scarcity:Machine learning expertise for target discrimination in cluttered environments concentrates in commercial autonomous vehicle and consumer electronics sectors, not traditional defense labor pools.
- Legacy System Integration Complexity:New interceptors must interface with fielded Patriot, Aegis, and THAAD command-and-control networks using decades-old data bus standards and proprietary protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Missiles and Missile Defense Systems Market |
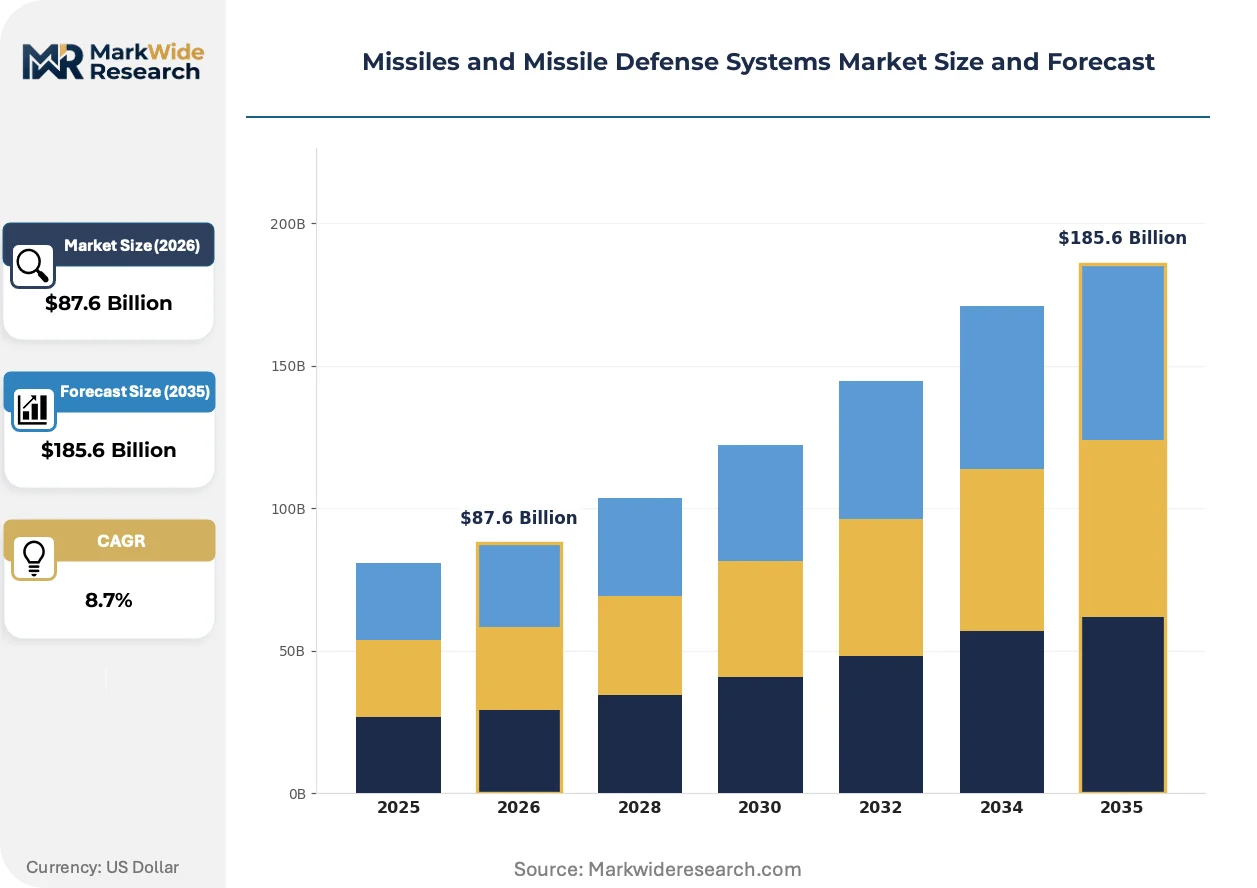
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $185.6 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Missiles, Cruise Missiles, Air-to-Air Missiles, Surface-to-Air Missiles Technology: Guided Systems, Unmanned Aerial Vehicles, Radar Systems, Sensor Systems End User: Government Agencies, Defense Contractors, Military Organizations, Research Institutions Installation: Ground-Based, Sea-Based, Airborne Systems, Mobile Units |
| Companies Covered | Northrop Grumman Corporation, L3Harris Technologies Inc., Lockheed Martin Corporation, China Aerospace Science and Technology Corporation (CASC), Israel Aerospace Industries, RTX Corporation (Raytheon Technologies), General Dynamics Corporation, MBDA, The Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Missiles and Missile Defense Systems Market Shifts & Advancements
Active electronically scanned array miniaturization and gallium nitride amplifier maturation are compressing radar front-end size and power draw, enabling distributed sensor architectures previously constrained by platform volume.
Multi-domain command-and-control software is absorbing functions previously executed by standalone fire control computers, collapsing hardware stack layers and reducing latency between sensor detection and interceptor launch authorization. U.S. Army Integrated Air and Missile Defense Battle Command System deployments are accelerating this consolidation, compressing vendor count in the C2 segment.
EU defense procurement coordination through the European Defence Fund and Permanent Structured Cooperation framework is mandating cross-border consortium participation for interceptor development contracts. This regulatory architecture fragments national industrial base preferences, forcing Franco-German-Italian joint ventures for medium-range systems that previously sustained single-country production lines.
Allied burden-sharing negotiations are shifting procurement from Foreign Military Sale to cooperative development with technology transfer provisions. Japanese and Australian defense ministries now demand in-country final assembly and software access for Aegis-compatible systems, displacing turnkey U.S. delivery models that dominated prior decades.
Missiles and Missile Defense Systems Market Segmentation
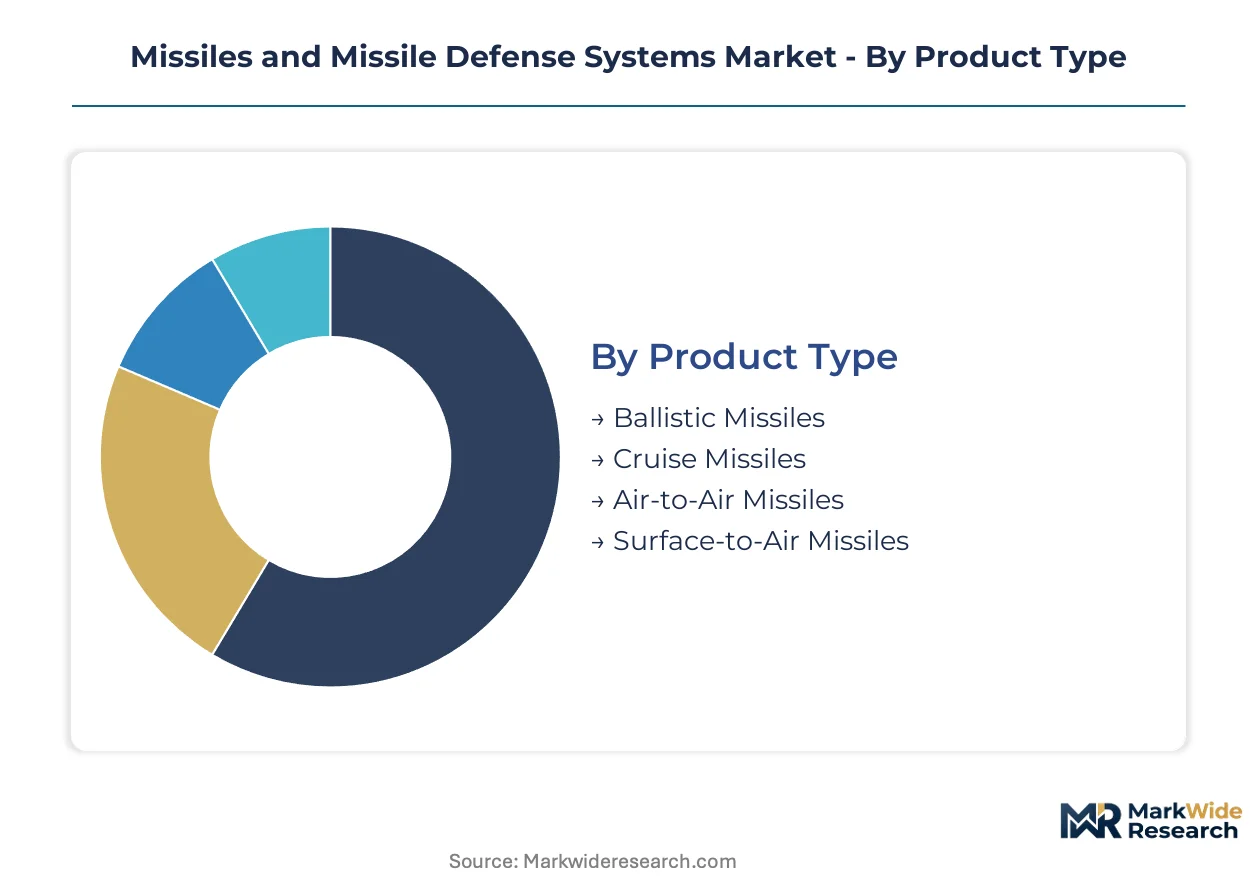
Missiles and missile defense systems fragment across four critical dimensions that determine procurement pathways, technology transfer protocols, and lifecycle sustainment economics. Each segmentation axis carries distinct supply chain vulnerabilities and customer concentration profiles that shape vendor positioning.
Product Type:
Supply concentration for propulsion and guidance subsystems varies sharply across product categories, with solid-fuel motor production and seeker manufacturing clustering among a handful of defense primes.
- Ballistic Missiles:These systems employ multi-stage solid or liquid propulsion architectures to deliver nuclear or conventional payloads along ballistic trajectories. Demand concentrates in nuclear deterrent modernization programs across the United States, Russia, and China, constrained by treaty verification protocols and fissile material stockpile limitations.
- Surface-to-Air Missiles:Interceptor systems integrate radar command guidance with infrared terminal homing for aircraft and missile engagement. Procurement concentrates in Indo-Pacific layered defense deployments, driven by territorial dispute escalation and integrated air defense network replacement cycles.
- Cruise Missiles:Turbofan-powered precision strike weapons with terrain-following navigation and electro-optical terminal guidance. Naval strike and land-attack variants sustain production lines for U.S. and allied standoff weapon requirements.
- Air-to-Air Missiles:Short and medium-range interceptors with thrust-vectoring agility and helmet-mounted cueing integration. Fighter fleet modernization across NATO and Pacific Rim air forces determines production lot sizing.
Ballistic Missiles absorb the bulk of installed capacity; Surface-to-Air Missiles are expanding most quickly.
Technology:
Cost tier differentiation separates mature analog systems from software-defined architectures demanding continuous firmware refresh cycles and cybersecurity hardening.
- Guided Systems:Inertial navigation platforms augmented by GPS and terrain-reference updating for precision delivery. Demand clusters in precision strike modernization programs requiring meter-level accuracy against relocatable targets.
- Radar Systems:Active electronically scanned arrays with gallium nitride transmit-receive modules for multi-target tracking. Naval fleet air defense upgrades and ground-based early warning networks drive procurement timing.
- Sensor Systems:Multi-spectral seekers combining infrared, millimeter-wave, and laser radar channels for target discrimination. Hypersonic defense requirements are accelerating focal plane array and signal processor development.
- Unmanned Aerial Vehicles:Loitering munitions and reconnaissance platforms with autonomous targeting algorithms. Electronic warfare integration and swarm coordination capabilities are reshaping subsystem specifications.
Radar Systems command the highest unit economics; Sensor Systems are climbing the fastest amid hypersonic tracking imperatives.
End User:
Customer type determines contracting mechanisms, with foreign military sales, cooperative development, and direct commercial sale each imposing distinct compliance and technology access boundaries.
- Government Agencies:National defense ministries and missile defense agencies specifying operational requirements and funding multi-year procurement. Budget authorization cycles and threat assessment revisions create demand volatility.
- Military Organizations:Service branches managing fleet integration, operator training, and depot-level maintenance. Platform-specific certification requirements constrain vendor substitution.
- Defense Contractors:Prime and subsystem suppliers executing design, manufacture, and sustainment under cost-plus and fixed-price arrangements. ITAR and export control classifications limit supplier pool expansion.
- Research Institutions:National laboratories and university affiliates advancing propulsion, materials, and algorithmic foundations. Cooperative research agreements bridge basic science and engineering development.
Government Agencies control funding authorization; Military Organizations are gaining procurement autonomy through delegated contracting authority.
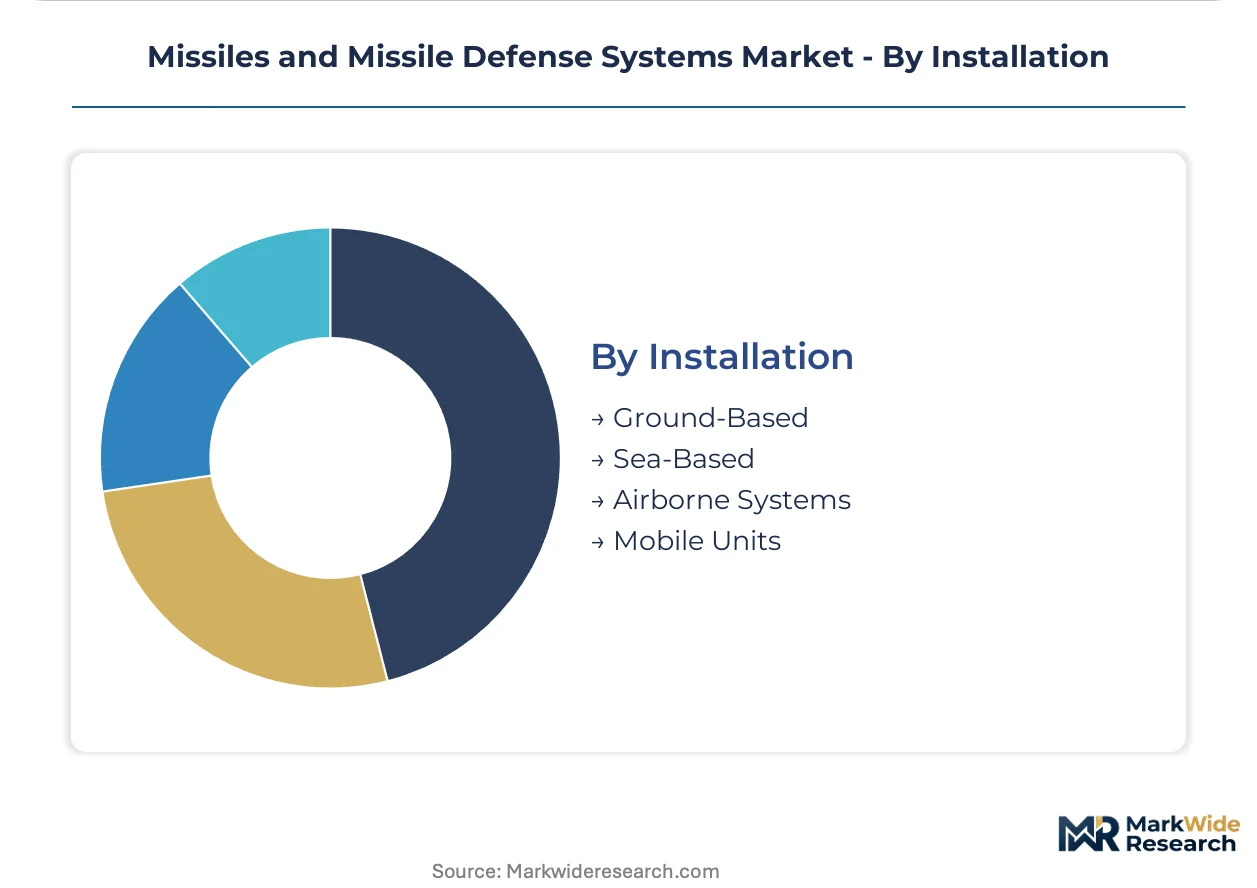
Installation:
Platform integration demands dictate form factor, environmental hardening, and electromagnetic compatibility specifications that fragment engineering requirements across deployment modes.
- Sea-Based:Vertical launch system-compatible interceptors with salvo firing and shipboard radar cueing. Destroyer hull construction schedules across Pacific Rim navies are accelerating procurement.
- Ground-Based:Fixed-site and mobile launchers with transportable radar and command modules. European and Middle Eastern territorial defense deployments sustain production commitments.
- Airborne Systems:Fighter and bomber carriage with pylon integration and cockpit display interfaces. Fifth-generation fighter fleet expansion determines missile rack and launcher demand.
- Mobile Units:Road and rail transportable systems with rapid emplacement and displacement protocols. Contingency response and forward deployment requirements drive lightweight launcher development.
Ground-Based installations retain the largest deployed base; Sea-Based systems are gaining share fastest amid naval modernization acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense industrial zones and shipyard corridors concentrate missile system production. Tax-advantaged manufacturing districts in coastal states and aerospace clusters sustain prime contractor final assembly and subsystem supplier networks.
United States
Aegis destroyer construction at Bath Iron Works and Ingalls Shipbuilding sustains sea-based interceptor demand. The U.S. Missile Defense Agency test schedules at Pacific Spaceport Complex Alaska and Vandenberg Space Force Base determine production lot authorizations. Tucson, Arizona and Huntsville, Alabama anchor solid-rocket motor and guidance system manufacturing corridors.
Japan
Ministry of Defense procurement for Aegis-equipped destroyers and SM-3 Block IIA interceptors drives multi-year commitments. Japan's defense production base guidelines mandate in-country final assembly for BMD systems, displacing turnkey U.S. delivery. Nagasaki and Yokohama shipyards integrate vertical launch systems with domestic radar cueing architectures.
Israel
Iron Dome and Arrow system deployments sustain tiered defense production lines against short-range and ballistic threats. Israel's Ministry of Defense Directorate of Defense Research and Development governs technology transfer protocols for cooperative programs. Rafael Advanced Defense Systems and Israel Aerospace Industries cluster around Haifa's defense technology corridor.
United Kingdom
MOD procurement through the Defence Equipment and Support organization funds MBDA consortium participation in European missile programs. The UK's Defense and Security Industrial Strategy mandates sovereign capability retention for nuclear deterrent and complex weapons. Stevenage and Bristol house guidance system integration facilities for Storm Shadow and naval point-defense programs.
South Korea
Korea Aerospace Industries and LIG Nex1 scale domestic L-SAM and M-SAM production for layered air defense modernization. The Defense Acquisition Program Administration accelerates indigenous seeker and propulsion development through offset agreements. Seongnam and Sacheon concentrate radar and missile integration facilities for KF-21 and destroyer programs.
Missiles and Missile Defense Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with system integrators capturing value from interceptor production while subsystem suppliers compete on sensor and propulsion components. Market structure concentrates around five to seven prime contractors with established government relationships, tiered beneath a fragmented base of component specialists. Two strategic archetypes dominate: vertically integrated defense primes with captive seeker and motor production, and consortium-based entities pooling national industrial bases. Competitive moves center on cooperative development frameworks with technology transfer provisions, and modular open systems architecture compliance to displace legacy proprietary protocols.
Within the vertically integrated tier, Lockheed Martin Corporation and RTX Corporation anchor U.S. sea-based and ground-based interceptor portfolios. MBDA represents the consortium archetype, pooling French, British, and Italian industrial access to European procurement frameworks. Northrop Grumman Corporation occupies a position in directed-energy and space-based sensor layer development, reflecting prime contractor diversification into next-generation architectures.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| L3Harris Technologies Inc. |
| Lockheed Martin Corporation |
| China Aerospace Science and Technology Corporation (CASC) |
| Israel Aerospace Industries |
| RTX Corporation (Raytheon Technologies) |
| General Dynamics Corporation |
| MBDA |
| The Boeing Company |
| Others |
Supply & Pricing Matrix
Solid-state laser maturation aboard U.S. Navy destroyers is compressing thermal management and power electronics costs while concentrating procurement leverage among three prime contractors with captive gallium nitride foundry access. This technology transition simultaneously reshapes unit economics and supplier tiers across directed-energy and kinetic interceptor programs.
Pricing Analysis
Short lead-time premiums dominate contract structures for SM-3 Block IIA and THAAD interceptors, with spot inventory discounts rare given ITAR-controlled production queues. Three-tier pricing structure across developmental prototypes, low-rate initial production, and full-rate manufacturing separates congressional authorization timing from per-unit cost curves. Pricing pressure stems from hypersonic interceptor precision tolerances resisting scale economies. Foreign military sale customers exhibit highest price sensitivity; U.S. Missile Defense Agency commitments show lowest.
Supply Chain Analysis
Regional distribution centers in Tucson, Huntsville, and Stevenage anchor hub-and-spoke patterns for solid-rocket motors and guidance electronics. Supply concentrates in the United States, United Kingdom, and Japan for seeker integration and propulsion subsystems. Neodymium and dysprosium refining rests on Chinese processing facilities. Single-source vulnerability in rare earth magnet supply creates tariff exposure. Distribution runs through defense prime contractor logistics networks with classified handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Captive gallium nitride foundry capacity and in-house seeker algorithm development represent the decisive upstream levers separating prime contractors from subsystem-dependent competitors.
For Market Incumbents: Extend software-defined upgrade roadmaps to displace proprietary legacy protocols in fielded Patriot and Aegis networks. Acquire machine learning talent pools from autonomous vehicle sectors to close seeker algorithm gaps. Hypersonic defense test failures threaten production lot authorizations. Backward integration into rare earth magnet recycling mitigates Chinese supply concentration. For New Entrants and Emerging Players: Defense contractor tier-2 suppliers offer the most penetrable channel for modular open systems architecture compliance. Target Australian and Japanese final assembly mandates as white-space entry points. White-space exists in ground station integration for Space-Based Sensor Layer deployments. Pursue cooperative development frameworks with technology transfer provisions as primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in prime contractor acquisition of sensor fusion and directed-energy specialists. Long-term viability hinges on hypersonic interceptor production scale and allied burden-sharing negotiation outcomes. Acquisition target archetype: mid-tier firms with ITAR-compliant facilities and software-defined architecture expertise. Watch hypersonic glide vehicle test outcomes as inflection indicator for interceptor architecture shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cooperative Development Framework | Japanese and Australian in-country assembly mandates displace turnkey U.S. delivery models. |
| Modular Open Systems Architecture Compliance | U.S. Department of Defense mandates enable non-traditional subsystem supplier entry. |
| Gallium Nitride Foundry Investment | Captive T/R module production secures radar miniaturization cost advantages. |
| Machine Learning Talent Acquisition | Target discrimination algorithms concentrate in commercial autonomous vehicle sectors. |
| Rare Earth Magnet Recycling Facility | Neodymium recovery from fielded systems reduces Chinese refining dependency. |
Research Methodology
Multi-period observation of U.S. Missile Defense Agency test schedules and Japanese Ministry of Defense procurement authorizations anchored the trend analysis, supplemented by interviews with program managers at prime contractors, guidance system engineers at national laboratories, procurement officers at NATO Support and Procurement Agency, and fleet integration leads at Indo-Pacific navies. Secondary validation drew from U.S. Department of Defense budget justification materials, NATO cooperative development framework documents, Japanese defense production base guidelines, and SEC filings from publicly traded defense primes. Bottom-up production lot sizing and top-down threat assessment modeling were triangulated.
Input-output matrices connected interceptor platform demand to subsystem supplier capacity across product type, technology tier, end-user contracting mechanism, and installation platform dimensions. CAGRs were derived from production authorization trajectories and allied procurement commitment schedules. Hypersonic defense test outcomes, Aegis destroyer hull construction timelines, and burden-sharing negotiation progress served as industry-specific forecast inputs across the modeling period.
Several conditions sit outside the modeled scope, including classified threat velocity specifications, treaty-limited ballistic missile production ceilings, and sudden export control reclassifications. Forecasts reflect documented assumptions regarding test success rates and congressional authorization continuity. Periodic stress-testing of base assumptions is recommended given hypersonic interceptor cost structure constraints and rare earth supply vulnerability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
Global Military Laser Designator Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market