
 India Defense Market | 2026-2036
India Defense Market Size, Share, and Industry Trends Forecast 2026-2036
India Defense Market Outlook
Market Context
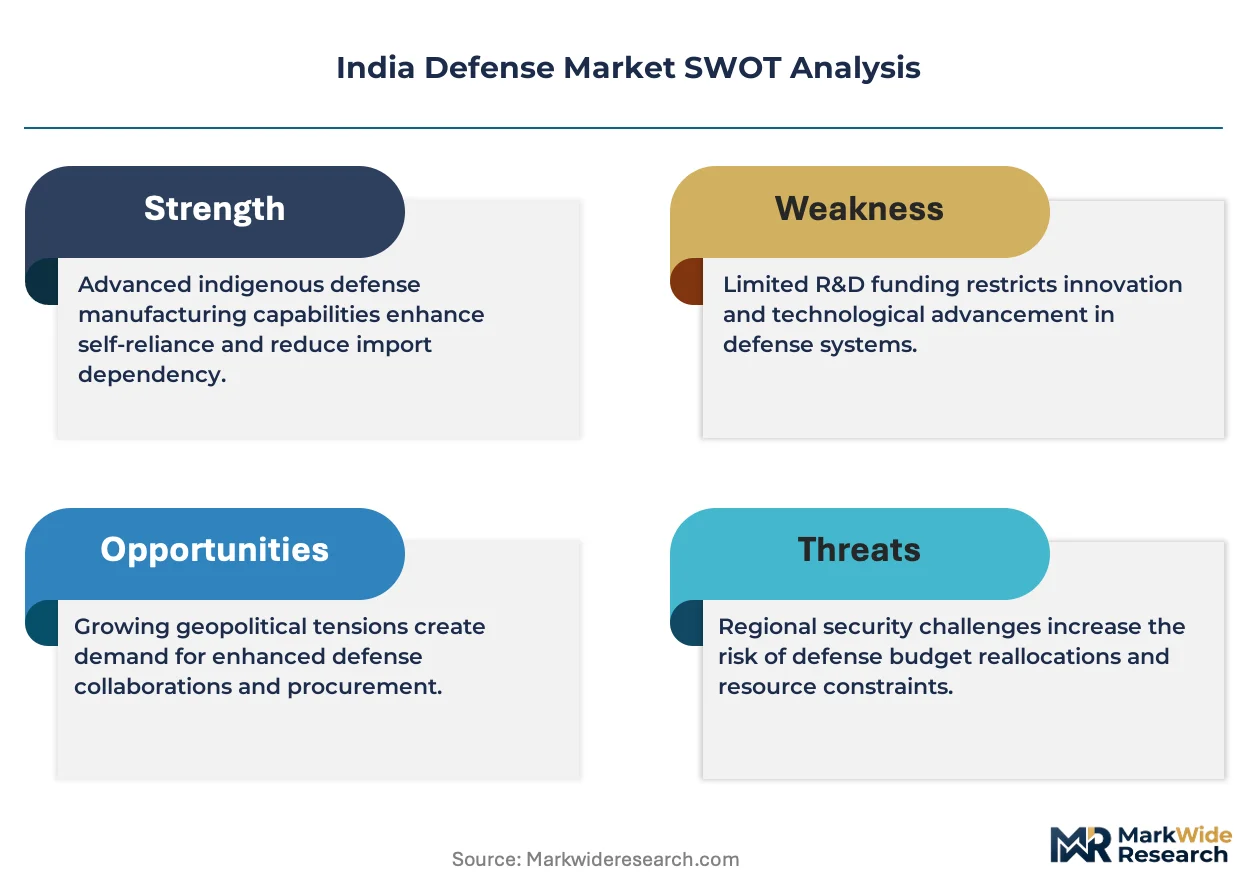
The capital-intensity divergence between players is rotating procurement advantage toward firms with captive metallurgical and propulsion capabilities. Hindustan Aeronautics Limited leverages its integrated aero-engine test facilities to dominate fighter aircraft upgrades. Bharat Electronics Limited anchors India's radar and electronic warfare supply chain through in-house semiconductor packaging lines. Mazagon Dock Shipbuilders Limited sustains submarine construction leadership via its pressure hull forging partnerships with domestic steel mills.
Technical Definition and Structural Segments
India Defense encompasses the design, engineering, and production of military platforms, subsystems, and support services governed by stringent indigenous content thresholds and offset obligations. The sector spans metallurgical grades such as DMR-249A naval steel and composites for airborne structures, with primary purpose being sovereign deterrence capability and force modernization for tri-service operational readiness. Aircraft and naval vessels command the deepest procurement cycles and longest supplier qualification timelines, while cybersecurity solutions within the technology dimension attract the fastest contract velocity from intelligence agencies. The missiles product type occupies concentrated margin pools due to restricted foreign vendor access and controlled propellant chemistry know-how.
Regulatory Framework
The Ministry of Defence's Defence Acquisition Procedure, coupled with the Department of Defence Production's iDEX framework and CEA power allocation mandates for manufacturing clusters, shapes vendor eligibility through indigenization tiering and local value-add thresholds. BIS certification for military-grade materials and DGFT export control classifications further constrain supply base participation to qualified domestic entities. Stakeholders must monitor how the PLI scheme for drone components and emerging SAMR-style dual-use technology controls recalibrate competitive entry barriers across the supplier pyramid.
Market Dynamics
The Defence Acquisition Procedure's indigenization tiering is compressing foreign vendor participation while elevating domestic metallurgical and propulsion capabilities as procurement gatekeepers.
Growth Catalysts
- iDEX framework:The Department of Defence Production's innovation platform is channeling seed funding toward dual-use drone startups and AI-enabled surveillance systems, accelerating technology maturation timelines for army and navy applications.
- Naval shipbuilding corridor:Concentrated demand across Mumbai, Visakhapatnam, and Kochi is driving specialized steel forging capacity expansion and pressure hull fabrication expertise at Mazagon Dock and partner mills.
- CEA power allocation mandates:Guaranteed electricity supply for defense manufacturing clusters is reducing operational uncertainty for precision machining and heat treatment processes critical to aero-engine production.
Market Restraints
- DMR-249A steel supply concentration:Domestic production of naval-grade steel remains captive to three integrated steel mills, creating single-source vulnerability for submarine and destroyer hull fabrication.
- Offset obligation complexity:DGFT export control classifications and foreign vendor offset calculations are elongating contract finalization timelines and increasing compliance overhead for tier-2 suppliers.
- Propellant chemistry import dependence:Controlled energetic materials and solid-fuel precursors remain subject to international non-proliferation restrictions, constraining missile production autonomy.
Strategic Opportunities
- PLI scheme for drone components:Production-linked incentives for unmanned aerial systems are opening component-level entry points for electronics and composite airframe specialists previously excluded from prime contracting.
- Semiconductor packaging localization:Bharat Electronics' in-house chip packaging lines demonstrate viability for radar and electronic warfare subsystem indigenization, creating supplier qualification pathways for fabless design houses.
- Cybersecurity procurement velocity:Intelligence agency demand for network defense solutions operates on compressed contract cycles compared to platform procurement, enabling faster revenue recognition for software-focused vendors.
Industry Challenges
- Aero-engine test facility scarcity:Hindustan Aeronautics Limited's integrated test beds represent the sole domestic qualification pathway, creating bottlenecks for fighter upgrade program schedules and vendor certification.
- BIS military-grade certification timelines:Bureau of Indian Standards validation for specialized alloys and composites extends 18-24 months, delaying supplier onboarding for critical subsystems.
- Tri-service integration complexity:Army, Navy, and Air Force platform modernization cycles operate on mismatched procurement rhythms, complicating joint program coordination and common subsystem adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Defense Market |
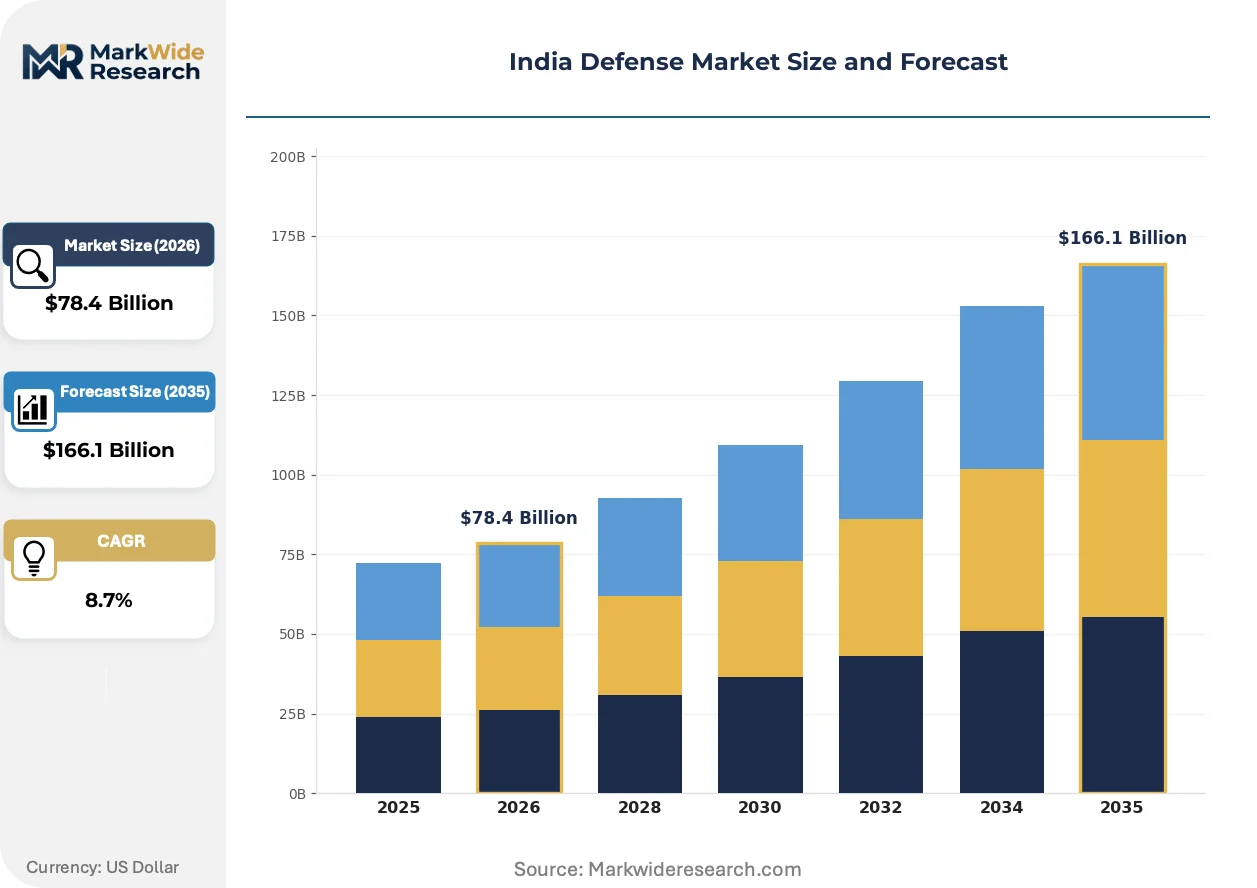
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $166.1 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Armored Vehicles, Aircraft, Naval Vessels, Missiles Technology: Cybersecurity Solutions, Communication Systems, Radar Systems, Drones End User: Military, Paramilitary, Intelligence Agencies, Government Service Type: Maintenance, Logistics, Training, Consulting |
| Companies Covered | Mazagon Dock Shipbuilders Limited, Bharat Forge Limited, Hindustan Aeronautics Limited, MTAR Technologies Limited, Cochin Shipyard Limited, Bharat Electronics Limited, Bharat Dynamics Limited, Paras Defence and Space Technologies Limited, Solar Industries India Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Defense Market Strategic Shifts
Active materials and sovereign manufacturing mandates are restructuring competitive entry barriers across India's defense supplier pyramid.
Carbon-ceramic brake systems for armored vehicles are displacing conventional steel disc assemblies in mechanized infantry modernization programs. The Army's armored platform procurement specifications now prioritize thermal management and weight reduction for desert and high-altitude deployment. Domestic forging partnerships are capturing this transition through captive metallurgical process development.
PLI scheme expansion into drone subsystems is redirecting component sourcing from import-dependent channels toward qualified domestic electronics packaging and composite fabrication facilities. The Department of Defence Production's tiered incentive structure rewards local value-add thresholds for flight controllers, propulsion systems, and sensor payloads. Tier-2 suppliers in Bengaluru and Hyderabad are reconfiguring production lines to capture these qualification pathways.
Service unbundling is separating platform lifecycle support from initial procurement contracts across naval vessel programs. The Navy's submarine and surface combatant fleets are driving independent maintenance, repair, and overhaul competition at Visakhapatnam and Kochi facilities. This fragmentation creates specialized aftermarket entry points for propulsion and combat system integrators previously locked out of prime construction awards.
India Defense Market Segmentation
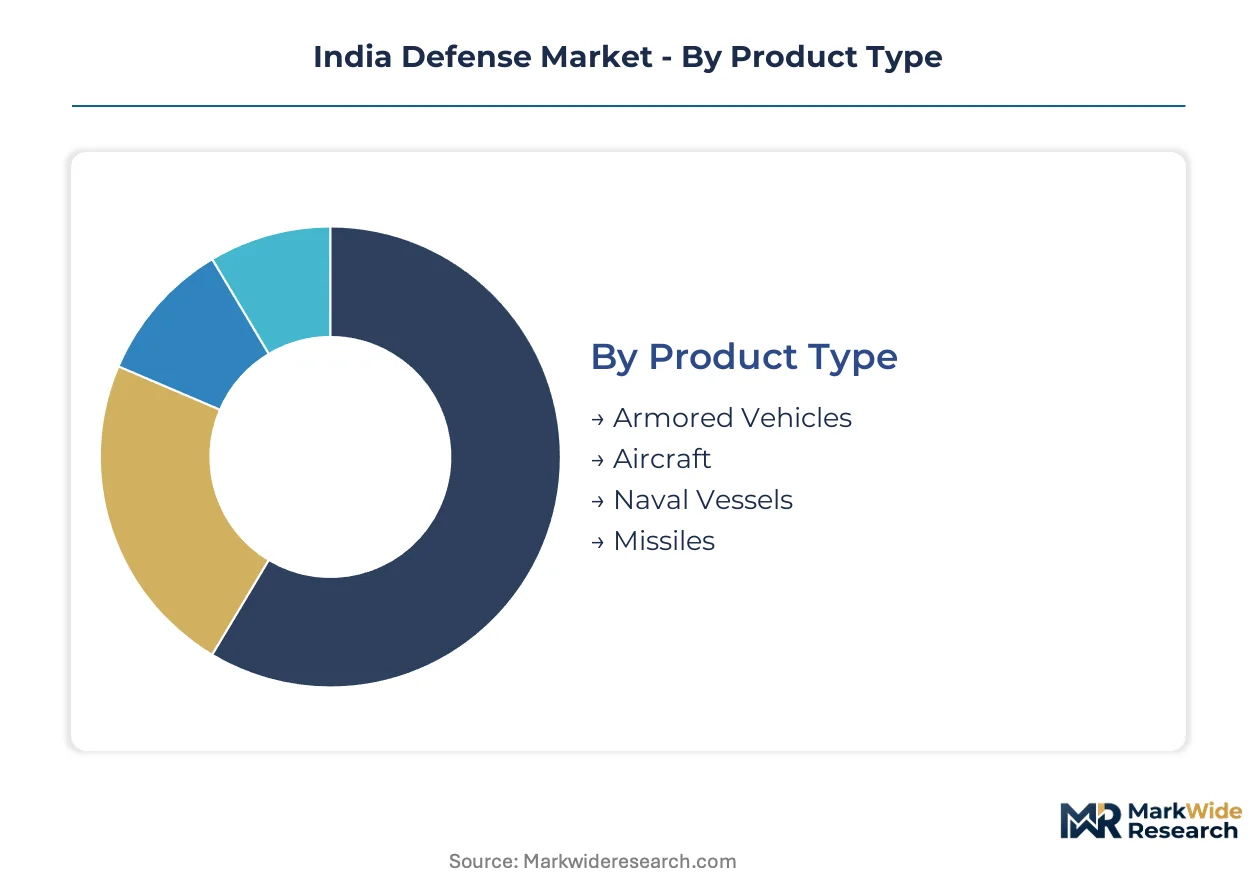
Segmentation in India's defense market reveals how procurement cycles, indigenization mandates, and service unbundling create distinct competitive arenas. Each dimension exposes different capability requirements and qualification barriers for domestic and foreign vendors.
Product Type:
Margin pools concentrate in platforms requiring sovereign metallurgical and propulsion capabilities, with naval and aerial systems commanding the longest supplier maturation timelines.
- Naval Vessels:Submarine and surface combatant construction demands DMR-249A naval steel and pressure hull forging partnerships with domestic mills. Mumbai, Visakhapatnam, and Kochi anchor concentrated demand for specialized fabrication capacity at Mazagon Dock and partner facilities.
- Aircraft:Fighter platforms and upgrade programs require integrated aero-engine test facilities, creating bottlenecks at Hindustan Aeronautics Limited's captive qualification pathways. Thermal management specifications for desert and high-altitude deployment are accelerating carbon-ceramic brake adoption in mechanized variants.
- Missiles:Restricted foreign vendor access and controlled propellant chemistry know-how protect concentrated margin pools for domestic specialists navigating international non-proliferation restrictions on solid-fuel precursors.
- Armored Vehicles:Mechanized infantry modernization drives procurement of platforms with weight reduction and thermal management priorities for varied terrain deployment.
Naval vessels hold installed capacity. Missiles are rotating up the share rankings.
Technology:
Contract velocity diverges sharply across this category, with software-intensive systems outpacing hardware-heavy platforms in procurement cycle compression.
- Cybersecurity Solutions:Intelligence agency demand for network defense operates on compressed contract cycles compared to platform procurement, enabling faster revenue recognition. SAMR-style dual-use technology controls are recalibrating competitive entry barriers for software-focused vendors.
- Drones:PLI scheme incentives for unmanned aerial systems are redirecting component sourcing toward qualified domestic electronics packaging and composite fabrication facilities in Bengaluru and Hyderabad.
- Radar Systems:Bharat Electronics anchors supply chain leadership through in-house semiconductor packaging lines, demonstrating viability for electronic warfare subsystem indigenization.
- Communication Systems:Tri-service integration complexity complicates joint program coordination as Army, Navy, and Air Force modernization cycles operate on mismatched procurement rhythms.
Radar systems hold installed capacity. Cybersecurity solutions are expanding most quickly.
End User:
Procurement authority fragmentation across this category creates tiered access pathways, with prime contracting eligibility narrowing toward military and intelligence channels.
- Military:Tri-service platform modernization spans mechanized infantry, naval combatants, and fighter aircraft, with Defence Acquisition Procedure reforms streamlining indigenization mandates across all three branches.
- Intelligence Agencies:Network defense and surveillance technology demand operates outside standard platform procurement cycles, creating accelerated vendor qualification pathways for specialized contractors.
- Paramilitary:Internal security applications drive demand for surveillance drones and communication systems with lower technical thresholds than military-grade specifications.
- Government:Civilian defense infrastructure and dual-use technology adoption follow distinct procurement protocols with separate offset obligation calculations.
The military holds installed capacity. Intelligence agencies are gaining share fastest.
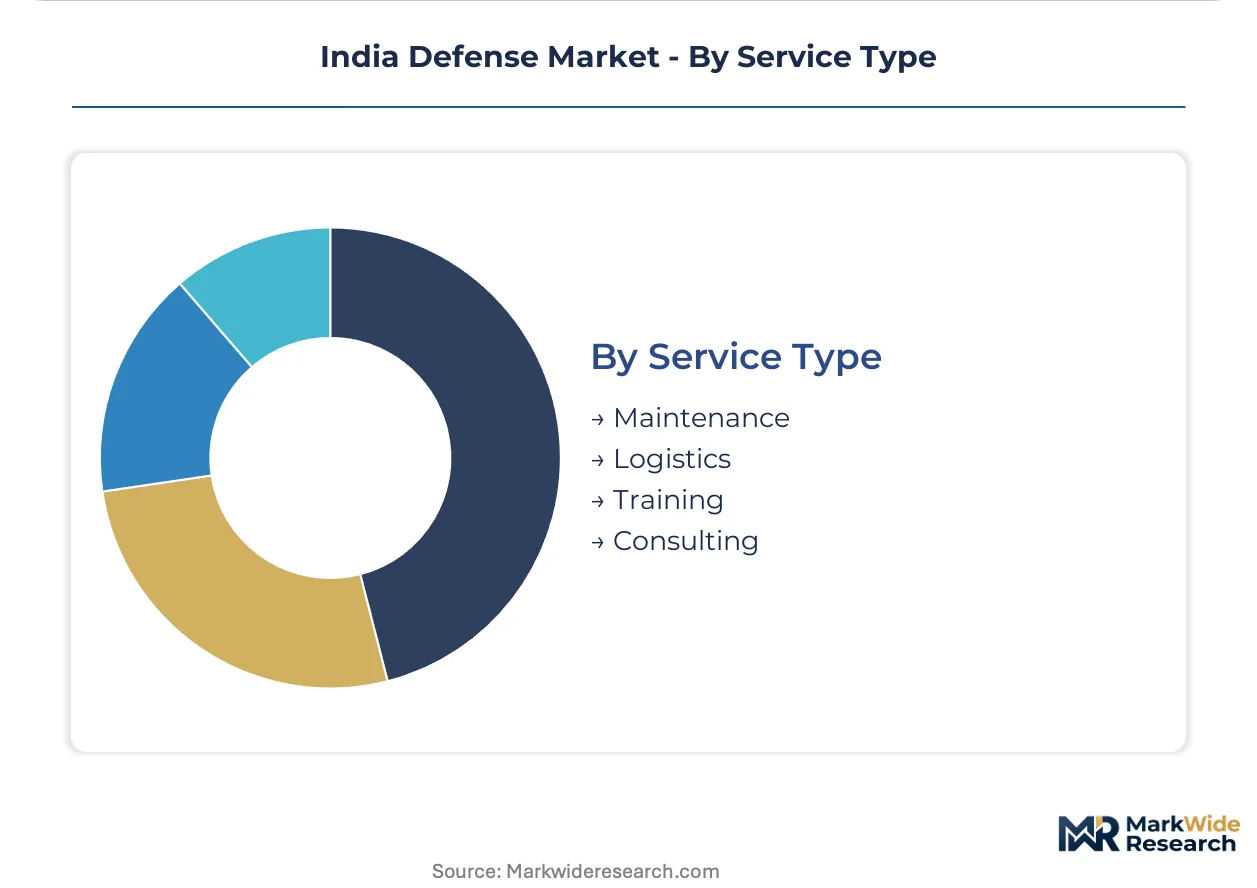
Service Type:
Platform lifecycle economics are unbundling initial procurement from recurring revenue streams, with aftermarket specialization emerging as a distinct competitive arena.
- Maintenance:Service unbundling across naval vessel programs is creating independent competition for submarine and surface combatant upkeep at Visakhapatnam and Kochi facilities.
- Logistics:Supply chain localization mandates under iDEX and PLI frameworks are redirecting spare parts sourcing toward domestic tier-2 suppliers previously excluded from prime contracting.
- Training:Simulator and virtual environment procurement follows technology acquisition timelines rather than platform construction cycles, enabling faster contract velocity.
- Consulting:Offset obligation complexity and DGFT export control classifications drive demand for compliance advisory services among foreign vendors and domestic tier-2 suppliers.
Maintenance holds installed capacity. Logistics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across India's defense procurement landscape. Platform buyers at Mazagon Dock and Hindustan Aeronautics Limited absorb premium costs for sovereign capability, while tier-2 component vendors face acute cost pressure from indigenization mandates.
Maharashtra
Mumbai anchors India's submarine and surface combatant construction through Mazagon Dock Shipbuilders Limited's integrated facilities. The state's Defence Acquisition Procedure compliance infrastructure streamlines offset obligation processing for foreign vendors. Pune-based Bharat Forge Limited supplies pressure hull forgings and armored vehicle components to naval and mechanized infantry programs.
Karnataka
Bengaluru concentrates aerospace and electronics manufacturing with Hindustan Aeronautics Limited's aero-engine test facilities dominating fighter upgrade qualification. The state's PLI scheme for drone components is redirecting flight controller and sensor payload sourcing toward domestic electronics packaging specialists. BIS military-grade certification centers here process specialized alloy validations for airborne structures.
Telangana
Hyderabad hosts Bharat Dynamics Limited's missile integration complexes and propellant chemistry facilities. The state's controlled energetic materials production navigates international non-proliferation restrictions through DGFT export control classifications. DRDO laboratories here anchor solid-fuel precursor research for strategic programs.
Kerala
Kochi's Cochin Shipyard Limited constructs aircraft carriers and support vessels for Indian Navy fleet expansion. The state's naval shipbuilding corridor position drives pressure hull fabrication expertise and specialized steel forging partnerships. CEA power allocation mandates guarantee electricity supply for precision machining processes at maritime manufacturing clusters.
Andhra Pradesh
Visakhapatnam's submarine maintenance, repair, and overhaul facilities service Eastern Naval Command fleet requirements. The state's service unbundling trends create independent aftermarket competition for propulsion and combat system integrators. Bharat Electronics Limited's radar subsystem suppliers here leverage in-house semiconductor packaging for electronic warfare indigenization.
India Defense Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in India's defense supplier pyramid. Hindustan Aeronautics Limited, Mazagon Dock Shipbuilders Limited, and Bharat Electronics Limited control captive metallurgical and propulsion capabilities that function as procurement gatekeepers. Three strategic archetypes dominate: sovereign platform integrators with test facility monopolies, component specialists capturing PLI scheme incentives, and aftermarket service providers exploiting unbundled lifecycle contracts. Competitive moves concentrate on backward integration into naval steel forging and qualification pathway partnerships with domestic mills.
Within the sovereign platform integrator tier, Hindustan Aeronautics Limited exemplifies aero-engine test facility scarcity that constrains vendor certification timelines. Mazagon Dock Shipbuilders Limited anchors submarine construction leadership through pressure hull forging partnerships. Bharat Electronics Limited occupies a position demonstrating radar and electronic warfare subsystem viability through in-house semiconductor packaging capabilities.
| Leading Market Players |
|---|
| Mazagon Dock Shipbuilders Limited |
| Bharat Forge Limited |
| Hindustan Aeronautics Limited |
| MTAR Technologies Limited |
| Cochin Shipyard Limited |
| Bharat Electronics Limited |
| Bharat Dynamics Limited |
| Paras Defence and Space Technologies Limited |
| Solar Industries India Limited |
| Others |
Value Chain & Pricing Dynamics
BIS military-grade certification for specialized alloys and composites gates both supplier qualification timelines and price differentiation across India's defense procurement tiers. The certification regime creates 18-24 month validation windows that compress margins for tier-2 component vendors while insulating integrated platform builders with captive metallurgical capabilities.
Pricing Analysis
After-sales service contracts and lifecycle maintenance agreements drive lifetime value capture across naval and aerial platform programs. Three-tier pricing structure across prime integrators, qualified subsystem vendors, and tier-2 component suppliers reflects certification grade and captive test facility access. Cost compression in tier-2 electronics and composite fabrication is intensifying because PLI scheme incentives are attracting new domestic entrants. Paramilitary and internal security buyers exhibit highest price sensitivity, while military platform procurement absorbs premium costs for sovereign capability assurance.
Supply Chain Analysis
India anchors pressure hull forging and naval-grade steel production through DMR-249A partnerships with domestic integrated mills. The supply chain draws from controlled energetic materials sources subject to international non-proliferation restrictions, specialized alloy feedstock for airborne structures, and semiconductor packaging equipment for radar subsystem production. Single-source vulnerability concentrates in solid-fuel precursor chemistry for missile programs. Distribution runs through Defence Acquisition Procedure-mandated indigenization tiers that elevate domestic value-add thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's defense market rewards scarce metallurgical and propulsion capabilities that function as procurement gatekeepers, with bottlenecked aero-engine test facilities and pressure hull forging partnerships determining competitive access.
For Market Incumbents: Consolidate backward integration into naval steel forging partnerships and captive semiconductor packaging lines to defend against PLI scheme-enabled component specialists. Lock in long-term DMR-249A supply agreements with domestic mills before tier-2 entrants qualify alternative metallurgical sources. Priority lever rests on securing exclusive aero-engine test bed access at Hindustan Aeronautics Limited facilities. For New Entrants and Emerging Players: Lead with cybersecurity solutions for intelligence agency procurement channels, where compressed contract cycles bypass platform procurement bottlenecks. Target drone subsystem qualification under PLI scheme incentives in Bengaluru and Hyderabad electronics clusters. Go-to-market angle emphasizes fabless design partnerships with Bharat Electronics' packaging lines for radar and electronic warfare subsystem entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed drone component manufacturers and AI-enabled surveillance startups maturing through iDEX seed funding. Long-term viability hinges on 5-10 year indigenization mandate durability and Defence Acquisition Procedure tiering stability. Signal to watch: CEA power allocation expansion to new defense manufacturing clusters as indicator of sovereign manufacturing commitment depth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naval Steel Forging | Captive DMR-249A supply secures submarine and destroyer hull fabrication contracts at Mazagon Dock. |
| Semiconductor Packaging Localization | In-house chip packaging lines unlock radar and electronic warfare subsystem qualification with Bharat Electronics. |
| iDEX Partnership for Drone Subsystems | Seed-funded flight controller development accelerates PLI scheme qualification for Bengaluru electronics specialists. |
| Service Unbundling Capture | Independent MRO competition at Visakhapatnam and Kochi creates aftermarket revenue streams separate from prime construction. |
| Cybersecurity Procurement Channel Development | Intelligence agency network defense contracts compress revenue recognition timelines versus platform procurement cycles. |
Study Parameters
A spread of perspectives from platform program managers at Hindustan Aeronautics Limited and Mazagon Dock, tier-2 component procurement leads, Defence Acquisition Procedure compliance officers, and iDEX startup founders converged on the working assumptions. Primary fieldwork combined with secondary validation from BIS certification records, CEA power allocation filings, DGFT export control classifications, and PLI scheme beneficiary disclosures. Bottom-up vendor capacity assessments and top-down procurement budget triangulation anchored value estimates.
Segmentation dimensions modeled span product type across naval vessels, aircraft, missiles, and armored vehicles; technology across cybersecurity, drones, radar, and communication systems; end user across military, intelligence agencies, paramilitary, and government; and service type across maintenance, logistics, training, and consulting. CAGRs were derived from procurement cycle analysis and indigenization mandate trajectory across the projection horizon. Forecast inputs incorporated Defence Acquisition Procedure reform implementation pace and iDEX funding disbursement velocity.
Forecasts assume regulatory continuity in BIS military-grade certification regimes and CEA power allocation mandates; material policy shifts would require re-modeling. Specific risks include international non-proliferation restriction tightening on solid-fuel precursors and tri-service procurement rhythm misalignment. Recalibration cycles align with material shifts in PLI scheme expansion scope and SAMR-style dual-use technology control adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Asia-Pacific Digital Battlefield Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Europe Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Military Software Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market